
 Pharmaceutical Logistics Market | 2026-2036
Pharmaceutical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Logistics Market Intelligence
The split between validated cold chain lanes and standard freight is realigning contract structures across the industry. Deutsche Post DHL anchors its position through integrated temperature-controlled networks spanning pharmaceutical hubs on three continents. FedEx differentiates via sensor-driven visibility platforms that track shipment integrity in real time. Kuehne + Nagel competes by specializing in clinical trial logistics with dedicated quality management systems.
Pharmaceutical logistics encompasses the temperature-controlled storage, handling, and distribution of medicinal products requiring chain-of-custody documentation and validated equipment qualification. Active thermal containers maintain 2-8°C or -20°C set points through compressor-based or phase-change material systems, ensuring potency preservation for biologics and vaccines. Cold chain management captures premium margin pools due to qualification complexity and regulatory audit density, while transportation remains volume-heavy with compressed yields. Warehousing is consolidating toward multi-client licensed facilities with automated picking and serialization integration.
The US FDA enforces current Good Distribution Practice through facility inspections and supply chain security directives, while the EU EMA coordinates GDP compliance across member states with national competent authority oversight. The WHO prequalification program shapes market access for temperature-sensitive vaccines in lower-income procurement channels. Stakeholders must weigh capital deployment between owned cold chain infrastructure and fourth-party logistics partnerships as regulatory serialization deadlines tighten.
Market Dynamics
Cold chain qualification complexity is compressing carrier margins while concentrating volume among operators with validated multi-modal networks. The US FDA DSCSA serialization mandate and EU GDP guideline revisions are forcing infrastructure reinvestment timelines that favor scaled incumbents over regional specialists.
Growth Catalysts
- Biologics expansion:Cell and gene therapies requiring -80°C to -150°C cryogenic transport are pulling investment into specialized container fleets and liquid nitrogen logistics infrastructure.
- EU Falsified Medicines Directive:The 2019 safety feature mandate and ongoing GDP guideline updates are standardizing serialization compliance costs that lock in qualified 3PL relationships.
- India's pharmaceutical exports:Contract manufacturing concentration in Hyderabad and Ahmedabad is generating outbound cold lane demand to US and EU regulatory markets.
Market Restraints
- Refrigerant cost volatility:Phase-change materials and compressor-based cooling systems face input price pressure from energy market fluctuations and refrigerant phase-out schedules under EU F-Gas Regulation.
- Container asset concentration:Active thermal container pools remain concentrated among three global leasing networks, creating availability bottlenecks during pandemic-scale vaccine distribution surges.
- Last-mile temperature excursion risk:Urban congestion and handoff complexity at pharmacy and hospital receiving points generate spoilage rates that erode shipper confidence in non-validated lanes.
Strategic Opportunities
- Sub-Saharan Africa vaccine corridors:WHO prequalification pathways and Gavi procurement channels are opening dedicated cold chain infrastructure investment for temperature-sensitive immunization programs.
- Real-time sensor convergence:Integration of IoT temperature loggers with blockchain custody records is enabling parametric insurance products that transfer excursion risk from shippers to underwriters.
- Direct-to-patient distribution:Specialty pharmacy fulfillment from central fill pharmacies to home infusion is bypassing wholesale distribution for biologics requiring patient-specific handling protocols.
Industry Challenges
- Qualified personnel scarcity:GDP-certified supply chain managers and cold chain validation engineers command premium compensation that strains mid-size logistics operators.
- Serialization system integration:Legacy warehouse management platforms require costly middleware development to interface with EU hub-and-spoke verification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Logistics Market |
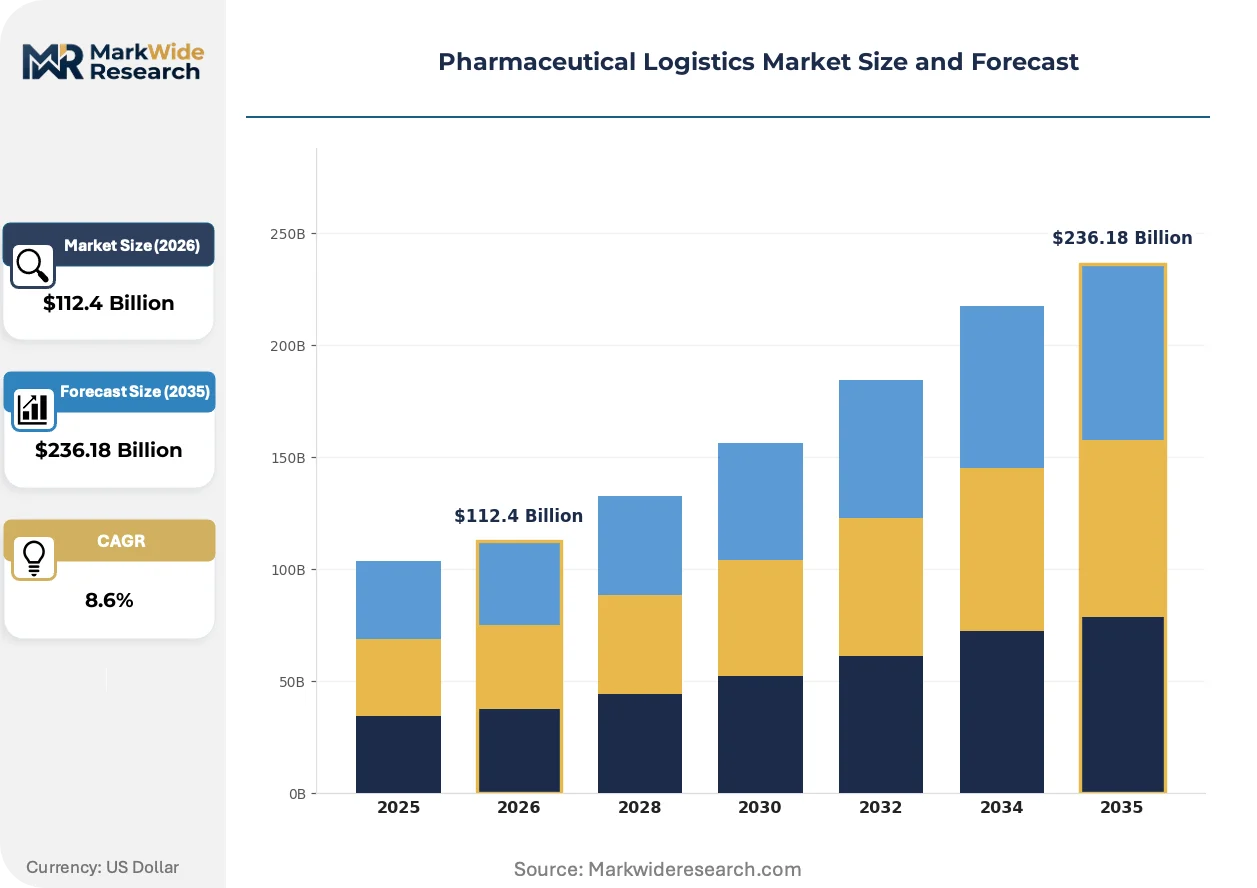
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $236.18 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cold Chain Management, Warehousing, Transportation, Inventory Management, Order Fulfillment Application: Clinical Trials, Vaccine Distribution, Hospital Supplies, Retail Pharmacy Deliveries, Medical Equipment Supply Packaging Type: Temperature-Controlled Containers, Insulated Boxes, Stability Packaging, Reusable Containers, Tamper-Evident Seals End User: Pharmaceutical Manufacturers, Wholesalers, Specialty Distributors, Healthcare Facilities, Research Laboratories |
| Companies Covered | Deutsche Post DHL, FedEx, Kuehne + Nagel, United Parcel Service, C.H. Robinson Worldwide, A.P. Møller – Mærsk, DB Schenker, AmerisourceBergen Corporation, CEVA Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Logistics Market Strategic Shifts & Innovations
Digitization of custody documentation and predictive risk analytics are compressing insurance costs while enabling lane optimization that was previously impossible. These shifts are reconfiguring how pharmaceutical shippers evaluate carrier performance and allocate freight spend.
Reusable active thermal containers with embedded telemetry are unifying physical transport and data capture into single asset systems. Large molecule manufacturers are deploying these units for intercontinental lanes at accelerating rates. The technology is unifying equipment qualification, real-time monitoring, and automated documentation into unified workflows that reduce manual intervention at customs and receiving points.
The EU Medical Device Regulation (MDR) is extending traceability requirements to combination products and their logistics intermediaries. Device manufacturers must now maintain distribution records that mirror pharmaceutical GDP standards. Clinical trial logistics providers serving EU sites are requalifying facilities and retraining staff to meet the expanded audit scope.
Consolidation of buying power among specialty pharmacy benefit managers is compressing freight tender cycles and demanding outcome-based lane performance guarantees. Traditional rate-per-kilogram pricing is giving way to contracted temperature excursion rates and on-time-in-full penalties. This shift is most visible in US oncology drug distribution, where narrow distribution networks concentrate volume among carriers with proven controlled-substance security protocols.
Pharmaceutical Logistics Market Segmentation
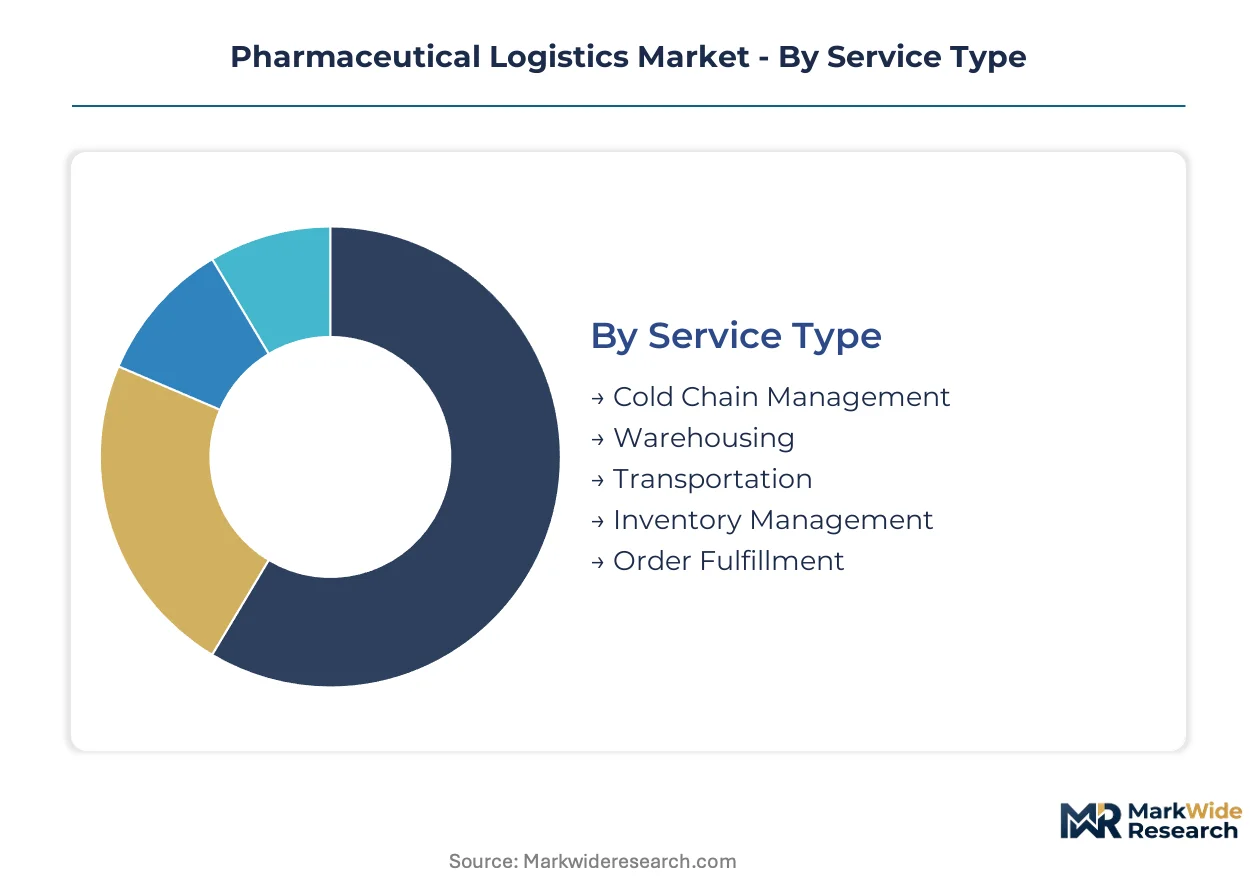
Segmentation in pharmaceutical logistics reveals how service specialization, regulatory intensity, and custody complexity fragment purchasing decisions across the value chain. Buyers select providers based on validated cold chain capability, geographic reach, and serialization compliance rather than price alone.
Service Type:
Cold chain capability drives premium pricing power, while transportation and warehousing compete on scale and network density.
- Cold Chain Management:Encompasses 2-8°C and -20°C to -80°C lane qualification, real-time telemetry integration, and GDP audit documentation. Demand concentrates among biologics manufacturers in Germany and the United States facing FDA and EMA inspection schedules. Cryogenic logistics for cell therapies commands the highest service premiums due to container asset scarcity and liquid nitrogen handling protocols.
- Warehousing:Multi-client licensed facilities with automated picking, serialization integration, and temperature mapping validation. Volume concentrates in India at Hyderabad and Ahmedabad clusters serving contract manufacturing exports to regulated markets. Facility licensing under EU GDP and US FDA standards creates barriers that favor scaled operators with established quality management systems.
- Transportation:Air, ocean, and road freight with validated thermal protection and chain-of-custody documentation. Active container leasing networks dominate intercontinental lanes.
- Inventory Management:Serialized stock tracking, expiry date monitoring, and recall readiness systems integrated with ERP platforms.
- Order Fulfillment:Direct-to-pharmacy and direct-to-patient distribution with specialty handling protocols for controlled substances and temperature-sensitive products.
Volume sits with Transportation; growth tilts toward Cold Chain Management.
Application:
Regulatory stringency and patient risk profile determine logistics specification intensity across therapeutic categories.
- Clinical Trials:Requires investigational product custody, site-to-laboratory specimen transport, and protocol-specific temperature windows. Demand is accelerating in the United States and Western Europe as decentralized trial models expand direct-to-patient drug shipments. GDP compliance and IATA CEIV Pharma certification filter carrier selection for Phase III programs.
- Vaccine Distribution:WHO prequalification pathways and Gavi procurement channels shape cold chain infrastructure investment for immunization programs in lower-income regions. Ultra-cold -70°C requirements for mRNA platforms have expanded specialized container fleet deployment.
- Hospital Supplies:Just-in-time delivery of high-value biologics with narrow temperature windows and controlled-substance security protocols.
- Retail Pharmacy Deliveries:Last-mile distribution facing urban congestion and handoff complexity that generates temperature excursion risk at receiving points.
- Medical Equipment Supply:EU MDR traceability requirements now extend to combination products and their logistics intermediaries.
Hospital Supplies capture the largest freight volume; Clinical Trials are expanding most quickly.
Packaging Type:
Asset utilization models and sustainability mandates are shifting procurement toward reusable systems with embedded telemetry.
- Temperature-Controlled Containers:Active compressor-based or phase-change material systems maintaining 2-8°C, -20°C, or cryogenic set points. Leasing pools remain concentrated among three global networks, creating availability constraints during surge demand. Integration with IoT loggers and blockchain custody records is enabling parametric insurance products.
- Reusable Containers:Embedded telemetry unifies physical transport and data capture into single asset systems, reducing manual intervention at customs and receiving points. Large molecule manufacturers in the United States and Germany are deploying these for intercontinental lanes at accelerating rates.
- Insulated Boxes:Passive thermal protection with gel packs for short-duration shipments in moderate climates.
- Stability Packaging:Qualified for specific product shelf-life extensions during transit excursions.
- Tamper-Evident Seals:Serialization integration for EU Falsified Medicines Directive compliance and supply chain security.
Insulated Boxes dominate shipment count; Reusable Containers gain share fastest.
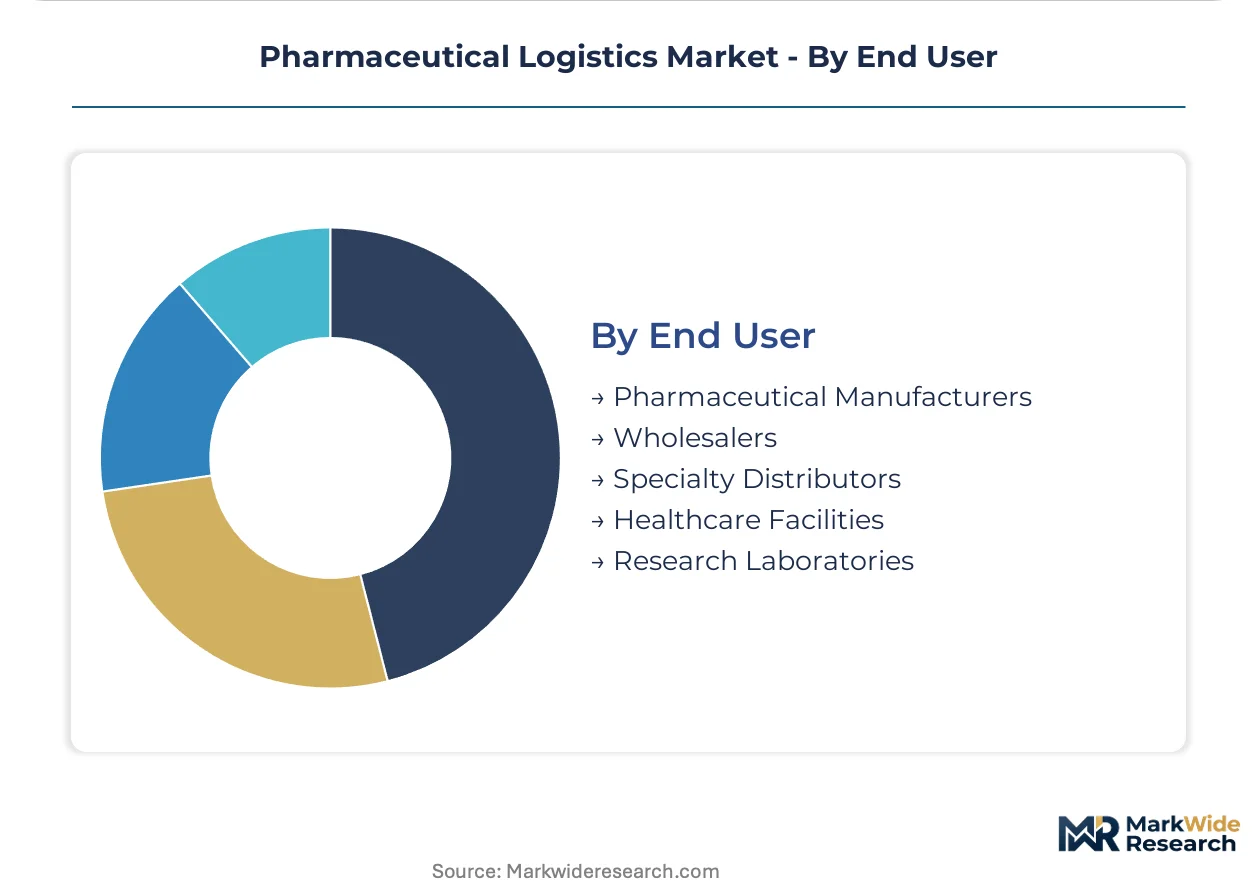
End User:
Consolidation among buyers is compressing tender cycles and demanding outcome-based performance guarantees.
- Pharmaceutical Manufacturers:Biologics and cell therapy producers requiring validated cold chain from production through distribution. Outsourcing decisions weigh capital deployment between owned infrastructure and fourth-party logistics partnerships as serialization deadlines tighten.
- Specialty Distributors:Narrow distribution networks for oncology and rare disease therapies with controlled-substance security and patient-specific handling protocols. Pricing is shifting from rate-per-kilogram to contracted temperature excursion rates and on-time-in-full penalties.
- Wholesalers:Hub-and-spoke verification systems under EU Falsified Medicines Directive with legacy WMS middleware requirements.
- Healthcare Facilities:Hospital and clinic receiving points generating last-mile spoilage rates that erode shipper confidence in non-validated lanes.
- Research Laboratories:Clinical trial specimen transport with protocol-specific chain-of-custody requirements.
Wholesalers move the highest tonnage; Specialty Distributors show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad and Ahmedabad anchor outbound pharmaceutical logistics demand from India, generating cold lane volumes toward US and EU regulatory markets that reshape intercontinental freight patterns.
United States
Specialty pharmacy benefit managers concentrate buying power and compress freight tender cycles for oncology and rare disease therapies. The FDA enforces current Good Distribution Practice through facility inspections and DSCSA serialization mandates that force infrastructure reinvestment timelines. Greater Boston and the San Francisco Bay Area host biologics manufacturers deploying cryogenic logistics for cell and gene therapy clinical trials.
Germany
EMA-coordinated GDP compliance across member states creates audit density that favors scaled operators with established quality management systems. The EU Falsified Medicines Directive and ongoing GDP guideline revisions standardize serialization compliance costs. Frankfurt and Cologne serve as pharmaceutical logistics hubs with multi-client licensed facilities integrating automated picking and serialization systems.
India
Contract manufacturing concentration in Hyderabad and Ahmedabad generates outbound cold lane demand to regulated markets. CDSCO alignment with international standards and PLI scheme incentives strengthen export competitiveness. Mumbai and Delhi-NCR operate as consolidation points for temperature-controlled air freight to Europe and North America.
Switzerland
Swissmedic oversight and proximity to EU markets position the country as a high-value pharmaceutical distribution node. Basel and Zurich host specialized cold chain infrastructure serving biologics manufacturers with intercontinental reach. The country's neutrality and regulatory reputation attract clinical trial logistics operations requiring protocol-specific custody.
United Arab Emirates
Dubai's pharmaceutical free zones and Jebel Ali port infrastructure serve as redistribution hubs for Middle East and Africa markets. MOHAP licensing requirements and WHO prequalification pathways shape cold chain investment for vaccine corridors. The emirate's air cargo connectivity supports temperature-sensitive shipments to Sub-Saharan African immunization programs.
Pharmaceutical Logistics Market Key Industry Players
Capital-heavy integrated carriers compete with asset-light freight forwarders and specialized clinical trial operators across tiered service segments. The market concentrates among scaled incumbents with validated multi-modal networks, while regional specialists face margin compression from qualification complexity. Three archetypes dominate: integrated express networks with owned cold chain infrastructure, global forwarders with leased container pooling arrangements, and clinical trial specialists with dedicated quality management systems. Competitive moves center on sensor platform development for real-time visibility and fourth-party logistics partnerships that transfer infrastructure risk.
Within the integrated carrier tier, Deutsche Post DHL and FedEx exemplify divergent strategic positioning. DHL anchors through temperature-controlled networks spanning pharmaceutical hubs on three continents. FedEx differentiates via sensor-driven visibility platforms that track shipment integrity in real time. Among forwarder specialists, Kuehne + Nagel occupies a position emphasizing clinical trial logistics with dedicated quality management systems and IATA CEIV Pharma certification density.
| Leading Market Players |
|---|
| Deutsche Post DHL |
| FedEx |
| Kuehne + Nagel |
| United Parcel Service |
| C.H. Robinson Worldwide |
| A.P. Møller – Mærsk |
| DB Schenker |
| AmerisourceBergen Corporation |
| CEVA Logistics |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation phase-out schedules and refrigerant restrictions gate qualified cold chain supply and premium-tier pricing access. Compliance-validated operators command rate premiums while non-compliant carriers face exclusion from regulated lanes.
Pricing Analysis
Outcome-based pricing anchors pharmaceutical logistics contracts, with shippers paying for temperature integrity rather than distance moved. Pricing stratifies across GDP-certified premium tiers, standard validated lanes, and non-validated economy options. Cost compression in standard freight intensifies because container asset scarcity concentrates among three global leasing networks. Specialty pharmacy benefit managers show least price sensitivity due to narrow distribution network requirements and patient-risk considerations.
Supply Chain Analysis
Reverse logistics for reusable active thermal containers with embedded telemetry creates circular asset flows that reduce per-shipment costs. Manufacturing concentrates in Germany, India, and the United States, with Hyderabad and Ahmedabad generating outbound cold lane volume. Supply chains rest on phase-change materials, compressor-based cooling systems, and liquid nitrogen logistics infrastructure. Single-source vulnerability runs through concentrated container leasing pools. Distribution runs through multi-client licensed facilities with automated picking and serialization integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical logistics is consolidating around qualification-heavy operators as EU GDP and US FDA serialization mandates force infrastructure reinvestment timelines that regional specialists cannot meet.
For Market Incumbents: Acquire cryogenic container fleets and liquid nitrogen handling capabilities to anchor cell and gene therapy logistics positions. Consolidate clinical trial logistics operations through IATA CEIV Pharma-certified facility networks. Defend against sensor-platform entrants by integrating IoT telemetry with blockchain custody documentation. For New Entrants and Emerging Players: Begin with direct-to-patient distribution for specialty pharmacy fulfillment, bypassing wholesale concentration. Target Sub-Saharan Africa vaccine corridors where WHO prequalification pathways create dedicated infrastructure demand. Pursue parametric insurance partnerships that transfer excursion risk from shippers to underwriters as differentiation. For Investors and Strategic Acquirers: CDSCO alignment announcements with international standards are the leading indicator that Indian contract manufacturing export volumes will accelerate cold chain demand. Five-to-ten year viability favors scaled operators with validated multi-modal networks over asset-light forwarders. Target acquisition archetype: clinical trial specialists with dedicated quality management systems and GDP audit density. Monitor EU Medical Device Regulation enforcement scope expansion as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Fleet Expansion | Liquid nitrogen logistics infrastructure captures cell therapy manufacturing demand from Boston and San Francisco Bay Area clusters. |
| Sensor Platform Integration | IoT telemetry unified with blockchain custody enables parametric insurance products that shift excursion risk. |
| GDP Certification Investment | EMA-coordinated compliance across EU member states locks in qualified 3PL relationships against non-compliant competitors. |
| Direct-to-Patient Distribution | Specialty pharmacy fulfillment bypasses wholesale concentration for biologics requiring patient-specific handling protocols. |
| Sub-Saharan Africa Corridor Development | WHO prequalification pathways and Gavi procurement channels open dedicated cold chain infrastructure investment. |
Research Approach
Regulatory filings, customs trade data, and clinical trial logistics operator disclosures formed the secondary backbone of this analysis. Primary interviews with pharmaceutical supply chain directors, GDP-certified quality managers, cold chain validation engineers, and specialty pharmacy procurement officers combined with secondary validation through bottom-up and top-down triangulation. FDA facility inspection records, EMA GDP compliance databases, and WHO prequalification pathways provided structured inputs.
Bottom-up modeling tracked service type, application, packaging format, and end-user segment across the projection horizon. Top-down validation cross-referenced macro pharmaceutical trade flows and biologics manufacturing capacity expansion. CAGRs derived from segment-level volume trajectories and pricing trend synthesis. Forecast inputs incorporated EU Falsified Medicines Directive implementation schedules and DSCSA serialization mandate compliance timelines.
Underlying measurement precision varies by segment; cryogenic logistics and clinical trial applications carry tighter precision than standard freight transportation. Forecasts reflect documented assumptions regarding regulatory deadline adherence and container fleet expansion rates. Practitioners should monitor EU GDP guideline revision announcements and active thermal container availability indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
Apparel Logistics Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Spain Pharmaceutical Logistics Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
North America Freight Brokerage Market
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
Hong Kong Freight and Logistics Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market