
 US Retail Logistics Market | 2026-2036
US Retail Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
US Retail Logistics Market Intelligence
The Federal Motor Carrier Safety Administration's hours-of-service reform is pivoting fleet economics toward asset-light broker models. J.B. Hunt leverages intermodal container networks to control costs across the Midwest-Southeast lanes. C.H. Robinson competes through digital freight-matching platforms that reduce empty-mile ratios for contracted carriers. Amazon anchors captive last-mile infrastructure in exurban zones, insulating delivery density from third-party rate volatility.
US retail logistics encompasses the planning, execution, and control of inventory movement from supplier through distribution center to end consumer, typically operating within delivery windows of two hours for grocery and twenty-four hours for general merchandise. Its primary commercial purpose centers on synchronizing stock availability with promotional calendars and seasonal demand spikes across fragmented store networks. Last mile delivery and warehousing together concentrate capital deployment, as e-commerce order profiles favor localized fulfillment nodes over centralized regional depots. Automated storage systems within warehouse management technology stacks are expanding fastest, though transportation management systems still capture the largest share of enterprise software spending in this segment.
The Department of Transportation, Occupational Safety and Health Administration, and Environmental Protection Agency collectively govern vehicle safety, warehouse working conditions, and emissions standards that shape fleet renewal cycles and facility siting decisions. California Air Resources Board mandates are accelerating electric vehicle trials among for-hire carriers serving the Ports of Long Beach and Los Angeles. Stakeholders must weigh compliance cost trajectories against automation payback periods when allocating capital across network nodes.
Market Dynamics
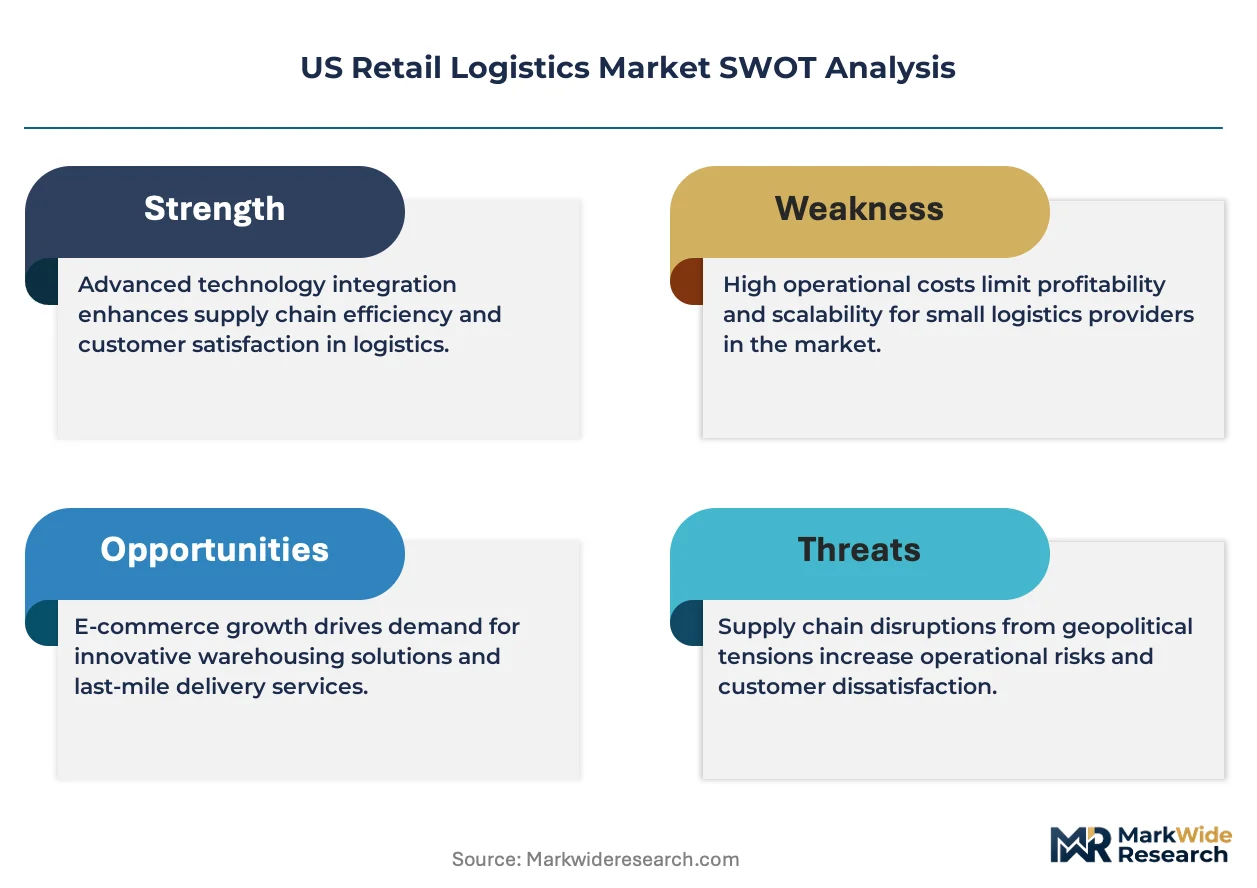
Omnichannel fulfillment density is forcing warehouse networks toward micro-fulfillment nodes in exurban corridors, compressing last-mile radii while inflating real estate competition around Texas, California, and Florida distribution clusters.
Growth Catalysts
- FMCSA Hours-of-Service Reform:Electronic logging device mandates are accelerating fleet digitization and expanding broker-mediated freight-matching platforms across for-hire trucking segments.
- Grocery E-Commerce Velocity:Two-hour delivery windows for perishables are driving automated storage and retrieval system deployment in temperature-controlled facilities.
- Texas-California-Florida Corridor Expansion:Distribution center construction outpaces national averages in these three states, anchoring intermodal rail-to-last-mile transfer infrastructure.
Market Restraints
- Driver Availability Compression:Commercial driver license pipeline constraints limit fleet expansion regardless of equipment investment cycles.
- California Air Resources Board Mandates:Accelerating electric vehicle trials at Long Beach and Los Angeles ports impose premature capital replacement on drayage operators.
- Real Estate Scarcity:Industrial land availability near urban consumption centers is tightening faster than construction velocity can offset.
Strategic Opportunities
- Midwest Intermodal Density:Container networks connecting Chicago to Southeast consumption corridors remain underutilized relative to coastal port dependency.
- Automated Yard Management:Convergence of computer vision and warehouse management systems enables trailer positioning optimization outside facility walls.
- OSHA Warehouse Ergonomics Standards:Compliance-driven automation incentives create capital deployment pathways for collaborative robotics in order fulfillment.
Industry Challenges
- Warehouse Automation Integration:Legacy warehouse management technology stacks require middleware development to interface with autonomous mobile robot fleets.
- EPA Emissions Compliance Timeline:Fleet renewal cycles must synchronize with evolving heavy-duty vehicle standards across multiple model years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Retail Logistics Market |
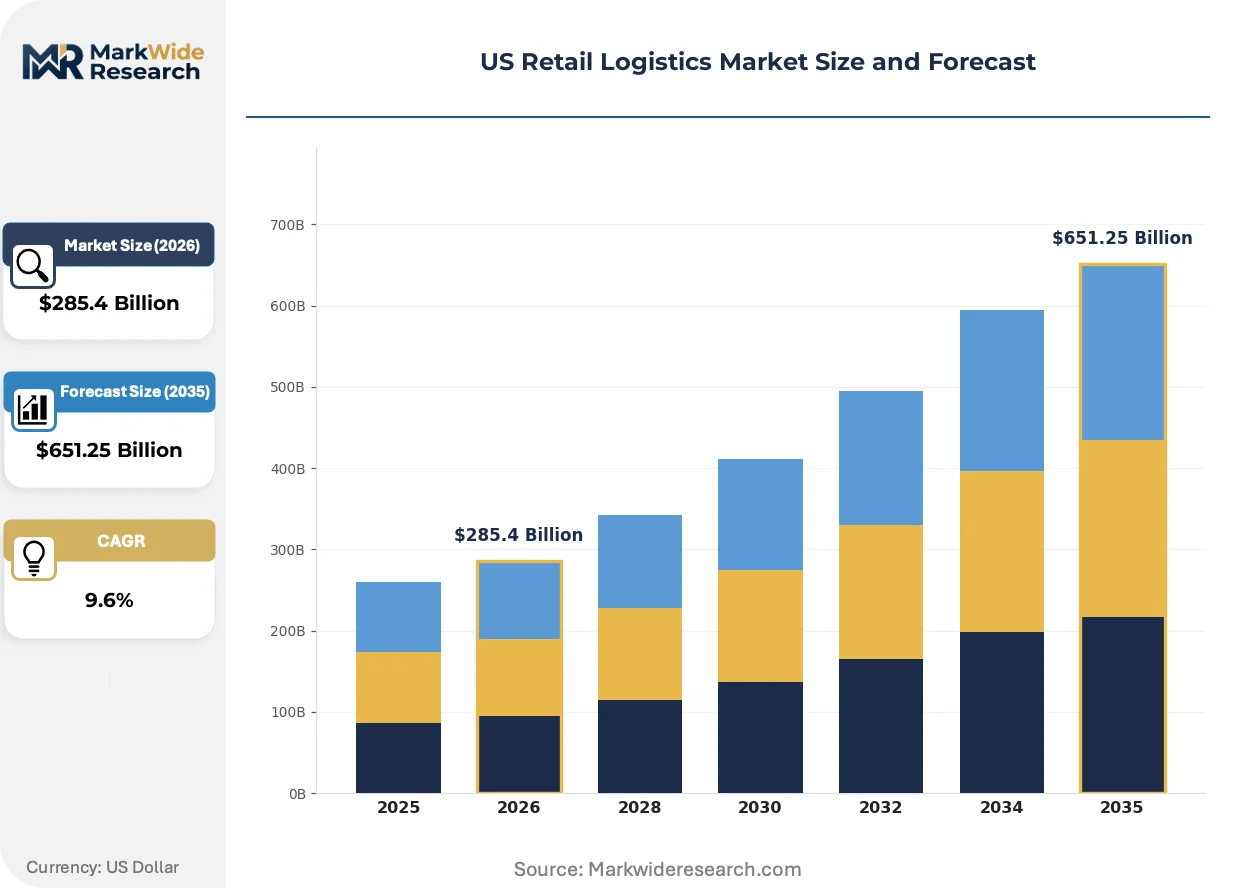
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $651.25 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Type: Same-Day Delivery, Next-Day Delivery, Standard Shipping, International Shipping Service Type: Freight Forwarding, Last Mile Delivery, Warehousing, Inventory Management Technology: Warehouse Management Systems, Transportation Management Systems, IoT Solutions, Automated Storage Customer Type: B2C, B2B, E-commerce, Wholesale, Retail Chains |
| Companies Covered | J.B. Hunt, Expeditors, Amazon, Kuehne + Nagel, Ryder Supply Chain Solutions, C.H. Robinson, UPS Supply Chain Solutions, Total Quality Logistics, GXO Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Retail Logistics Market Strategic Shifts & Innovations
Retail logistics infrastructure is bifurcating between centralized automation and distributed micro-fulfillment, with capital allocation tilting toward software-defined inventory positioning over fixed asset expansion.
Autonomous mobile robots within goods-to-person fulfillment architectures are absorbing repetitive picking and transport labor inside e-commerce distribution centers. Grocery and apparel retailers with high SKU volatility are deploying these systems fastest. The technology is absorbing manual warehouse headcount growth that would otherwise track with order volume expansion.
California Air Resources Board heavy-duty vehicle regulations are compressing diesel tractor-trailer operating windows at Southern California port complexes. Drayage carriers serving Long Beach and Los Angeles must accelerate electric truck pilot programs or face facility access restrictions. The mandate is forcing asset-heavy operators into leasing partnerships with technology-forward fleet providers.
Buyer procurement of transportation capacity is fragmenting across dedicated contract, spot market, and private fleet channels rather than consolidating under annual rate agreements. Large omnichannel retailers are building captive last-mile delivery infrastructure in exurban zones to insulate against third-party carrier rate volatility. This pattern concentrates in Texas and Florida markets where land availability permits network scale.
US Retail Logistics Market Segmentation
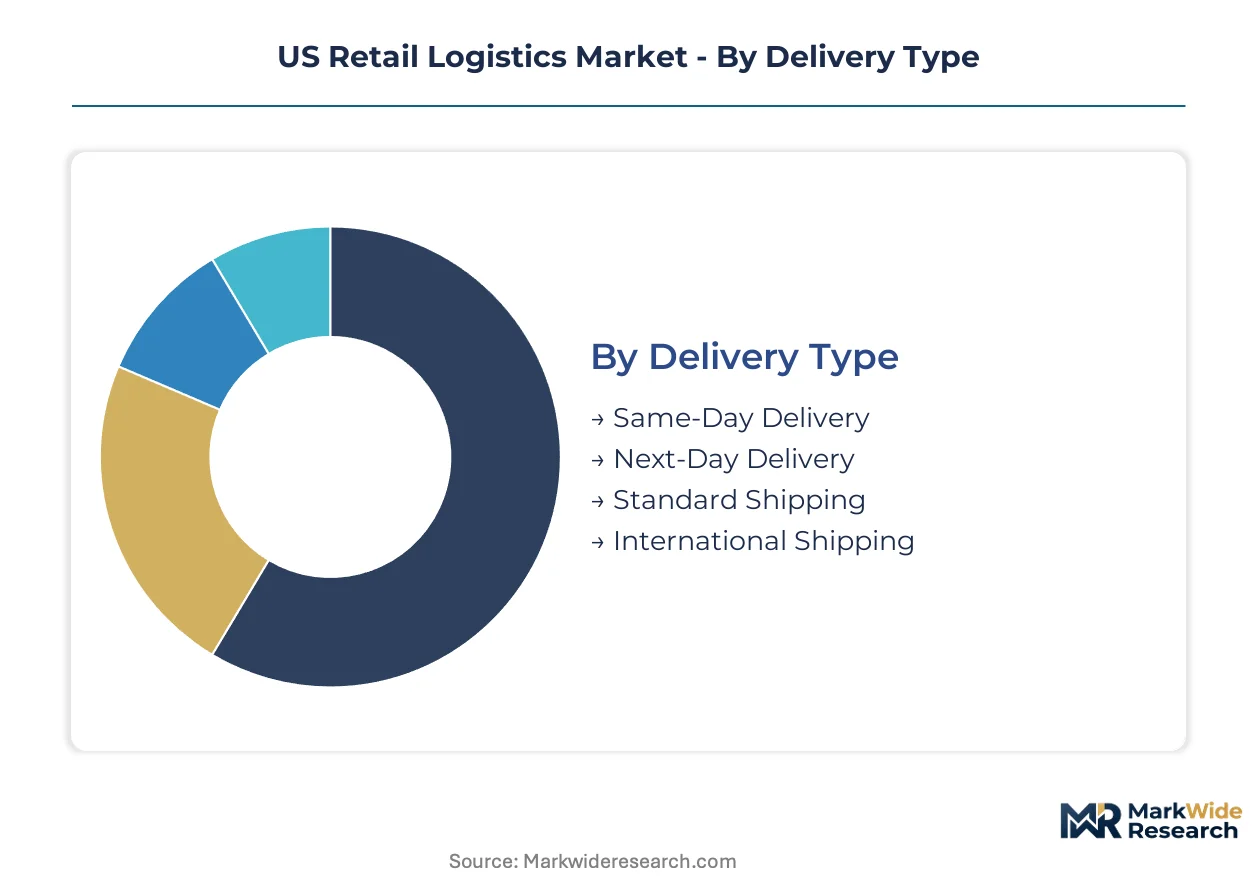
US retail logistics operators segment service offerings to match velocity requirements against cost tolerance. Delivery windows, infrastructure ownership, and technology deployment vary sharply across these divisions.
Delivery Type:
Volume concentrates in standard shipping while premium tiers capture margin expansion from grocery and apparel omnichannel networks.
- Same-Day Delivery:Requires micro-fulfillment nodes within fifteen-mile radii of dense consumption zones. Demand clusters in Texas and Florida exurban corridors where land costs permit last-mile station scale. Driver availability constraints limit network expansion regardless of facility investment.
- Next-Day Delivery:Balances inventory positioning against transportation speed through regional sortation hubs. California distribution centers anchor this tier for Pacific Coast consumption. Amazon's captive infrastructure insulates delivery density from third-party rate volatility.
- Standard Shipping:Consolidated line-haul networks optimize cost per unit across multi-day delivery windows.
- International Shipping:Port drayage and customs brokerage integration determines competitive positioning.
Today's leader: Standard Shipping. Tomorrow's challenger: Same-Day Delivery.
Service Type:
Asset-light models displace fixed infrastructure as broker platforms capture freight-matching economics.
- Last Mile Delivery:Dense stop sequences in exurban zones require route optimization software and gig-driver pools. Florida and Texas markets concentrate investment due to consumption growth and land availability. OSHA warehouse ergonomics standards indirectly shape last-mile labor costs through upstream facility automation.
- Warehousing:Temperature-controlled facilities command premium rents for grocery e-commerce fulfillment. Automated storage and retrieval systems compress labor headcount per unit shipped. California Air Resources Board mandates accelerate electric yard truck trials at Southern California nodes.
- Freight Forwarding:Intermodal container coordination across Midwest-Southeast lanes.
- Inventory Management:Real-time visibility software replacing static safety-stock models.
Fixed assets dominate revenue today. Asset-light platforms are climbing the fastest.
Technology:
Software spending tilts toward execution systems over planning layers.
- Automated Storage:Goods-to-person architectures absorb repetitive picking labor in e-commerce distribution centers. Grocery retailers with high SKU volatility deploy these systems fastest. Middleware requirements for legacy warehouse management integration constrain rollout velocity.
- Warehouse Management Systems:Core inventory tracking and labor management modules capture largest enterprise software share. Cloud-native vendors displace on-premise installations. API-first architectures enable faster autonomous mobile robot integration.
- Transportation Management Systems:Route optimization and carrier procurement modules.
- IoT Solutions:Trailer tracking and cold-chain monitoring sensors.
Execution automation leads deployment today. Planning layer AI represents the steepest expansion trajectory.
Customer Type:
B2C velocity requirements force infrastructure choices that B2B networks amortize over longer cycles.
- E-commerce:Two-hour grocery and twenty-four-hour general merchandise windows mandate distributed fulfillment nodes. Micro-fulfillment construction concentrates in Texas, California, and Florida distribution clusters. Real estate scarcity near urban centers tightens faster than construction velocity offsets.
- B2C:Direct-to-consumer parcel networks require dense last-mile injection points.
- B2B:Palletized freight moving through consolidated distribution networks.
- Wholesale:Full-truckload procurement patterns with annual contract structures.
- Retail Chains:Store replenishment schedules synchronized to promotional calendars.
E-commerce anchors capital deployment today. Wholesale contract structures face the most pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US retail logistics originated in the post-war interstate highway era, scaling through Chicago rail hubs and Southern California port complexes before fragmenting into today's distributed fulfillment networks. The modern infrastructure map reflects this lineage, with density concentrating in corridors that merged historical transport advantages with exurban land availability.
California
Los Angeles and Long Beach port complexes anchor trans-Pacific import volumes, while the Inland Empire warehouses distribute across Western states. California Air Resources Board mandates accelerate electric yard truck trials at Southern California nodes, forcing drayage operators into leasing partnerships. The Central Valley corridor between Stockton and Fresno is absorbing overflow distribution center construction as coastal land scarcity intensifies.
Texas
Dallas-Fort Worth and Houston consumption growth drives micro-fulfillment investment in exurban corridors where land costs permit last-mile station scale. OSHA warehouse ergonomics standards indirectly shape labor costs through upstream facility automation requirements. The I-35 corridor connecting Laredo border crossings to Midwest markets anchors intermodal rail-to-last-mile transfer infrastructure.
Florida
Miami and Tampa Bay consumption clusters concentrate same-day delivery demand for grocery and apparel networks. The state's lack of income tax attracts distribution center operators seeking workforce stability. Orlando's position between Atlantic and Gulf Coast consumption zones enables flexible inventory positioning for seasonal demand spikes.
Illinois
Chicago's intermodal container networks connecting to Southeast consumption corridors remain underutilized relative to coastal port dependency. The Department of Transportation hours-of-service reforms reshape fleet economics for carriers operating across the Midwest-Southeast lanes. Rockford and Joliet submarkets absorb overflow warehousing demand as Chicago proper faces industrial land constraints.
Georgia
Atlanta anchors Southeast distribution with Savannah port access and I-75/I-85 corridor convergence. The region's consumption growth outpaces national averages, attracting automated storage and retrieval system deployment in temperature-controlled facilities. Augusta and Macon submarkets emerge as lower-cost alternatives for non-time-sensitive inventory positioning.
US Retail Logistics Market Key Industry Players
The competitive structure tilts toward asset-light broker platforms that mediate freight-matching economics across fragmented carrier bases. Consolidation pressure concentrates among intermodal operators and last-mile specialists, while digital intermediaries capture margin from spot market volatility. Three archetypes dominate: captive retail infrastructure operators, technology-forward freight brokers, and integrated intermodal asset owners. M&A activity targets regional last-mile density, and strategic partnerships link automated warehouse technology to transportation management platforms.
Among integrated intermodal specialists, J.B. Hunt occupies a position exemplifying container network control across Midwest-Southeast lanes. C.H. Robinson and Amazon represent contrasting archetypes—broker-mediated platform scale versus captive retail infrastructure insulation from third-party rate volatility. These three anchors illustrate the strategic divergence between asset-heavy and asset-light positioning in fleet economics reshaped by FMCSA electronic logging mandates.
| Leading Market Players |
|---|
| J.B. Hunt |
| Expeditors |
| Amazon |
| Kuehne + Nagel |
| Ryder Supply Chain Solutions |
| C.H. Robinson |
| UPS Supply Chain Solutions |
| Total Quality Logistics |
| GXO Logistics |
| Others |
Cost & Logistics Intelligence
Captive last-mile infrastructure anchors both supply positioning and pricing power for large omnichannel retailers. Amazon's exurban delivery density insulates rate structures from third-party carrier volatility, while asset-light brokers extract margin from spot-market fragmentation.
Pricing Analysis
Bundled warehousing-transportation contracts dominate enterprise procurement, though unbundled spot-market access gains share among mid-market shippers. Three-tier pricing structure across premium same-day, standard next-day, and economy multi-day levels separates velocity tiers. Cost compression in standard shipping intensifies because broker platforms compress carrier margins through freight-matching density. Small and mid-sized retailers exhibit highest price sensitivity, while grocery omnichannel networks absorb premium tiers for two-hour delivery windows.
Supply Chain Analysis
Diesel tractor-trailer supply rests on domestic OEM production anchored in Indiana, Ohio, and Michigan manufacturing clusters. Warehouse automation hardware draws from German and Japanese robotics specialists, while intermodal chassis production concentrates in Chinese and Mexican foundries. Single-source vulnerability runs through semiconductor components for electronic logging devices and warehouse management systems. Distribution runs through Texas-California-Florida corridor hubs where rail-to-last-mile transfer infrastructure converges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in automation payback cycles and premium-tier same-day delivery capture. Fleet digitization and micro-fulfillment density represent the primary cost-down drivers reshaping returns.
For Market Incumbents: Anticipate broker platform encroachment by consolidating regional last-mile density through targeted acquisitions. Secure captive intermodal container access across Midwest-Southeast lanes before asset-light competitors capture freight-matching economics. California Air Resources Board compliance timelines threaten drayage operator viability; accelerate electric yard truck partnerships or face facility access restrictions. For New Entrants and Emerging Players: Third-party logistics providers serving temperature-controlled grocery fulfillment represent the most penetrable incumbent segment. Target Midwest intermodal corridors connecting Chicago to Southeast consumption zones, where container network utilization lags coastal dependency. Lead with automated yard management software that converges computer vision with warehouse management systems. For Investors and Strategic Acquirers: Roll-up economics work for regional last-mile specialists because delivery density in exurban corridors resists national platform replication. Five-to-ten year viability hinges on land acquisition timing ahead of real estate scarcity near urban centers. Watch FMCSA hours-of-service enforcement patterns as inflection indicator for broker platform versus asset-heavy carrier returns.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Network Expansion | Compresses last-mile radii in Texas and Florida exurban corridors where land costs permit station scale. |
| Automated Storage and Retrieval Deployment | Absorbs repetitive picking labor in grocery distribution centers facing OSHA ergonomics compliance pressure. |
| Intermodal Container Network Control | Secures cost position across Midwest-Southeast lanes reshaped by FMCSA electronic logging mandates. |
| Electric Yard Truck Pilot Programs | Satisfies California Air Resources Board mandates at Long Beach and Los Angeles port complexes. |
| Digital Freight-Matching Platform Scale | Captures margin from spot-market volatility through broker-mediated carrier procurement. |
Research Approach
Direct dialogue with fleet operations directors, warehouse automation engineers, third-party logistics procurement leads, and intermodal rail planners grounded qualitative findings. Secondary validation drew from FMCSA regulatory filings, Department of Transportation hours-of-service records, EPA emissions compliance databases, and industrial real estate transaction reports. Bottom-up carrier capacity modeling and top-down retail fulfillment spending estimates were triangulated against trade association benchmarks.
Top-down macroeconomic indicators and bottom-up segment-level unit economics converged across the analysis window. Segmentation dimensions modeled include delivery velocity tier, service type ownership structure, technology deployment stage, and customer channel archetype. CAGRs were derived from logistics infrastructure investment cycles and e-commerce order profile evolution. Forecast inputs incorporated warehouse construction permit data and commercial driver license pipeline constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to California zero-emission vehicle mandate acceleration and autonomous trucking regulatory clarity. Assumptions reflect current FMCSA enforcement posture and exurban land availability trends. A small set of triggers—driver availability inflection, intermodal rail rate spikes, and warehouse automation integration failures—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
Iraq Freight and Logistics Market
Logistics and Shipping
Singapore Chemical Logistics Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Digital Freight Forwarder Market
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Brazil Freight and Logistics Market