
 Multicarrier Shipping Software Market | 2026-2036
Multicarrier Shipping Software Market Size, Share, and Industry Trends Forecast 2026-2036
Multicarrier Shipping Software Market Insights
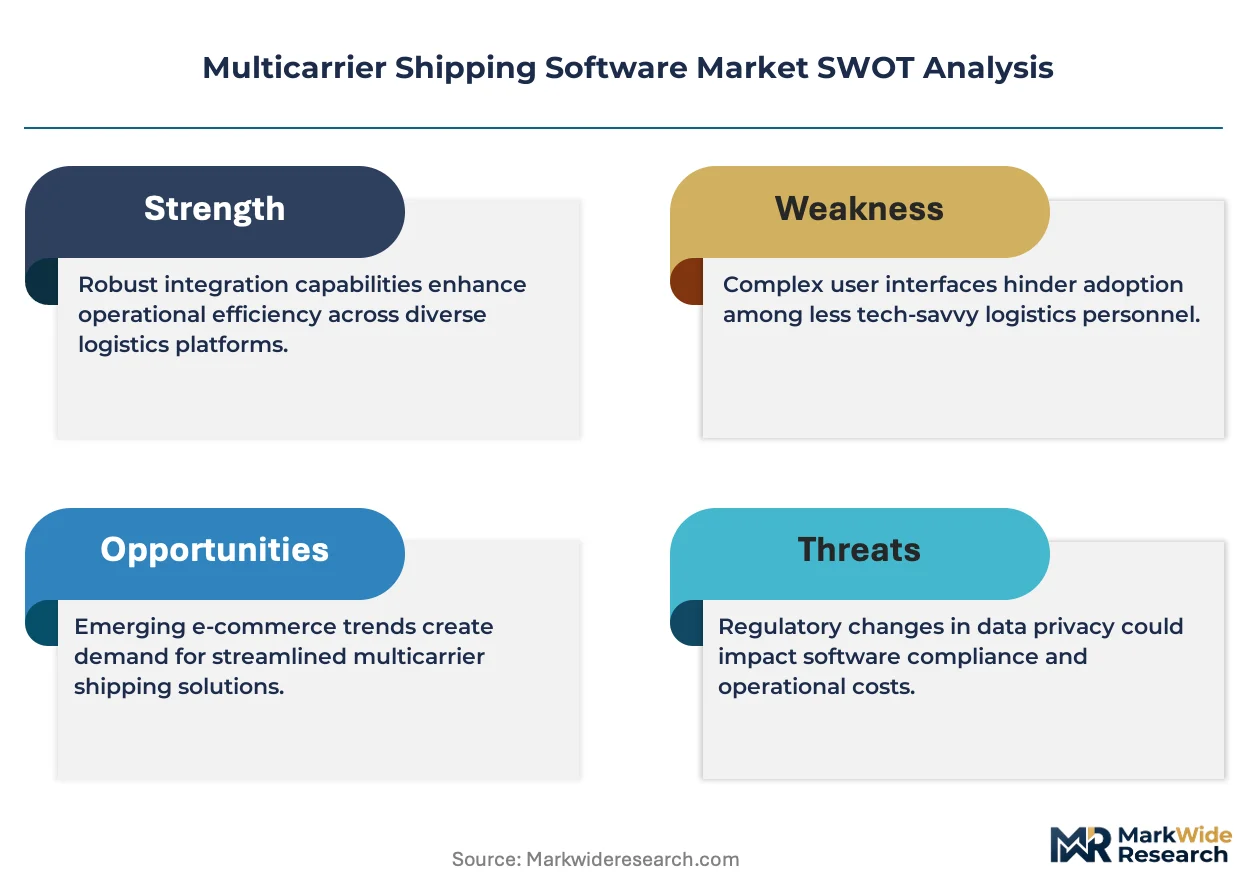
The multicarrier shipping software sector is pivoting sharply between premium enterprise suites and commodity parcel tools. Descartes Systems Group Inc. leverages its logistics network density to sustain high-margin platform contracts with multinational shippers. ShipStation competes aggressively on price for small and mid-sized e-commerce merchants. ProShip, Inc. specializes in complex enterprise integrations with warehouse management systems, occupying a defensible niche in high-volume fulfillment environments.
Multicarrier shipping software comprises cloud-native and on-premise platforms that aggregate carrier APIs, normalize rate data, and automate label generation across postal and parcel networks. These systems execute real-time rate shopping, address validation, and tracking consolidation through RESTful or SOAP-based interfaces, primarily serving organizations that ship through multiple carriers to optimize cost and service levels. Cloud-based deployment leads segment expansion due to lower implementation friction and faster carrier onboarding cycles. API integration represents the fastest-growing integration level, as merchants demand direct connectivity between storefronts and fulfillment engines without middleware latency.
The Federal Trade Commission monitors shipping cost transparency in consumer transactions, while the Federal Aviation Administration governs drone delivery pilots that software platforms must accommodate. The European Union's Digital Services Act and GDPR impose data residency and audit requirements on cross-border shipment tracking. Stakeholders must evaluate whether their carrier connectivity strategies can absorb emerging sustainability disclosure rules and autonomous last-mile regulations without architectural overhaul.
Market Dynamics
Carrier API proliferation is fragmenting integration architectures, forcing shippers to consolidate rate-shopping logic through middleware layers rather than direct carrier connections. Cloud-native platforms are capturing this consolidation demand by normalizing disparate carrier data formats into unified REST endpoints.
Growth Catalysts
- E-commerce fulfillment velocity:Direct-to-consumer brands require same-day label generation across postal, regional, and parcel networks to meet delivery promises. Multicarrier platforms aggregate these connections without custom carrier integrations.
- FAA drone delivery frameworks:Experimental airworthiness certifications for autonomous last-mile vehicles are creating new carrier categories that software platforms must accommodate through modular API architectures.
- GDPR data residency mandates:Cross-border shipment tracking requires EU-stored audit trails and consent management, driving replacement of legacy on-premise systems with cloud platforms offering regional data centers.
Market Restraints
- Carrier concentration risk:Three national parcel carriers control over 80% of US small-package volume, limiting rate negotiation leverage that software can deliver to shippers.
- Technical debt in WMS integration:Warehouse management systems running COBOL-based rate engines require expensive middleware translation layers, extending implementation timelines.
- FTC shipping cost disclosure rules:Mandatory upfront price display in checkout flows reduces carrier switching flexibility, compressing the value proposition of real-time rate shopping.
Strategic Opportunities
- Carbon accounting convergence:EU CSRD scope 3 emissions reporting requirements are creating demand for shipment-level CO2 calculation modules integrated into carrier selection algorithms.
- Mid-market ERP connectivity:NetSuite and SAP Business One users currently lack native multicarrier modules, representing an underserved integration segment.
- ISO 14064-1 certification pathways:Third-party verification of logistics emissions data is becoming a procurement prerequisite for enterprise shippers, enabling premium platform tiers.
Industry Challenges
- Carrier API versioning chaos:Major carriers release breaking changes to rating and label endpoints on 90-day cycles, requiring dedicated engineering resources for regression testing.
- Address validation standardization:Inconsistent international address formatting across 200+ postal authorities creates failed deliveries that shippers attribute to software providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multicarrier Shipping Software Market |
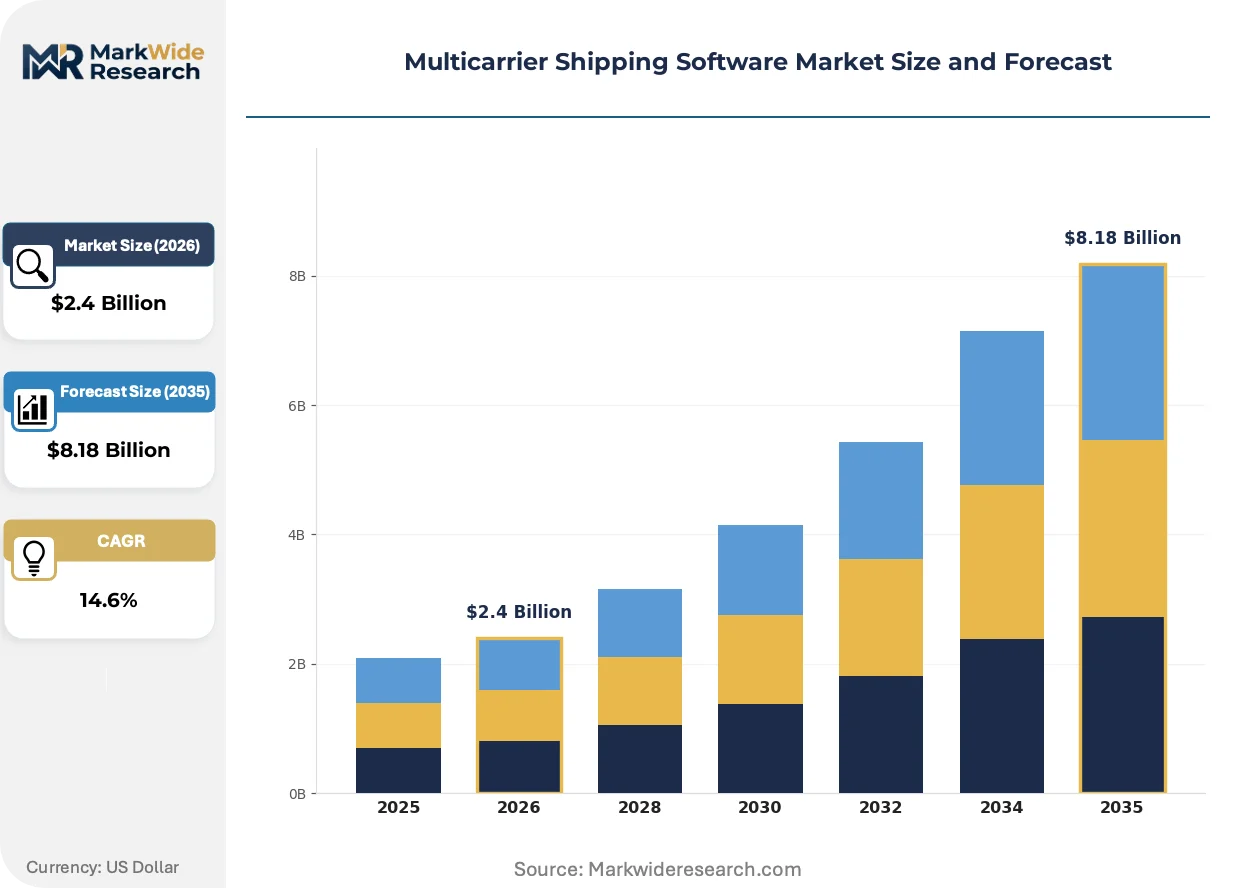
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: E-Commerce, Retail, Manufacturing, Logistics Service Type: Order Management, Tracking, Rate Shopping, Label Generation Integration Level: API Integration, ERP Integration, WMS Integration, Platform Integration |
| Companies Covered | Descartes Systems Group Inc., ShipStation, MetaPack, Pitney Bowes Inc., ProShip, Inc., Easyship, Shippo, ShippyPro, Centiro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multicarrier Shipping Software Market Trends and Innovations
Machine learning inference at the edge is compressing rate-decision latency from seconds to milliseconds, enabling checkout-integrated shipping calculations without page-load penalties. This architectural shift is redrawing competitive boundaries between pure-play shipping software and embedded commerce platforms.
GraphQL query layers are absorbing REST API fragmentation by allowing shippers to request precisely normalized rate, transit-time, and surcharge data across carriers in single round-trips. Mid-market merchants adopting headless commerce architectures are driving fastest uptake, with Shopify Plus and BigCommerce ecosystems showing particular momentum. The technology is absorbing complexity that previously required dedicated integration teams, collapsing carrier onboarding from months to days.
REACH substance-of-very-high-concern restrictions on lithium battery transport documentation are forcing software platforms to embed dangerous-goods classification engines directly into label workflows. Battery-powered electronics now require UN 38.3 test summary uploads at point of shipment, with carriers rejecting non-compliant labels. EU-based fulfillment centers are responding by pre-integrating compliance checks into address validation sequences.
Merchant procurement patterns are rotating toward outcome-based carrier performance guarantees rather than published rate tables. Enterprise shippers in Germany and the Netherlands now contract for on-time-in-full delivery percentages, with software platforms serving as measurement and penalty-calculation infrastructure. This shift is most visible in automotive and industrial parts verticals where production line stoppage costs dwarf shipping spend.
Multicarrier Shipping Software Market Segmentation
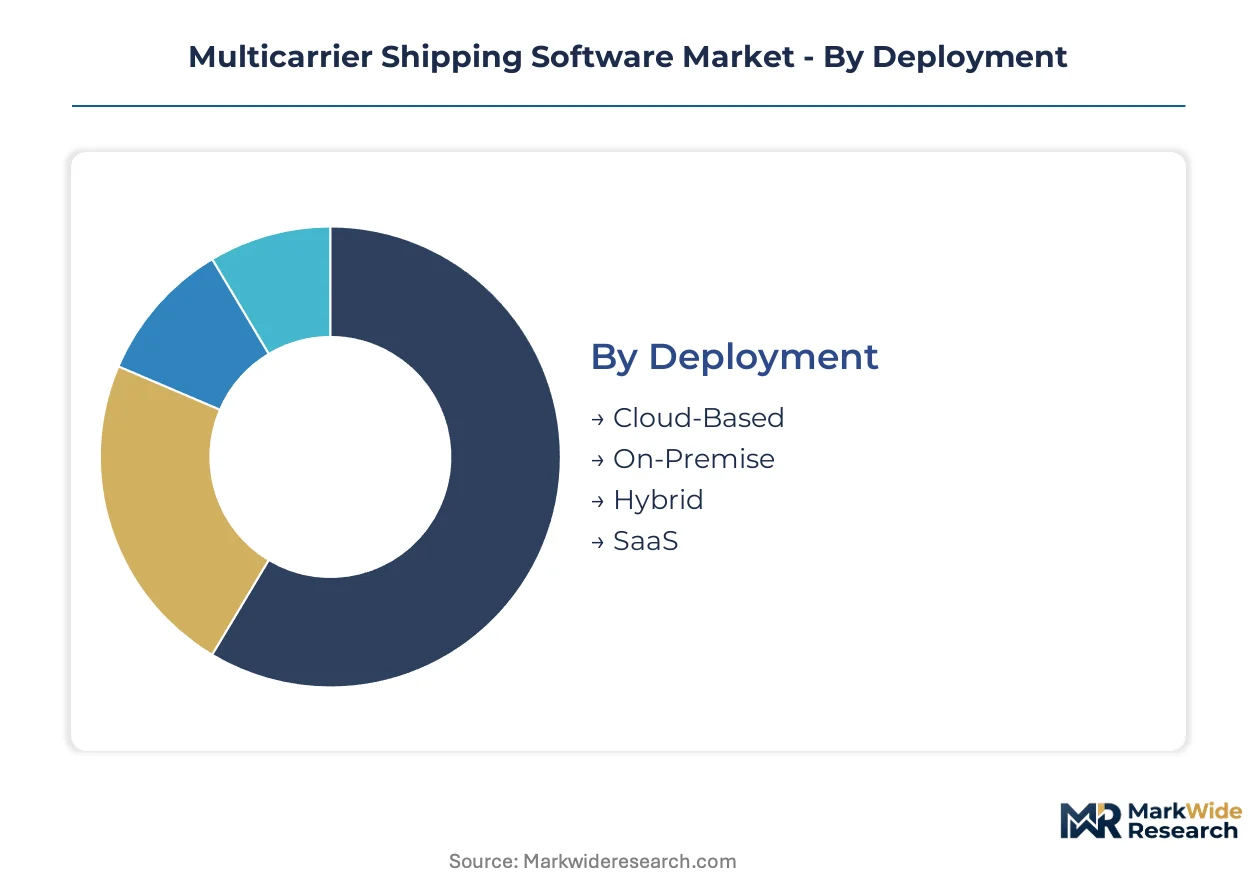
Segmentation in multicarrier shipping software reveals how procurement criteria diverge between cost-sensitive merchants and compliance-heavy enterprises. Deployment architecture and integration depth now determine platform selection more than carrier count or base subscription fees.
Deployment:
Volume deployments favor low-friction cloud models, while premium contracts cluster where data sovereignty demands physical infrastructure control.
- Cloud-Based:Browser-accessible platforms with multi-tenant architectures eliminate server maintenance overhead. E-commerce merchants in the United States gravitate toward these solutions for sub-24-hour carrier onboarding and automatic API updates.
- On-Premise:Dedicated server installations behind corporate firewalls satisfy pharmaceutical and defense sector audit requirements. German automotive suppliers specify these deployments to maintain GDPR-compliant audit trails without third-party data exposure.
- Hybrid:Split architectures keep rating engines local while pushing label generation to cloud endpoints.
- SaaS:Subscription models with usage-based tiering dominate mid-market procurement.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
End User:
Application context dictates feature prioritization, with fulfillment velocity requirements varying sharply across verticals.
- E-Commerce:Direct-to-consumer brands require checkout-integrated rate shopping across postal, regional, and parcel networks. Same-day delivery promises in the United States drive API-first platform adoption.
- Retail:Omnichannel merchants need unified shipping logic across storefront, warehouse, and drop-ship nodes. Buy-online-pickup-in-store fulfillment in France and the Netherlands demands real-time inventory-shipping synchronization.
- Manufacturing:Just-in-time production lines depend on guaranteed transit windows rather than lowest-cost routing.
- Logistics:Third-party fulfillment providers white-label multicarrier capabilities across multiple merchant accounts.
E-Commerce commands current platform revenue. Manufacturing offers the steepest expansion trajectory as industrial shippers digitize legacy routing decisions.
Service Type:
Service modules compete for implementation priority, with procurement patterns shifting from point solutions toward unified suites.
- Order Management:Centralized order ingestion from storefronts, marketplaces, and EDI feeds with automated routing rules. United States-based direct-to-consumer brands prioritize these modules to collapse order-to-label latency.
- Tracking:Consolidated event streams across carrier APIs with exception alerting. GDPR-compliant tracking portals for EU end consumers represent a mandatory feature in Germany and the Netherlands.
- Rate Shopping:Real-time cost optimization across contracted carrier rates.
- Label Generation:PDF and ZPL output with dangerous goods documentation.
Rate Shopping anchors current procurement RFPs. Tracking is gaining share fastest as delivery experience becomes a retention metric.
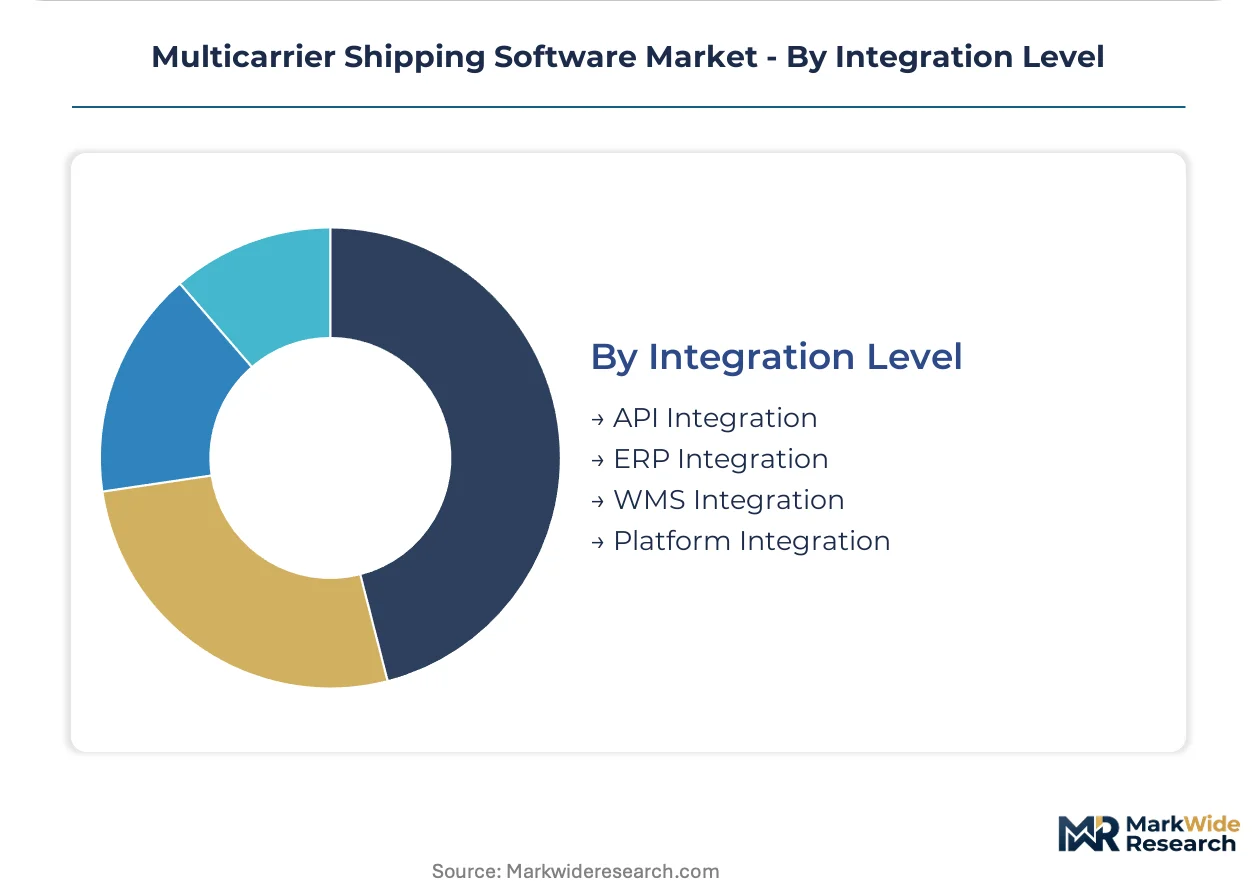
Integration Level:
Connectivity depth determines implementation cost and timeline, with headless commerce architectures reshaping technical requirements.
- API Integration:Direct REST or GraphQL connections between storefronts and shipping engines without middleware. Shopify Plus and BigCommerce ecosystems in the United States show particular momentum for this integration mode.
- ERP Integration:Native modules for financial and inventory synchronization. NetSuite and SAP Business One users currently lack robust multicarrier options, representing an underserved segment.
- WMS Integration:Warehouse management system plugins for pick-pack-ship workflows.
- Platform Integration:Pre-built connectors for e-commerce platforms and marketplaces.
API Integration leads current adoption. ERP Integration represents the largest untapped expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Seattle, Berlin, and Bengaluru anchor platform development for multicarrier shipping software. These concentrations support API infrastructure and cloud-native architectures that serve cross-border fulfillment networks.
United States
E-commerce fulfillment velocity and carrier diversification requirements drive platform adoption. The Federal Aviation Administration governs drone delivery pilots that software architectures must accommodate. Seattle and Austin host dense engineering clusters where API-first platforms compress carrier onboarding timelines.
Germany
Automotive just-in-time supply chains and pharmaceutical cold-chain compliance create demand for guaranteed transit windows. The EU's Digital Services Act and GDPR impose data residency requirements on cross-border tracking. Stuttgart and Munich anchor enterprise software development for industrial shippers.
United Kingdom
Omnichannel retail synchronization and post-Brexit customs documentation complexity spur integration investments. The Information Commissioner's Office enforces GDPR-compliant tracking portals for end consumers. London's fintech corridor attracts logistics software ventures serving pan-European merchants.
Netherlands
Rotterdam-Europoort distribution density and flower-perishable logistics demand precise delivery guarantees. REACH substance restrictions on lithium battery documentation force compliance engines into label workflows. Eindhoven's supply chain software cluster specializes in high-velocity fulfillment optimization.
India
Third-party logistics provider scaling and direct-to-consumer brand emergence create middleware demand. The Digital Personal Data Protection Act establishes consent frameworks for shipment tracking data. Bengaluru and Hyderabad host development centers building API aggregation layers for Asia-Pacific carrier networks.
Multicarrier Shipping Software Market Competitive Landscape
Capital-heavy platform operators compete with asset-light integration specialists across deployment models. Enterprise-grade vendors sustain premium contracts through warehouse management system depth, while commodity tools capture price-sensitive merchant segments. Three archetypes dominate: network-density platforms, mid-market SaaS providers, and specialized compliance engines. Consolidation through strategic acquisitions and API standardization partnerships represents the primary competitive vector.
Within the enterprise integration tier, Descartes Systems Group Inc. and ProShip, Inc. exemplify divergent specialization strategies. Descartes leverages logistics network density to anchor multinational contracts. ProShip occupies a defensible niche in high-volume fulfillment environments requiring complex warehouse management system connectivity. ShipStation represents the mid-market SaaS archetype, competing aggressively on implementation friction for small and mid-sized e-commerce merchants.
| Leading Market Players |
|---|
| Descartes Systems Group Inc. |
| ShipStation |
| MetaPack |
| Pitney Bowes Inc. |
| ProShip, Inc. |
| Easyship |
| Shippo |
| ShippyPro |
| Centiro |
| Others |
Pricing and Supply Chain Analysis
API engineering talent clustering in Seattle and Bengaluru creates labor-cost differentials that widen pricing-tier spreads between premium enterprise platforms and commodity SaaS tools. Cloud-native architectures command subscription premiums where specialized integration skills remain scarce, while standardized middleware offerings compete on per-transaction economics.
Pricing Analysis
Bundled platform suites versus unbundled point solutions define the pricing architecture. SaaS subscription tiers with usage-based scaling dominate mid-market procurement, while enterprise contracts blend fixed licensing with professional services. Price differentiation hinges on WMS integration depth and GDPR compliance certification. Cost compression in the commodity tier intensifies as carrier API standardization erodes proprietary connector value. Small e-commerce merchants exhibit highest price sensitivity; pharmaceutical and defense contractors prioritize audit capabilities over subscription cost.
Supply Chain Analysis
Domestic-content mandates for data residency are reshaping sourcing strategies across cloud infrastructure providers. Platform development concentrates in the United States, Germany, and India, with engineering delivery anchored in Bengaluru and Hyderabad. Raw material dependencies span cloud compute capacity, carrier API access agreements, and compliance documentation engines. Single-source vulnerability persists where major parcel carriers control rating endpoint access. Distribution runs through direct enterprise sales, channel partnerships with WMS vendors, and self-serve SaaS marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where compliance mandates generate replacement demand. The EU Digital Services Act and GDPR data residency requirements are accelerating platform migration cycles among cross-border shippers.
For Market Incumbents: Anticipate carrier API fragmentation by pre-building middleware abstraction layers that normalize breaking changes before customer impact. Invest in ISO 14064-1 certification pathways to capture carbon-accounting premiums as CSRD scope 3 reporting spreads. Defensive consolidation through WMS vendor partnerships protects against embedded commerce platforms absorbing shipping logic.
For New Entrants and Emerging Players: ERP implementation partners represent the most accessible channel for mid-market penetration. NetSuite and SAP Business One user bases lack native multicarrier modules, creating immediate white-space opportunity. Target manufacturing verticals in Germany and the Netherlands where just-in-time logistics demands guaranteed transit windows. Lead with GraphQL-native architectures that collapse carrier onboarding timelines.
For Investors and Strategic Acquirers: Logistics technology conglomerates are the most active acquirers in this space, seeking API aggregation capabilities to complement existing network infrastructure. Five-to-ten year viability favors platforms with warehouse management system integration depth over pure-play rate shopping tools. Monitor FAA drone delivery certification milestones as inflection indicators for autonomous last-mile software demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | GraphQL query layers absorb REST fragmentation for Shopify Plus ecosystems. |
| Compliance Engine Development | REACH lithium battery documentation modules prevent carrier label rejection. |
| Geographic Expansion | EU data centers satisfy GDPR residency mandates for German automotive suppliers. |
| Strategic Partnership | WMS vendor alliances defend against embedded commerce platform encroachment. |
| Acquisition of Specialist Firm | Carbon accounting modules integrate CO2 calculations into carrier selection algorithms. |
Research Methodology
Direct dialogue with logistics technology executives, carrier API product managers, e-commerce operations directors, and warehouse systems integrators grounded qualitative findings. Secondary validation drew from SEC filings of publicly traded logistics software vendors, FAA experimental airworthiness certifications, EU Digital Services Act implementation guidance, and customs data on cross-border e-commerce volumes. Bottom-up deployment estimates and top-down addressable market calculations were triangulated for consistency.
Segment-level outputs across deployment architecture, end-user vertical, service module, and integration depth were modeled over the projection horizon. CAGRs were derived from carrier API proliferation rates, cloud migration timelines, and e-commerce fulfillment velocity benchmarks. Forecast inputs included warehouse automation capex cycles, drone delivery regulatory progression, and ERP system replacement waves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carrier consolidation dynamics, autonomous vehicle regulatory frameworks, and sustainability disclosure rule expansion. Assumptions reflect current API standardization momentum and cross-border data governance trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
North America Same Day Delivery Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Cambodia Freight and Logistics Market