
 GCC Contract Logistics Market | 2026-2036
GCC Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Contract Logistics Market Foresight
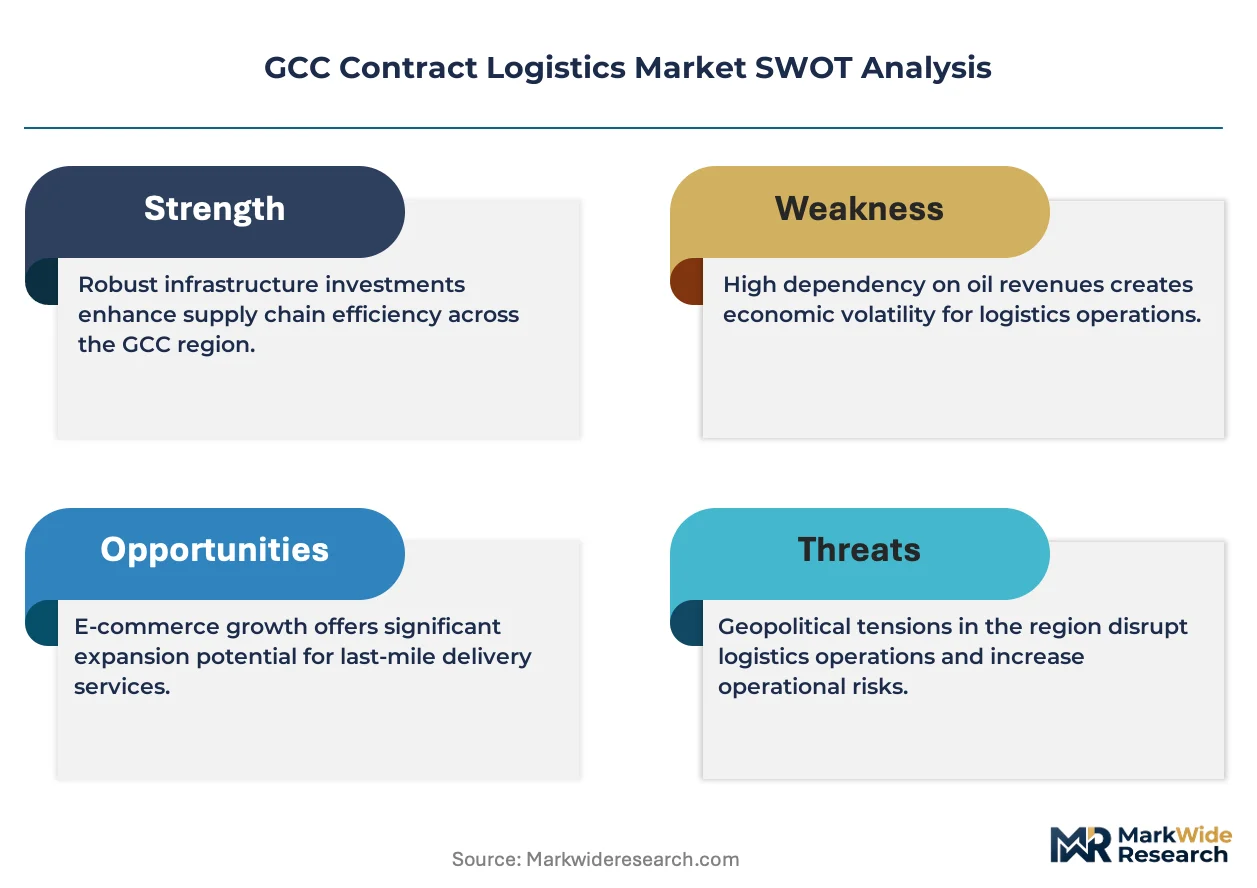
Saudi Vision 2030 sustainability targets are broadening contract logistics demand as state-backed industrial zones mandate LEED-certified warehousing and low-emission fleet transitions. DHL Supply Chain leverages its Jeddah-Riyadh corridor infrastructure to anchor pharmaceutical cold chain dominance. Agility Logistics competes through its Kuwait-based regional control tower and customs brokerage specialization. Gulf Warehousing Company dominates Qatar's hydrocarbon logistics with bonded warehouse certifications and defense-sector contracts.
Contract logistics encompasses the outsourced management of supply chain functions including transportation execution, inventory holding, order fulfillment, and value-added services under multi-year service agreements with defined KPI frameworks. GCC providers operate temperature-controlled facilities ranging from ambient to minus 25 degrees Celsius for pharmaceutical and food safety compliance. Warehousing services capture the largest margin pool as real estate scarcity in Dubai and Jeddah drives long-term lease premiums and automated storage retrieval investments. E-commerce platforms represent the fastest-growing customer type as same-day delivery commitments force inventory positioning closer to urban consumption centers.
Saudi Standards, Metrology and Quality Organization (SASO) enforces warehouse safety and product labeling standards that determine facility licensing across the Kingdom. UAE's Ministry of Economy and Dubai Customs coordinate free zone regulations that shape cross-border inventory routing and duty deferral structures. Stakeholders must monitor how Saudi PIF-backed giga-project construction schedules will redistribute freight volumes between Red Sea and Arabian Gulf port gateways.
Market Dynamics
Saudi Vision 2030's privatization mandates are forcing state-owned enterprises to divest logistics assets, creating immediate tender opportunities for third-party operators while rewiring procurement relationships across the Kingdom's industrial zones.
Growth Catalysts
- E-commerce fulfillment networks:Same-day delivery commitments from Saudi and UAE platforms are pulling inventory closer to urban consumption centers, expanding warehouse footprints in Riyadh and Dubai.
- SASO facility licensing:Saudi Standards, Metrology and Quality Organization warehouse safety mandates are disqualifying informal operators and consolidating volume toward certified third-party providers.
- Pharmaceutical cold chain:Temperature-sensitive biologics distribution requirements are driving investment in minus 25 degrees Celsius infrastructure across Jeddah and Dammam corridors.
Market Restraints
- Real estate scarcity:Dubai's Jebel Ali corridor and Jeddah's industrial zones face land constraints that inflate long-term lease premiums and compress facility development timelines.
- Equipment import dependence:Automated storage retrieval systems and fleet assets concentrate sourcing from European and East Asian manufacturers, exposing operators to currency and shipping volatility.
- Skilled technician shortage:Maintenance and calibration expertise for multi-temperature zone facilities remains concentrated among a limited pool of certified engineers across the Gulf.
Strategic Opportunities
- Qatar hydrocarbon logistics:Bonded warehouse certifications for defense and energy sector contracts remain underpenetrated by regional players outside Doha-based incumbents.
- Kuwait control tower services:Centralized freight coordination and customs brokerage specialization offer expansion vectors for operators with existing Saudi-UAE corridor infrastructure.
- LEED-certified warehousing:Saudi PIF-backed giga-projects are mandating sustainable facility standards, creating first-mover advantages for operators with pre-certified assets.
Industry Challenges
- Legacy WMS integration:Enterprise resource planning system compatibility gaps between shipper platforms and third-party warehouse management systems delay contract onboarding.
- Multi-temperature certification timelines:Pharmaceutical and food safety accreditations require 12-18 month validation cycles that constrain rapid capacity scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Contract Logistics Market |
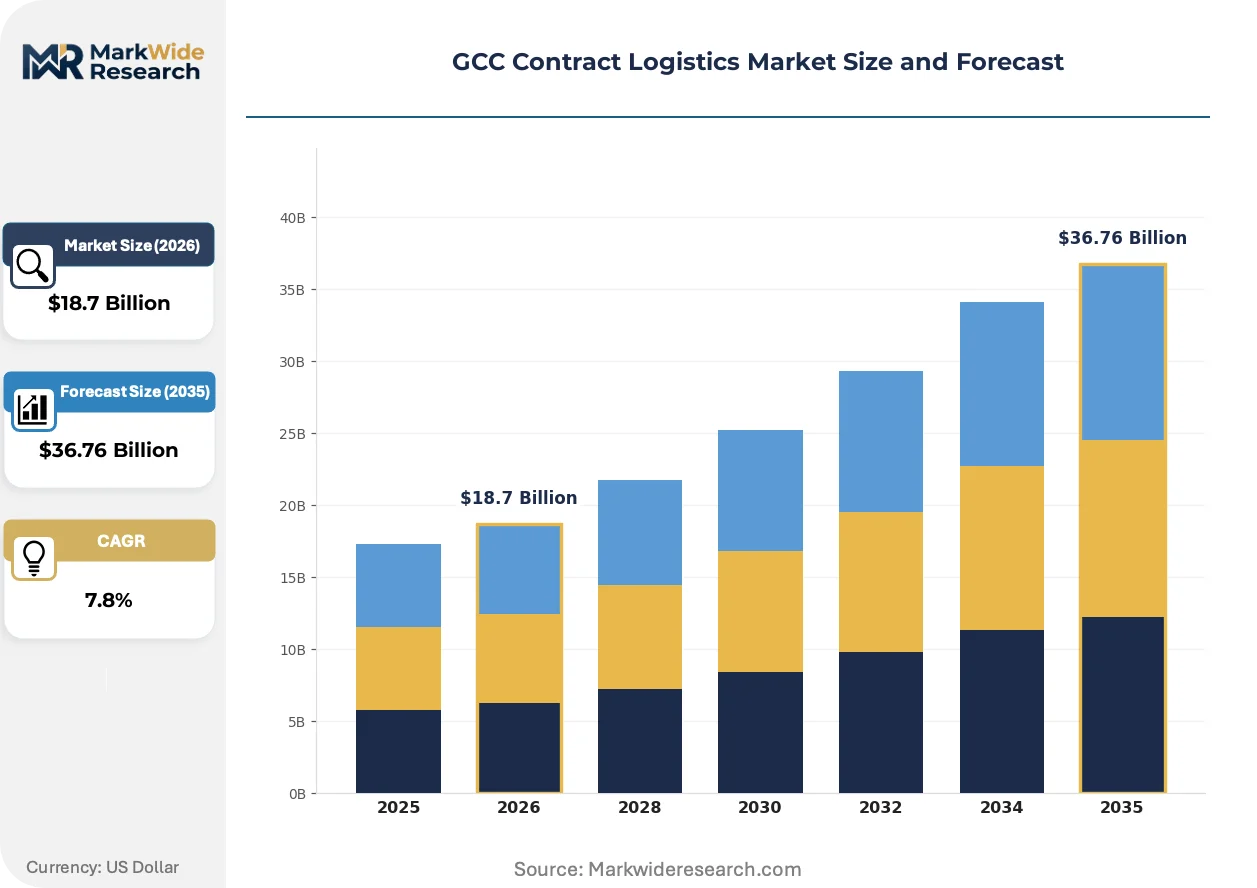
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Inventory Management, Packaging, Distribution Industry Vertical: Consumer Electronics, Pharmaceuticals, Automotive OEMs, FMCG, Oilfield Equipment, Food & Beverage Customer Type: Manufacturers, Retailers, Wholesalers, E-commerce Platforms, Government Agencies, Construction Firms Technology Integration: Warehouse Management System, Transport Management System, RFID Tracking, GPS Monitoring, Automated Sorting, Cloud-based Platforms |
| Companies Covered | Deutsche Post DHL Group (DHL Supply Chain), Al Futtaim Logistics, Agility Logistics, Hellmann Worldwide Logistics, Yusen Logistics, Ceva Logistics, Gulf Warehousing Company (GWC), Almajdouie Logistics, DB Schenker, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Contract Logistics Market Shifts & Advancements
Operational technology investments are compressing fulfillment cycle times while regulatory pressure on emissions and safety is redefining facility specifications across Saudi Arabia and the UAE.
Autonomous mobile robots are automating put-away and picking workflows in Dubai's high-velocity e-commerce fulfillment centers. Retail platforms operating same-day delivery networks are deploying these systems at scale to offset labor availability constraints. The technology is automating inventory positioning decisions that previously required manual oversight, reducing dock-to-stock intervals by half.
SASO's warehouse safety enforcement protocols are mandating fire suppression, racking integrity, and product labeling standards that determine facility licensing eligibility. Industrial developers in Riyadh's emerging zones are pre-integrating these specifications into greenfield construction to accelerate operator certification. Pharmaceutical and food-grade tenants are prioritizing SASO-compliant assets, compressing demand toward certified facilities.
Shippers are unbundling transportation execution from inventory holding to optimize working capital deployment. E-commerce platforms are retaining direct control over last-mile fleet operations while outsourcing forward stock positioning to third-party warehouse operators. This bifurcation is most visible in Saudi Arabia, where Vision 2030 localization targets are pressuring foreign platforms to demonstrate domestic supply chain investment.
GCC Contract Logistics Market Segmentation
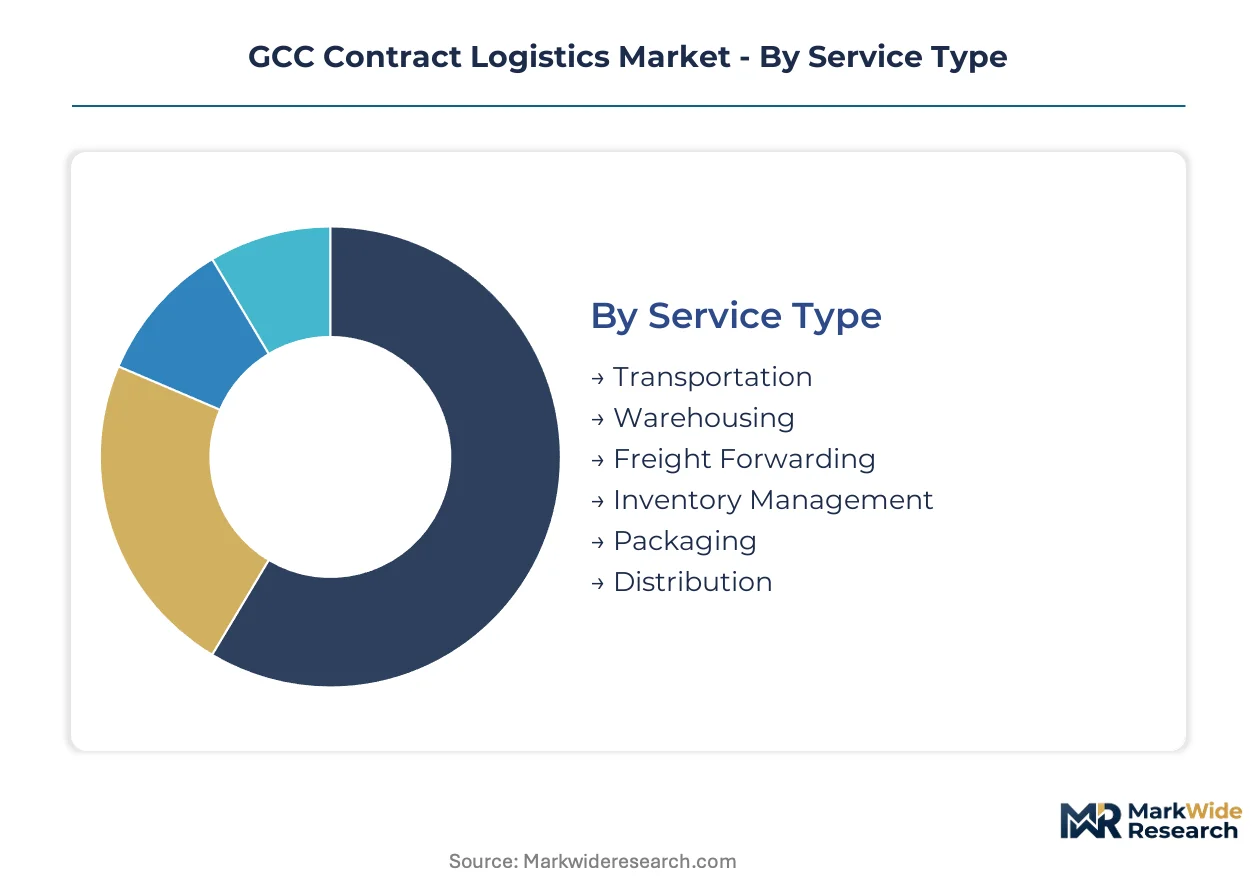
GCC contract logistics operators configure service portfolios around asset-heavy warehousing and asset-light freight coordination. Segment boundaries blur as integrated providers bundle transportation execution with inventory holding under unified KPI frameworks. Procurement teams evaluate segments against capital intensity, regulatory exposure, and network density requirements.
Service Type:
Warehouse scarcity in Dubai's Jebel Ali corridor and Riyadh's emerging industrial zones concentrates margin capture in facility-based services.
- Transportation:Fleet operations span dedicated contract carriage and spot-market brokerage across Saudi Arabia's Red Sea-Arabian Gulf axis. Demand clusters around pharmaceutical cold chain and automotive just-in-time sequences where temperature integrity and delivery precision determine contract renewal.
- Warehousing:Multi-temperature facilities ranging from ambient to minus 25 degrees Celsius command lease premiums in land-constrained Jeddah and Dubai. Real estate scarcity drives automated storage retrieval investments to maximize cube utilization per square meter.
- Freight Forwarding:Customs brokerage and cross-border documentation coordination for GCC free zone routing.
- Inventory Management:Vendor-managed stock programs and safety buffer optimization for manufacturing supply chains.
- Packaging:Value-added kitting, labeling, and promotional bundling services for retail distribution.
- Distribution:Last-mile execution and regional hub consolidation for e-commerce fulfillment networks.
Warehousing absorbs the bulk of installed capacity; distribution is expanding most quickly.
Industry Vertical:
Regulatory compliance intensity varies sharply across verticals, with pharmaceutical and food safety mandates disqualifying generalist operators.
- Consumer Electronics:High-velocity fulfillment centers in Dubai process smartphone and appliance volumes with same-day delivery commitments. Seasonal demand spikes around Ramadan and Gulf shopping festivals strain forward stock positioning.
- Pharmaceuticals:Temperature-sensitive biologics distribution requires SASO-validated cold chain infrastructure across Jeddah-Riyadh-Dammam corridors. Vaccine and insulin shipments drive investment in redundant backup power and real-time telemetry systems.
- Automotive OEMs:Sequenced parts delivery to Saudi assembly plants and UAE free zone manufacturing.
- FMCG:High-frequency replenishment of retail shelves with short shelf-life inventory rotation.
- Oilfield Equipment:Project logistics for Saudi Aramco and ADNOC procurement with bonded warehouse requirements.
- Food & Beverage:Halal certification compliance and perishable cold chain for retail and foodservice distribution.
Pharmaceuticals commands the steepest facility investment per square meter; consumer electronics shows the steepest expansion trajectory.
Customer Type:
Procurement sophistication diverges between multinational manufacturers with centralized tenders and fragmented local construction contractors.
- Manufacturers:Industrial producers outsource inbound material handling and finished goods distribution to optimize working capital. Saudi Vision 2030 localization targets pressure foreign manufacturers to demonstrate domestic supply chain investment through third-party contracts.
- Retailers:Department store and hypermarket chains consolidate regional distribution through shared-user facilities in Dubai and Riyadh. Promotional calendar volatility demands flexible labor scaling and surge capacity access.
- Wholesalers:Traditional trade distributors serving fragmented grocery and pharmacy networks.
- E-commerce Platforms:Pure-play digital retailers and marketplace operators with same-day delivery service level agreements.
- Government Agencies:Defense and healthcare procurement with bonded warehouse and security clearance requirements.
- Construction Firms:Project-based logistics for Saudi giga-project sites with temporary staging yard needs.
Manufacturers anchor long-term contract value; e-commerce platforms are climbing the fastest.
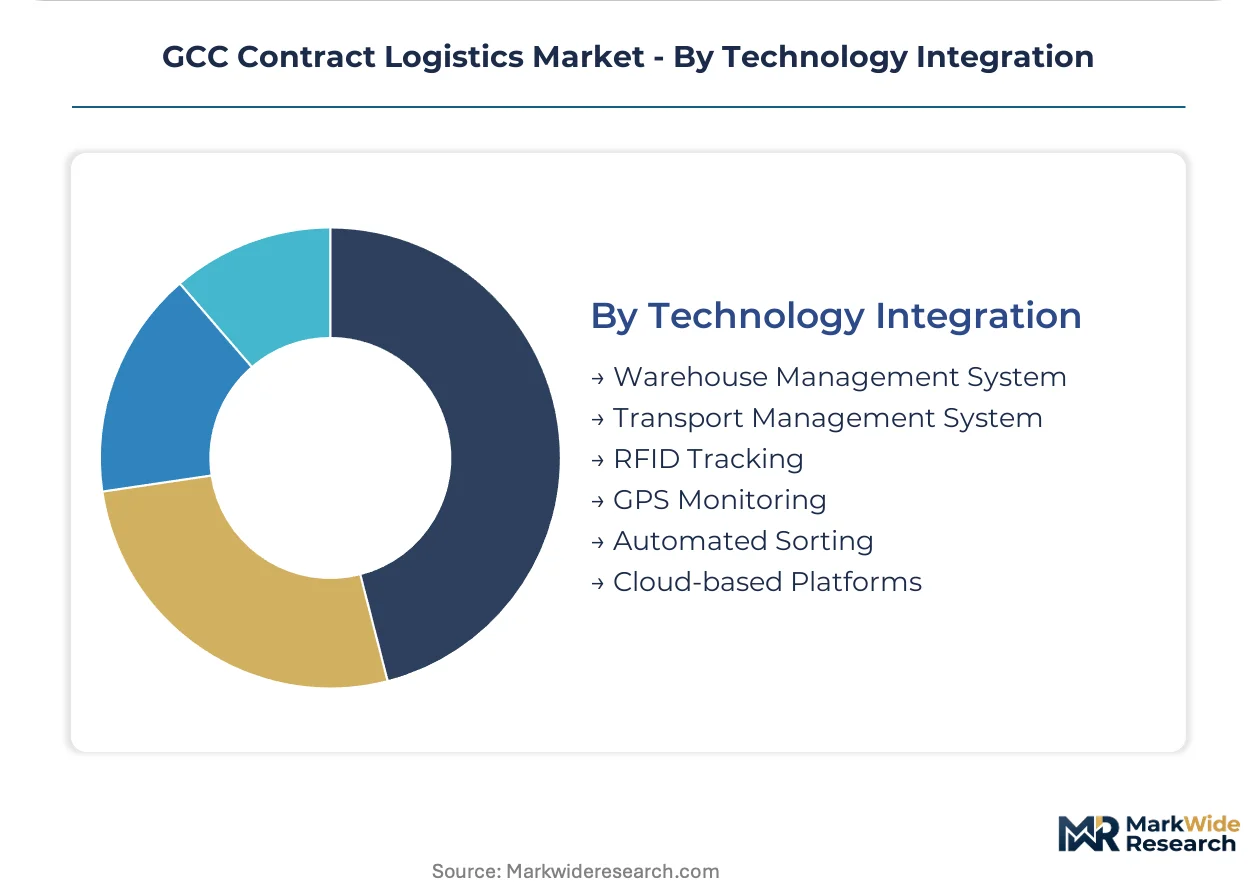
Technology Integration:
System interoperability gaps between shipper ERP platforms and third-party warehouse management systems delay contract onboarding.
- Warehouse Management System:Real-time inventory visibility and labor optimization modules integrate with automated material handling equipment. Saudi and UAE operators prioritize cloud-native architectures to accelerate deployment across multi-site networks.
- Transport Management System:Route optimization and carrier selection algorithms reduce empty kilometers across GCC highway corridors. Fuel cost volatility and driver hour regulations drive adoption among mid-size fleet operators.
- RFID Tracking:Item-level serialization for pharmaceutical authentication and retail loss prevention.
- GPS Monitoring:Fleet telematics for delivery confirmation and cold chain temperature logging.
- Automated Sorting:Parcel handling systems for high-volume e-commerce fulfillment centers.
- Cloud-based Platforms:API-first integration layers connecting shipper systems with logistics execution.
Warehouse Management System captures the dominant share of technology spending; cloud-based platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia consumes the largest share of contract logistics services while the UAE concentrates operational capacity. Infrastructure investment patterns diverge between consumption-driven warehousing demand and trade-gateway specialization.
Saudi Arabia
Saudi Vision 2030 giga-projects and e-commerce platform expansion are pulling inventory toward Riyadh and Jeddah consumption corridors. SASO warehouse safety mandates are disqualifying uncertified operators and consolidating volume toward compliant third-party providers. NEOM's northwest development and the Red Sea Project are redistributing freight volumes between Red Sea and Arabian Gulf port gateways.
United Arab Emirates
Dubai's Jebel Ali corridor anchors regional trade-gateway logistics with bonded warehouse infrastructure and free zone duty deferral structures. Dubai Customs and the Ministry of Economy coordinate cross-border inventory routing regulations that shape operator licensing. Same-day delivery commitments from e-commerce platforms are expanding automated fulfillment center footprints in Dubai South and Abu Dhabi Khalifa Industrial Zone.
Qatar
Hydrocarbon sector procurement and defense logistics contracts concentrate demand in Doha-based bonded warehouse facilities. The country's national logistics regulator enforces facility certification standards for energy and aerospace supply chains. Ras Laffan Industrial City and Mesaieed Industrial Area host specialized operators serving QatarEnergy and defense sector tenders.
Kuwait
Regional control tower services and customs brokerage specialization differentiate operators serving Saudi-UAE corridor freight coordination. The central logistics authority oversees cross-border documentation standards for GCC routing. Shuwaikh Port and Mina Abdullah industrial zones concentrate warehousing investment serving re-export and domestic distribution.
Bahrain
Financial services and pharmaceutical logistics demand are expanding temperature-controlled facility requirements in the Sitra and Hidd industrial areas. The national investment authority promotes logistics zone development adjacent to Khalifa Bin Salman Port. Operators are positioning to capture Saudi market overflow from land-constrained eastern province industrial zones.
GCC Contract Logistics Market Competitive Landscape
The competitive structure tilts toward diversified multinational providers with integrated service portfolios. Tier-one operators combine asset-heavy warehousing with asset-light freight coordination under unified KPI frameworks. Three archetypes dominate: global integrated logistics networks, regional specialists with customs brokerage depth, and state-adjacent operators capturing hydrocarbon and defense contracts. Competitive moves concentrate on LEED-certified facility pre-positioning and automated storage retrieval deployment in land-constrained Jeddah and Dubai corridors.
Within the global integrated tier, Deutsche Post DHL Group and DB Schenker represent asset-heavy network operators with pharmaceutical cold chain infrastructure. Regional specialists include Agility Logistics, which occupies a position emphasizing control tower coordination. Gulf Warehousing Company exemplifies the state-adjacent archetype serving Qatar's energy and defense procurement. Almajdouie Logistics anchors Saudi-focused industrial logistics. Al Futtaim Logistics sits within the UAE-centric retail and automotive distribution segment.
| Leading Market Players |
|---|
| Deutsche Post DHL Group (DHL Supply Chain) |
| Al Futtaim Logistics |
| Agility Logistics |
| Hellmann Worldwide Logistics |
| Yusen Logistics |
| Ceva Logistics |
| Gulf Warehousing Company (GWC) |
| Almajdouie Logistics |
| DB Schenker |
| Others |
Supply & Pricing Matrix
Automated storage retrieval systems sourced from European and East Asian manufacturers flow through currency-adjusted procurement tiers into warehouse lease premiums, compressing margins for operators lacking scale purchasing power while concentrating pricing power among integrated providers with captive equipment sourcing.
Pricing Analysis
Outcome-based contracts tied to inventory accuracy and on-time-in-full delivery metrics anchor value-based pricing for pharmaceutical and e-commerce fulfillment segments. Three-tier pricing structure across premium certified, standard compliant, and economy generalist levels separates SASO-validated cold chain facilities from ambient warehousing. Cost compression in economy tiers is intensifying because informal operators face disqualification under tightening safety mandates. E-commerce platforms show the least price sensitivity due to same-day delivery SLA penalties, while construction contractors exhibit the highest sensitivity given project-based procurement cycles.
Supply Chain Analysis
Regional distribution centers in Dubai's Jebel Ali corridor and Riyadh's emerging industrial zones form a hub-and-spoke pattern radiating toward consumption clusters. Equipment sourcing draws from Germany, Japan, and South Korea for automated material handling systems. Single-source vulnerability concentrates in ASRS component suppliers exposed to shipping lane disruptions. Distribution runs through bonded warehouse facilities in free zones with duty deferral structures shaping cross-border inventory positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Land scarcity in Jeddah and Dubai industrial corridors props facility lease premiums, creating supply-constrained pricing power for certified operators with pre-positioned assets.
For Market Incumbents: Lock in long-term lease agreements in Riyadh's emerging zones before SASO certification mandates disqualify competitor expansions. Secure backward integration into equipment maintenance capabilities to offset skilled technician shortages threatening uptime guarantees. Consolidate through selective acquisition of distressed ambient warehousing operators facing compliance-driven obsolescence. For New Entrants and Emerging Players: Launch via specialized pharmaceutical cold chain services in Dammam corridor where temperature-validated infrastructure remains undersupplied relative to biologics distribution demand. Target Qatar hydrocarbon logistics segment where bonded warehouse certifications for defense contracts face limited regional competition. Prioritize LEED-certified greenfield construction to capture Saudi PIF-backed giga-project tenders mandating sustainable facility standards. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale operators with SASO pre-certification in secondary Saudi cities where land costs lag primary corridor premiums. Five-to-ten year viability hinges on automation deployment pace and regulatory compliance depth rather than pure scale. Monitor Saudi Aramco and ADNOC procurement schedule shifts as inflection indicators for oilfield equipment logistics demand.| Strategic Initiative | Industry Significance |
|---|---|
| LEED-Certified Warehouse Pre-Positioning | Captures Saudi PIF giga-project mandates requiring sustainable facility standards ahead of competitor certification timelines. |
| Pharmaceutical Cold Chain Infrastructure Investment | Secures SASO-validated minus 25 degrees Celsius capacity for biologics distribution along Jeddah-Riyadh-Dammam corridors. |
| Automated Storage Retrieval Deployment | Maximizes cube utilization per square meter in land-constrained Dubai Jebel Ali and Jeddah industrial zones. |
| Customs Brokerage Specialization | Differentiates Kuwait-based operators serving Saudi-UAE corridor freight coordination with centralized control tower services. |
| Multi-Temperature Zone Certification | Accelerates facility licensing eligibility under tightening SASO warehouse safety and product labeling enforcement protocols. |
Research Methodology
Trade publications, customs filings, and free zone regulatory notices formed the secondary backbone, supplemented by primary interviews with warehouse operations directors, pharmaceutical supply chain managers, e-commerce fulfillment executives, and customs brokerage specialists. Bottom-up facility capacity counts across Dubai, Riyadh, Jeddah, and Dammam corridors were triangulated against top-down contract value estimates derived from disclosed tender awards and lease transaction benchmarks.
Historical trendline analysis of warehousing absorption rates and automation investment cycles informed the projection framework across service type, industry vertical, and customer segmentation dimensions. Modeled variables included e-commerce penetration trajectories, SASO enforcement intensity timelines, and PIF project construction schedules. CAGRs were derived from regression-adjusted capacity expansion curves rather than linear extrapolation.
Regulatory enforcement delays, currency volatility in equipment import markets, and skilled labor availability constraints are the dominant revision risks to capacity and pricing assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
Shipping Supplies Market
Logistics and Shipping
United Kingdom Freight and Logistics Market
Logistics and Shipping
Cold Chain Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Halal Logistics Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
France Parcel Market