
 Automotive Logistics Market | 2026-2036
Automotive Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Logistics Market Analysis
Modular parts bundling is shifting how OEMs procure inbound logistics services, replacing discrete component shipments with pre-assembled kit deliveries. DHL International GmbH leverages its global warehousing footprint to support this transition. XPO Logistics anchors North American finished-vehicle distribution through its dedicated transport network. Kuehne + Nagel specializes in ocean freight consolidation for automotive shippers moving production parts from Asia to Europe.
Automotive logistics encompasses the planning, execution, and control of material flows from raw material suppliers through Tier-1 and Tier-2 vendors to final vehicle assembly and distribution, incorporating multimodal coordination with temperature-sensitive and just-in-time delivery parameters. The discipline ensures production continuity for OEMs operating lean manufacturing systems with minimal inventory buffers. Transportation services dominate value capture given fuel volatility and driver scarcity, while warehousing margins expand as OEMs outsource parts sequencing and quality inspection. Telematics adoption is accelerating fastest among road freight operators seeking real-time visibility into vehicle location and condition across dealer networks.
The EPA enforces emissions standards that affect fleet composition and route optimization for logistics providers serving US automotive clients. EMA guidelines and REACH compliance requirements in Europe mandate hazardous-material documentation for battery and paint shipments moving through automotive supply chains. The EU AI Act introduces algorithmic accountability rules that will affect automated dispatch and predictive maintenance systems deployed by logistics platforms. Stakeholders must weigh regulatory compliance costs against operational efficiency gains when selecting technology investments for cross-border automotive freight.
Market Dynamics
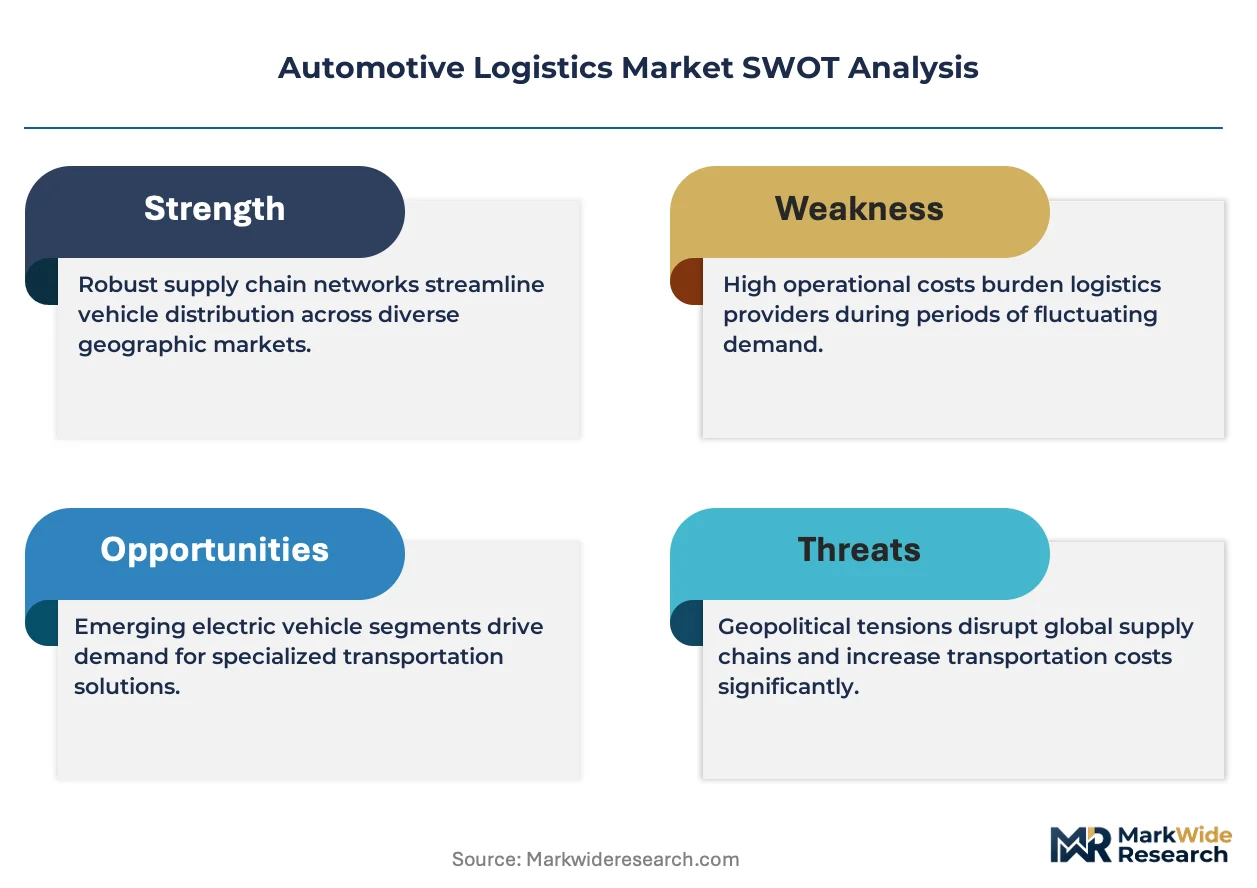
Electric vehicle platform standardization is compressing legacy powertrain logistics networks while expanding battery supply chain complexity. Tier-1 suppliers must reconfigure warehouse footprints to accommodate hazardous-material storage protocols and thermal-controlled transport corridors.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Automotive OEMs are relocating final assembly capacity to EU member states to minimize embedded-emissions tariffs on imported vehicles.
- Solid-state battery commercialization:Dry-electrode cell manufacturing requires precision logistics for moisture-sensitive electrolyte materials and inert-atmosphere transport containers.
- Stuttgart-Munich-Wolfsburg corridor concentration:German OEM clustering generates dense just-in-time parts flows that justify dedicated high-frequency rail shuttles from supplier parks.
Market Restraints
- Lithium hydroxide price volatility:Battery cell producers face margin compression when cathode-active-material costs spike, forcing logistics providers to absorb inventory carrying-cost increases.
- Semiconductor foundry concentration in Taiwan:Single-source dependency for automotive-grade chips creates vulnerability to shipping lane disruptions through the Taiwan Strait.
- REACH substance authorization delays:Automotive coatings and adhesives containing restricted chemicals face extended compliance timelines that stall new model launches.
Strategic Opportunities
- Polish-Czech battery corridor underdevelopment:Central European locations offer lower-cost warehousing for EV component distribution into German assembly plants.
- Vehicle-to-grid integration services:Logistics platforms can capture value from bidirectional charging infrastructure deployed at distribution yards.
- EU AI Act algorithmic dispatch compliance:First-mover platforms that build explainable routing systems will win OEM contracts requiring audit trails for automated freight allocation.
Industry Challenges
- Hazmat-certified driver scarcity:Battery transport regulations require ADR-licensed operators, and training pipeline capacity lags demand expansion.
- Multi-enterprise platform integration:OEMs operate legacy ERP systems that resist API connectivity with cloud-based freight visibility tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Logistics Market |
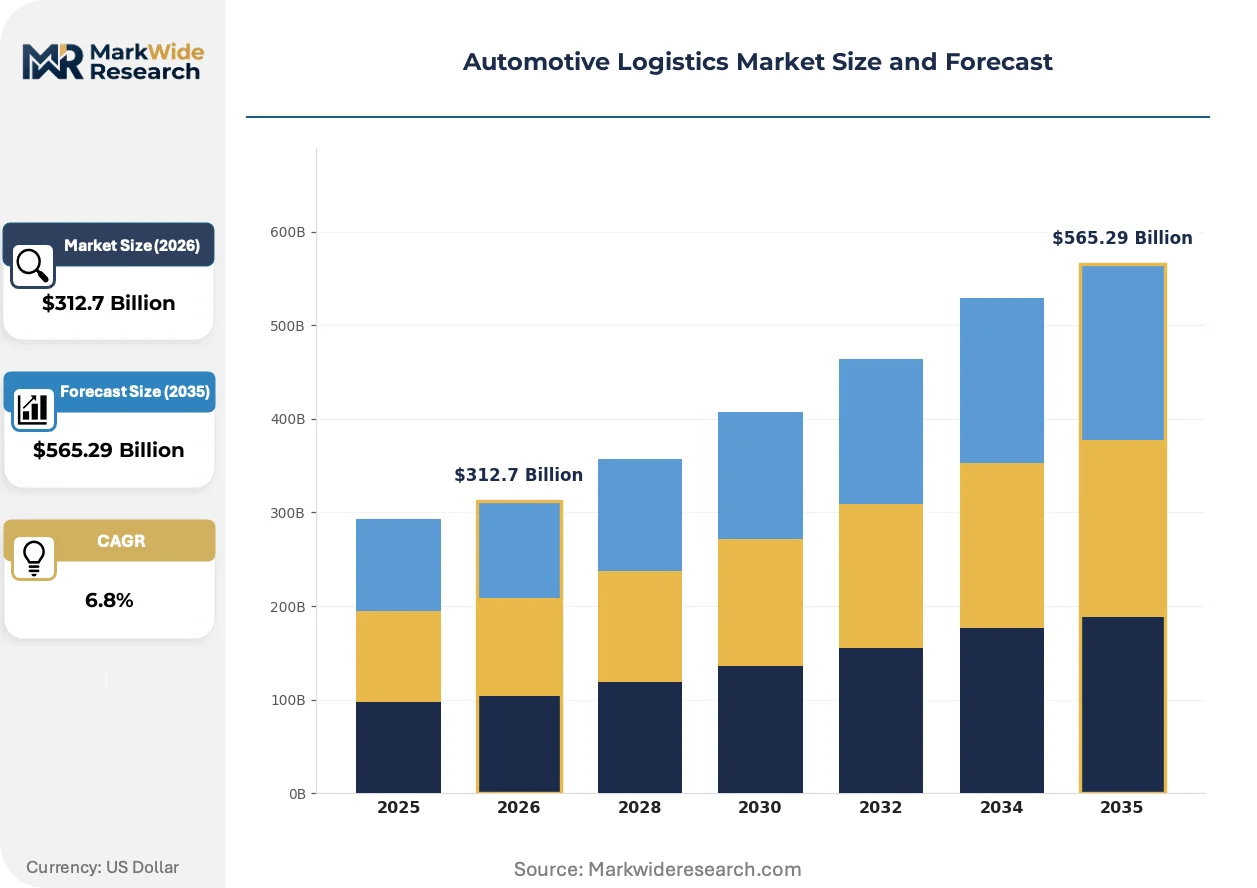
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Freight Forwarding Technology: Telematics, RFID, WMS, TMS End User: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers Delivery Mode: Road, Rail, Sea, Air |
| Companies Covered | DHL International GmbH, XPO Logistics, Kuehne + Nagel, CEVA Logistics, DSV, DB Schenker, Ryder System, Expeditors International, Deutsche Post AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Logistics Market Emerging Trajectories
Digital freight matching platforms are compressing spot-market transaction costs while autonomous yard tractors are automating trailer repositioning at vehicle distribution centers. These shifts are redrawing competitive boundaries between asset-heavy carriers and technology-enabled brokers.
Autonomous yard management systems are automating trailer sequencing and gate coordination at high-volume vehicle processing facilities. Major OEM distribution centers in the US and Germany are piloting these systems to reduce dwell time and labor dependency. The technology is automating repetitive material-handling tasks that previously required dedicated spotter crews.
REACH compliance documentation requirements are mandating digital substance passports for automotive plastics and coatings crossing into EU customs territory. Suppliers must retrofit legacy inventory systems to track chemical composition at the batch level. Battery manufacturers face the steepest adaptation burden due to cathode material complexity.
Buyers are consolidating logistics procurement under outcome-based contracts that penalize delivery variance rather than paying fixed transport rates. Tier-1 suppliers in Germany are leading this shift, replacing rate-card agreements with guaranteed-sequence contracts. The model transfers inventory-risk ownership from OEMs to logistics providers while demanding real-time visibility infrastructure.
Automotive Logistics Market Segmentation
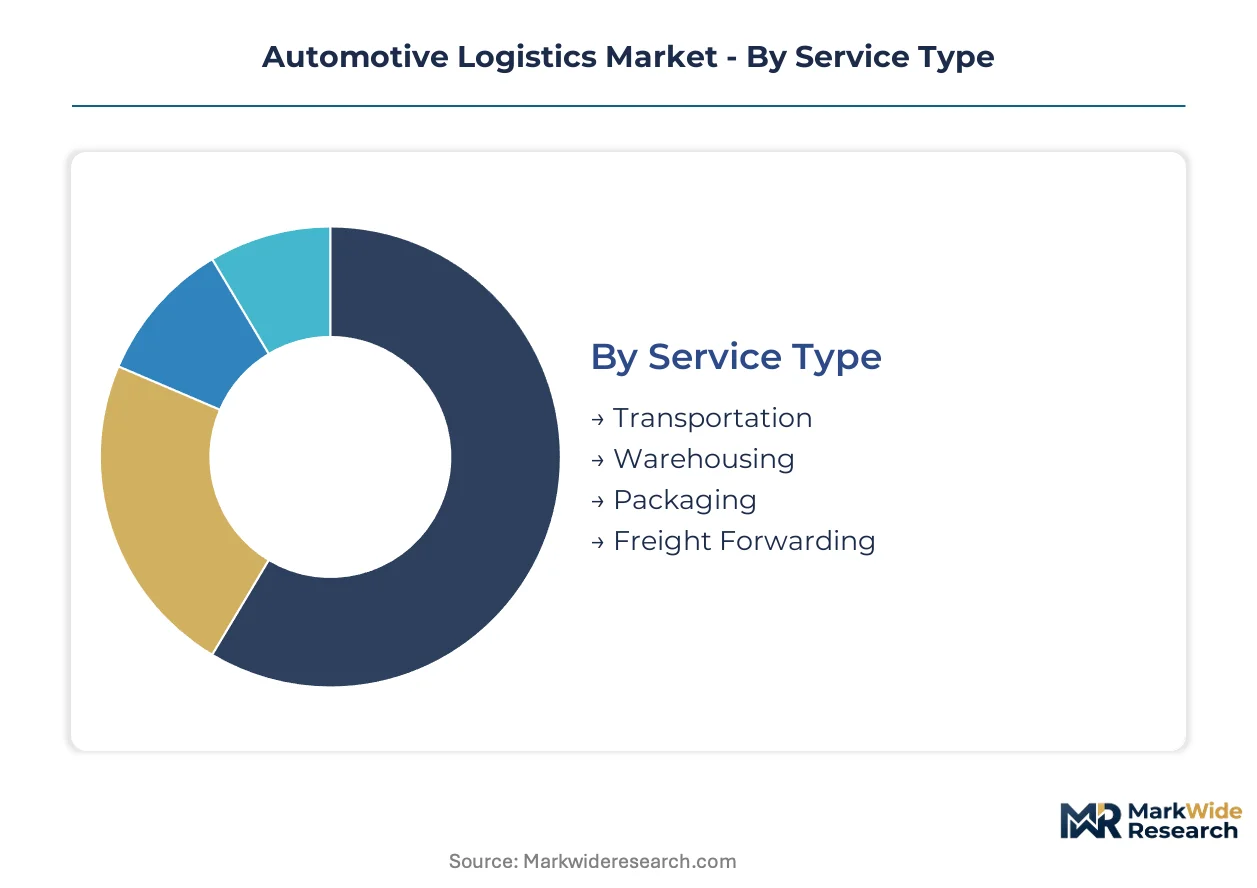
Automotive logistics segmentation reflects divergent buyer priorities across the value chain. OEM procurement teams select service bundles based on inventory-risk transfer preferences, while Tier-1 suppliers prioritize hazardous-material handling certifications for battery component flows.
Service Type:
Cost tier determines provider selection, with asset-heavy carriers commanding premium rates for dedicated capacity guarantees during production ramp-ups.
- Transportation:Fuel expenditure and driver scarcity dominate operational economics for road freight operators serving just-in-time assembly schedules. German OEM corridors around Stuttgart and Wolfsburg sustain dedicated high-frequency rail shuttles that compress inbound parts cycle times. Fleet composition shifts under EPA emissions enforcement, pressuring route optimization investments.
- Warehousing:Temperature-controlled storage protocols accommodate lithium-ion battery cells requiring thermal stability across seasonal variance. Polish and Czech distribution centers capture EV component flows into German assembly plants, leveraging lower facility costs. ECHA REACH compliance mandates digital substance passports for batch-level chemical tracking.
- Packaging:Modular kit bundling replaces discrete component shipments, reducing OEM line-side handling labor.
- Freight Forwarding:Ocean consolidation specialists manage Asia-Europe production parts flows through Rotterdam and Hamburg gateways.
Transportation leads on scale; warehousing leads on momentum.
Technology:
Application specificity drives adoption sequencing, with yard automation preceding full network visibility deployments due to concentrated ROI at distribution centers.
- Telematics:Real-time location and condition monitoring penetrates fastest among finished-vehicle carriers serving dealer networks across extended delivery routes. Road freight operators in North America and Germany deploy these systems to satisfy outcome-based contract penalties on delivery variance. EU AI Act algorithmic accountability rules will reshape predictive maintenance system architectures.
- RFID:Batch-level traceability supports REACH compliance documentation for automotive plastics and coatings crossing EU customs borders. Tagging density concentrates at Tier-1 supplier parks feeding Munich-area assembly plants. Battery manufacturers face steepest adaptation burden due to cathode material complexity.
- WMS:Warehouse management systems sequence parts deliveries to match OEM production cadence.
- TMS:Transport management platforms optimize multimodal routing across modal handoffs.
Telematics leads on scale; RFID leads on momentum.
End User:
Volume concentration shapes service design, with the largest contract structures originating from consolidated OEM procurement functions.
- OEMs:Lean manufacturing systems demand minimal inventory buffers, forcing logistics providers to absorb sequence-risk ownership through guaranteed-delivery contracts. German manufacturers cluster procurement under outcome-based frameworks that penalize variance rather than paying fixed transport rates. Stuttgart-Munich-Wolfsburg corridor density justifies dedicated supplier park infrastructure.
- Tier-1 Suppliers:Battery cell producers reconfigure warehouse footprints for hazardous-material storage protocols and thermal-controlled transport corridors. ADR-licensed operator scarcity constrains expansion pace for cathode-active-material shipments. Lithium hydroxide price volatility forces inventory carrying-cost absorption.
- Dealerships:Finished-vehicle distribution centers deploy autonomous yard tractors to reduce dwell time.
- Aftermarket Providers:Spare parts networks require flexible warehousing for slow-moving SKU proliferation.
OEMs lead on scale; Tier-1 Suppliers lead on momentum.
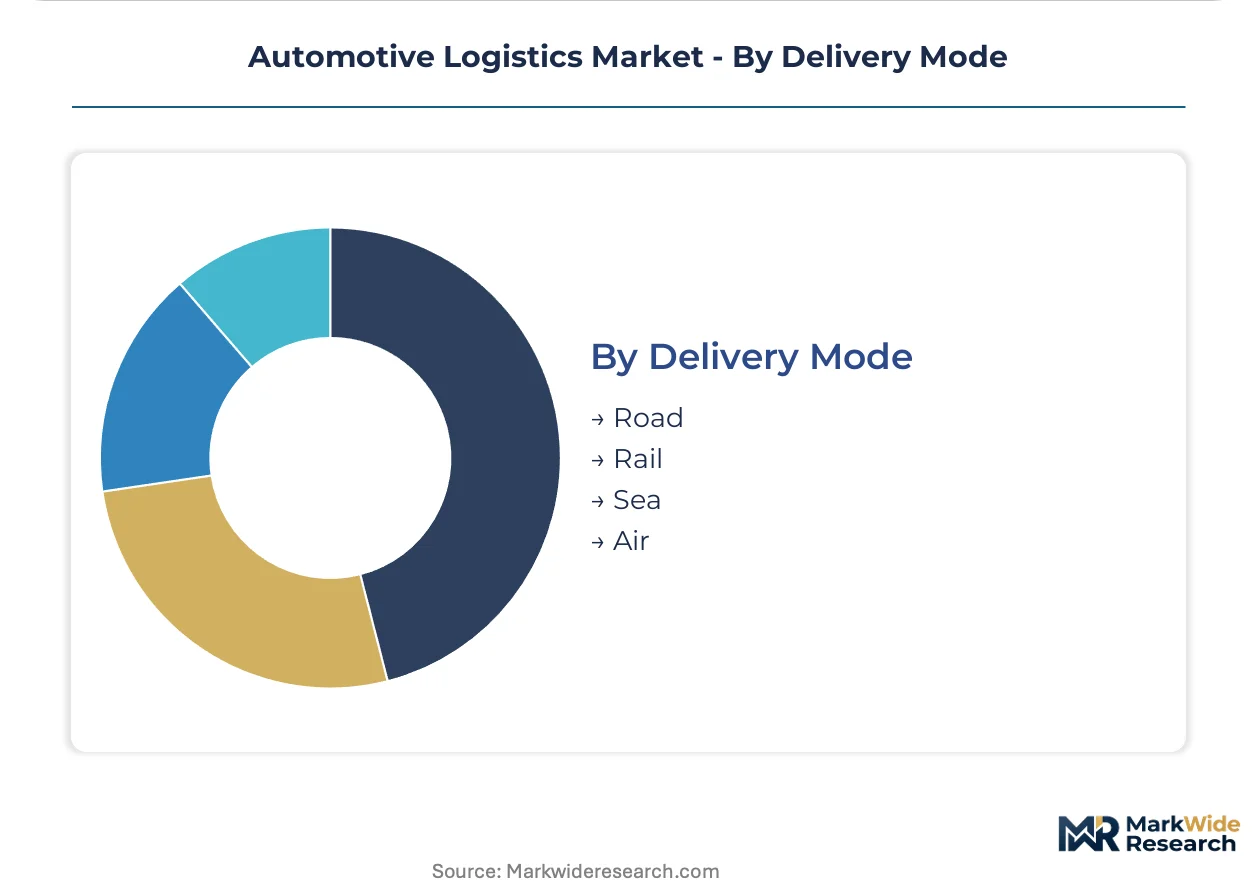
Delivery Mode:
Maturity gradients separate established infrastructure from emerging corridor investments, with rail and sea offering cost efficiency against air freight speed premiums.
- Road:Dominant modal share for just-in-time parts delivery within 300-kilometer radii of assembly plants, constrained by hazmat-certified driver training pipeline capacity. ADR licensing requirements for battery transport lag demand expansion across European EV production ramps. Telematics penetration accelerates fastest here.
- Rail:High-frequency shuttles from Central European supplier parks into German OEM clusters capture dense volume flows. Polish-Czech battery corridor development targets lower-cost warehousing integration with rail connectivity. Infrastructure investment concentrates on electrified corridors.
- Sea:Ocean freight consolidation manages Asia-Europe production parts movements.
- Air:Emergency shipment mode for semiconductor and critical path components.
Road leads on scale; rail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive logistics originated in the industrial corridors of Germany and the United States, where Ford's Highland Park assembly line and Volkswagen's Wolfsburg complex pioneered just-in-time material flows. These historical foundations established the geographic patterns still visible today.
United States
Domestic EV production ramps and reshoring mandates under the Inflation Reduction Act drive demand for battery transport infrastructure. The EPA enforces fleet emissions standards that reshape carrier route optimization investments. The Detroit-Toledo corridor anchors finished-vehicle distribution networks serving Midwest assembly plants.
Germany
OEM clustering around Stuttgart, Munich, and Wolfsburg generates dense just-in-time parts flows requiring precision sequencing. The EU Green Deal carbon-border adjustment mechanism pressures logistics providers to document embedded emissions across cross-border freight. Dedicated high-frequency rail shuttles connect supplier parks to assembly plants along the Neckar-Alb corridor.
China
Domestic EV platform proliferation and battery cell manufacturing expansion strain port capacity at Shanghai and Ningbo. The Ministry of Industry and Information Technology enforces dual carbon goals that accelerate electric truck adoption in fleet operations. The Yangtze River Delta logistics hub concentrates automotive parts consolidation for both domestic assembly and export markets.
Japan
Hybrid powertrain component exports and semiconductor equipment logistics sustain specialized air freight demand. METI industrial policy supports automated port infrastructure investments at Yokohama and Nagoya. The Toyota City supplier ecosystem maintains proprietary milk-run collection networks that compress inbound material cycle times.
India
PLI scheme incentives for EV manufacturing attract logistics providers to Tamil Nadu and Gujarat industrial corridors. The Automotive Research Association of India certifies battery safety standards that govern hazmat transport protocols. The Delhi-Mumbai Industrial Corridor hosts emerging supplier parks requiring multimodal connectivity investments.
Automotive Logistics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across service specialization depth, with asset-heavy carriers commanding dedicated capacity premiums while technology-enabled brokers capture spot-market efficiency gains. The vendor base organizes into three tiers: integrated global networks, regional specialists with hazardous-material certifications, and digital freight platforms. Consolidation pressures favor scale advantages in ocean freight consolidation and battery transport compliance. Dominant competitive moves include M&A to acquire ADR-certified fleet capacity and strategic partnerships to build vehicle-to-grid infrastructure at distribution yards.
Among integrated global networks, DHL International GmbH and Kuehne + Nagel occupy positions exemplifying the asset-light forwarding archetype with deep ocean consolidation expertise, while XPO Logistics represents the North American dedicated transport specialist model. These three entities anchor the competitive structure across distinct geographic and service vectors.
| Leading Market Players |
|---|
| DHL International GmbH |
| XPO Logistics |
| Kuehne + Nagel |
| CEVA Logistics |
| DSV |
| DB Schenker |
| Ryder System |
| Expeditors International |
| Deutsche Post AG |
| Others |
Supply Flow & Price Mechanics
Captive warehousing integration by German OEMs anchors both supply positioning and pricing power, compressing third-party margins while concentrating volume leverage in the Stuttgart-Munich-Wolfsburg corridor. This vertical control over inbound sequencing forces logistics providers to absorb inventory risk through outcome-based contracts that penalize delivery variance rather than reward fixed-rate reliability.
Pricing Analysis
Outcome-based contract structures with penalty clauses for sequence disruption dominate procurement frameworks, replacing traditional rate-card agreements. Price differentiation hinges on ADR hazmat certification tier and real-time visibility infrastructure maturity. Cost compression intensifies in standard freight tiers as digital freight platforms compress spot-market spreads through algorithmic matching. Tier-1 battery suppliers exhibit highest price sensitivity due to lithium hydroxide margin volatility, while OEM procurement functions prioritize guaranteed-sequence premiums over unit cost minimization.
Supply Chain Analysis
ADR-certified operator scarcity gates capacity expansion across European battery corridors, constraining Tier-1 supplier network growth. Manufacturing concentration clusters in Germany, China, and Mexico for powertrain components, with cathode-active-material supply drawing from South Korea and China. Single-source dependency on Taiwan semiconductor foundries creates vulnerability to Taiwan Strait shipping disruptions. Distribution runs through multimodal hubs at Rotterdam and Hamburg for Asia-Europe production parts consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive logistics has entered a late-cycle quality phase where premium specifications around battery transport compliance and algorithmic auditability command sustained margin premiums. Demand is concentrating toward providers with embedded emissions documentation capabilities under EU Green Deal enforcement.
For Market Incumbents: Lock in ADR-certified fleet capacity through long-term operator training pipelines before hazmat driver scarcity intensifies. Acquire Polish-Czech distribution assets to capture Central European battery corridor flows. Consolidate around explainable routing systems that satisfy EU AI Act algorithmic accountability requirements for automated freight allocation.
For New Entrants and Emerging Players: The premium-economy price-point gap in aftermarket spare parts logistics offers white-space entry with lower certification barriers than OEM-facing battery transport. Target Indian PLI scheme corridors around Tamil Nadu and Gujarat for EV manufacturing logistics buildout. Lead with vehicle-to-grid integration services at distribution yards as a differentiated value-capture mechanism.
For Investors and Strategic Acquirers: Roll-up economics work for regional ADR-certified specialists because carrier fragmentation and compliance cost escalation favor scaled platforms with training infrastructure. The five-to-ten year viability window favors asset-light forwarding networks with deep ocean consolidation expertise over pure-play road operators. Watch lithium hydroxide price volatility as the inflection signal for inventory carrying-cost pressure on logistics provider margins.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cathode-active-material flows from South Korean producers under long-term offtake terms. |
| Software-Defined Vehicle Investment | Enables telematics integration for real-time condition monitoring across dealer distribution networks. |
| Geographic Manufacturing Footprint | Relocates final assembly to EU member states minimizing embedded-emissions tariffs under carbon-border adjustments. |
| Charging Infrastructure Partnership | Deploys bidirectional vehicle-to-grid systems at distribution yards capturing grid services revenue. |
| Platform Standardization | Compresses legacy powertrain logistics complexity while expanding battery supply chain coordination requirements. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and ADR-certified carrier operations managers with secondary validation against customs trade data, vehicle production databases, IHS Markit registration data, and SEC filings from listed logistics providers. Bottom-up service line estimates and top-down market sizing triangulated to converge on segment-level figures.
Historical reference periods anchored the projection horizon through regression analysis of transport expenditure against vehicle production volumes across the analysis window. Segmentation dimensions modeled include service type, technology adoption tier, end-user category, and delivery mode, with propulsion architecture and regional production cluster as automotive-specific stratifiers. CAGRs derived from curve-fitting observed growth patterns against macroeconomic drivers, incorporating battery cell manufacturing capacity expansion and EU regulatory compliance cost trajectories as industry-specific inputs.
Caveats apply where lithium hydroxide price spikes, Taiwan Strait shipping disruptions, or REACH substance authorization delays could materially shift the outlook. Deviation in ADR-certified driver training pipeline capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Germany Freight Forwarding Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market