
 Logistics Automation Market | 2026-2036
Logistics Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Logistics Automation Market Analysis
Software-defined fleet orchestration is broadening what logistics automation vendors monetize beyond hardware sales. Godrej Körber leverages its Indian manufacturing footprint to anchor regional project delivery for multi-client distribution centers. Vanderlande Industries B.V competes on large-scale baggage and parcel handling integration, while Blue Yonder differentiates through cloud-native supply chain planning that feeds execution-layer automation.
Logistics automation encompasses the hardware, control software, and system integration that mechanize material flow, inventory handling, and order dispatch across supply chain nodes, typically operating through programmable logic controllers, machine vision guidance, and real-time warehouse management system protocols with throughput rates measured in units per hour. The technology dimension spans warehouse robotics, autonomous vehicles, automated guided vehicles, and drones, with warehouse robotics currently occupying the largest installed base while autonomous vehicles represent the fastest-expanding category as last-mile and yard operations electrify. On-premise deployment still dominates legacy facility retrofits, though cloud-based and edge computing architectures are gaining share among greenfield e-commerce and healthcare distribution builds where IT-OT convergence demands lower latency.
The EU Green Deal and F-Gas Regulation shape equipment electrification and refrigerant choices in cold-chain automation, while Germany's KBA and REACH compliance through ECHA influence autonomous vehicle safety certification and battery material sourcing across European deployments. India's BIS standards and PLI scheme for manufacturing are accelerating domestic production of automated guided vehicles and warehouse robotics for local and export markets. Stakeholders must weigh regulatory timelines for carbon reporting and autonomous system certification against capital replacement cycles when committing to multi-year automation roadmaps.
Market Dynamics
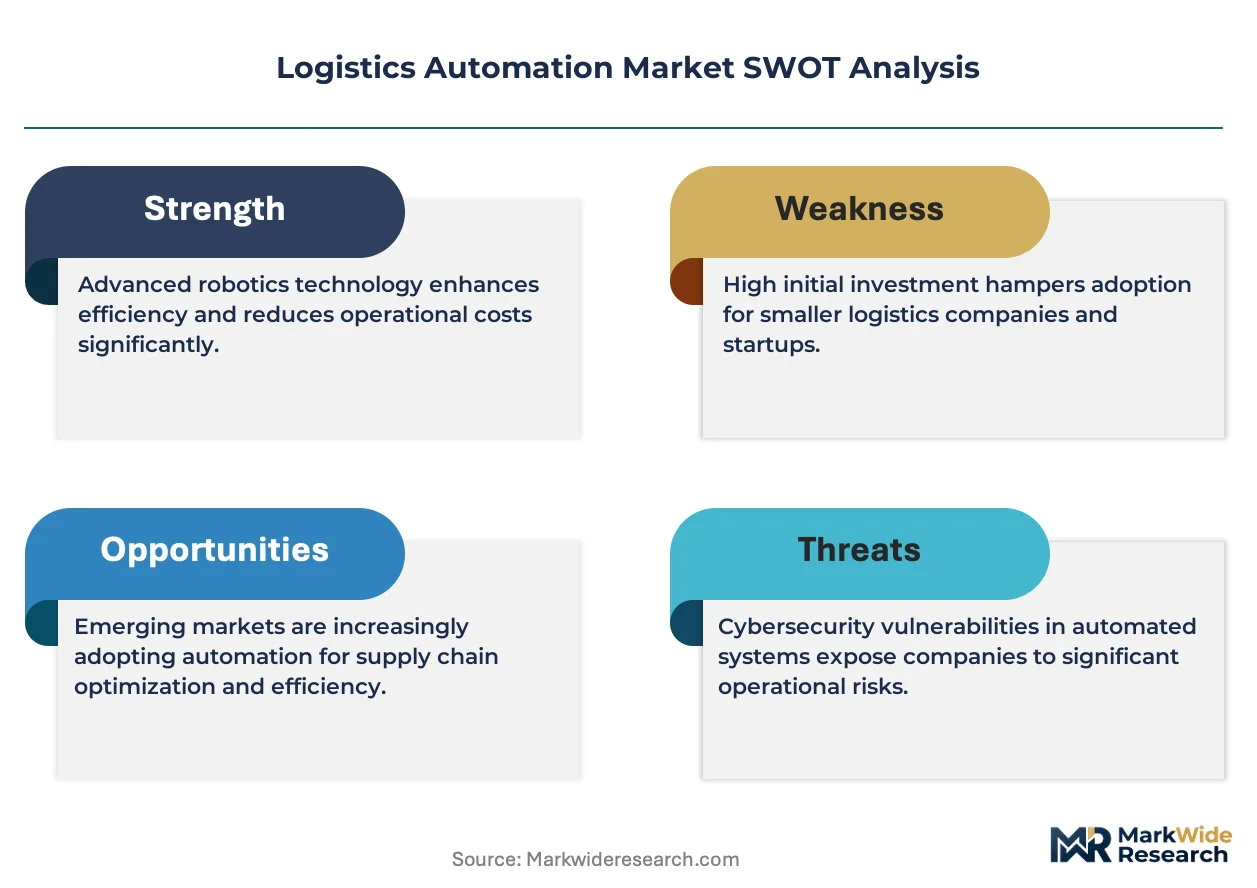
Software-defined orchestration is collapsing the traditional hardware-software boundary in logistics automation, forcing vendors to restructure revenue models around recurring platform fees rather than capital equipment sales. This shift compresses customer switching costs while accelerating replacement cycles for legacy fixed automation.
Growth Catalysts
- EU Green Deal carbon accounting mandates:Warehouse operators in Germany and the Netherlands face mandatory scope emissions reporting, accelerating fleet electrification and automated energy management retrofits.
- Same-day delivery commitments:E-commerce fulfillment networks are deploying robotic sortation and autonomous mobile robots to meet speed guarantees without proportional labor expansion.
- Pharmaceutical cold-chain integrity requirements:Temperature-sensitive distribution hubs are automating storage and retrieval to minimize human touchpoints and thermal excursions.
Market Restraints
- Lithium-ion battery supply concentration:Cell production for autonomous vehicle fleets clusters in East Asian suppliers, exposing European and North American operators to price volatility and qualification delays.
- REACH compliance costs for battery materials:ECHA substance restrictions on cobalt and nickel compounds raise material qualification expenses for warehouse robotics manufacturers serving EU markets.
- Legacy PLC architecture incompatibility:Brownfield facilities running proprietary control systems face integration friction with modern cloud-native fleet management platforms.
Strategic Opportunities
- India PLI scheme for manufacturing automation:Domestic production incentives are enabling local assembly of automated guided vehicles for export to Southeast Asian and Middle Eastern distribution markets.
- Healthcare micro-fulfillment:Hospital and pharmacy networks are deploying compact automated storage systems for unit-dose medication dispensing and surgical kit preparation.
- Machine vision and edge AI convergence:Real-time object recognition paired with localized processing is enabling dynamic path planning for autonomous mobile robots in unstructured yard environments.
Industry Challenges
- Mechatronics technician scarcity:Maintenance organizations struggle to recruit personnel fluent in both mechanical systems and PLC programming for automated storage and retrieval equipment.
- Multi-vendor integration complexity:Facilities mixing hardware from different OEMs face protocol mismatches between proprietary warehouse management systems and third-party fleet orchestration software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logistics Automation Market |
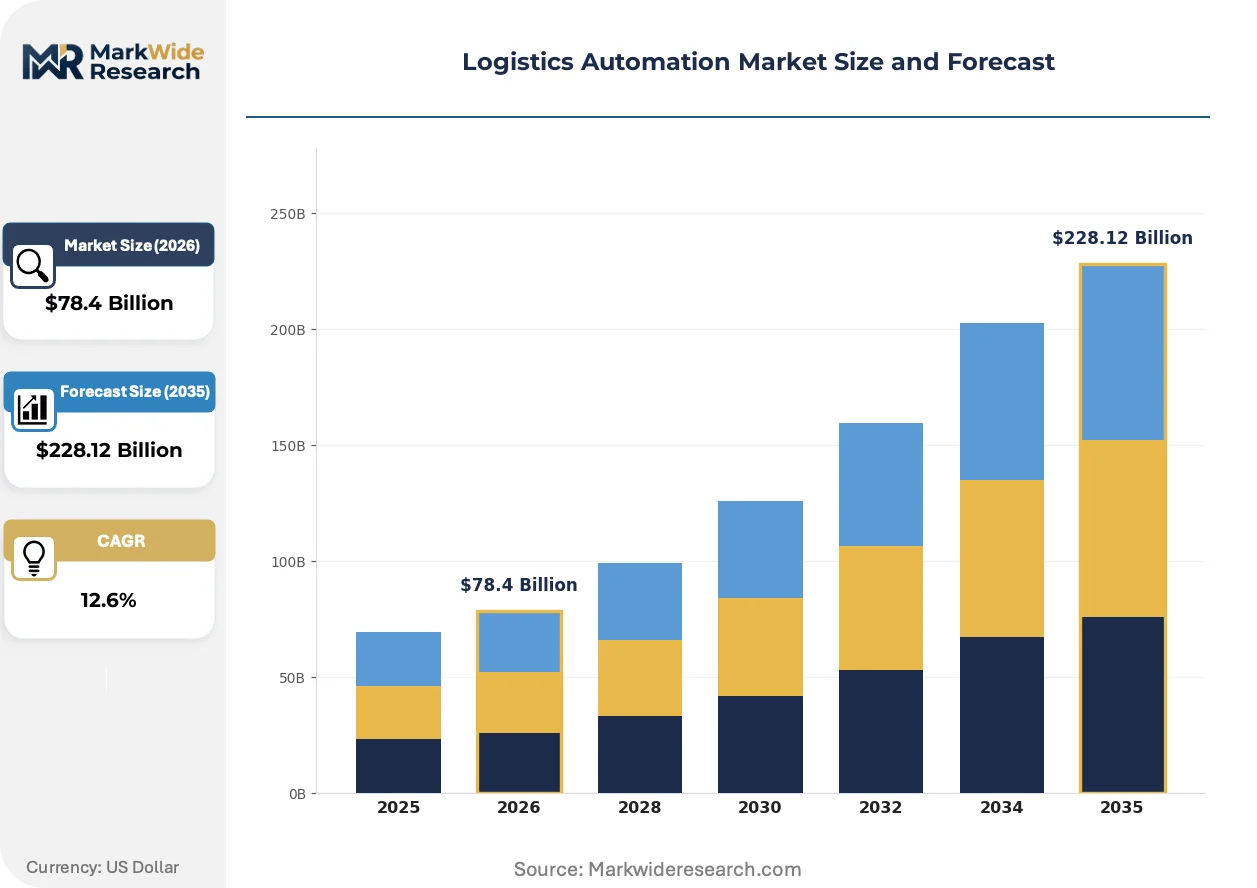
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $228.12 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Warehouse Robotics, Autonomous Vehicles, Automated Guided Vehicles, Drones End User: Retail, Manufacturing, E-Commerce, Healthcare Solution: Inventory Management, Freight Tracking, Order Fulfillment, Fleet Management Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Godrej Körber, Armstrong, Daifuku Intralogistics India, Alstrut India, Alligator Automations, Vanderlande Industries B.V, Clearpack India, Blue Yonder, Kardex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Logistics Automation Market Emerging Trajectories
Edge computing architectures are displacing centralized cloud dependency for latency-critical automation decisions, while regulatory pressure on embodied carbon reshapes equipment procurement criteria across European distribution networks.
Autonomous mobile robots equipped with onboard SLAM navigation and local path computation are decentralizing fleet control away from centralized warehouse management systems. Pharmaceutical and grocery distribution centers are deploying these units fastest, often retrofitting existing facilities without fixed infrastructure modifications. This architecture is decentralizing operational decision-making to individual units, reducing single points of failure while complicating vendor support models.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in automated cold storage, forcing equipment redesign around CO2 transcritical systems and ammonia-based alternatives. Cold-chain automation vendors serving European markets must requalify thermal equipment portfolios under tightened leakage thresholds and service ban timelines. German and Dutch operators are responding fastest, driven by national carbon pricing mechanisms that penalize high-GWP refrigerant use.
Capital expenditure fatigue among mid-market third-party logistics providers is accelerating equipment-as-a-service contracting for warehouse robotics. Traditional outright purchase models are yielding to per-pick or uptime-guarantee arrangements that transfer obsolescence risk to vendors. This shift is most pronounced in North American e-commerce fulfillment, where balance-sheet constraints and technology refresh uncertainty favor operational expenditure treatment.
Logistics Automation Market Segmentation
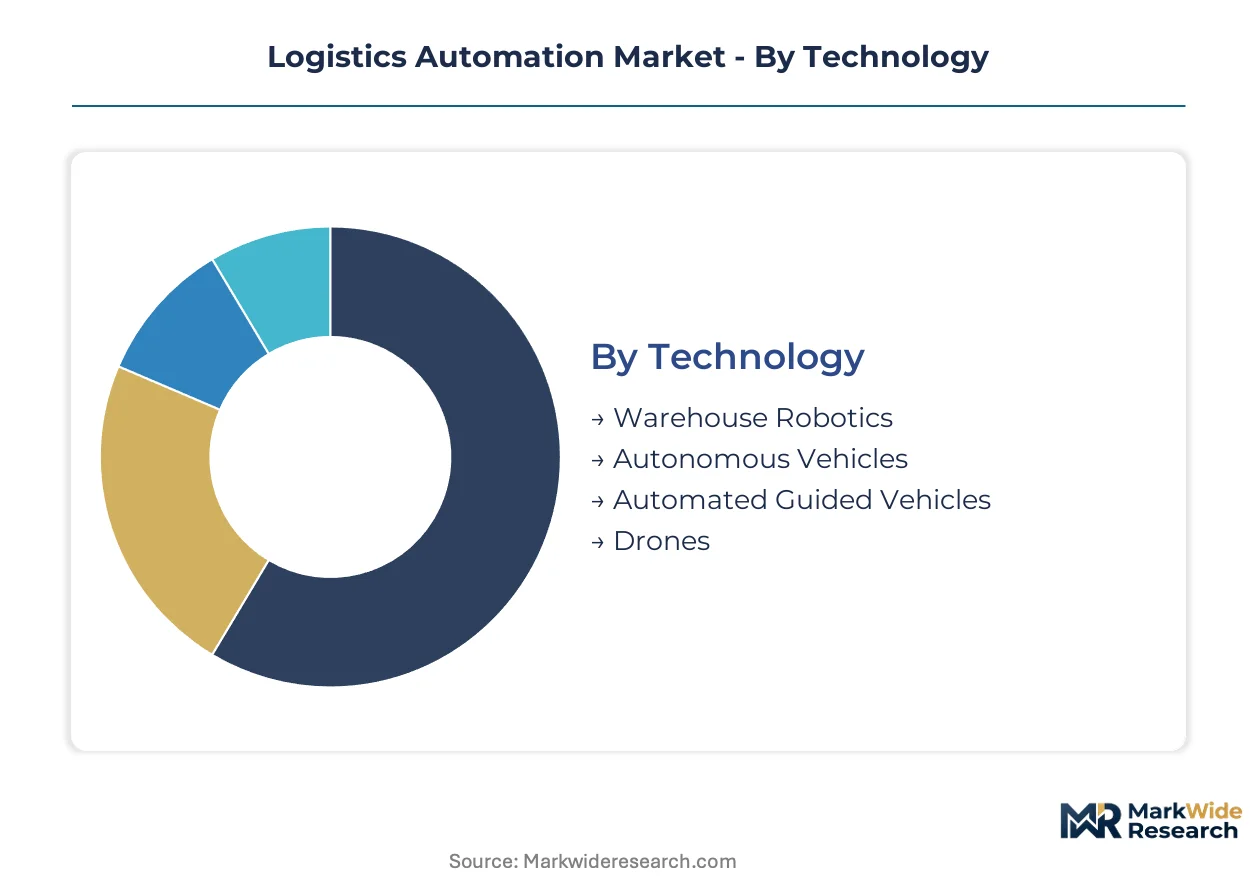
Technology heterogeneity in logistics automation creates distinct investment profiles across hardware categories, deployment architectures, and end-use applications. Procurement patterns diverge sharply between asset-heavy warehouse robotics and software-centric fleet orchestration platforms.
Technology:
Hardware specifications define integration complexity and maintenance protocols across automation modalities.
- Warehouse Robotics:Fixed and mobile robotic systems handle pick-and-place, palletizing, and sortation through articulated arms and gantry configurations. German automotive distribution hubs and Dutch e-commerce fulfillment centers are retrofitting legacy facilities with these systems to meet EU Green Deal carbon reporting requirements. Installed base concentration reflects maturity in repetitive handling tasks.
- Autonomous Vehicles:Self-driving yard trucks and last-mile delivery pods navigate unstructured environments through lidar and camera fusion. Battery-electric platforms are expanding fastest in German and US logistics networks as operators electrify material handling fleets under tightening emissions mandates. Cell supply concentration in East Asian suppliers creates procurement risk.
- Automated Guided Vehicles:Wire-guided and magnetic-tape-follower systems transport pallets along fixed routes in manufacturing and distribution facilities. India's PLI scheme for manufacturing automation is accelerating domestic assembly for export to Southeast Asian markets.
- Drones:Aerial inventory scanning and last-mile delivery units operate in controlled airspace with FAA, EASA, or national aviation authority certification. Regulatory fragmentation constrains cross-border deployment standardization.
Warehouse robotics leads on scale; autonomous vehicles lead on momentum.
End User:
Operational requirements and regulatory exposure vary substantially across customer verticals.
- Retail:Seasonal demand volatility drives interest in flexible automation that scales with promotional cycles. European fashion and grocery retailers are deploying robotic sortation to meet same-day delivery commitments without proportional labor expansion.
- Manufacturing:Just-in-time component delivery and work-in-process tracking integrate automated guided vehicles with enterprise resource planning systems. German automotive plants represent concentrated demand for synchronized material flow.
- E-Commerce:Order profile fragmentation and speed guarantees push fulfillment networks toward autonomous mobile robots and goods-to-person systems. North American operators favor equipment-as-a-service contracting to manage technology refresh risk.
- Healthcare:Temperature-sensitive distribution and unit-dose accuracy requirements automate storage and retrieval to minimize human touchpoints. Pharmaceutical cold-chain integrity mandates from FDA and EMA drive capital allocation.
E-commerce leads on scale; healthcare leads on momentum.
Solution:
Functional modules address distinct pain points across the order-to-delivery value chain.
- Inventory Management:Real-time location tracking and cycle counting through RFID, vision systems, and sensor fusion. Retail and healthcare operators prioritize accuracy over speed given shrinkage and compliance exposure.
- Freight Tracking:In-transit visibility platforms aggregate carrier data and IoT sensor feeds for exception management. Cross-border regulatory documentation integration varies by trade corridor.
- Order Fulfillment:Wave planning, pick path optimization, and packing automation coordinate human and robotic labor. E-commerce peak season throughput requirements strain legacy warehouse management system architectures.
- Fleet Management:Multi-vendor robot orchestration and predictive maintenance scheduling consolidate control across heterogeneous hardware. Cloud-native platforms are gaining share among greenfield builds where IT-OT convergence demands lower latency.
Order fulfillment leads on scale; fleet management leads on momentum.
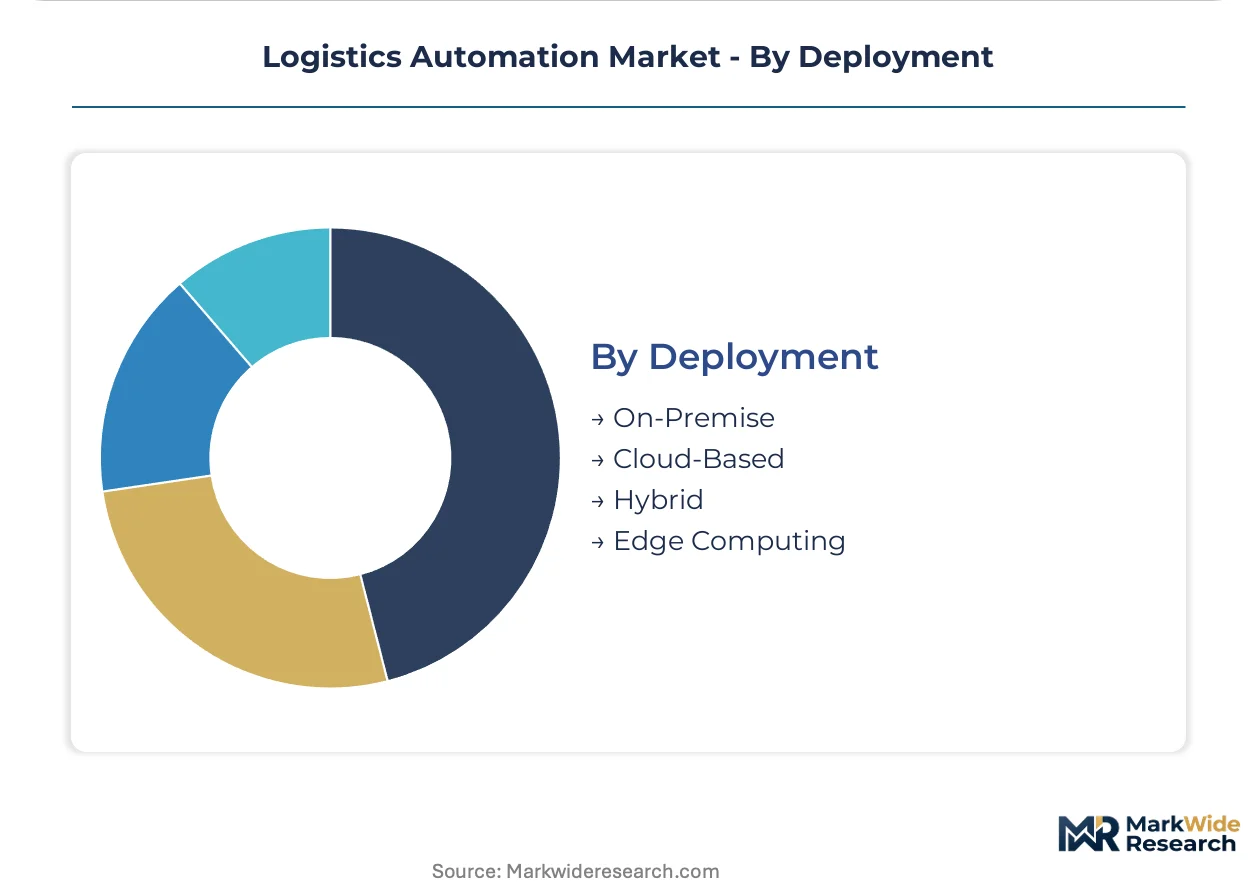
Deployment:
Infrastructure architecture choices reflect facility vintage, data sovereignty requirements, and latency tolerance.
- On-Premise:Legacy programmable logic controller architectures and localized data storage dominate brownfield retrofits. Proprietary control systems create integration friction with modern cloud-native fleet management platforms.
- Cloud-Based:Centralized compute and software-as-a-service delivery enable rapid scaling and vendor-managed updates. Healthcare and financial services operators face data residency constraints under GDPR and national privacy regulations.
- Hybrid:Split processing between edge devices and cloud analytics balances real-time responsiveness with advanced analytics. Pharmaceutical distribution centers favor this model for cold-chain monitoring with centralized compliance reporting.
- Edge Computing:Localized processing on robot-mounted controllers or facility gateways reduces dependence on wide-area network reliability. SLAM navigation and real-time path planning for autonomous mobile robots in unstructured yard environments depend on this architecture.
On-premise leads on scale; edge computing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in warehouse robotics deployment density, while India narrows the automation gap through domestic manufacturing incentives. National regulatory frameworks and industrial cluster specialization shape divergent investment trajectories across major economies.
Germany
Automotive distribution hubs in Stuttgart and Wolfsburg drive automated storage and retrieval retrofits, with pharmaceutical cold-chain facilities in Frankfurt expanding robotic handling capacity. The KBA enforces autonomous vehicle safety certification standards that influence battery material sourcing across European deployments. Bavaria's Ingolstadt logistics corridor hosts concentrated ASRS installations serving just-in-time automotive component flows.
United States
E-commerce fulfillment networks in California and Texas deploy autonomous mobile robots to meet same-day delivery commitments without proportional labor expansion. The FAA regulates aerial inventory scanning and last-mile drone delivery certification, constraining cross-state operational standardization. The Pacific Northwest corridor concentrates warehouse robotics R&D facilities alongside major cloud-native fleet management platform development.
India
Multi-client distribution centers in Maharashtra and Gujarat accelerate automated guided vehicle adoption for regional project delivery. The BIS standards and PLI scheme for manufacturing automation incentivize domestic AGV assembly for Southeast Asian and Middle Eastern export markets. Karnataka's Bangalore-Tumkur industrial belt anchors warehouse robotics production serving pharmaceutical and automotive verticals.
Netherlands
Rotterdam port logistics operators electrify material handling fleets under EU Green Deal carbon accounting mandates, with greenhouse gas reporting requirements accelerating automated energy management retrofits. The national carbon pricing mechanism penalizes high-GWP refrigerant use in cold-chain automation. Eindhoven's Brainport region concentrates edge computing architecture development for pharmaceutical distribution applications.
Japan
Manufacturing plants in Aichi Prefecture integrate automated guided vehicles with enterprise resource planning systems for synchronized just-in-time component delivery. METI influences industrial automation standards adoption across automotive and electronics distribution networks. The Chubu-Nagoya logistics corridor hosts concentrated deployments of fixed-route pallet transport systems serving tier-one supplier hubs.
Logistics Automation Market Vendor Landscape
Top-tier vendors anchor large-scale system integration contracts, while mid-tier specialists compete on regional project delivery and vertical-specific module customization. The vendor base stratifies across hardware fabricators, control software developers, and full-stack integrators with divergent margin profiles. Three archetypes dominate: diversified industrial conglomerates with captive automation divisions, pure-play warehouse robotics manufacturers, and cloud-native supply chain planning platforms feeding execution-layer systems. Competitive moves center on equipment-as-a-service contracting transitions and edge AI capability acquisitions.
Within the diversified industrial tier, Godrej Körber leverages its Indian manufacturing footprint to anchor regional distribution center deployments. Vanderlande Industries B.V occupies a position exemplifying large-scale baggage and parcel handling integration specialization. Blue Yonder represents the cloud-native planning-to-execution convergence archetype, with its platform architecture influencing how fleet orchestration software monetizes beyond hardware sales. These three entities illustrate distinct competitive vectors: geographic manufacturing advantage, vertical integration depth, and software-defined revenue model transformation.
| Leading Market Players |
|---|
| Godrej Körber |
| Armstrong |
| Daifuku Intralogistics India |
| Alstrut India |
| Alligator Automations |
| Vanderlande Industries B.V |
| Clearpack India |
| Blue Yonder |
| Kardex |
| Others |
Supply Flow & Price Mechanics
Software-defined orchestration platforms are collapsing hardware-software boundaries while simultaneously compressing supplier margins and fragmenting procurement authority across fleet management buyers. This dual transformation concentrates pricing power among cloud-native platform vendors even as lithium-ion cell supply tightens under East Asian production dominance.
Pricing Analysis
Capacity additions in India under the PLI scheme are reshaping price floors for automated guided vehicles and warehouse robotics serving Southeast Asian export markets. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European systems from BIS-certified Indian assembly and unbranded Chinese components. Cost compression in mid-tier warehouse robotics is intensifying because cloud-native fleet management vendors bundle hardware at negative margins to capture recurring SaaS revenue. Third-party logistics providers exhibit highest price sensitivity due to balance-sheet constraints, while pharmaceutical cold-chain operators prioritize certification tier over unit cost.
Supply Chain Analysis
CE marking and KBA safety certification gate European market access for autonomous vehicle battery packs and control systems, lengthening supplier qualification timelines. Manufacturing concentrates in China for lithium-ion cells, Germany for precision mechatronics, and India for PLI-incentivized AGV assembly. Raw material dependencies span cobalt and nickel compounds restricted under REACH, rare earth magnets for servo motors, and high-grade steel for fixed automation structures. Single-source vulnerability runs through East Asian cell suppliers exposed to export control volatility. Distribution runs through system integrators who bundle multi-vendor hardware with proprietary control software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's mandatory scope emissions reporting functions as a regulatory compounder, forcing warehouse operators into accelerated automation refresh cycles regardless of underlying demand cyclicality.
For Market Incumbents: Anchor defensive positioning through captive battery material sourcing and in-house production of edge computing controllers to offset REACH compliance cost inflation. Consolidate around equipment-as-a-service contracting to lock in multi-year revenue streams before cloud-native entrants capture fleet management relationships. Vertical integration into Indian manufacturing under PLI terms preserves margin against Chinese hardware commoditization. For New Entrants and Emerging Players: Cloud-native sales channels targeting mid-market third-party logistics providers offer the most penetrable entry vector given incumbent neglect of operational expenditure contracting models. Focus initial deployment on pharmaceutical micro-fulfillment applications where temperature integrity requirements justify premium pricing and longer sales cycles deter established hardware vendors. Pursue white-label fleet orchestration partnerships with Indian AGV assemblers seeking software differentiation for Middle Eastern export markets. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play warehouse robotics manufacturers facing hardware margin compression without recurring revenue offsets. Long-term viability across the projection horizon rests on successful SaaS transition or strategic acquisition by industrial conglomerates seeking automation platform capabilities. Monitor equipment-as-a-service contract penetration rates as the inflection signal distinguishing sustainable platform economics from legacy hardware dependence.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Transition | Transfers obsolescence risk to vendors while capturing recurring revenue from e-commerce fulfillment networks. |
| Edge AI Capability Acquisition | Enables real-time path planning for autonomous mobile robots in unstructured yard environments. |
| Backward Integration into Battery Supply | Reduces exposure to East Asian cell concentration and REACH compliance cost volatility. |
| Healthcare Micro-Fulfillment Partnership | Captures pharmaceutical cold-chain automation demand driven by FDA and EMA integrity mandates. |
| PLI-Anchored Indian Manufacturing Scale-Up | Positions domestic AGV assembly for Southeast Asian and Middle Eastern distribution market exports. |
Methodological Framework
Multiple input streams — primary interviews with warehouse operations directors, fleet management platform engineers, and mechatronics procurement leads; secondary validation through customs trade data, SEC equipment vendor filings, and EU ETS carbon registry disclosures — were reconciled through bottom-up installation tracking and top-down market sizing triangulation.
Segment-level demand was modeled across technology modality, deployment architecture, and end-use vertical throughout the forecast period, with CAGRs derived from logistic curve penetration assumptions and replacement cycle analysis. Forecast inputs incorporated EU Green Deal compliance timeline acceleration, lithium-ion cell supply concentration risk, and cloud-native platform adoption elasticity among greenfield versus brownfield facilities.
Regulatory enforcement delays, battery material price spikes, and autonomous vehicle safety certification backlogs are the dominant revision risks to modeled deployment trajectories. A model refresh is warranted upon material change in EU carbon pricing mechanism stringency or PLI scheme renewal terms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
ASEAN Domestic Courier Market
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
Latin America Cold Chain Logistics Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
North America Refrigerated Container Shipping Market
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
Cargo Shipping Market
Logistics and Shipping
South Africa Air Freight Market