
 Egypt Freight and Logistics Market | 2026-2036
Egypt Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Freight and Logistics Market Foresight
Market Context with Strategic Players
Composite container flooring is hardening as a replacement for traditional hardwood surfaces in reefer and dry-van units serving Egyptian pharmaceutical exports. CMA CGM Group leverages its Alexandria terminal presence to control transshipment flows across the Eastern Mediterranean. DHL Group anchors pharmaceutical cold chain operations through certified GDP facilities in Cairo and 10th of Ramadan City. MISR Logistics competes on domestic last-mile density, operating a fleet exceeding 1,200 vehicles concentrated in the Nile Delta manufacturing corridor.
Technical Definition and Structural Segments
Egypt Freight and Logistics encompasses the integrated planning, execution, and control of goods movement across road, rail, maritime, and air modalities, with cold chain maintaining 2-8°C for pharmaceutical shipments and bonded warehousing requiring 72-hour customs clearance windows under Egyptian customs protocols. The sector's primary commercial purpose is reducing inventory carrying costs for importers while enabling just-in-sequence delivery to manufacturing zones. Transportation services dominate value capture given Suez Canal transit volumes and Alexandria-Dekheila port throughput, while Freight Forwarding segments attract margin premiums from pharmaceutical and automotive clients requiring documentation precision. Last Mile delivery models are expanding fastest as e-commerce order frequency rises in Greater Cairo and Alexandria, though Port-to-Port movements retain volume leadership through containerized agricultural and petrochemical exports.
Regulatory Frame and Forward-Looking Close
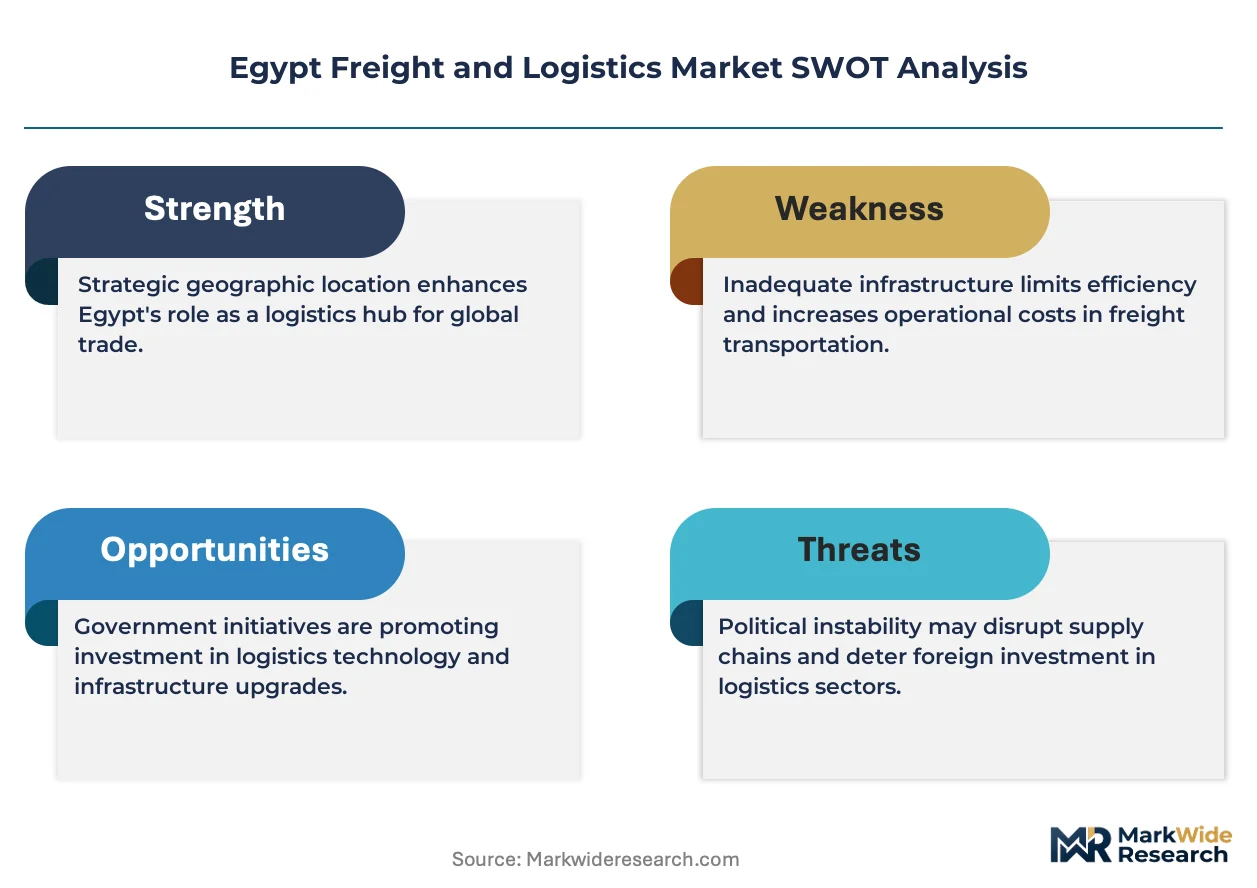
The General Authority for Supply Commodities, Egyptian Customs Authority, and Maritime Transport Sector regulations govern market access, with GDP certification from the national pharmaceutical regulator mandating temperature validation for drug distribution. These frameworks elevate compliance costs for unauthorized warehouse operators while creating accredited capacity shortages in Alexandria and Port Said. Stakeholders must monitor Suez Canal tariff adjustments and customs digitization timelines to calibrate bonded space investments against evolving clearance velocity requirements.
Market Dynamics
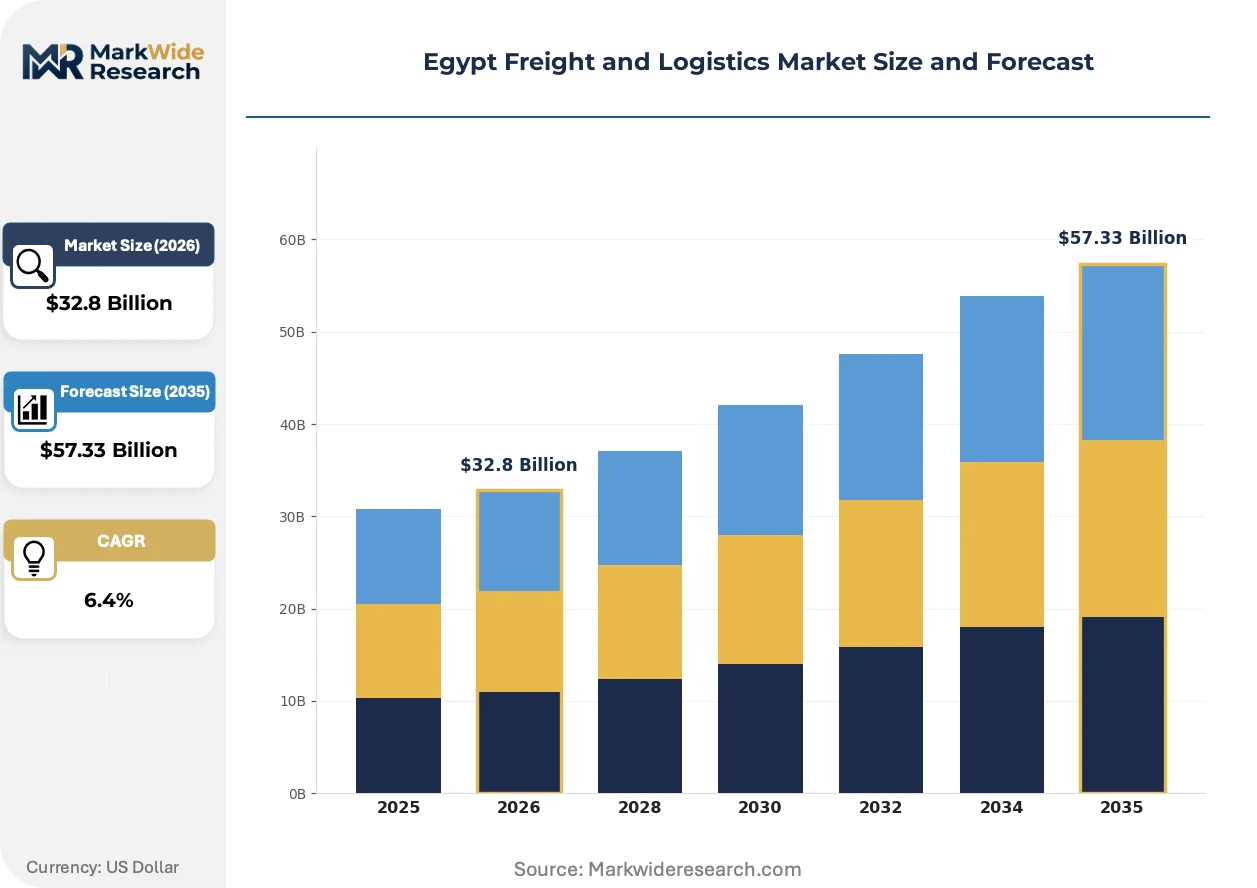
Egypt's freight sector is compressing clearance timelines as customs digitization and bonded warehouse expansion reshape competitive positioning between Alexandria and Port Said logistics clusters.
Growth Catalysts
- Suez Canal tariff recalibration:Transit fee adjustments are drawing re-export volume away from competing Mediterranean hubs into Egyptian bonded zones.
- Pharmaceutical cold chain infrastructure:Temperature-sensitive drug imports from European manufacturers are demanding GDP-certified storage capacity in Cairo and 10th of Ramadan City.
- E-commerce order frequency:Greater Cairo's rising digital retail transaction density is pulling last-mile delivery network expansion into the Nile Delta manufacturing corridor.
Market Restraints
- Fuel cost volatility:Diesel price fluctuations directly compress road freight margins for domestic fleet operators serving Alexandria-Dekheila port corridors.
- Accredited warehouse scarcity:GDP-certified cold storage capacity concentrates in Cairo, creating bottlenecks for pharmaceutical distributors requiring Alexandria or Port Said access.
- Hardwood flooring substitution:Composite container flooring is displacing traditional timber surfaces in reefer units, forcing equipment retrofit cycles on existing domestic fleets.
Strategic Opportunities
- Suez Canal Economic Zone bonded expansion:Underpenetrated re-export processing capacity in Port Said East offers white space for transshipment logistics operators.
- Customs digitization timelines:Egyptian Customs Authority clearance automation mandates are creating first-mover advantages for integrated platform providers.
- Reefer-automation convergence:IoT temperature monitoring fused with automated warehouse management is opening precision cold chain service tiers for vaccine distributors.
Industry Challenges
- GDP certification timelines:Pharmaceutical warehouse accreditation delays from the national pharmaceutical regulator are extending facility commissioning cycles beyond 18 months.
- Legacy fleet integration:Telematics deployment across 1,200-plus vehicle domestic fleets requires capital intensity that mid-tier operators struggle to absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Freight and Logistics Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage Delivery Model: Door-to-Door, Port-to-Port, Intermodal, Last Mile End User: Retail, Manufacturing, Automotive, Pharmaceuticals Technology: GPS Tracking, Warehouse Management Systems, IoT Solutions, Blockchain Logistics |
| Companies Covered | CMA CGM Group, DB Schenker, DHL Group, MISR Logistics, Kadmar Group, DSV A/S, DP World, Damietta Container & Cargo Handling Co, Kuehne + Nagel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Freight and Logistics Market Shifts & Advancements
Digital integration is compressing documentation cycles while regulatory mandates and buyer behavior shifts restructure service tier definitions across Egyptian logistics corridors.
Blockchain-enabled documentation platforms are unifying customs declaration, bill of lading, and insurance verification into single-source data architectures. Pharmaceutical exporters and automotive parts distributors are adopting these systems fastest to satisfy Egyptian Customs Authority digitization requirements. This unifying infrastructure is eliminating redundant paper-based checkpoints at Alexandria and Port Said entry points.
Egyptian Customs Authority modernization protocols are mandating pre-arrival declaration submission and risk-based inspection algorithms. Industrial consequence includes accelerated clearance velocity for compliant importers and extended detention exposure for documentation-deficient shipments. Pharmaceutical and automotive verticals are responding by integrating freight forwarders directly into enterprise ERP systems.
Just-in-sequence delivery contracting is replacing traditional inventory-holding arrangements for Nile Delta manufacturing clients. Tier-one automotive assemblers and electronics contract manufacturers are pushing liability upstream to logistics providers, who must now guarantee delivery windows rather than merely transit times. This compression is most visible in 10th of Ramadan City industrial zones where component sequencing errors halt production lines.
Egypt Freight and Logistics Market Segmentation
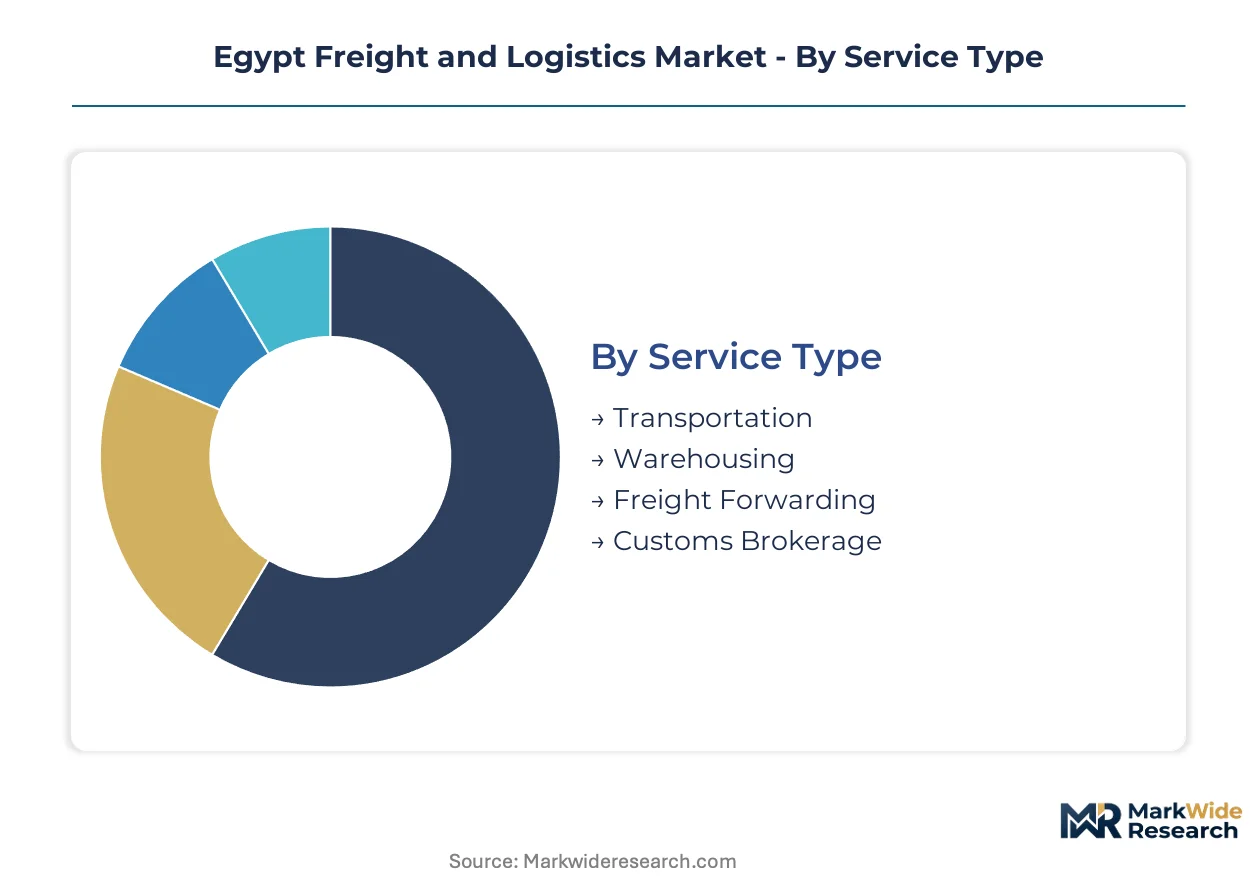
Egypt's freight and logistics market fragments across service modalities, delivery architectures, and technology layers that determine margin capture. Procurement patterns in Alexandria and Cairo industrial zones favor integrated providers spanning multiple segments rather than point solutions.
Service Type:
Cost tier determines buyer selection, with large importers consolidating spend under full-service contracts while SMEs purchase modular capabilities.
- Transportation:Road freight dominates domestic volume through Alexandria-Dekheila and Port Said corridors, with fleet operators absorbing diesel price volatility through fuel surcharge mechanisms. Suez Canal transit volumes and Nile Delta manufacturing density concentrate demand in containerized trucking and heavy-haul segments serving petrochemical and agricultural exporters.
- Warehousing:Bonded facilities in the Suez Canal Economic Zone command premium rates for re-export processing, while GDP-certified cold storage in Cairo and 10th of Ramadan City serves pharmaceutical distributors. Accredited capacity scarcity in Alexandria creates bottlenecks for temperature-sensitive imports requiring customs-adjacent staging.
- Freight Forwarding:Documentation precision and customs relationship depth differentiate providers serving automotive and pharmaceutical verticals in Greater Cairo.
- Customs Brokerage:Egyptian Customs Authority digitization mandates are elevating compliance complexity for port clearance operators in Alexandria and Port Said.
Transportation leads on scale; warehousing leads on momentum.
Delivery Model:
Application context shapes model selection, with manufacturing supply chains demanding sequencing precision while commodity traders prioritize cost minimization.
- Door-to-Door:Integrated liability coverage appeals to pharmaceutical and automotive manufacturers in 10th of Ramadan City requiring just-in-sequence delivery guarantees without inter-party handoff risk.
- Port-to-Port:Containerized agricultural and petrochemical exports through Alexandria-Dekheila retain volume leadership, with Suez Canal transit fee structures influencing routing decisions between Egyptian and competing Mediterranean hubs.
- Intermodal:Rail-sea combinations are gaining traction for bulk commodities moving from Upper Egypt industrial zones to Port Said export terminals.
- Last Mile:E-commerce order frequency in Greater Cairo and Alexandria is pulling network expansion into the Nile Delta manufacturing corridor, with MISR Logistics and similar operators building vehicle density for same-day fulfillment.
Port-to-Port dominates absolute volume; Last Mile is expanding most quickly.
End User:
Customer type dictates service tier requirements, with regulated industries demanding certification depth and commodity sectors prioritizing unit economics.
- Retail:Omnichannel inventory positioning in Greater Cairo requires flexible warehousing contracts with seasonal surge capacity and returns processing capabilities.
- Manufacturing:Nile Delta electronics and automotive assemblers in 10th of Ramadan City are pushing just-in-sequence liability upstream to logistics providers, substituting delivery window guarantees for traditional inventory-holding arrangements.
- Automotive:Tier-one assemblers require component sequencing precision that halts production lines upon error, elevating freight forwarder integration into enterprise ERP systems.
- Pharmaceuticals:Temperature-sensitive drug imports from European manufacturers demand GDP-certified cold chain infrastructure with 2-8°C validation, concentrating accredited capacity in Cairo and creating Alexandria access bottlenecks.
Manufacturing leads on scale; pharmaceuticals leads on margin expansion.
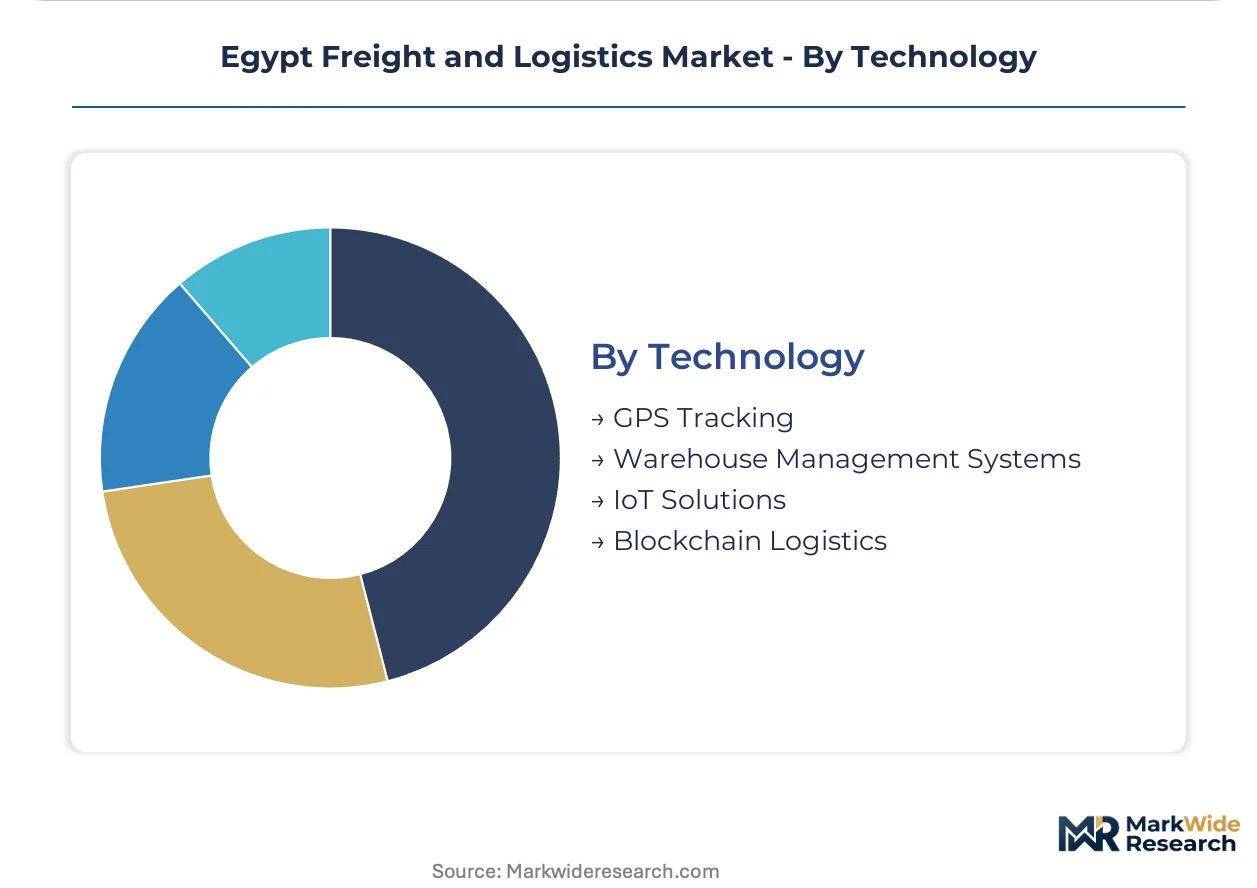
Technology:
Supply concentration among integrated platform providers is segmenting the market between digitized incumbents and legacy operators facing compliance pressure.
- GPS Tracking:Telematics deployment across 1,200-plus vehicle domestic fleets enables real-time visibility for Nile Delta manufacturing clients, though capital intensity excludes mid-tier operators from full fleet retrofit.
- Warehouse Management Systems:Automated inventory positioning and order fulfillment are becoming prerequisites for bonded warehouse accreditation in the Suez Canal Economic Zone, compressing labor-dependent operations.
- IoT Solutions:Temperature monitoring fused with automated warehouse management is opening precision cold chain service tiers for vaccine distributors requiring continuous 2-8°C validation documentation.
- Blockchain Logistics:Egyptian Customs Authority digitization requirements are accelerating adoption for pharmaceutical exporters and automotive parts distributors seeking unified customs declaration, bill of lading, and insurance verification architectures.
Warehouse Management Systems leads on deployment breadth; Blockchain Logistics shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Suez Canal Economic Zone anchors Egypt's freight and logistics infrastructure, concentrating bonded warehousing and re-export processing capacity along the canal corridor. Demand distribution across Egyptian sub-regions reflects manufacturing density, port proximity, and regulatory accreditation availability.
Greater Cairo
Pharmaceutical cold chain infrastructure and GDP-certified warehousing concentrate in Cairo and 10th of Ramadan City, serving temperature-sensitive drug imports from European manufacturers. The Egyptian Customs Authority mandates pre-arrival declaration submission for pharmaceutical distributors operating in this cluster. Last-mile delivery networks are expanding vehicle density to serve e-commerce order frequency across the metropolitan area.
Alexandria and Dekheila Port Corridor
Containerized agricultural and petrochemical exports drive port-to-port volume leadership through Alexandria-Dekheila terminals. CMA CGM Group leverages terminal presence to control transshipment flows across the Eastern Mediterranean. Accredited warehouse scarcity creates bottlenecks for pharmaceutical distributors requiring customs-adjacent staging in this northern coastal zone.
Port Said and the Suez Canal Economic Zone
Underpenetrated re-export processing capacity in Port Said East offers expansion white space for transshipment logistics operators. The General Authority for Supply Commodities streamlines bonded warehouse clearance protocols within this zone. Maritime transit fee structures are drawing re-export volume away from competing Mediterranean hubs into Egyptian bonded facilities.
Nile Delta Manufacturing Corridor
Just-in-sequence delivery contracting is replacing traditional inventory-holding arrangements for automotive and electronics assemblers in this industrial belt. MISR Logistics operates fleet density exceeding 1,200 vehicles concentrated in this corridor. Diesel price fluctuations directly compress road freight margins for domestic operators serving manufacturing clients.
Egypt Freight and Logistics Market Competitive Landscape
Capacity expansion dominates the current landscape as operators race to capture bonded warehousing demand and GDP-certified cold storage accreditation. The market structures around integrated global forwarders with Egyptian terminal assets, regional specialists with domestic fleet density, and port-centric handlers with customs relationship depth. Three archetypes define competitive positioning: maritime-integrated multinationals controlling transshipment flows, domestic last-mile specialists with Nile Delta coverage, and customs-bonded warehouse operators with Suez Canal Economic Zone presence. M&A activity and strategic partnerships represent the dominant competitive moves as players seek vertical coverage.
Among maritime-integrated multinationals, CMA CGM Group and DP World exemplify terminal-anchored strategies that leverage physical infrastructure control to capture re-export and transshipment value. DHL Group occupies a position within the pharmaceutical cold chain tier, representing the integrated forwarder archetype that combines global network reach with local GDP-certified facility accreditation. These three companies illustrate how competitive positioning in Egyptian logistics increasingly depends on bonded space control and regulatory certification depth rather than pure transportation scale.
| Leading Market Players |
|---|
| CMA CGM Group |
| DB Schenker |
| DHL Group |
| MISR Logistics |
| Kadmar Group |
| DSV A/S |
| DP World |
| Damietta Container & Cargo Handling Co |
| Kuehne + Nagel |
| Others |
Supply & Pricing Matrix
Captive warehousing networks in the Suez Canal Economic Zone anchor both supply positioning and pricing power for bonded logistics operators serving re-export flows. Egyptian Customs Authority digitization mandates compress clearance velocity differentials between accredited and non-accredited facilities, concentrating margin capture in GDP-certified cold storage tiers.
Pricing Analysis
Diesel pass-through mechanisms dominate road freight contracting across the Alexandria-Dekheila corridor, with fleet operators indexing fuel surcharges to Egyptian General Petroleum Corporation pricing benchmarks. Three-tier pricing structure separates GDP-certified pharmaceutical cold chain from standard bonded warehousing and commodity dry storage, with certification grade and volume scale as primary differentiation drivers. Cost compression in domestic last-mile segments is intensifying because e-commerce order frequency pulls new vehicle capacity into Greater Cairo. SMEs exhibit highest price sensitivity, while pharmaceutical distributors accept premium rates for temperature-validated 2-8°C documentation.
Supply Chain Analysis
Single-source vulnerability sits with European pharmaceutical manufacturers supplying temperature-sensitive drug imports into Cairo and 10th of Ramadan City. Equipment manufacturing draws from China, Germany, and South Korea for reefer container production and telematics hardware. Logistics chokepoint risk concentrates in Alexandria-Dekheila port throughput capacity, where customs-adjacent staging scarcity extends detention exposure. Distribution runs through bonded warehouse networks in the Suez Canal Economic Zone, with Port Said East offering underpenetrated re-export processing white space.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's freight sector functions as a geographic-arbitrage play between European pharmaceutical sourcing costs and Suez Canal transit fee advantages relative to competing Mediterranean hubs.
For Market Incumbents: To counter GDP-certified capacity scarcity in Alexandria, CMA CGM Group and DHL Group should accelerate backward integration into cold storage construction. Port Said East bonded warehouse expansion represents a priority lever for capturing transshipment volume diversion from competing hubs.
For New Entrants and Emerging Players: Customs-digitization platform routes offer lowest barrier-to-entry for integrated software providers targeting Egyptian Customs Authority compliance automation. White space concentrates in IoT-enabled reefer monitoring for vaccine distributors and last-mile vehicle density in the Nile Delta manufacturing corridor beyond MISR Logistics coverage.
For Investors and Strategic Acquirers: Roll-up economics work for domestic fleet operators because fragmentation across 1,200-plus vehicle mid-tier carriers creates scale-premium acquisition targets. Long-term viability hinges on Suez Canal tariff recalibration sustaining re-export volume inflows. The signal to watch is Egyptian Customs Authority clearance automation timelines accelerating bonded warehouse accreditation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| GDP-Certified Cold Storage Expansion | Pharmaceutical distributors in Cairo require 2-8°C validation for European drug imports. |
| Customs Digitization Platform Integration | Egyptian Customs Authority mandates compress documentation cycles for automotive exporters. |
| Last-Mile Fleet Density Buildout | E-commerce order frequency in Greater Cairo pulls vehicle capacity from Nile Delta corridors. |
| Bonded Warehouse Accreditation | General Authority for Supply Commodities protocols streamline Port Said East clearance windows. |
| Reefer Telematics Deployment | IoT temperature monitoring enables precision service tiers for vaccine distribution contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations managers, pharmaceutical supply chain directors, customs brokerage heads, and bonded warehouse operators with secondary validation. Egyptian Customs Authority regulatory filings, Suez Canal Authority transit statistics, General Authority for Supply Commodities accreditation databases, and operator fleet disclosures anchored the dataset. Bottom-up vehicle count and facility capacity estimates triangulated against top-down port throughput and trade flow analyses.
Comparable-period anchoring linked historical clearance velocity and bonded space utilization to projected pharmaceutical import growth and e-commerce order frequency trajectories across the modeling period. Segmentation dimensions spanned service modality, delivery architecture, end-user vertical, and technology layer, with cold chain certification tier and customs zone location as industry-specific stratifiers. CAGRs derived from weighted regression across import volume, fleet expansion, and accreditation pipeline indicators, incorporating diesel price volatility and Suez Canal tariff adjustment scenarios.
The model assumes a particular technology adoption path; alternative pathways for blockchain-enabled documentation platforms would alter the outlook if Egyptian Customs Authority mandates accelerate beyond current timelines. Forecasts reflect assumptions about GDP certification commissioning cycles and bonded warehouse construction lead times. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Argentina Freight and Logistics Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Warehousing and Distribution Logistics Market
Logistics and Shipping
Saudi Arabia Third-Party Logistics (3PL) Market
Logistics and Shipping
Australia Mining Logistics Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Bangladesh Freight and Logistics Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
India less than Truckload Road Freight Transport Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
Hong Kong Container Transshipment Market