
 Reusable Sediment Control Wattles Market | 2026-2036
Reusable Sediment Control Wattles Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Sediment Control Wattles Market Analytics
Skilled erosion control installer availability is collapsing across active construction corridors, forcing contractors toward durable, redeployable products that reduce repeat site visits. Durawattle leverages its specialized geotextile manufacturing to capture premium specification work. ERTEC Environmental Systems anchors its position through direct contractor channel control in the Pacific Northwest. Gator Guard Environmental Products differentiates via bamboo-based material portfolios that appeal to municipal green procurement criteria.
Reusable sediment control wattles are cylindrical filtration barriers constructed from geotextile or natural fiber jackets filled with compost, wood fiber, or synthetic media, typically 6 to 12 inches in diameter and designed for perimeter protection, inlet defense, and slope interruption across disturbed sites. Fiber-wrapped and geotextile product types dominate current procurement volumes due to superior hydraulic performance and extended deployment cycles. Compost-filled configurations command attention from environmental agencies prioritizing biodegradability, while stormwater management applications generate the fastest specification growth as MS4 permittees face escalating compliance scrutiny.
EPA NPDES Phase II requirements, state-level department of environmental quality erosion control mandates, and ISO 14001-aligned municipal procurement frameworks collectively elevate product certification and performance documentation standards. These regulatory layers filter market access toward manufacturers with verified third-party testing and transparent material sourcing. Stakeholders must monitor evolving state-level sediment load limits and green infrastructure incentives that will determine specification winners in high-growth construction corridors.
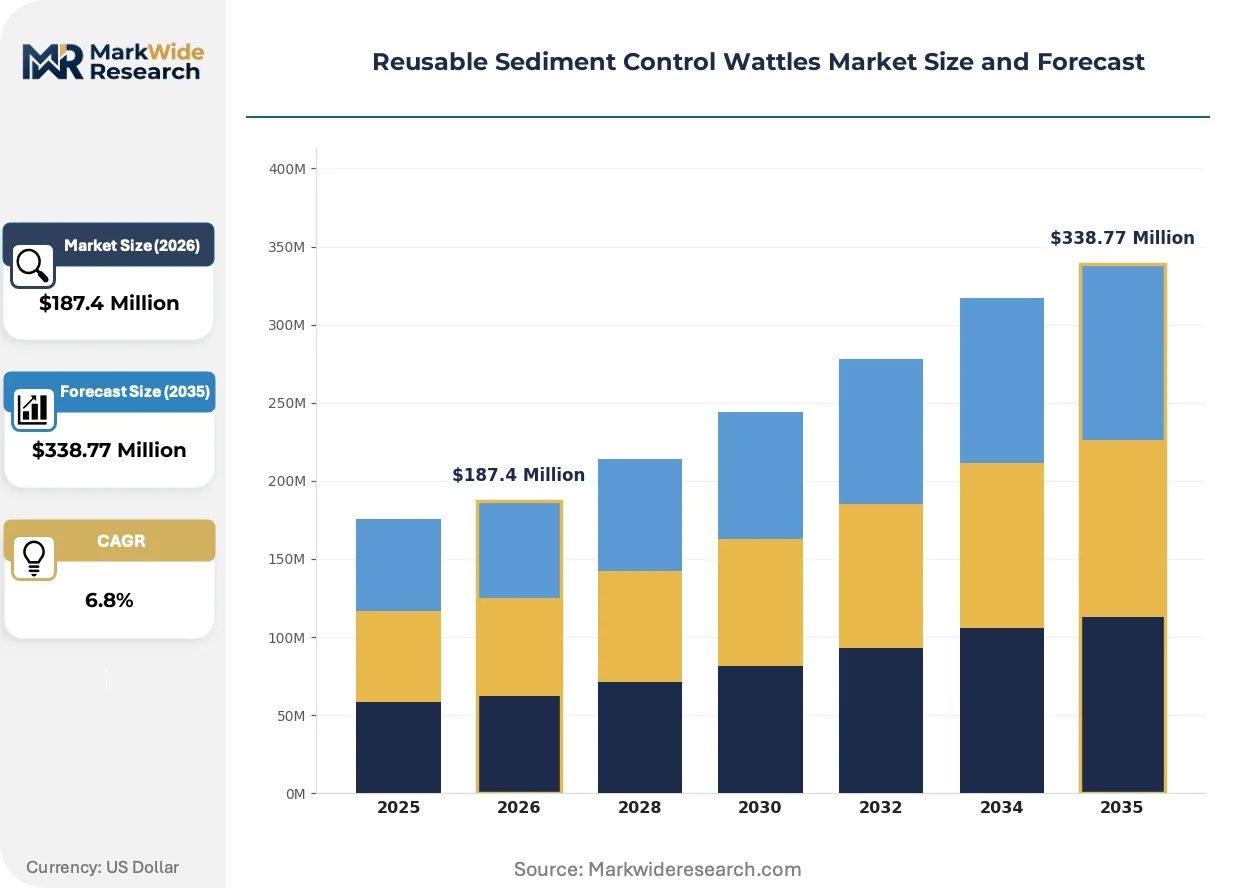
Market Dynamics
Installer labor shortages across active construction corridors are compressing deployment cycles and forcing specification shifts toward durable, redeployable filtration barriers that minimize repeat site visits.
Growth Catalysts
- EPA Phase II MS4 Permitting:Municipal stormwater departments face escalating discharge scrutiny, driving specification of reusable wattles over single-use alternatives for compliance durability.
- Compost-Filled Configurations:Environmental agencies prioritize biodegradability in green procurement frameworks, elevating organic media-filled products in municipal bidding processes.
- Southeastern United States Concentration:Construction activity intersects with high rainfall erosion risk in Florida, Georgia, and the Carolinas, concentrating demand for perimeter protection systems.
Market Restraints
- Geotextile Input Volatility:Polypropylene and polyester fiber costs fluctuate with petrochemical feedstock markets, compressing margin stability for jacket manufacturers.
- Specialized Installer Scarcity:Certified erosion control technicians concentrate in limited metropolitan labor pools, creating deployment bottlenecks during peak construction seasons.
- Single-Use Competing Products:Straw wattles and silt socks retain cost advantages for short-duration projects, limiting price elasticity in budget-constrained segments.
Strategic Opportunities
- Green Infrastructure Incentives:State-level stormwater credit programs reward municipalities for biodegradable filtration media, opening procurement pathways for compost-filled configurations.
- Pacific Northwest Channel Expansion:Direct contractor relationships in Washington and Oregon remain underdeveloped relative to specification potential from wet-climate construction activity.
- ISO 14001-Aligned Certification:Transparent material sourcing documentation unlocks municipal procurement frameworks that filter access toward verified manufacturers.
Industry Challenges
- Third-Party Testing Documentation:Hydraulic performance verification requires extended laboratory cycles that delay product qualification for urgent infrastructure bids.
- Geotextile Manufacturing Integration:In-house jacket production demands capital equipment for specialized weaving and coating operations that mid-scale competitors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Sediment Control Wattles Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber-Wrapped, Geotextile, Compost, Erosion Control Material: Bamboo, Coconut Coir, Synthetic Fiber, Wood Fiber Application: Construction Sites, Agricultural Fields, Stormwater Management, Landscaping End User: Contractors, Municipalities, Environmental Agencies, Landscape Professionals |
| Companies Covered | Durawattle, Gator Guard Environmental Products, ERTEC Environmental Systems, Earthsavers Erosion Control, Envirotech Environmental Consulting, The Wattle Guys, Enviroscape ECM, MKB Company, Cascade Geosynthetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Sediment Control Wattles Market Evolving Landscape
Material science advances and procurement digitization are reconfiguring how filtration barriers are specified, deployed, and redeployed across disturbed construction sites.
Biodegradable jacket materials derived from coconut coir and jute fiber are fragmenting the traditional synthetic geotextile dominance in municipal specifications. Environmental agencies in the southeastern United States now mandate organic alternatives for projects adjacent to sensitive watersheds. This shift is fragmenting supplier hierarchies as natural fiber processors without petrochemical supply chains capture specification share.
State-level total maximum daily load requirements are tightening sediment discharge thresholds beyond federal EPA baselines. California's regional water quality control boards and Virginia's department of environmental quality now impose site-specific wattle performance standards. Contractors in these jurisdictions must document hydraulic capacity and deployment cycle counts, elevating certified products over commodity alternatives.
Municipal procurement departments are consolidating vendor pools through pre-qualified product lists that filter access by certification status. Stormwater managers in Florida and Georgia now require ISO 14001-aligned sourcing documentation before bid consideration. This behavioral shift is compressing the competitive field toward manufacturers with transparent supply chain auditing and third-party performance verification.
Reusable Sediment Control Wattles Market Segmentation
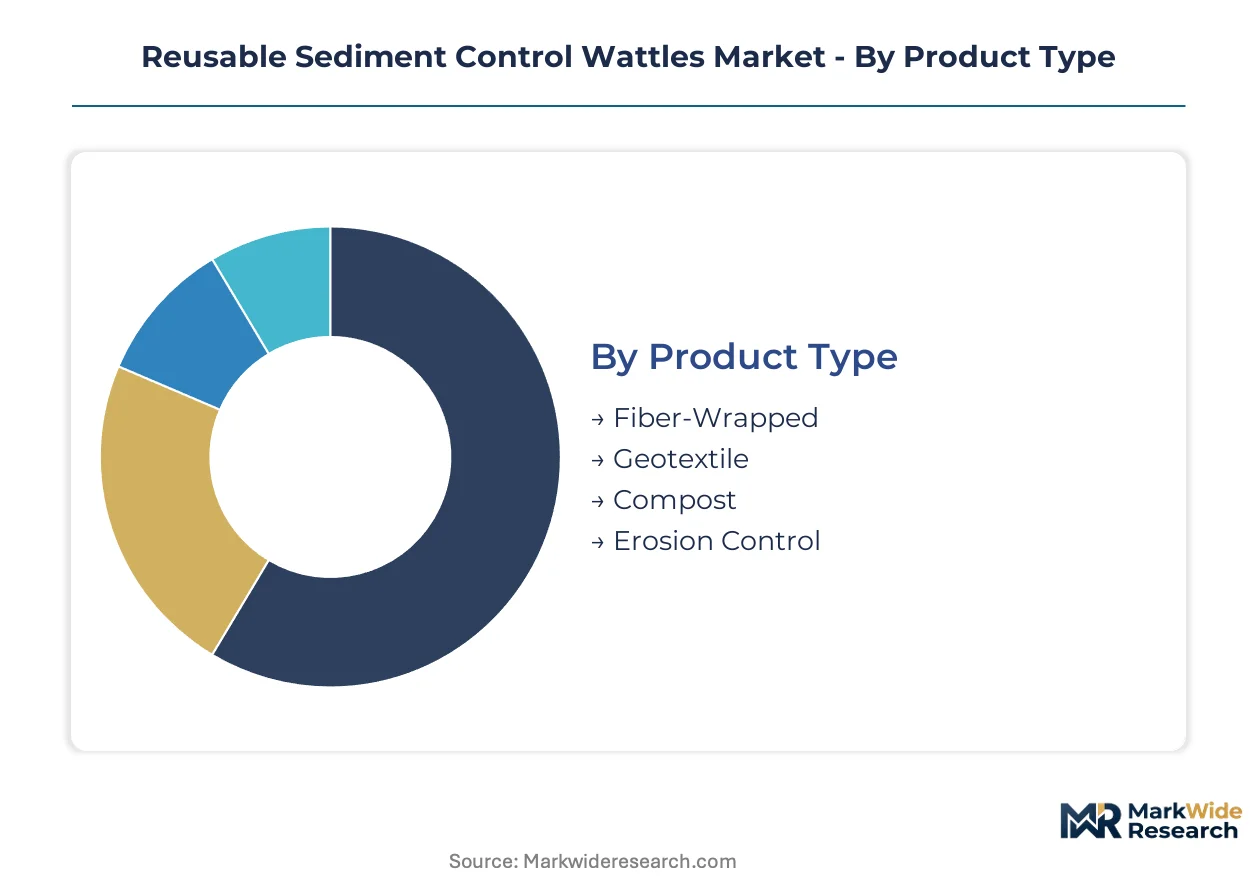
Segmentation in the reusable sediment control wattles market reveals distinct margin structures across material technologies and procurement channels. Specification patterns diverge sharply between municipal stormwater departments and commercial contractors, with certification requirements filtering access by product category.
Product Type:
Fiber-wrapped and geotextile configurations capture premium margin pools due to extended deployment cycles and hydraulic performance documentation requirements.
- Fiber-Wrapped:Cylindrical barriers constructed from woven natural fiber jackets filled with compost or wood media. Demand concentrates in Florida and Georgia where municipal stormwater departments mandate biodegradable perimeter protection for watershed-adjacent projects. EPA Phase II MS4 compliance documentation drives specification toward certified fiber-wrapped products with verified sediment retention rates.
- Geotextile:Synthetic polypropylene or polyester jacket constructions offering superior durability across multiple deployment cycles. Carolina construction corridors specify these for high-traffic commercial sites where inlet defense requires repeated pressure washing and redeployment. Labor scarcity across southeastern installer pools accelerates demand for products minimizing repeat site visits.
- Compost:Organic media-filled configurations prioritizing biodegradability in green procurement frameworks.
- Erosion Control:General-purpose filtration barriers for slope interruption and perimeter sediment containment.
The dominant share belongs to Geotextile, while Compost is closing the gap fastest.
Material:
Natural fiber inputs command specification premiums in municipal bidding processes where environmental agencies prioritize transparent sourcing documentation.
- Bamboo:Rapid-renewable structural fiber with high tensile strength for jacket construction. Municipal green procurement criteria in the southeastern United States elevate bamboo-based portfolios in pre-qualified vendor lists. State-level stormwater credit programs reward biodegradable filtration media selection.
- Coconut Coir:Lignin-rich fiber derived from coconut husks with superior water retention and decomposition characteristics. Virginia Department of Environmental Quality watershed protection mandates specify coir for projects adjacent to impaired water bodies. Site-specific performance standards require documented hydraulic capacity.
- Synthetic Fiber:Polypropylene and polyester constructions offering cost stability and manufacturing consistency.
- Wood Fiber:Processed cellulose media from forestry byproducts for compost-filled configurations.
Bamboo holds the specification lead among natural alternatives, though Coconut Coir is expanding most quickly in coastal jurisdictions.
Application:
Stormwater management applications generate the steepest specification growth curves as MS4 permittees face escalating discharge scrutiny.
- Stormwater Management:Inlet defense and discharge point filtration for municipal separate storm sewer systems. California Regional Water Quality Control Boards impose performance standards beyond federal EPA baselines, requiring documented deployment cycle counts. Contractors must specify certified products with third-party hydraulic verification.
- Construction Sites:Perimeter protection and slope interruption across disturbed earthworks. High rainfall erosion risk in Florida and Georgia concentrates demand for durable redeployable barriers that reduce installer labor requirements during compressed deployment cycles.
- Agricultural Fields:Runoff control and sediment retention for cultivated land management.
- Landscaping:Aesthetic and functional filtration for residential and commercial green infrastructure.
Construction Sites maintain volume leadership, yet Stormwater Management is gaining share fastest under tightening regulatory thresholds.
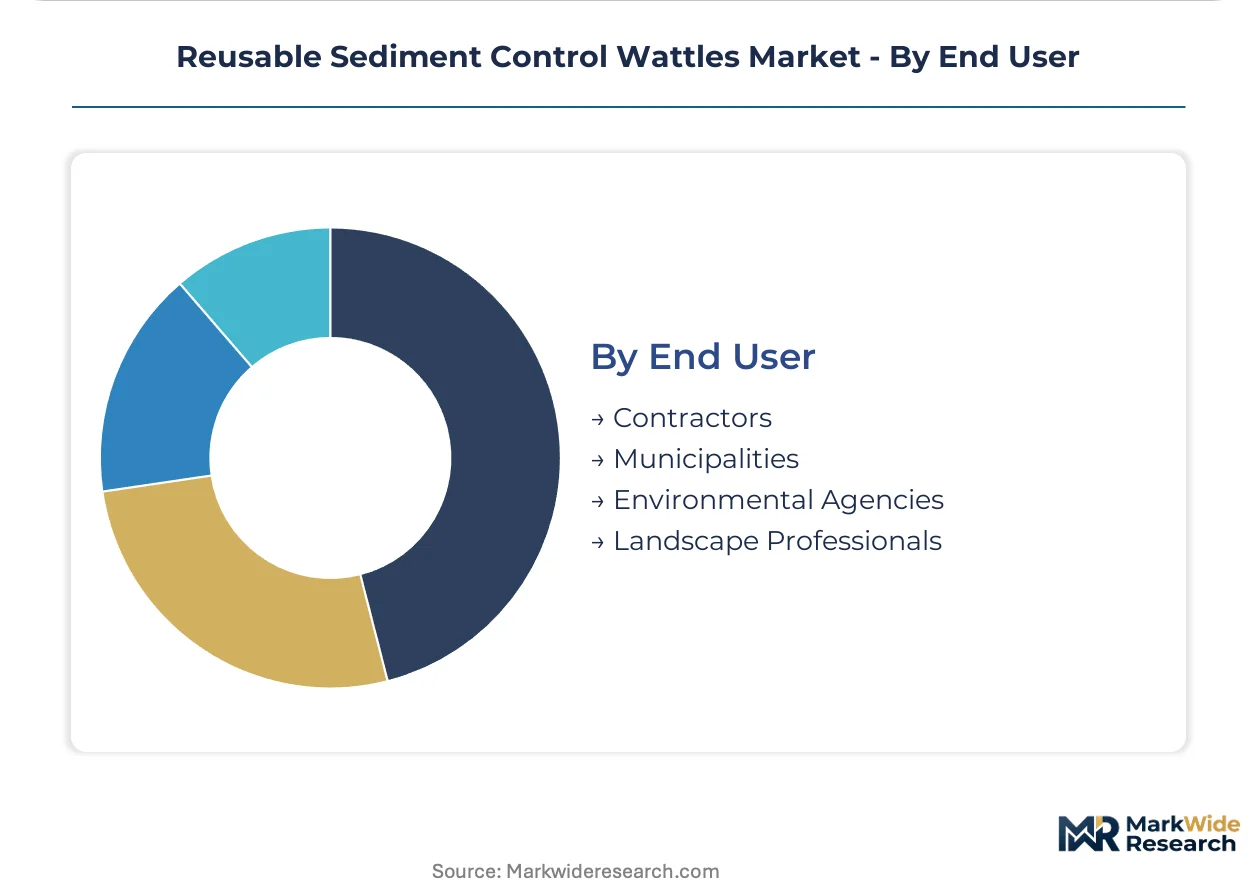
End User:
Municipal procurement departments consolidate vendor access through ISO 14001-aligned certification requirements that filter toward transparent supply chain auditing.
- Municipalities:Stormwater departments and public works agencies managing MS4 infrastructure. Florida and Georgia procurement offices now require third-party performance verification and material sourcing documentation before bid consideration. Pre-qualified product lists compress competitive fields toward verified manufacturers.
- Contractors:Commercial construction firms and erosion control specialists deploying filtration barriers. Pacific Northwest wet-climate construction activity generates specification potential, though direct contractor channel relationships remain underdeveloped relative to demand concentration in Washington and Oregon.
- Environmental Agencies:Regulatory bodies and watershed management districts mandating compliance technologies.
- Landscape Professionals:Residential and commercial green infrastructure installers.
Contractors represent the largest procurement volume, while Municipalities are tightening qualification standards most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between the southeastern United States, where high rainfall drives perimeter protection demand, and the Pacific Northwest, where wet-climate construction generates inlet defense specifications. Municipal procurement intensity concentrates in Florida and Georgia, while contractor-driven volume clusters in the Carolinas.
United States
EPA Phase II MS4 permitting and state-level total maximum daily load requirements tighten discharge standards across Florida, Georgia, and the Carolinas. The Virginia Department of Environmental Quality imposes site-specific wattle performance standards for watershed-adjacent projects. Construction corridors in Charlotte and Atlanta concentrate demand for durable, redeployable barriers that reduce installer labor requirements during compressed deployment cycles.
Canada
Municipal stormwater departments in Ontario and British Columbia specify reusable wattles over single-use alternatives for compliance durability in high-rainfall construction zones. Environment and Climate Change Canada guidelines align with ISO 14001 procurement frameworks that filter vendor access by certification status. The Greater Toronto Area generates specification volume for geotextile configurations serving commercial site perimeter protection.
Germany
The EU Green Deal and national implementation of the Water Framework Directive elevate biodegradable filtration media in public procurement processes. REACH compliance documentation requirements filter market access toward manufacturers with transparent material sourcing. Industrial construction clusters in Bavaria and North Rhine-Westphalia drive demand for certified products with verified hydraulic performance.
Australia
State-level environmental protection authorities in New South Wales and Queensland impose sediment discharge thresholds that exceed federal baselines for construction activity near impaired water bodies. The country's national environmental regulator mandates performance documentation for stormwater management infrastructure. Sydney and Melbourne metropolitan construction corridors concentrate demand for extended-deployment filtration barriers.
United Kingdom
Environment Agency discharge permits and local authority sediment control mandates tighten compliance requirements for construction sites across England and Wales. The UK regulator's permitting framework elevates certified products with third-party hydraulic verification. London and Southeast England infrastructure projects generate specification volume for municipal stormwater departments managing MS4 infrastructure.
Reusable Sediment Control Wattles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding premium specification work through in-house geotextile manufacturing and the latter competing on niche material portfolios. The market structure rewards vertical control over jacket production and direct contractor channel relationships. Three archetypes dominate: integrated manufacturers with captive weaving operations, regional specialists leveraging localized installer networks, and natural-fiber processors capturing green procurement share. Competitive moves concentrate on capacity expansion for specialized coating operations and strategic partnerships with municipal procurement departments.
Among North American specialists, Durawattle and ERTEC Environmental Systems exemplify contrasting positioning archetypes, with the former representing integrated manufacturing depth and the latter anchoring direct contractor channel control in underdeveloped Pacific Northwest markets. Gator Guard Environmental Products occupies a position within the natural-fiber tier, exemplifying how bamboo-based material portfolios capture municipal green procurement criteria in the southeastern United States. These three companies illustrate how certification status and material sourcing transparency increasingly determine specification outcomes across tightening regulatory environments.
| Leading Market Players |
|---|
| Durawattle |
| Gator Guard Environmental Products |
| ERTEC Environmental Systems |
| Earthsavers Erosion Control |
| Envirotech Environmental Consulting |
| The Wattle Guys |
| Enviroscape ECM |
| MKB Company |
| Cascade Geosynthetics |
| Others |
Value Network & Pricing Analysis
Specialized weaving capacity utilization above eighty percent in southeastern US geotextile mills creates asymmetric pricing power for jacket manufacturers with in-house production, compressing margin recovery options for mid-scale competitors sourcing from merchant suppliers while elevating floor prices for certified products across municipal procurement channels.
Pricing Analysis
Long-term offtake agreements dominate municipal stormwater department procurement, with Florida and Georgia agencies locking in eighteen-to-thirty-six month supply contracts that insulate certified manufacturers from spot polypropylene volatility. Price differentiation stratifies across ISO 14001-aligned certification tiers, with third-party verified products commanding fifteen-to-twenty-five percent premiums over commodity alternatives. Cost compression in standard-grade geotextile configurations is intensifying because straw wattle competitors retain acute price advantages for short-duration projects. Commercial contractors exhibit highest price sensitivity, while municipal procurement offices prioritize compliance durability over unit economics.
Supply Chain Analysis
Inventory cycles extending ninety-to-one-hundred-twenty days for coconut coir fiber create working capital intensity for natural fiber processors competing against synthetic alternatives with faster replenishment. Geotextile jacket production concentrates in the United States, China, and Germany, with specialized coating operations tethered to petrochemical feedstock corridors in Texas and Louisiana. Raw material dependencies center on polypropylene resin, polyester staple fiber, and lignin-rich organic media from coconut processing. Single-source vulnerability in certified compost supply from southeastern US facilities exposes manufacturers to state-level environmental agency sourcing mandates. Distribution runs through direct contractor channels in the Carolinas and municipal procurement frameworks in Florida and Georgia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where municipal pre-qualified vendor lists function as two-sided platforms connecting certified manufacturers with MS4 permittees, with interoperability emerging around ISO 14001-aligned documentation standards that lock in specification winners.
For Market Incumbents: Shield specification share by accelerating captive weaving capacity additions in Georgia and the Carolinas before mid-scale competitors secure financing for comparable vertical integration. Defend against natural fiber processors by pre-empting state-level stormwater credit program eligibility through third-party biodegradability certification. Channel control in underdeveloped Pacific Northwest markets represents the priority defensive perimeter. For New Entrants and Emerging Players: Lead with compost-filled configurations targeting Virginia Department of Environmental Quality watershed protection mandates where site-specific performance standards have thinned incumbent coverage. The Pacific Northwest contractor channel remains the most penetrable geography, with Washington and Oregon wet-climate construction activity outpacing established distributor relationships. A go-to-market angle anchored in direct installer training partnerships bypasses municipal procurement bottlenecks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated manufacturers with municipal offtake visibility and in-house geotextile production, positioning these archetypes for durable cash flow quality across the five-to-ten year infrastructure investment window. Acquisition targets should display ISO 14001-aligned certification infrastructure and transparent supply chain auditing capabilities. The signal to watch is state-level total maximum daily load threshold tightening beyond federal EPA baselines, which would accelerate specification consolidation toward verified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Geotextile Weaving | In-house jacket production captures margin pools from merchant suppliers while satisfying municipal ISO 14001 sourcing documentation requirements. |
| Third-Party Biodegradability Certification | State-level stormwater credit programs in Florida and Georgia reward certified compost-filled configurations with pre-qualified vendor list placement. |
| Pacific Northwest Channel Development | Direct contractor relationships in Washington and Oregon unlock wet-climate construction demand currently underserved by established distributors. |
| Installer Training Network Expansion | Certified technician scarcity across southeastern construction corridors creates competitive moats for manufacturers with proprietary deployment education programs. |
| Compost Supply Partnership Structuring | Long-term agreements with southeastern US organic media processors mitigate single-source vulnerability under tightening state-level environmental agency mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with erosion control contractors, municipal stormwater managers, geotextile manufacturing plant engineers, and certified installation technicians; alongside secondary validation through EPA NPDES permit databases, state department of environmental quality enforcement records, and SEC filings from publicly traded geosynthetics manufacturers. Bottom-up deployment volume estimates from construction permit data triangulated against top-down municipal procurement budget allocations.
Across the analysis window, the forecasting framework modeled volume and value trajectories across product type, material composition, application intensity, and end-user procurement channel dimensions. CAGRs were derived from regression-weighted historical deployment patterns and regulatory timeline acceleration assumptions. Industry-specific inputs included MS4 permittee compliance cost surveys and geotextile input price elasticity coefficients from petrochemical feedstock correlation models.
Forecasts assume regulatory continuity in EPA Phase II MS4 permitting and state-level total maximum daily load regimes; material policy shifts in Virginia or California water quality board thresholds would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
North America Waste Management Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
Mining Waste Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
Scrap Metal Recycling Market