
 Vacuum Waste Systems Market | 2026-2036
Vacuum Waste Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Waste Systems Market Analysis
Specialized vacuum engineering talent is rotating from maritime and aerospace sectors into urban infrastructure applications, easing a bottleneck that had delayed municipal deployment timelines. Envac leverages decades of pneumatic network experience from Swedish district heating corridors to sustain technology leadership in dense urban installations. Wärtsilä anchors its position through marine vacuum sanitation expertise that transfers directly to offshore and island communities lacking conventional waste logistics. MariMatic Oy competes with automated sorting integration that extends system value beyond mere collection.
Vacuum waste systems transport refuse through underground or overhead pipe networks using differential air pressure, typically operating at flow velocities of 18–25 meters per second with particle sizes up to 50 millimeters to serve high-throughput commercial and residential environments. The primary industrial purpose centers on eliminating truck-based collection in dense districts, cutting transport emissions and surface congestion while enabling continuous rather than scheduled waste removal. Pneumatic vacuum technology dominates current installations across Nordic and East Asian cities, though hybrid systems that combine electric pre-sorting with pneumatic transport represent the fastest-expanding segment as facilities seek energy optimization. Medical facilities command premium system configurations due to stringent contamination control requirements, while commercial spaces generate the broadest volume base for standardized product offerings.
EU F-Gas Regulation and national building codes in Sweden, Finland, and Denmark mandate energy-efficient waste handling in new urban developments, directly embedding vacuum infrastructure into permitting requirements. ISO 18601 packaging standards and REACH chemical compliance shape material selection for system components, particularly in food-adjacent and medical applications. Stakeholders must monitor how municipal procurement frameworks evolve to bundle vacuum collection with circular economy obligations rather than treating it as standalone infrastructure.
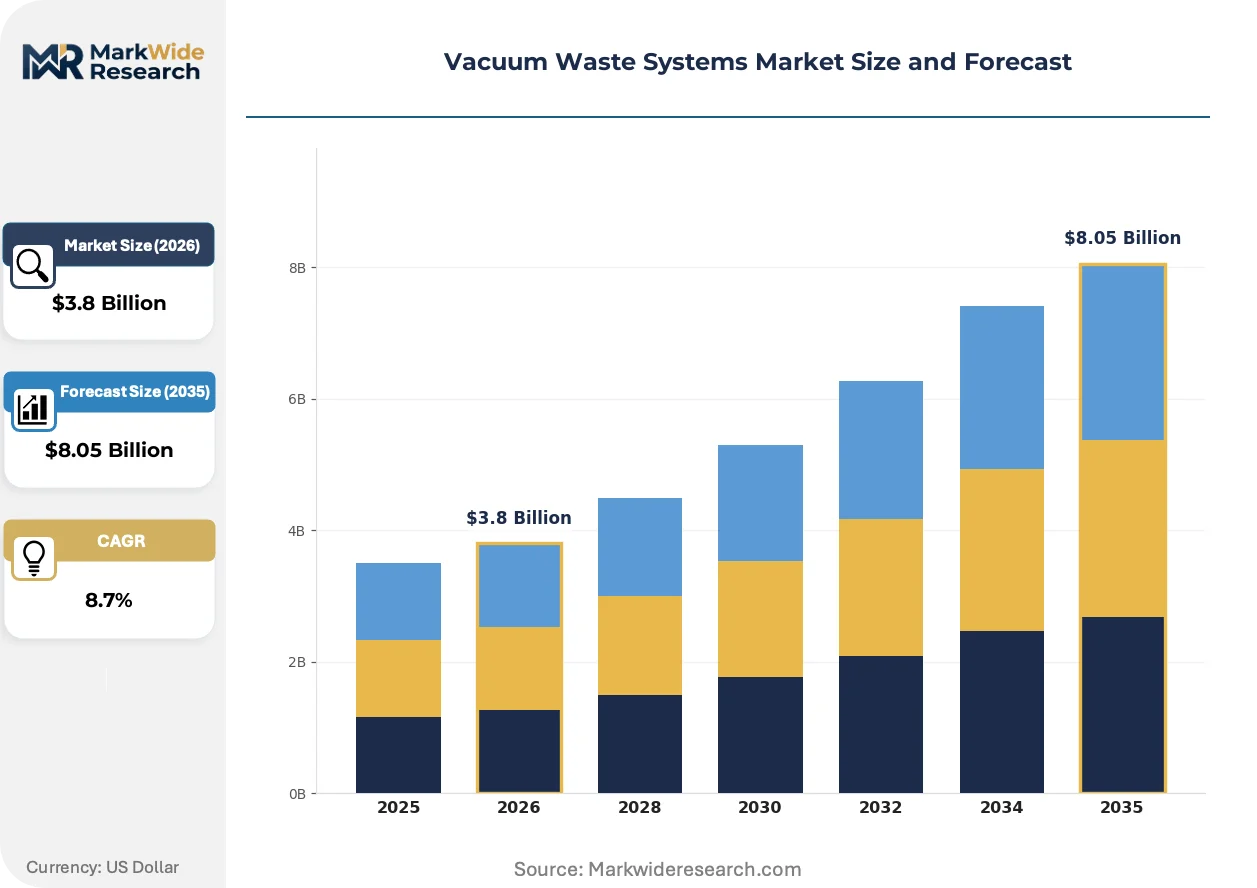
Market Dynamics
The EU Green Deal's waste hierarchy mandate is compressing deployment timelines for pneumatic collection infrastructure across Nordic municipal procurement cycles.
Growth Catalysts
- EU F-Gas Regulation:Building codes in Sweden, Finland, and Denmark now embed energy-efficient waste handling into permitting requirements for new urban districts.
- Maritime-to-infrastructure talent rotation:Specialized vacuum engineering expertise is migrating from shipbuilding and aerospace sectors into urban infrastructure applications.
- Stockholm cluster effect:Hammarby Sjöstad's district-scale deployment has created a replicable template that municipal planners across Scandinavia are now adopting.
Market Restraints
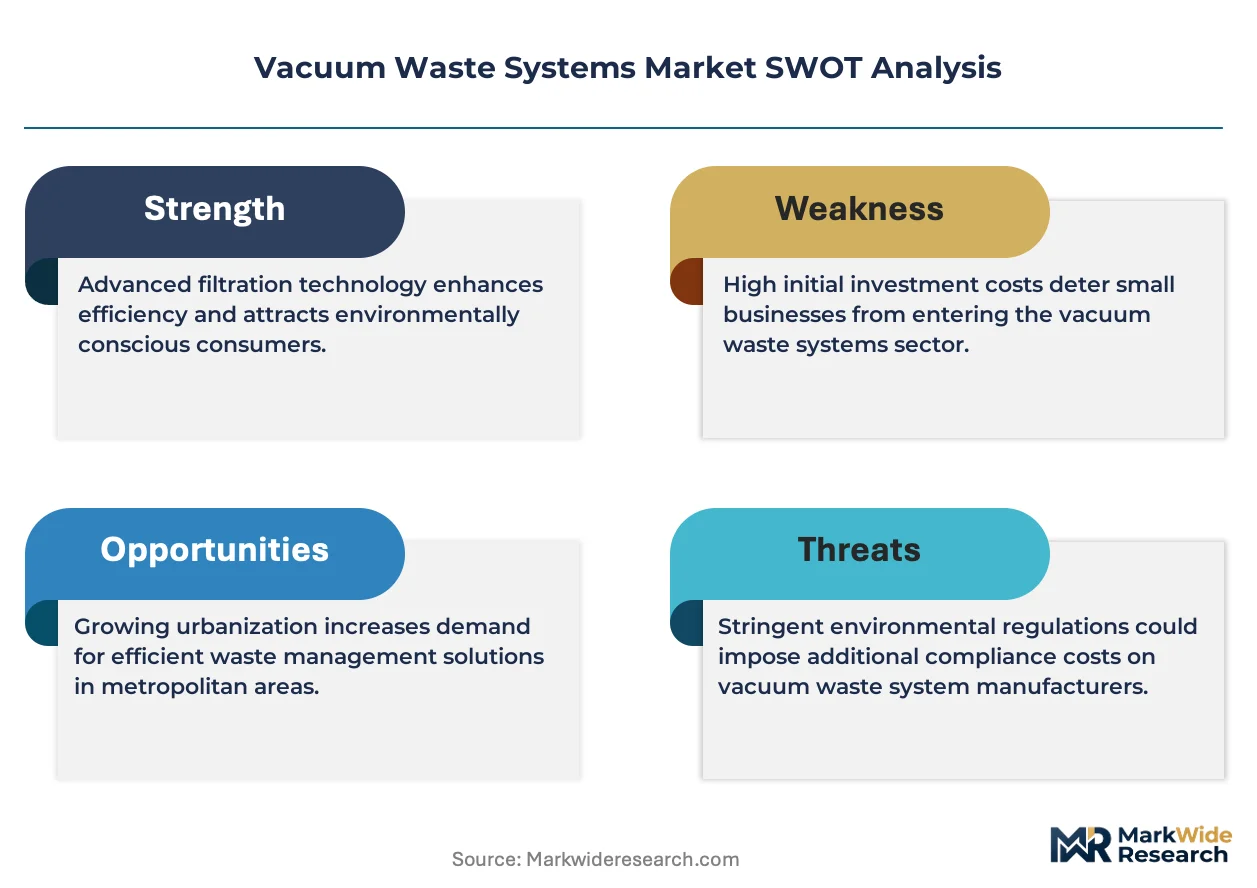
- Capital intensity:Underground pipe network installation requires substantial upfront municipal expenditure that strains budget-constrained city administrations.
- Steel and polymer input volatility:System component manufacturing faces cost pressure from fluctuating stainless steel and high-density polyethylene prices.
- Technical throughput ceilings:Current pneumatic systems max out at particle sizes of 50 millimeters, excluding bulky furniture and construction debris streams.
Strategic Opportunities
- Hybrid electric-pneumatic convergence:Facilities are integrating automated pre-sorting with pneumatic transport to capture energy optimization gains.
- Medical facility premium configurations:Contamination control requirements in healthcare settings command specialized system designs at higher margin tiers.
- Island and offshore communities:Locations lacking conventional waste logistics infrastructure represent captive demand for self-contained vacuum networks.
Industry Challenges
- Vacuum engineering talent scarcity:Municipal deployment timelines face delays from insufficient specialized technicians trained in pneumatic network maintenance.
- Legacy bin collection integration:Retrofitting existing dense urban districts requires complex coordination with established waste management contracts and surface infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Waste Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centralized Systems, Portable Systems, Stationary Units, Mobile Units Application: Residential Use, Commercial Spaces, Industrial Facilities, Medical Facilities Technology: Pneumatic Vacuum, Electric Vacuum, Hydro Vacuum, Hybrid Systems End User: Households, Hotels, Hospitals, Manufacturing Plants |
| Companies Covered | Envac, Evac Group, Aqseptence Group, Jets Vacuum AS, MariMatic Oy, Logiwaste AB, Collins Aerospace, MEIKO Group, Wärtsilä, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Waste Systems Market Emerging Trajectories
Active experimentation with hybrid system architectures is reshaping how facilities balance energy consumption against collection throughput in pneumatic waste networks.
Automated sorting integration is decomposing the traditional boundary between collection and processing stages. Medical facilities and high-throughput commercial complexes are adopting sensor-equipped inlet stations that separate recyclables before pneumatic transport. This convergence is decomposing the standalone collection value proposition that dominated early market development.
REACH chemical compliance and ISO 18601 packaging standards are tightening material specifications for food-adjacent and medical system components. Manufacturers must now certify polymer selections against migration limits and mechanical durability benchmarks. Medical waste streams and hospital procurement departments face the steepest compliance burden, driving preference toward pre-certified system suppliers.
After-sales service unbundling is fragmenting long-term maintenance relationships between municipal buyers and original equipment providers. Stockholm and Copenhagen procurement frameworks now separate capital installation from decade-long operations contracts, enabling third-party facility management firms to bid on network maintenance. This shift is most pronounced in Scandinavian cities with mature pneumatic infrastructure seeking operational cost transparency.
Vacuum Waste Systems Market Segmentation
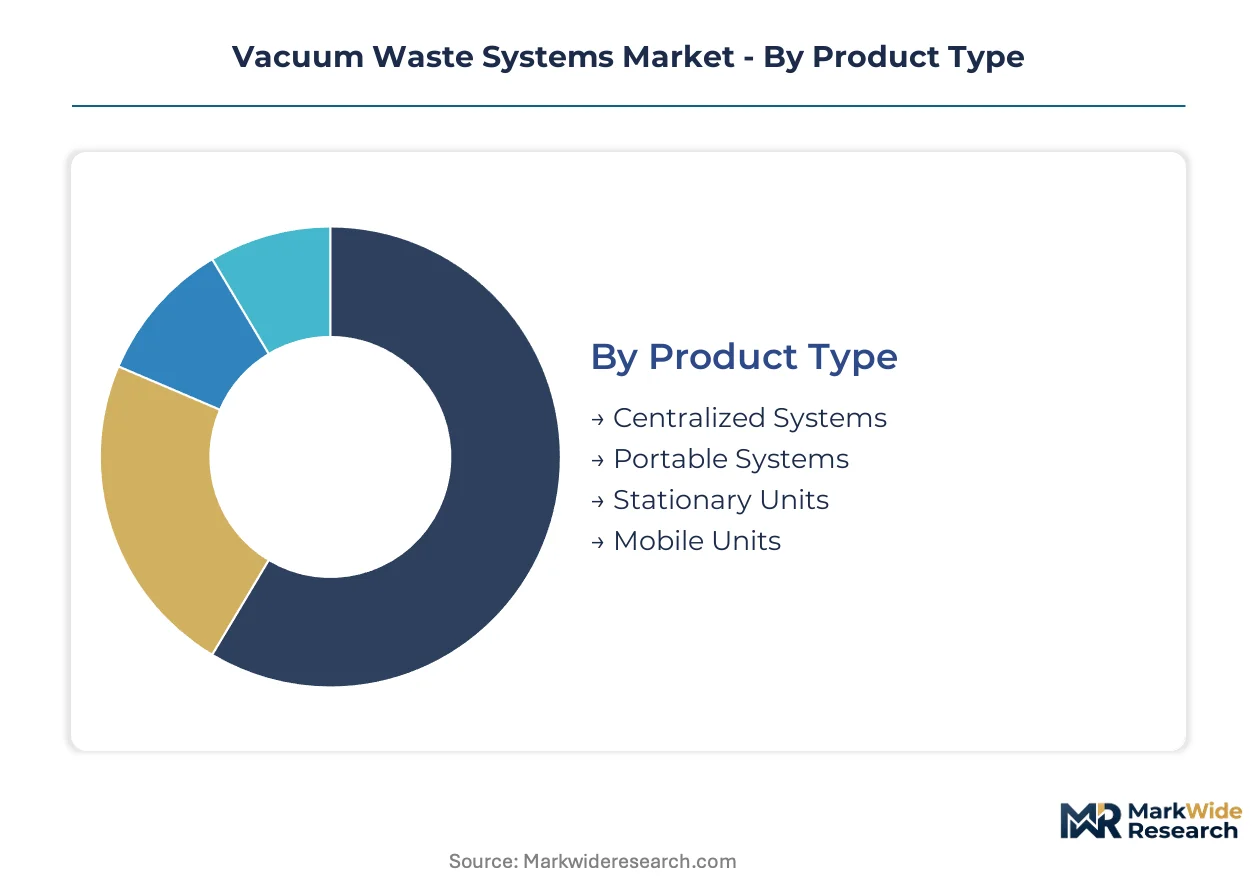
Vacuum waste systems fragment across four critical dimensions that determine both capital deployment patterns and operational economics. Product architecture dictates underground infrastructure requirements, while application context shapes contamination protocols and throughput specifications. Technology selection governs energy intensity and maintenance cadence. End-user concentration in Nordic urban corridors concentrates margin pools with municipal procurement sophistication.
Product Type:
Margin pools concentrate in subterranean network installations where engineering complexity creates pricing power for specialized contractors.
- Centralized Systems:Underground pipe networks serve entire districts through automated collection stations, requiring municipal-scale capital commitment. Sweden's Hammarby Sjöstad deployment anchors European demand, with Finnish and Danish planners replicating the template in waterfront redevelopment zones.
- Portable Systems:Modular units deploy temporarily at construction sites, festivals, or emergency response scenarios where permanent infrastructure is impractical. Island communities lacking conventional waste logistics generate captive demand across Scandinavian archipelagos and Mediterranean resorts.
- Stationary Units:Fixed installations serve single buildings or complexes with dedicated vacuum infrastructure.
- Mobile Units:Truck-mounted or trailer-based systems enable flexible collection route coverage.
Centralized systems hold installed capacity. Portable systems are rotating up the share rankings.
Application:
Volume concentration follows urban density gradients, with premium pricing available where contamination control requirements escalate.
- Residential Use:Multi-family housing developments integrate inlet stations directly into building lobbies or basement corridors. Stockholm's municipal housing corporations bundle vacuum collection into new construction permits, creating standardized procurement templates.
- Commercial Spaces:Shopping centers, airports, and business districts demand high-throughput configurations with continuous rather than scheduled removal. Copenhagen's Ørestad development demonstrates district-scale commercial deployment.
- Industrial Facilities:Manufacturing plants require robust particle handling and chemical resistance specifications.
- Medical Facilities:Hospitals and clinics mandate sealed transport pathways with infection control certification. EU F-Gas Regulation and national building codes in Sweden, Finland, and Denmark embed energy-efficient waste handling into healthcare construction permits.
Commercial spaces hold installed capacity. Medical facilities are rotating up the share rankings.
Technology:
Customer procurement patterns bifurcate between proven pneumatic reliability and emerging hybrid architectures seeking energy optimization.
- Pneumatic Vacuum:Differential air pressure systems dominate Nordic and East Asian installations, operating at 18–25 meters per second flow velocity. Decades of Swedish district heating corridor engineering transfer directly to urban waste networks.
- Electric Vacuum:Motor-driven suction enables precise flow control and reduced noise profiles in sensitive environments.
- Hydro Vacuum:Water-assisted transport handles heavy or abrasive waste streams in industrial contexts.
- Hybrid Systems:Electric pre-sorting converges with pneumatic transport to capture energy gains while maintaining throughput. Facilities across Denmark and Finland are expanding most quickly in this configuration as they retrofit existing pneumatic networks with automated inlet stations.
Pneumatic vacuum holds installed capacity. Hybrid systems are climbing the fastest.
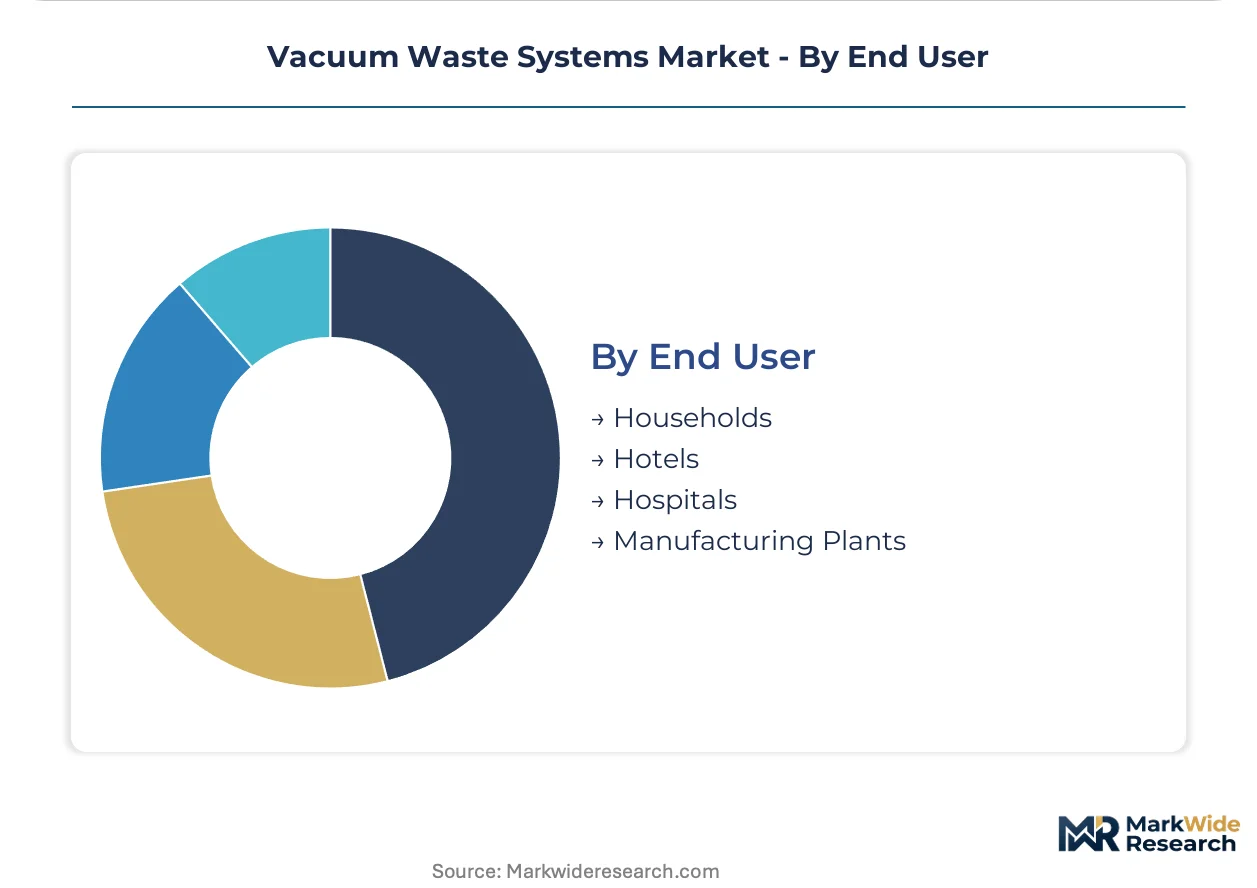
End User:
Purchasing authority concentrates with facility management departments that bundle long-term operations contracts separately from capital installation.
- Households:Individual consumers access vacuum waste through multi-family housing developments rather than single-family installations. Municipal procurement frameworks in Stockholm and Copenhagen now separate decade-long operations from initial capital deployment.
- Hotels:Hospitality properties in dense urban cores leverage continuous removal to eliminate surface collection schedules and guest disruption.
- Hospitals:Healthcare procurement departments face REACH chemical compliance and ISO 18601 packaging standards for food-adjacent and medical system components.
- Manufacturing Plants:Industrial operations require integration with production schedules and hazardous waste protocols.
Households hold installed capacity. Hospitals are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden deploys vacuum waste at district scale for residential decarbonization, while Japan and South Korea prioritize commercial high-throughput installations in dense urban cores. The United Arab Emirates and Singapore represent emerging demand centers where island geography and zero-landfill mandates override conventional collection economics.
Sweden
Stockholm's Hammarby Sjöstad district anchors European pneumatic network deployment, with municipal housing corporations bundling vacuum collection into new construction permits. The EU F-Gas Regulation and national building codes embed energy-efficient waste handling into urban development approvals. Gothenburg and Malmö planners replicate the template in waterfront redevelopment zones.
Japan
Tokyo commercial districts and Osaka airport complexes drive high-throughput system demand for continuous waste removal without surface truck access. METI building efficiency standards incentivize pneumatic infrastructure in new high-rise developments. The Kansai region demonstrates district-scale commercial deployment with automated inlet stations.
South Korea
Seoul Capital Area multi-family housing developments integrate vacuum collection to eliminate basement storage odors and collection vehicle congestion. The Ministry of Environment enforces extended producer responsibility frameworks that accelerate substitution of conventional bin systems. Busan-Ulsan coastal developments adopt marine-adapted configurations for humidity resistance.
Singapore
Public Housing Development Board estates pilot centralized vacuum networks to reduce manual collection labor in aging demographic conditions. The National Environment Agency mandates smart waste infrastructure in new town developments. Tampines and Punggol districts host operational installations with automated sorting integration.
United Arab Emirates
Dubai Expo 2020 legacy districts and Abu Dhabi Masdar City deploy vacuum systems where conventional landfill logistics face geographic constraints. Dubai Municipality building codes incentivize pneumatic collection in mega-development permits. NEOM Northwest represents planned district-scale deployment in zero-carbon city construction.
Vacuum Waste Systems Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in vacuum waste systems. The upper tier commands municipal-scale project execution capability and decade-long service contracting relationships. Below them, component specialists and regional installers compete on installation speed and maintenance responsiveness. Two strategic archetypes dominate: full-system integrators with pneumatic network heritage, and marine-aerospace crossover players transferring vacuum engineering expertise. Competitive moves concentrate on hybrid technology licensing partnerships and operations contract unbundling to capture facility management relationships.
Among Nordic full-system integrators, Envac and MariMatic Oy occupy positions shaped by decades of district heating corridor and automated sorting integration experience respectively. Wärtsilä anchors the marine crossover archetype, transferring vacuum sanitation expertise from shipbuilding into island and offshore community applications. These three exemplify how engineering heritage from adjacent sectors creates differentiated positioning in municipal infrastructure procurement cycles.
| Leading Market Players |
|---|
| Envac |
| Evac Group |
| Aqseptence Group |
| Jets Vacuum AS |
| MariMatic Oy |
| Logiwaste AB |
| Collins Aerospace |
| MEIKO Group |
| Wärtsilä |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month project lead times for centralized pneumatic network deployment concentrate pricing power with Scandinavian system integrators who control engineering talent pools and municipal reference sites. This temporal compression simultaneously exposes buyers to steel and polymer input volatility while rewarding contractors with proven district-scale execution track records.
Pricing Analysis
Long-term municipal offtake contracts dominate vacuum waste system procurement, with decade-spanning operations agreements now unbundled from capital installation in Stockholm and Copenhagen frameworks. Price differentiation separates medical-grade sealed configurations from standard commercial installations, with contamination control certification commanding substantial premiums. Cost compression in standardized commercial tiers is intensifying as third-party facility management firms compete for maintenance contracts. Municipal housing corporations exhibit highest price sensitivity due to budget-constrained procurement cycles, while medical facilities demonstrate lowest sensitivity given stringent compliance mandates.
Supply Chain Analysis
Port congestion on Baltic trade lanes elevates inbound logistics costs for stainless steel piping and high-density polyethylene components sourced from German and Polish manufacturing centers. System manufacturing concentrates in Sweden, Finland, and Denmark, drawing from specialized vacuum engineering talent pools anchored in maritime and aerospace sectors. Supply chains rest on single-source vulnerability for pneumatic valve assemblies and automated inlet station controllers. Distribution runs through municipal procurement frameworks that bundle vacuum infrastructure with circular economy permitting requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum waste systems are entering a cyclical upswing as EU Green Deal waste hierarchy mandates compress municipal deployment timelines and accelerate substitution of conventional bin collection.
For Market Incumbents: Consolidate engineering talent pools in Stockholm and Copenhagen to defend against maritime-aerospace crossover entrants poaching pneumatic network specialists. Pursue backward integration into automated inlet station manufacturing to capture margin from hybrid system convergence and reduce exposure to third-party component volatility.
For New Entrants and Emerging Players: CE marking fast-track for medical facility configurations opens immediate revenue paths in hospital procurement cycles facing REACH compliance burdens. Target island and offshore communities lacking conventional waste logistics as captive demand centers with self-contained portable system offerings. Lead with automated sorting integration to differentiate from established collection-only incumbents.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hybrid electric-pneumatic configurations as pre-sorting technology commoditizes, shifting returns toward software-enabled service layers. Acquire facility management firms with municipal operations contracts to capture recurring revenue streams decoupled from capital deployment cycles. Monitor municipal procurement framework evolution toward circular economy bundling as inflection signal for system integrator margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Licensing Partnership | Electric-pneumatic convergence captures energy optimization gains in Danish retrofit installations. |
| Medical Facility Certification Investment | ISO 18601 and REACH compliance opens premium-tier hospital procurement channels. |
| Operations Contract Unbundling | Separate maintenance bidding enables third-party facility management firm market entry. |
| Maritime-Aerospace Talent Acquisition | Specialized vacuum engineering migration accelerates municipal deployment capability. |
| Island Community Portable System Deployment | Geographic constraints in Scandinavian archipelagos generate captive demand for modular units. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of municipal procurement databases, EU regulatory filings, and pneumatic network engineering specifications. Primary interviews engaged municipal infrastructure planners, vacuum system maintenance technicians, hospital procurement managers, and district heating corridor engineers. Secondary validation drew from EU F-Gas Regulation implementation reports, REACH chemical compliance databases, and ISO 18601 packaging standard documentation. Bottom-up installation capacity estimates triangulate against top-down municipal capital expenditure projections.
Segmentation dimensions modeled span product architecture, application context, technology selection, and end-user concentration across the projection horizon. Pneumatic vacuum, electric vacuum, hydro vacuum, and hybrid system configurations anchor technology-based splits. Residential, commercial, industrial, and medical application tiers shape demand calibration. CAGRs derive from municipal procurement cycle analysis, EU Green Deal mandate implementation trajectories, and steel-polymer input cost sensitivity modeling.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and stable Baltic logistics corridors; material deviation would warrant model refresh. Specific risk factors include municipal budget constraint intensification, pneumatic engineering talent scarcity escalation, and alternative waste-to-energy technology substitution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market
Waste Management & Pollution Control
Compostable Straws Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
North America Solid Waste Management Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
Food Waste Management Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market