
 GCC Waste Management Market | 2026-2036
GCC Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Waste Management Market Foresight
Saudi Arabia's landfill diversion mandates are rebalancing how collection and treatment capacity gets distributed across the GCC. Bee'ah leverages its Sharjah-based infrastructure to anchor UAE emirate-level contracts. Averda competes through hazardous waste specialization across multiple Gulf states. Saudi Investment Recycling Company dominates domestic material recovery with upstream control over feedstock streams.
GCC Waste Management encompasses the systematic collection, transportation, treatment, and disposal of solid, liquid, and gaseous waste streams generated across municipal, industrial, and commercial sources, with thermal processing facilities typically operating at combustion temperatures between 850°C and 1,100°C to ensure complete pathogen destruction and energy capture. The primary purpose is environmental protection through pollution prevention, resource recovery, and regulatory compliance with landfill diversion targets. Municipal Solid Waste commands the largest volume share across collection and transportation services, where per-capita generation rates in Qatar and Bahrain exceed regional averages. Energy Recovery through waste-to-gasification represents the fastest-expanding technology segment, as developers seek higher calorific extraction rates than conventional incineration permits. Hazardous Waste processing maintains the densest margin pool due to specialized handling certifications and limited treatment site availability.
The UAE's Ministry of Climate Change and Environment, Saudi Arabia's National Center for Waste Management, and Bahrain's Supreme Council for Environment enforce landfill diversion quotas and emissions thresholds that directly determine facility permitting timelines and operational compliance costs. These frameworks mandate source segregation, extended producer responsibility pilots, and waste-to-energy procurement targets that reshape capital allocation across the value chain. Stakeholders must monitor how emirate-level procurement consolidation and cross-border treatment agreements redefine competitive access before capacity commitments lock in.
Market Dynamics
Landfill diversion mandates across Saudi Arabia and the UAE are compressing treatment capacity timelines and forcing capital reallocation toward thermal processing infrastructure before legacy sites reach saturation.
Growth Catalysts
- Saudi Arabia's Circular Economy Policy Framework:The National Center for Waste Management enforces diversion quotas that accelerate waste-to-energy procurement and material recovery facility development.
- Waste-to-Gasification Technology Maturation:Higher calorific extraction rates than conventional incineration attract developer investment across Qatar and Bahrain industrial zones.
- Emirate-Level Consolidation:UAE procurement clustering around Sharjah-based infrastructure creates economies of scale in collection and transportation services.
Market Restraints
- Thermal Processing Capex Intensity:Combustion facilities operating at 850°C to 1,100°C require specialized refractory materials and emissions control systems that strain project finance structures.
- Hazardous Waste Site Scarcity:Limited treatment facility availability across Oman and Kuwait concentrates supply risk and extends logistics chains for specialized handling.
- Feedstock Quality Variability:Inconsistent municipal solid waste composition reduces energy recovery efficiency and complicates long-term power purchase agreements.
Strategic Opportunities
- Bahrain Industrial Waste Streams:Per-capita generation rates exceeding regional averages create underpenetrated demand for integrated collection and treatment services.
- Extended Producer Responsibility Pilots:UAE Ministry of Climate Change and Environment testing shifts liability upstream and opens new service revenue pools for packaging waste recovery.
- AI-Enabled Sorting Convergence:Machine vision integration with mechanical separation improves material purity and reduces manual labor dependency in material recovery facilities.
Industry Challenges
- Specialized Technician Scarcity:Waste-to-energy plant operations require certified boiler operators and emissions monitoring specialists that Gulf labor markets undersupply.
- Permitting Timeline Compression:Saudi Investment Recycling Company and competing developers face extended environmental impact review periods as regulatory capacity lags project pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Waste Management Market |
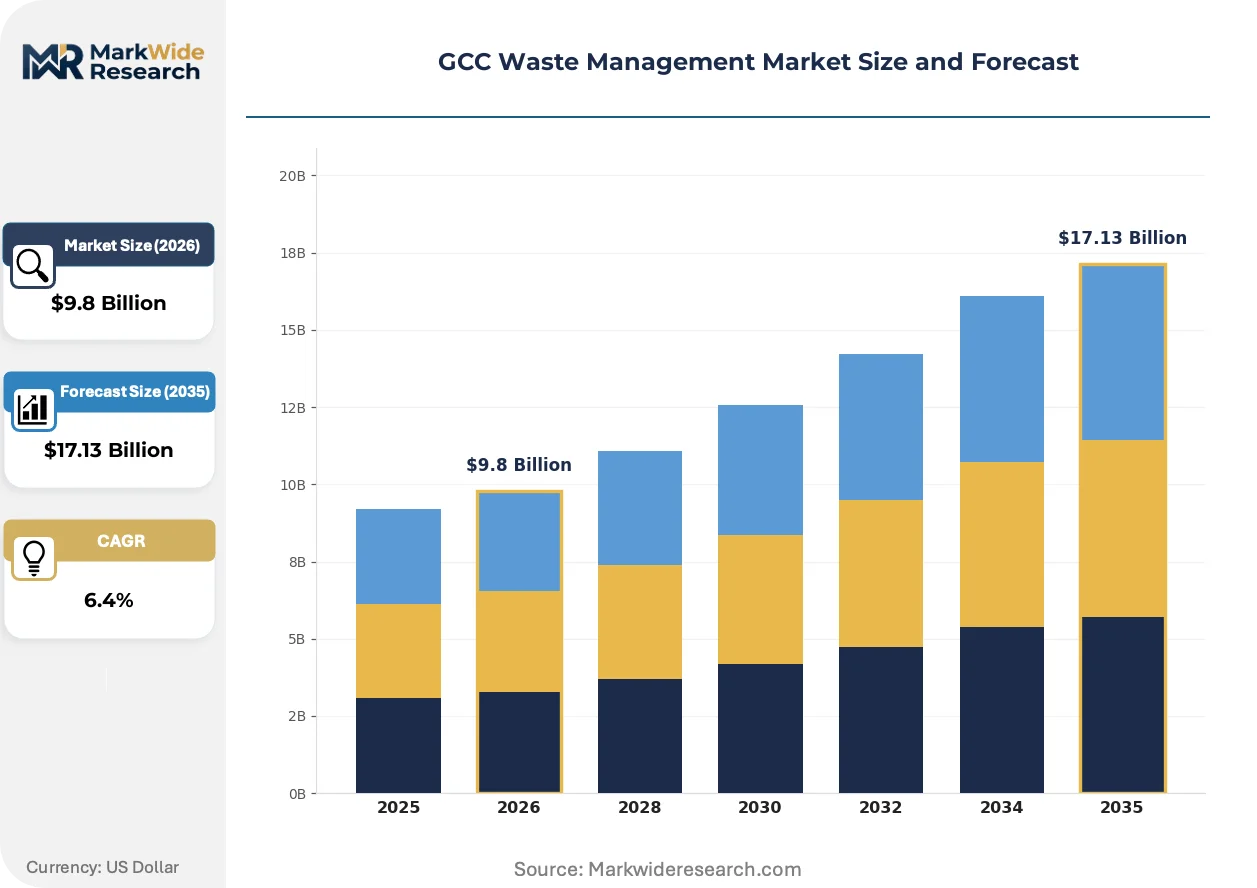
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Municipal Solid Waste, Industrial Waste, Hazardous Waste, Biomedical Waste, Construction Debris, Agricultural Residue Service Type: Collection & Transportation, Recycling, Waste Treatment, Landfill Management, Composting, Energy Recovery Waste Processing Technology: Incineration, Anaerobic Digestion, Mechanical Biological Treatment, Gasification, Pyrolysis, Chemical Treatment End User Sector: Municipal Authorities, Manufacturing Units, Healthcare Facilities, Construction Firms, Agricultural Organizations, Retail Chains |
| Companies Covered | SUEZ Middle East Recycling LLC, EnviroServe, Averda, SEPCO Environment, Blue LLC, Bee'ah, Veolia, Saudi Investment Recycling Company, Tadweer, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Waste Management Market Shifts & Advancements
Digital tracking systems and advanced thermal processing architectures are compressing operational transparency gaps and enabling real-time feedstock optimization across the GCC waste value chain.
Smart bin sensor networks paired with route optimization algorithms are decentralizing collection logistics across Saudi Arabia's municipal authorities. Riyadh and Jeddah municipalities deploy fill-level monitoring to eliminate static scheduling and reduce fleet fuel consumption. This distributed intelligence model compresses collection cycle times and enables dynamic resource allocation during seasonal pilgrimage peaks.
Saudi Arabia's National Center for Waste Management landfill diversion mandates are forcing facility developers to secure alternative treatment capacity before legacy site permits expire. Developers now front-load thermal processing investments to maintain operational continuity under tightening disposal restrictions. The hazardous waste segment faces the steepest compliance cost escalation due to limited substitute disposal pathways.
Service unbundling is fragmenting long-term municipal contracts into discrete collection, transportation, and treatment procurement lots. UAE emirate-level authorities now tender segregated service lines rather than integrated concessions, enabling specialized operators to capture niche segments. This procurement model shift is most visible in Sharjah, where Bee'ah anchors cluster infrastructure while competitors bid for satellite emirate contracts.
GCC Waste Management Market Segmentation
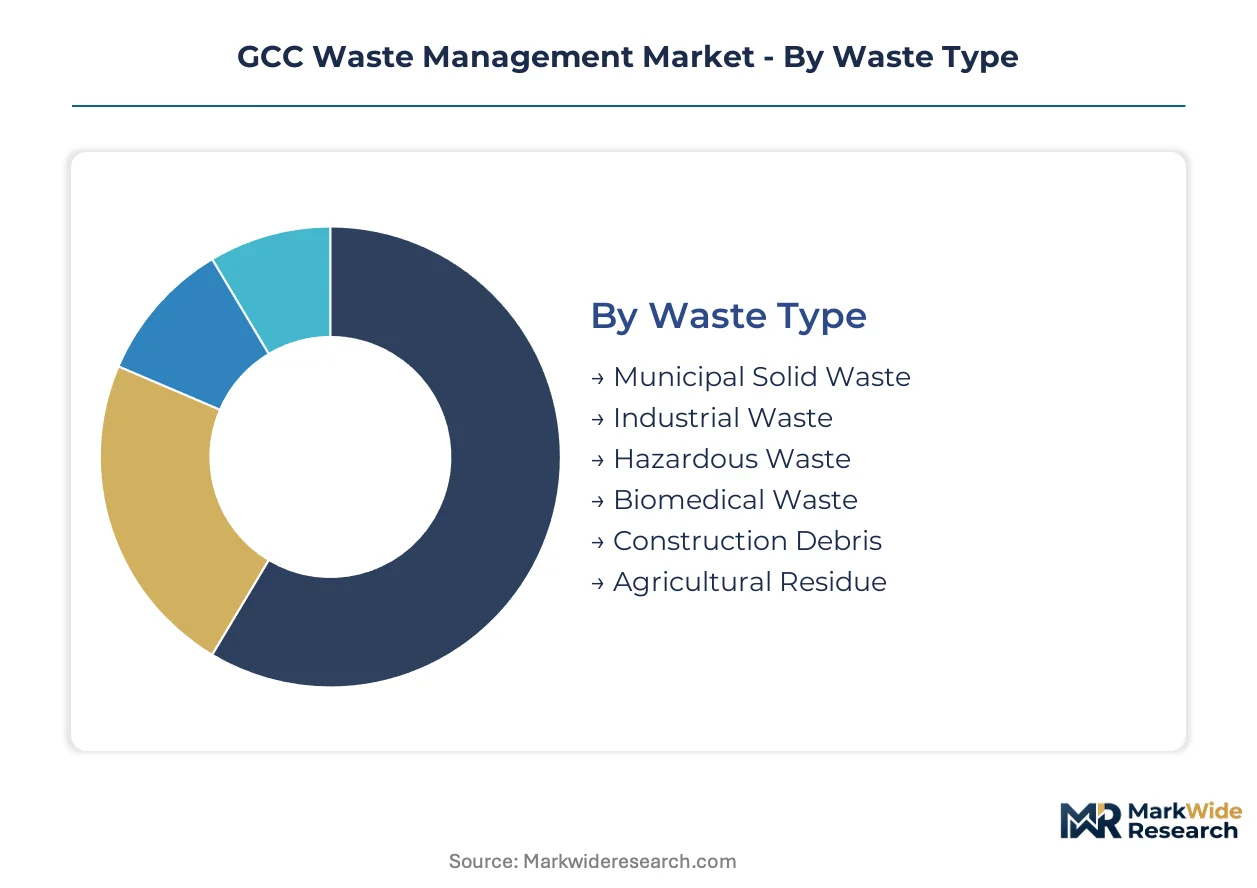
GCC waste management segmentation reveals how landfill diversion mandates and circular economy procurement reshape capital allocation across distinct waste streams and service tiers. Each category isolates where regulatory pressure concentrates versus where technology maturation unlocks new revenue pools.
Waste Type:
Volume concentration and margin density diverge sharply across waste categories, with municipal authorities prioritizing high-throughput streams while industrial generators pay premiums for specialized handling.
- Municipal Solid Waste:Household and commercial refuse streams dominate collection volumes across Saudi Arabia and UAE emirate-level contracts. Per-capita generation rates in Qatar and Bahrain exceed regional averages, forcing municipalities to front-load sorting infrastructure before thermal processing investments.
- Hazardous Waste:Chemical, flammable, and toxic material streams require specialized handling certifications and limited treatment site availability. Saudi Investment Recycling Company and Averda compete for industrial zone contracts where disposal pathway scarcity concentrates pricing power.
- Industrial Waste:Manufacturing byproduct streams span metal slag, spent solvents, and process wastewater requiring sector-specific treatment protocols.
- Biomedical Waste:Healthcare facility outputs demand pathogen destruction protocols at 850°C minimum combustion temperatures.
- Construction Debris:Concrete, asphalt, and demolition waste streams feed recycling aggregates markets across Gulf urbanization corridors.
- Agricultural Residue:Crop waste and livestock manure streams supply anaerobic digestion feedstocks in Saudi Arabia's central agricultural regions.
Volume sits with Municipal Solid Waste; growth tilts toward Hazardous Waste.
Service Type:
Procurement unbundling across UAE emirates fragments long-term concessions into discrete service lots, enabling specialized operators to capture niche segments without integrated infrastructure commitments.
- Collection & Transportation:Fleet-based logistics services deploy smart bin sensors and route optimization algorithms across Riyadh and Jeddah municipalities. Bee'ah anchors Sharjah-based cluster infrastructure while competitors bid for satellite emirate satellite contracts.
- Energy Recovery:Waste-to-gasification and incineration services extract calorific value at 850°C to 1,100°C operating temperatures. Qatar and Bahrain industrial zones attract developer investment seeking higher extraction rates than conventional incineration permits.
- Recycling:Material recovery facilities process segregated feedstocks into commodity-grade outputs for reprocessing industries.
- Waste Treatment:Physical, chemical, and biological processing services render waste streams inert or recoverable.
- Landfill Management:Legacy site operations face permit expiration timelines under Saudi Arabia's National Center for Waste Management diversion mandates.
- Composting:Organic waste aerobic decomposition services supply agricultural amendment markets.
Revenue concentrates in Collection & Transportation; margins expand fastest in Energy Recovery.
Waste Processing Technology:
Capital intensity and emissions compliance costs stratify technology adoption, with thermal processing architectures requiring specialized refractory materials and extended environmental impact review periods.
- Gasification:Partial oxidation at high temperature converts carbonaceous feedstocks into synthetic gas for power generation or chemical synthesis. Bahrain and Qatar industrial developers prioritize this pathway for superior calorific extraction versus conventional incineration.
- Incineration:Mass-burn combustion at 850°C to 1,100°C destroys pathogens and captures energy for district heating or electricity export. UAE Ministry of Climate Change and Environment procurement targets accelerate facility development despite project finance strain from emissions control system costs.
- Anaerobic Digestion:Microbial decomposition in oxygen-free environments produces biogas from organic feedstocks.
- Mechanical Biological Treatment:Combined sorting and composting processes stabilize residual waste before landfill disposal.
- Pyrolysis:Thermal decomposition in oxygen-limited conditions yields liquid fuels and carbon char.
- Chemical Treatment:Neutralization and stabilization processes render hazardous waste streams inert.
Deployment concentrates in Incineration; investment flows fastest into Gasification.
End User Sector:
Contract structure and payment security vary dramatically across buyer types, with municipal authorities offering volume visibility and industrial generators accepting premium pricing for specialized handling.
- Municipal Authorities:City and emirate-level governments tender integrated or unbundled waste services under landfill diversion quotas. Saudi Arabia's National Center for Waste Management enforcement accelerates procurement timelines as legacy site permits approach expiration.
- Healthcare Facilities:Hospitals and clinics generate biomedical waste streams requiring certified destruction documentation and chain-of-custody protocols. UAE Ministry of Climate Change and Environment mandates drive facility-level segregation investments.
- Manufacturing Units:Industrial plants produce process waste streams with variable composition and hazardous characteristics.
- Construction Firms:Developers and contractors generate debris streams subject to diversion targets for recycled aggregates.
- Agricultural Organizations:Farming cooperatives and livestock operations supply organic feedstocks for composting and digestion facilities.
- Retail Chains:Commercial establishments generate packaging and food waste streams targeted by extended producer responsibility pilots.
Contract volume sits with Municipal Authorities; fee growth tilts toward Healthcare Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Landfill diversion mandates and circular economy procurement are reshaping waste infrastructure investment across the Gulf Cooperation Council. Saudi Arabia and the UAE anchor regional capacity expansion through emirate-level clustering and national recycling company formation.
Saudi Arabia
Riyadh and Jeddah municipalities deploy smart bin sensor networks to compress collection cycle times during seasonal pilgrimage peaks. The National Center for Waste Management enforces diversion quotas that accelerate waste-to-energy procurement timelines. The Saudi Investment Recycling Company dominates domestic material recovery with upstream control over municipal feedstock streams.
United Arab Emirates
Sharjah-based infrastructure anchors UAE emirate-level waste-to-energy clusters through integrated collection and transportation services. The Ministry of Climate Change and Environment mandates source segregation and extended producer responsibility pilots that reshape capital allocation. Dubai and Abu Dhabi procurement authorities now tender unbundled service lots rather than integrated concessions.
Qatar
Per-capita waste generation rates exceeding regional averages force municipalities to front-load sorting infrastructure investments. The Supreme Council for Environment enforces landfill diversion targets that compress treatment capacity timelines. Industrial zones in Doha attract developer investment seeking higher calorific extraction through gasification technology.
Bahrain
Household and commercial refuse volumes create underpenetrated demand for integrated collection and treatment services. The Supreme Council for Environment mandates emissions thresholds that determine facility permitting timelines. Manama metropolitan authorities face legacy site saturation pressures under tightening disposal restrictions.
GCC Waste Management Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hazardous waste specialization and AI-enabled sorting convergence. The vendor base stratifies across three tiers: integrated infrastructure operators with emirate-level concessions, material recovery specialists controlling upstream feedstock access, and technology-focused entrants targeting unbundled service procurement lots. Dominant competitive moves include strategic partnerships for thermal processing capacity and geographic expansion through cross-border treatment agreements.
Within the integrated infrastructure tier, Bee'ah anchors Sharjah-based cluster development while Averda competes across multiple Gulf states through hazardous waste handling certifications. Saudi Investment Recycling Company occupies a position exemplifying upstream feedstock control in domestic material recovery. These three entities represent distinct competitive archetypes: emirate-cluster anchoring, multi-jurisdiction hazardous specialization, and national-scale vertical integration.
| Leading Market Players |
|---|
| SUEZ Middle East Recycling LLC |
| EnviroServe |
| Averda |
| SEPCO Environment |
| Blue LLC |
| Bee'ah |
| Veolia |
| Saudi Investment Recycling Company |
| Tadweer |
| Others |
Supply & Pricing Matrix
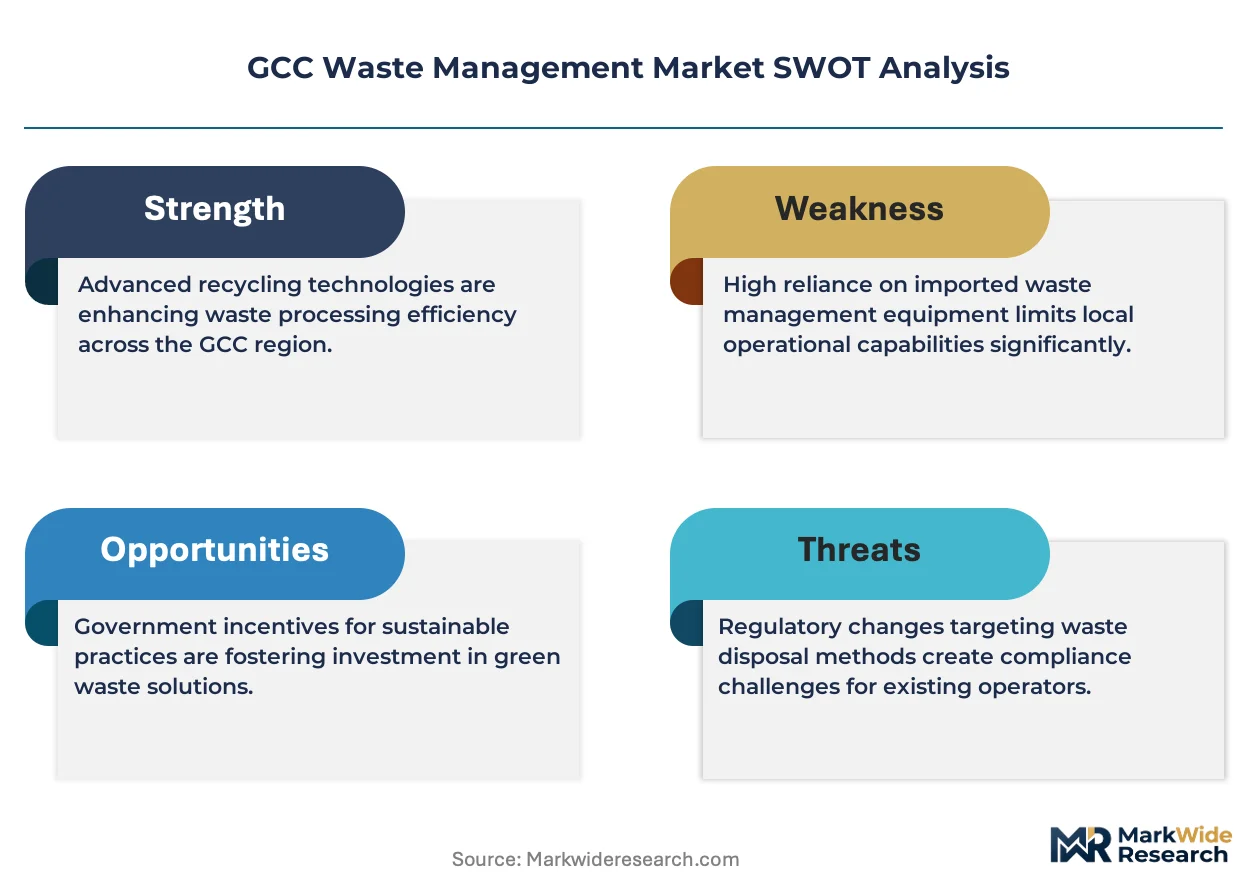
UAE Ministry of Climate Change and Environment procurement unbundling into discrete collection, transportation, and treatment lots is forcing suppliers to specialize rather than bundle, compressing margins on integrated services while creating premium capture opportunities for certified niche operators.
Pricing Analysis
Extended producer responsibility pilots in the UAE bundle compliance documentation with collection services, while Saudi Arabia's landfill diversion mandates unbundle treatment from transportation to accelerate competitive bidding. Three-tier pricing structure across premium certified-hazardous, standard municipal, and economy construction-debris levels stratifies the market. Price differentiation hinges on ISO 14001 environmental management certification and hazardous waste handling permits. Cost compression in standard municipal tiers is intensifying because emirate-level procurement clustering concentrates volume leverage with anchor operators. Industrial generators accepting premium pricing for specialized handling exhibit the lowest price sensitivity, while construction firms bidding aggregate recycling contracts show the highest.
Supply Chain Analysis
ISO 14001 and hazardous waste handling certifications gate supplier eligibility for Saudi Investment Recycling Company feedstock partnerships and UAE Ministry tenders, creating qualification backlogs that extend procurement timelines. Equipment manufacturing concentrates in Germany, Japan, and South Korea for combustion systems and emissions control technologies. Refractory materials for thermal processing chambers and specialized flue gas scrubbing chemicals constitute critical input dependencies. Single-source vulnerability runs through European refractory suppliers given limited Gulf domestic production. Distribution runs through EPC contractors and technology licensors who bundle engineering with long-term service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's National Center for Waste Management landfill diversion quotas function as a cost-of-compliance moat, elevating capital requirements for thermal processing investments and concentrating market access with operators possessing pre-qualified environmental permits.
For Market Incumbents: To counter emirate-level procurement fragmentation eroding integrated concession margins, anchor operators should deepen backward integration into feedstock sorting infrastructure and secure captive supply agreements with municipal authorities ahead of tender unbundling. Capacity addition in Bahrain and Qatar industrial zones captures per-capita generation premiums before competitor facility commissioning. For New Entrants and Emerging Players: AI-enabled route optimization platforms offer a digital-channel route to penetrate Saudi Arabia's municipal collection market without fleet ownership, licensing algorithms to Riyadh and Jeddah authorities seeking pilgrimage-period logistics flexibility. White-space concentration sits with hazardous waste treatment site development in Oman and Kuwait, where limited substitute disposal pathways extend logistics chains and concentrate pricing power for certified entrants. For Investors and Strategic Acquirers: The window for entry favors technology-integrated mid-cap specialists possessing AI sorting capabilities or gasification engineering expertise rather than pure-play logistics operators facing margin compression. Long-term viability across the analysis window rests on regulatory permit banks that accelerate project timelines versus greenfield applicants. The signal to watch is UAE Ministry of Climate Change and Environment extended producer responsibility mandate expansion beyond packaging into electronics and automotive waste streams.| Strategic Initiative | Industry Significance |
|---|---|
| Gasification Technology Licensing | Bahrain and Qatar industrial developers prioritize higher calorific extraction rates than conventional incineration permits. |
| Backward Integration into Feedstock Sorting | Saudi Investment Recycling Company upstream control over municipal streams anchors material recovery market position. |
| AI-Enabled Route Optimization Deployment | Riyadh and Jeddah municipalities deploy fill-level monitoring to eliminate static scheduling during pilgrimage peaks. |
| Hazardous Waste Treatment Site Development | Limited facility availability across Oman and Kuwait concentrates supply risk and extends logistics chains. |
| Extended Producer Responsibility Program Participation | UAE Ministry pilots shift liability upstream and open packaging waste recovery revenue pools. |
Research Methodology
Independent corroboration across municipal waste authority procurement officers, thermal processing plant engineers, hazardous waste certification auditors, and EPC contractor project managers underwrites the qualitative findings. Primary interviews with Bee'ah operations executives, Averda compliance leads, and Saudi Investment Recycling Company feedstock planners combined with secondary validation from customs trade data, National Center for Waste Management policy circulars, and SEC filings of listed environmental services firms. Bottom-up facility capacity tallies and top-down municipal budget allocation analysis triangulate market sizing.
Rate-of-change decomposition across waste type, service tier, processing technology, and end-user sector isolates volume and value drivers throughout the forecast period. Segmentation modeling incorporates waste stream composition variability, regulatory enforcement intensity by emirate, and technology maturation curves for gasification versus incineration. CAGRs derive from facility commissioning pipelines, procurement tender calendars, and feedstock availability projections without year-specific anchoring.
The model holds under sustained landfill diversion mandate enforcement and thermal processing capex availability; deviation in feedstock quality consistency or permitting timeline compression would shift capacity deployment schedules. Forecasts reflect assumptions regarding regulatory capacity keeping pace with project pipelines and specialized technician labor market development. A model refresh is warranted upon material change in Saudi Arabia's National Center for Waste Management enforcement intensity or UAE extended producer responsibility mandate scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Rare Earth Recycling Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Mining Waste Management Market