
 Global Waste Oil Market | 2026-2036
Global Waste Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Waste Oil Market Foresight
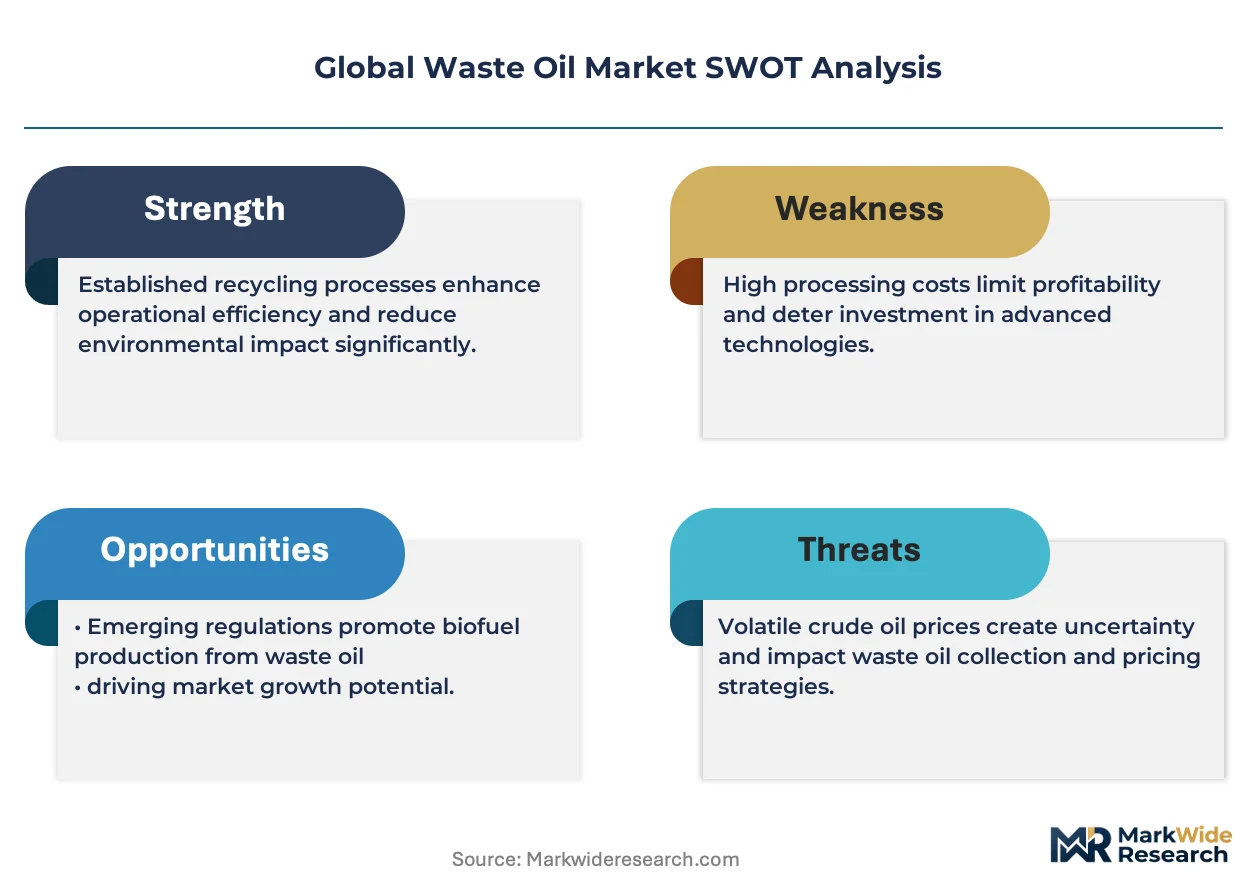
Certified hazardous waste technician availability is collapsing across North America and Western Europe, constraining collection network expansion and forcing automation investment. Safety-Kleen leverages its integrated collection and re-refining footprint to sustain national coverage in the United States. Veolia Environnement anchors European operations through licensed treatment facilities in France and Germany. Neste competes by converting waste oils into renewable fuels at its Singapore and Rotterdam refineries.
Waste oil comprises petroleum-based or synthetic lubricants degraded by thermal breakdown, oxidation, and contamination with metals, water, or particulates, typically requiring flash point testing and heavy metal analysis before processing. Its primary commercial purpose centers on feedstock recovery for base oil re-refining or fuel blending in industrial burners. Used engine oil dominates volume flows due to universal automotive and fleet consumption, while re-refining applications command premium margins against energy recovery alternatives. Mobile collection services are expanding fastest among logistics models, though drop-off centers retain cost advantages in dense urban corridors.
The EPA governs waste oil management under 40 CFR Part 279, mandating storage standards and tracking from generator to processor, while the EU Green Deal and REACH restrict hazardous substance release across member state recovery chains. OSHA and analogous national regulators enforce worker exposure limits during collection and handling, elevating compliance costs for manual operations. Stakeholders must monitor re-refining yield improvements and regional collection density gaps to determine facility siting and technology partnerships.
Market Dynamics
Re-refining yield improvements are compressing virgin base oil demand as hydrotreating and vacuum distillation technologies mature across European and North American processing facilities.
Growth Catalysts
- EU Green Deal circular economy mandates:Germany, France, and Italy now enforce extended producer responsibility frameworks that obligate lubricant manufacturers to finance collection infrastructure, accelerating licensed processor capacity expansion.
- Transportation fleet electrification residuals:Hybrid and electric vehicle powertrains still require thermal management fluids and gear lubricants, sustaining waste oil generation volumes even as combustion engine populations plateau.
- Industrial burner fuel substitution:Cement and lime kilns in Poland, Spain, and Mexico are retrofitting combustion systems to accept processed waste oil as a lower-carbon alternative to heavy fuel oil and petcoke.
Market Restraints
- Used oil generator fragmentation:The United States alone contains over 200,000 automotive repair shops and quick-lube facilities, creating collection logistics complexity and quality inconsistency that depresses re-refining feedstock premiums.
- Crude oil price volatility:Virgin base oil pricing from Group I and Group II refineries in the US Gulf Coast and Rotterdam directly caps re-refined product price ceilings, erasing margin during low crude cycles.
- Contaminant heterogeneity:Polyalphaolefin synthetic lubricants and biodegradable ester formulations resist conventional acid-clay and solvent extraction processes, requiring capital-intensive hydroprocessing upgrades.
Strategic Opportunities
- Southeast Asia collection infrastructure:Indonesia, Thailand, and Vietnam maintain minimal licensed waste oil recovery networks, presenting first-mover advantages for mobile collection service deployment and port-based aggregation hubs.
- Renewable diesel co-processing:Neste, World Energy, and Diamond Green Diesel facilities in California, Louisiana, and Rotterdam can hydrotreat waste oils alongside animal fats and used cooking oils, unlocking fuel pathway diversification.
- Blockchain provenance tracking:Integration of distributed ledger systems with EPA manifest requirements and EU waste shipment regulations enables real-time chain-of-custody verification that commands premium pricing from sustainability-linked procurement programs.
Industry Challenges
- Certified hazardous waste technician scarcity:OSHA 40-hour HAZWOPER training completion rates are declining across US metropolitan markets, forcing collection operators to automate drum handling and invest in remote monitoring systems.
- Re-refining capital intensity:Vacuum distillation and hydrotreating trains require 36-48 month construction timelines and specialized pressure vessel fabrication, exposing project sponsors to interest rate and construction cost escalation risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Waste Oil Market |
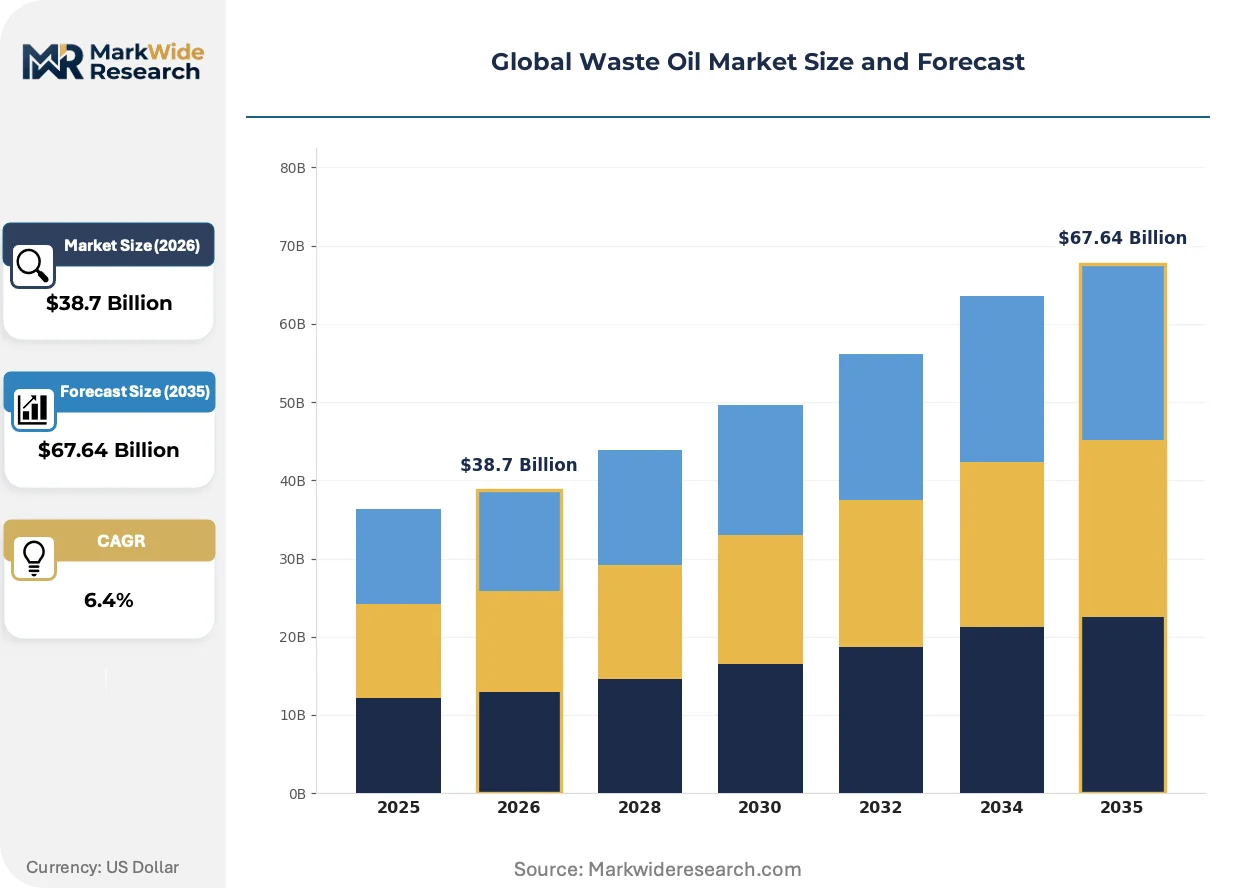
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Used Engine Oil, Hydraulic Oil, Gear Oil, Transformer Oil, Others Collection Method: Drop-off Centers, Mobile Collection, Pick-up Services, Onsite Collection Application: Re-refining, Energy Recovery, Metalworking, Lubrication, Road Construction End User: Manufacturing Plants, Transportation Operators, Mining Companies, Marine Vessels |
| Companies Covered | Safety-Kleen, Veolia Environnement, Neste, Clean Harbors, TotalEnergies, Darling Ingredients, Valero Energy Corporation, Repsol, Eni, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Waste Oil Market Shifts & Advancements
Digital logistics platforms and advanced separation chemistries are converging to transform waste oil from a compliance burden into a traceable, specification-grade feedstock stream.
Membrane filtration technology is miniaturizing. Ceramic and polymeric cross-flow systems now enable on-site dewatering and particulate removal at collection points, reducing transport costs and contamination penalties. Fleet maintenance depots in Germany and California are piloting containerized units that upgrade used oil to burner-fuel specification before highway shipment, compressing the traditional processor intermediary role.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in extender oils are tightening. The European Chemicals Agency's 2023 amendment lowers PAH limits in rubber and tire manufacturing inputs, forcing re-refiners to deploy more severe hydrotreating or solvent extraction to meet specification. German and Benelux base oil consumers are now requiring batch-specific analytical certificates, shifting procurement toward integrated collection-re-refining operators with in-house laboratory capabilities.
Certification-driven supplier consolidation is accelerating among automotive aftermarket buyers. Large fleet operators and national quick-lube chains are narrowing approved vendor lists to processors with R2 or e-Stewards electronics recycling credentials, even for purely petroleum-derived waste streams. This preference shift is most visible in US Midwest and Northeast metropolitan corridors, where municipal sustainability procurement policies cascade into private sector specifications.
Global Waste Oil Market Segmentation
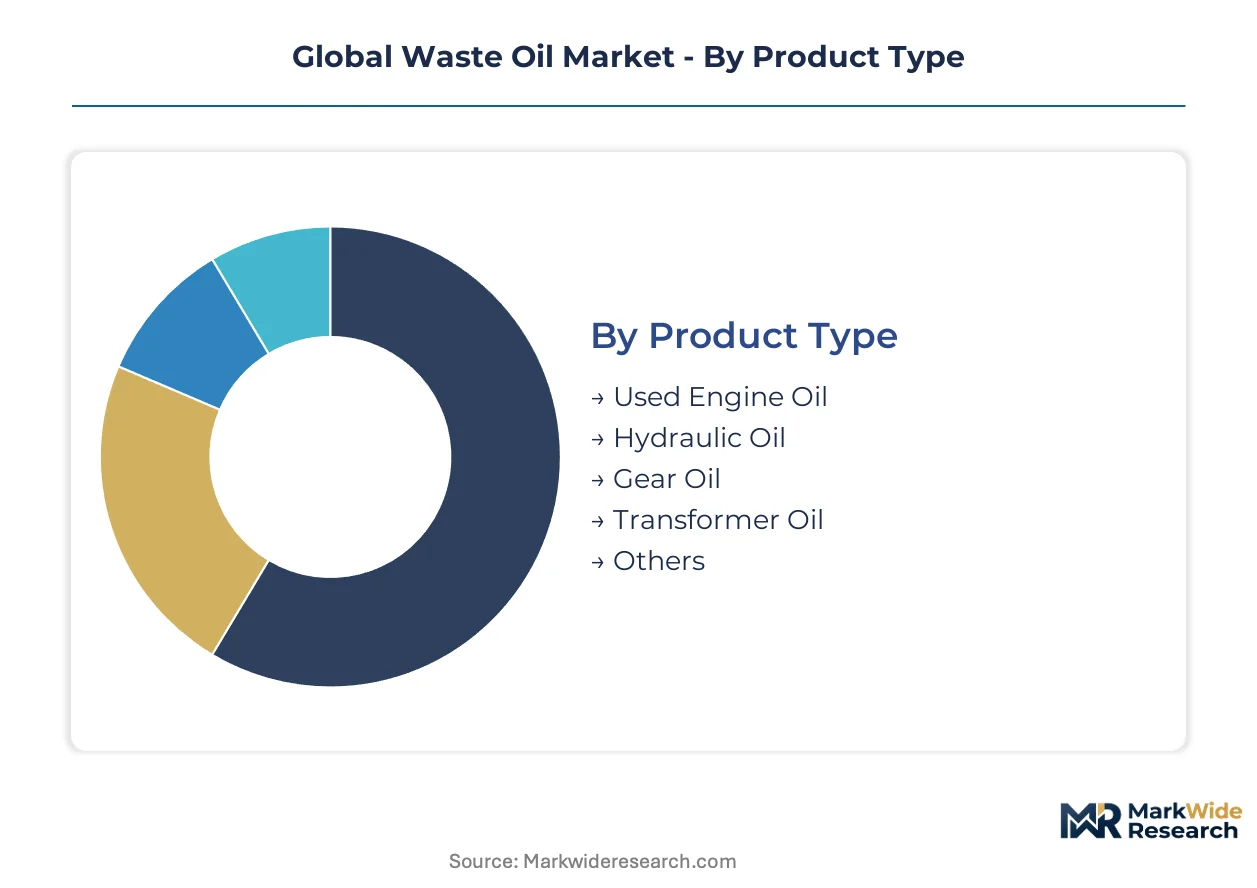
Waste oil market segmentation reveals how regulatory frameworks, logistics economics, and end-use specifications fragment value capture across the recovery chain. Understanding these divisions exposes where capital deployment yields superior returns.
Product Type:
EPA 40 CFR Part 279 and EU REACH impose divergent testing protocols on different oil chemistries, creating compliance cost tiers that reshape competitive positioning.
- Used Engine Oil:Degraded petroleum-based or synthetic lubricants contaminated with metals, water, and particulates from combustion engine operation. Automotive fleets and quick-lube networks in Germany and the United States generate the dominant volume flows, though generator fragmentation depresses feedstock premiums.
- Hydraulic Oil:Pressure-fluid formulations degraded by thermal breakdown and oxidation in industrial machinery. Manufacturing plants in the US Midwest and Benelux concentrate demand for recovery services, driven by OSHA exposure limits and extended producer responsibility mandates.
- Gear Oil:High-viscosity lubricants from transmission and differential systems.
- Transformer Oil:Dielectric fluids from electrical distribution infrastructure.
- Others:Cutting fluids, heat transfer oils, and specialty industrial lubricants.
Used Engine Oil handles the majority of throughput; Hydraulic Oil is expanding most quickly on share.
Collection Method:
Logistics cost structures and population density determine which models achieve unit economic viability across metropolitan versus rural geographies.
- Mobile Collection:Fleet-based drum retrieval services serving dispersed generators. Indonesia, Thailand, and Vietnam present first-mover advantages as licensed recovery networks remain minimal.
- Drop-off Centers:Fixed aggregation points in dense urban corridors. California and Germany retain cost advantages through high generator concentration and municipal sustainability procurement policies.
- Pick-up Services:Scheduled collection for high-volume industrial accounts.
- Onsite Collection:Containerized systems at fleet maintenance depots and manufacturing facilities.
Drop-off Centers handle the majority of throughput; Mobile Collection is gaining share fastest.
Application:
Yield differentials and specification requirements separate premium feedstock pathways from commodity fuel blending alternatives.
- Re-refining:Hydrotreating and vacuum distillation to recover Group I and Group II base oils. EU Green Deal circular economy mandates in Germany, France, and Italy obligate lubricant manufacturers to finance collection infrastructure.
- Energy Recovery:Processed waste oil combustion in industrial burners. Cement and lime kilns in Poland, Spain, and Mexico are retrofitting systems to accept lower-carbon alternatives to heavy fuel oil.
- Metalworking:Direct reuse or regeneration in machining operations.
- Lubrication:Lower-specification reuse in non-critical machinery.
- Road Construction:Binder applications in asphalt and bitumen formulations.
Re-refining handles the majority of throughput; Energy Recovery is climbing the fastest on share.
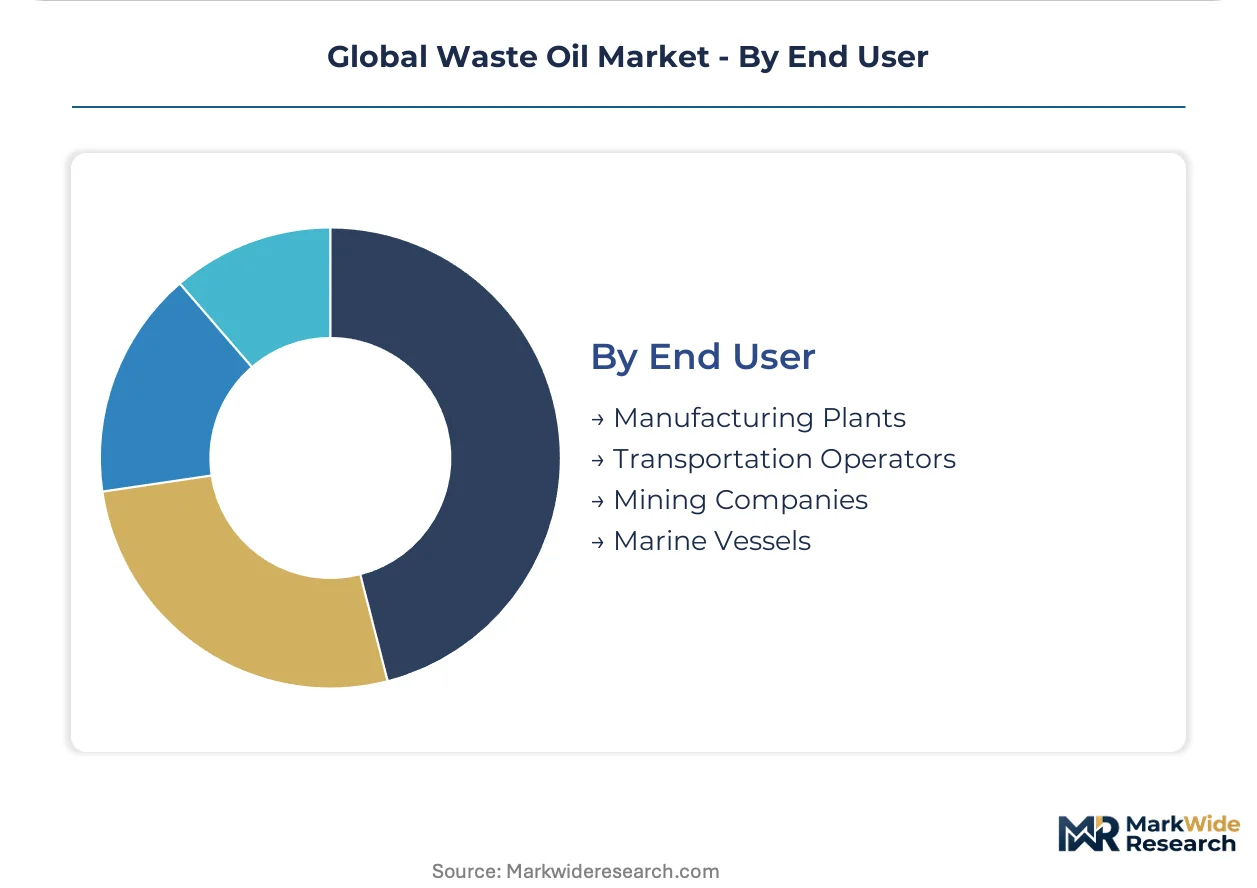
End User:
Generator scale and location concentration dictate whether integrated collection-re-refining operators or specialized logistics providers capture the value chain margin.
- Transportation Operators:Commercial fleets and automotive service chains generating predictable waste oil volumes. National quick-lube chains in the US Midwest and Northeast are narrowing approved vendor lists to processors with R2 or e-Stewards credentials.
- Manufacturing Plants:Industrial facilities with continuous lubricant consumption. German industrial re-refining capacity and circular economy mandates are accelerating collection infrastructure investment.
- Mining Companies:Remote extraction operations with high-volume, intermittent generation patterns.
- Marine Vessels:International shipping subject to MARPOL and port state control regulations.
Transportation Operators handle the majority of throughput; Manufacturing Plants are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for re-refined base oils while Indonesia operates at thin margins due to collection infrastructure gaps. This asymmetry reflects divergent regulatory maturity and circular economy policy enforcement across markets.
United States
Commercial fleet electrification sustains thermal fluid and gear lubricant waste streams even as combustion engine populations plateau. EPA 40 CFR Part 279 mandates generator-to-processor tracking that elevates compliance costs for fragmented automotive repair networks. The US Midwest and Northeast metropolitan corridors concentrate quick-lube chain demand where municipal sustainability procurement narrows approved vendor lists.
Germany
Industrial re-refining capacity and circular economy mandates accelerate collection infrastructure investment across lubricant manufacturing clusters. EU Green Deal extended producer responsibility frameworks obligate manufacturers to finance recovery networks. The Benelux-connected Rhine-Ruhr industrial corridor hosts licensed treatment facilities where batch-specific analytical certificates now dominate procurement specifications.
China
Manufacturing plant lubricant consumption generates continuous hydraulic and cutting fluid waste volumes across industrial machinery hubs. The country's national environmental regulator enforces dual carbon goals that tighten disposal standards for metalworking operations. The Yangtze River Delta manufacturing belt concentrates demand for on-site dewatering containerization pilots that compress traditional processor intermediary roles.
Indonesia
Minimal licensed recovery networks create first-mover advantages for mobile collection service deployment across dispersed generator geographies. The country's national environmental ministry maintains nascent hazardous waste tracking systems that lag EU implementation timelines. Java-based port aggregation hubs attract regional logistics investment seeking to capture feedstock flows from Thailand and Vietnam.
Poland
Cement and lime kiln retrofitting to processed waste oil combustion drives energy recovery application demand as heavy fuel oil substitution accelerates. REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons filter into national implementation through the European Chemicals Agency amendment framework. Silesian industrial clusters host burner-fuel specification upgrading facilities serving cross-border Central European markets.
Global Waste Oil Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the waste oil recovery chain. Integrated collection-re-refining operators sustain national coverage through licensed treatment infrastructure and laboratory certification capabilities. The market structure fragments between mobile logistics specialists, fixed-facility processors, and renewable fuel converters. Three archetypes dominate: circular-economy-integrated operators, port-based aggregation specialists, and hydrotreating technology licensors. Competitive moves concentrate on strategic partnerships for collection density and technology licensing for yield improvement.
Within the integrated operator tier, Safety-Kleen and Veolia Environnement exemplify archetypes spanning collection logistics through re-refining. Neste occupies a position representing renewable fuel pathway diversification through hydrotreating co-processing. These three anchors demonstrate how geographic footprint breadth and technology integration depth separate premium feedstock capture from commodity energy recovery positioning.
| Leading Market Players |
|---|
| Safety-Kleen |
| Veolia Environnement |
| Neste |
| Clean Harbors |
| TotalEnergies |
| Darling Ingredients |
| Valero Energy Corporation |
| Repsol |
| Eni |
| Others |
Supply & Pricing Matrix
EU REACH Annex XVII polycyclic aromatic hydrocarbon limits and EPA 40 CFR Part 279 tracking mandates simultaneously gate processor licensing and stratify feedstock premiums across the recovery chain. Certification tiers separate integrated collection-re-refining operators from commodity energy recovery processors, compressing margins for uncertified intermediaries while rewarding laboratory-backed batch verification.
Pricing Analysis
Germany commands premium spreads over Indonesia by three-to-one ratios on re-refined base oil quotations. Three-tier pricing structure across R2-certified premium, standard licensed, and unverified economy grades anchors procurement decisions by automotive fleet operators. Cost compression in the economy tier is intensifying because crude-linked virgin base oil pricing caps re-refined product ceilings. National quick-lube chains exhibit lowest price sensitivity, while fragmented automotive repair shops in the United States drive spot-market volatility.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and Rhine River low-water disruptions elevate feedstock delivery expenses to German re-refining clusters. Supply concentrates in Germany, the United States, and Singapore, where licensed treatment infrastructure and renewable fuel co-processing capacity anchor value capture. Raw material flows draw from petroleum-based lubricants, synthetic polyalphaolefin formulations, and biodegradable ester chemistries. Single-source vulnerability concentrates in specialized hydrotreating catalyst supply. Distribution runs through mobile collection fleets, port-based aggregation hubs, and fixed-facility drop-off networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal circular economy mandates and hydrotreating yield improvements are disrupting competitive positioning across waste oil recovery, compressing timelines for technology deployment and collection density capture.
For Market Incumbents: Shield re-refining margins by accelerating backward integration into mobile collection networks across the US Midwest and Northeast corridors. Invest in automated drum handling systems to offset OSHA 40-hour HAZWOPER technician scarcity. Defend against renewable fuel co-processing entrants by securing long-term offtake agreements with national quick-lube chains requiring R2 certification. For New Entrants and Emerging Players: R2 or e-Stewards certification fast-track unlocks approved vendor status with municipal sustainability procurement programs in California and Germany. Target Indonesia, Thailand, and Vietnam for mobile collection service deployment where licensed recovery networks remain minimal. Pursue port-based aggregation hub partnerships to capture Southeast Asian feedstock flows before incumbent integrated operators establish beachheads. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrotreating and vacuum distillation capacity additions, extending construction timelines and elevating project finance risk premiums. Prioritize acquisition targets with existing licensed treatment infrastructure and in-house laboratory certification capabilities rather than greenfield development exposure. Monitor re-refining yield improvement announcements as the primary signal for feedstock premium compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captures feedstock premiums by controlling drum retrieval logistics across fragmented generator bases in the United States. |
| Hydrotreating Technology Licensing | Enables renewable diesel co-processing at Neste and Diamond Green Diesel facilities in Rotterdam and California. |
| Blockchain Provenance Tracking Deployment | Integrates distributed ledger systems with EPA manifest requirements for real-time chain-of-custody verification. |
| Mobile Collection Fleet Expansion | Addresses generator fragmentation across Indonesia, Thailand, and Vietnam where fixed infrastructure remains underdeveloped. |
| Automated Drum Handling Investment | Offsets certified hazardous waste technician scarcity through OSHA-compliant remote monitoring and robotic retrieval systems. |
Research Methodology
Desk research of EPA enforcement databases, EU waste shipment registries, and re-refining capacity disclosures preceded structured interviews with collection fleet operators, licensed treatment facility managers, lubricant manufacturer sustainability officers, and automotive fleet procurement directors. Secondary validation drew from customs trade data, SEC 10-K filings by integrated energy companies, and national environmental ministry hazardous waste tracking reports. Bottom-up generator volume estimates triangulated against top-down re-refining capacity utilization rates across Germany, the United States, and Singapore.
Variance decomposition across product type, collection method, application pathway, and end-user segment anchored the analytical framework over the projection horizon. Modeled dimensions included used engine oil versus hydraulic oil chemistries, mobile collection versus drop-off center logistics, re-refining versus energy recovery applications, and transportation operator versus manufacturing plant demand. CAGRs were derived from segment-level volume projections weighted by regional regulatory enforcement intensity and technology penetration curves.
Underlying assumptions cover sustained EU Green Deal implementation timelines and EPA enforcement continuity, with deviation risk concentrated in crude oil price volatility and hydrotreating catalyst supply disruptions. Forecasts reflect these documented conditions with explicit scenario boundaries. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Europe Waste Management Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
Recycled Ocean Plastics Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Trash Rakes Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
Waste Sorting Equipment Market
Waste Management & Pollution Control
India Municipal Solid Waste Management Market