
 Griddle Market | 2026-2036
Griddle Market Size, Share, and Industry Trends Forecast 2026-2036
Griddle Market Analytics
Commercial kitchen technician shortages across major foodservice hubs is reorganizing how operators source griddle equipment and maintenance contracts. AB Electrolux leverages its European service network to capture aftermarket revenue from high-volume restaurant clients. The Middleby Corp. sustains dominance in the premium commercial segment through captive distribution to chain accounts. Blackstone anchors the outdoor and residential griddle category with direct-to-consumer channel control and seasonal product positioning.
A griddle is a flat metal cooking surface, typically constructed from cold-rolled steel, cast iron, or chromium-plated composite, heated by gas burners, electric elements, or induction coils to temperatures between 150°C and 300°C for simultaneous batch cooking of proteins, starches, and breakfast items. Gas griddles retain the largest installed base in legacy commercial kitchens, though induction griddles are gaining share where electricity costs and ventilation constraints favor zero-combustion operation. Electric griddles occupy the mid-market for catering services and food trucks requiring portable, code-compliant equipment without gas line dependencies. Non-stick griddles differentiate through reduced oil usage and faster cleaning cycles, appealing to health-focused household buyers and high-turnover restaurant concepts.
FDA food-contact surface regulations and NSF International sanitation standards govern commercial griddle materials and cleanability requirements in the United States, while CE marking and EU Ecodesign directives shape efficiency thresholds for electric units sold across European markets. ETL and UL safety certifications function as gatekeeping mechanisms for market access, particularly for induction models with complex electromagnetic components. Stakeholders must monitor evolving energy efficiency mandates and electrification incentives, as these policy levers will increasingly determine which heating technologies operators can justify in new construction and retrofit decisions.
Market Dynamics
Electrification mandates across commercial building codes are compressing replacement cycles for gas-fired kitchen equipment, forcing operators to pre-emptively retire functional assets before end-of-life. This regulatory pressure is redistributing capital allocation across foodservice chains and independent operators alike.
Growth Catalysts
- Commercial kitchen electrification incentives:The US Inflation Reduction Act allocates tax credits for zero-emission cooking equipment retrofits, accelerating induction griddle adoption in full-service restaurants and hotel kitchens.
- Food truck regulatory compliance:Municipal fire codes in dense urban centers increasingly prohibit propane storage on mobile food units, pushing operators toward electric griddle configurations with onboard battery systems.
- Cast iron surface innovations:Advanced chromium-plated composites with embedded heating elements reduce thermal recovery time by half, enabling higher throughput for breakfast-focused quick-service chains.
Market Restraints
- Copper and nickel price volatility:Induction coil manufacturing depends on concentrated supply from Chilean and Indonesian mining operations, creating input cost instability for electric griddle producers.
- Ventilation infrastructure lock-in:Legacy commercial kitchens carry sunk costs in gas-rated hood systems that require complete replacement to accommodate induction equipment, extending payback periods.
- Commercial combi-oven substitution:Multi-function cooking equipment with griddle plates captures floor space-constrained operators seeking single-unit versatility over dedicated flat-top surfaces.
Strategic Opportunities
- Ghost kitchen electrification:Delivery-only food facilities in the United States prioritize compact, ventless induction griddles to minimize real estate costs and eliminate ductwork requirements.
- EU Ecodesign directive expansion:Pending efficiency thresholds for commercial cooking equipment will disqualify low-performance gas models, creating replacement demand across German, French, and Italian foodservice markets.
- Cloud-connected maintenance:IoT-enabled griddles with predictive diagnostics allow manufacturers to capture recurring service revenue through subscription-based uptime guarantees.
Industry Challenges
- Commercial kitchen technician scarcity:Electromagnetic induction systems require specialized repair skills that vocational programs have not scaled to match equipment deployment rates.
- NSF certification timeline compression:Accelerated product development cycles strain third-party testing capacity, delaying market entry for new griddle configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Griddle Market |
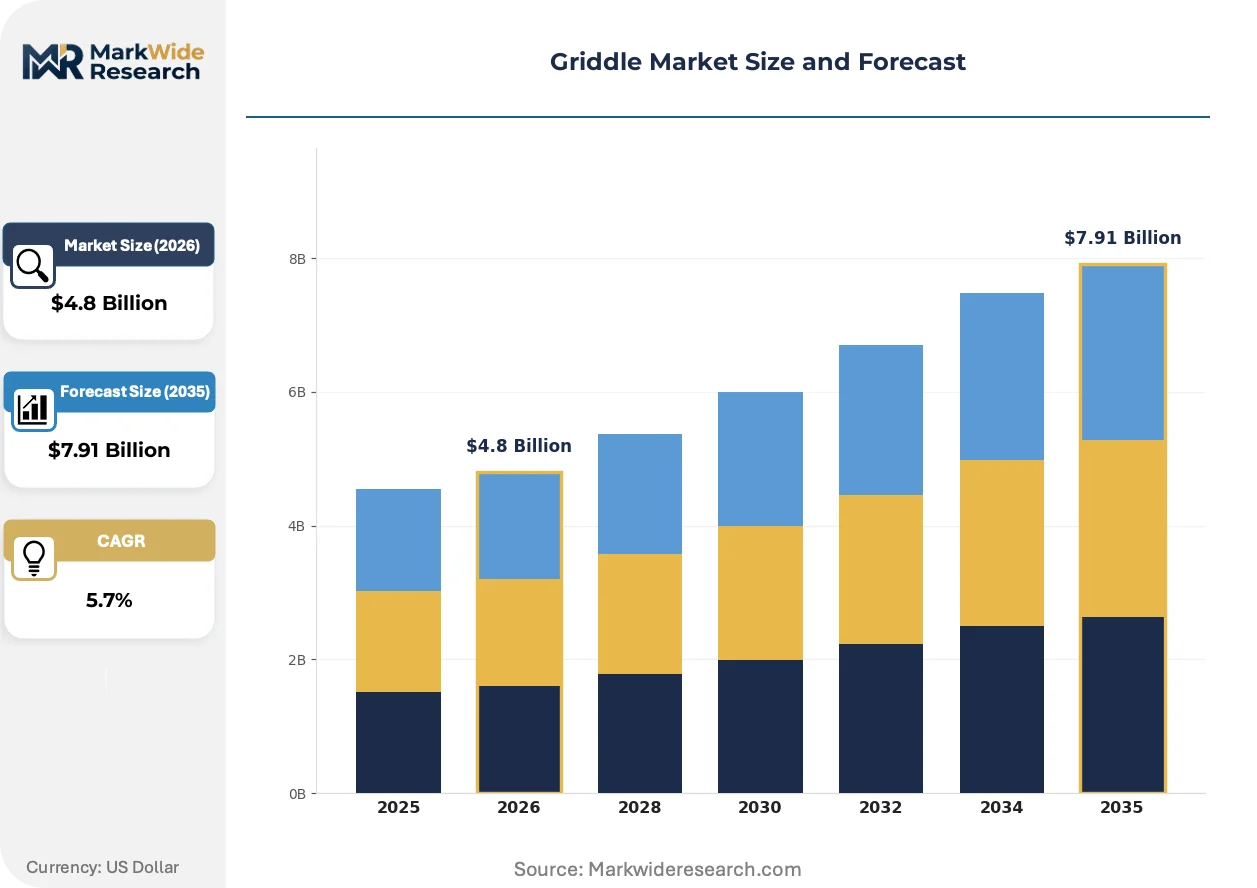
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Griddles, Gas Griddles, Induction Griddles, Non-Stick Griddles End User: Households, Restaurants, Catering Services, Food Trucks Heating Source: Electric, Gas, Charcoal, Wood Size: Compact, Standard, Large, Extra Large |
| Companies Covered | AB Electrolux, AccuTemp Products Inc., Ali Group Srl, The Middleby Corp., The Vollrath Co. LLC, Hatco Corp., Illinois Tool Works Inc., Blackstone, Traeger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Griddle Market Evolving Landscape
Griddle equipment is converging with building energy management systems and predictive maintenance platforms, transforming standalone cooking assets into networked infrastructure components. This connectivity shift is redefining vendor-customer relationships and value capture mechanisms.
Induction coil arrays with segmented temperature zones are miniaturizing control electronics into modular cartridges that slot beneath standard countertop cutouts. Catering operators and food truck proprietors are adopting these drop-in units to replace portable gas griddles without kitchen redesign. The technology is miniaturizing equipment footprints while preserving cooking surface area, enabling high-output operations in sub-200-square-foot facilities.
REACH chemical restrictions in the European Union are phasing out certain non-stick coating formulations used on consumer griddles, compelling manufacturers to reformulate surfaces with ceramic-based alternatives. Industrial consequence includes extended product development cycles and retooling costs for coating applicators. Residential griddle producers serving German and French markets are responding with pre-emptive coating transitions ahead of enforcement deadlines.
Chain restaurant procurement teams are consolidating vendor relationships into single-source agreements covering equipment, installation, and multi-year service contracts. Independent distributors lose access to large accounts as captive distribution networks tighten. This concentration is most visible in the United States, where top-50 quick-service chains now specify approved vendor lists that exclude regional equipment dealers.
Griddle Market Segmentation
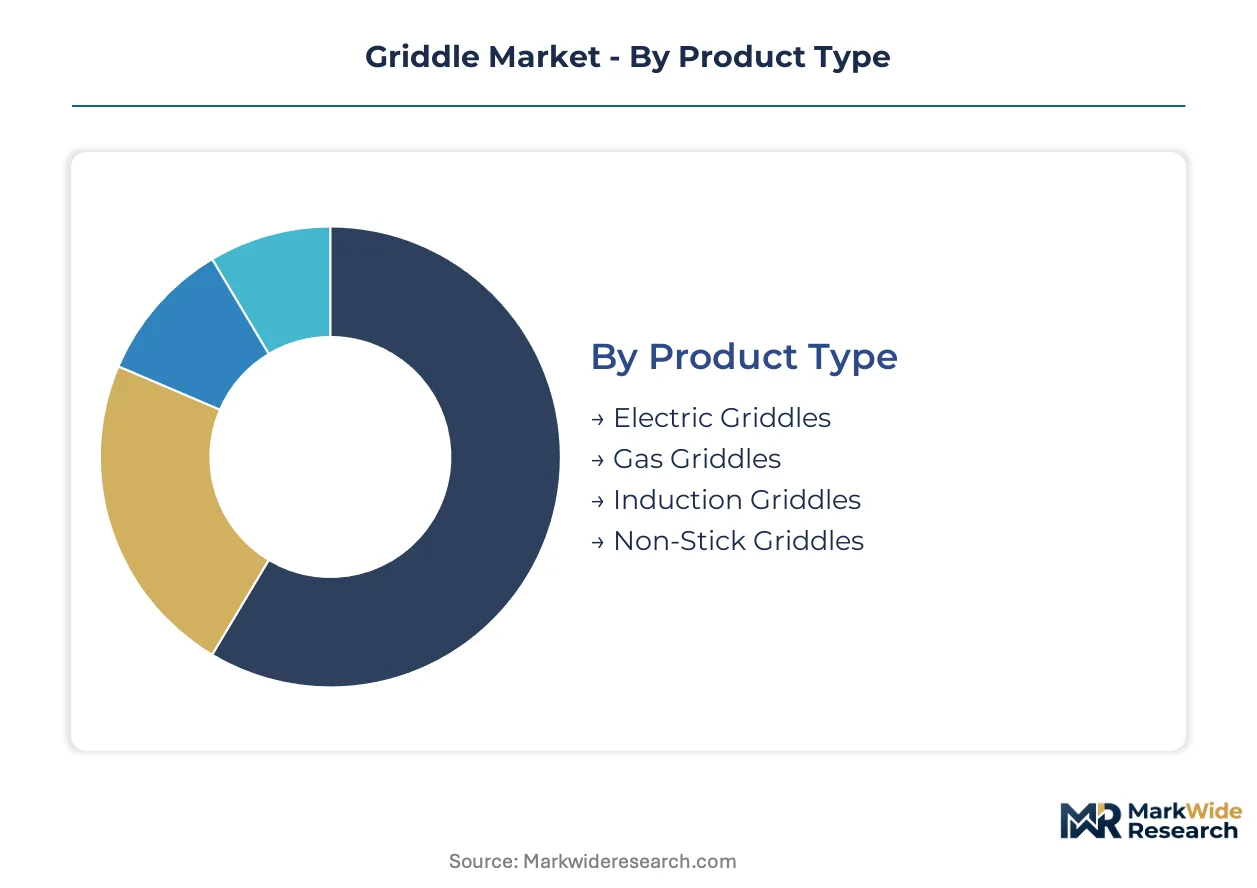
Griddle purchasing decisions split sharply between commercial operators optimizing throughput per square foot and residential buyers prioritizing storage convenience. Equipment specifications diverge across heating technologies, creating distinct margin architectures that reward specialized manufacturers over generalists.
Product Type:
Margin pools concentrate in electrified equipment where NSF certification complexity and IoT integration create pricing power unavailable to legacy gas fabricators.
- Electric Griddles:Resistance-element heating systems with embedded thermostats deliver temperature stability within 5°C variance. Demand clusters in United States catering operations and food trucks where municipal fire codes restrict propane storage. Compact countertop configurations dominate this channel.
- Gas Griddles:Cast iron or cold-rolled steel surfaces heated by atmospheric or infrared burners retain the largest installed base in legacy full-service restaurants. Replacement cycles are compressing as electrification mandates in California, New York, and Washington State accelerate pre-emptive retirements.
- Induction Griddles:Electromagnetic coil arrays beneath ceramic or composite surfaces enable instant thermal response and zone-level control. Ghost kitchens and hotel breakfast operations in Chicago, Miami, and Austin are standardizing on ventless configurations.
- Non-Stick Griddles:Ceramic or polymer-coated surfaces target residential buyers seeking reduced oil usage. REACH chemical restrictions are forcing coating reformulations for European market access.
The dominant share belongs to Gas Griddles, while Induction Griddles is closing the gap fastest.
End User:
Application context determines equipment durability specifications and service contract structures more than purchase price alone.
- Households:Countertop electric units with 1,500-2,000 watt draw and detachable grease trays. United States suburban buyers favor 22-inch surfaces for weekend breakfast preparation.
- Restaurants:Heavy-duty steel plate construction with recovery times under 90 seconds. Quick-service breakfast chains in Texas and Florida drive specification standardization across franchise networks.
- Catering Services:Portable electric griddles with folding legs and NSF-listed components. Operators in Atlanta and Philadelphia prioritize equipment mobility between event venues.
- Food Trucks:Battery-compatible induction systems eliminating propane tank storage. Los Angeles, Seattle, and Portland municipal codes are accelerating this transition.
Restaurants command the largest equipment expenditure, though Food Trucks are expanding most quickly as regulatory pressure mounts.
Heating Source:
Energy infrastructure availability and operating cost structures create geographic concentration patterns for each fuel type.
- Electric:Grid-dependent operation suits fixed installations with predictable load profiles. Northeastern United States operators facing volatile natural gas pricing are standardizing here.
- Gas:Propane or natural gas burners deliver highest Btu output for high-volume protein cooking. Independent steakhouses in Houston and Dallas maintain this preference.
- Charcoal:Lump or briquette combustion for outdoor residential use and specialty barbecue concepts. Limited commercial penetration outside Kansas City and Memphis regional styles.
- Wood:Hardwood-fueled surfaces for smoke-integrated flavor profiles. Niche adoption in Portland and Austin farm-to-table establishments.
Electric heating holds the widest addressable market, with Gas retaining share in legacy infrastructure corridors.
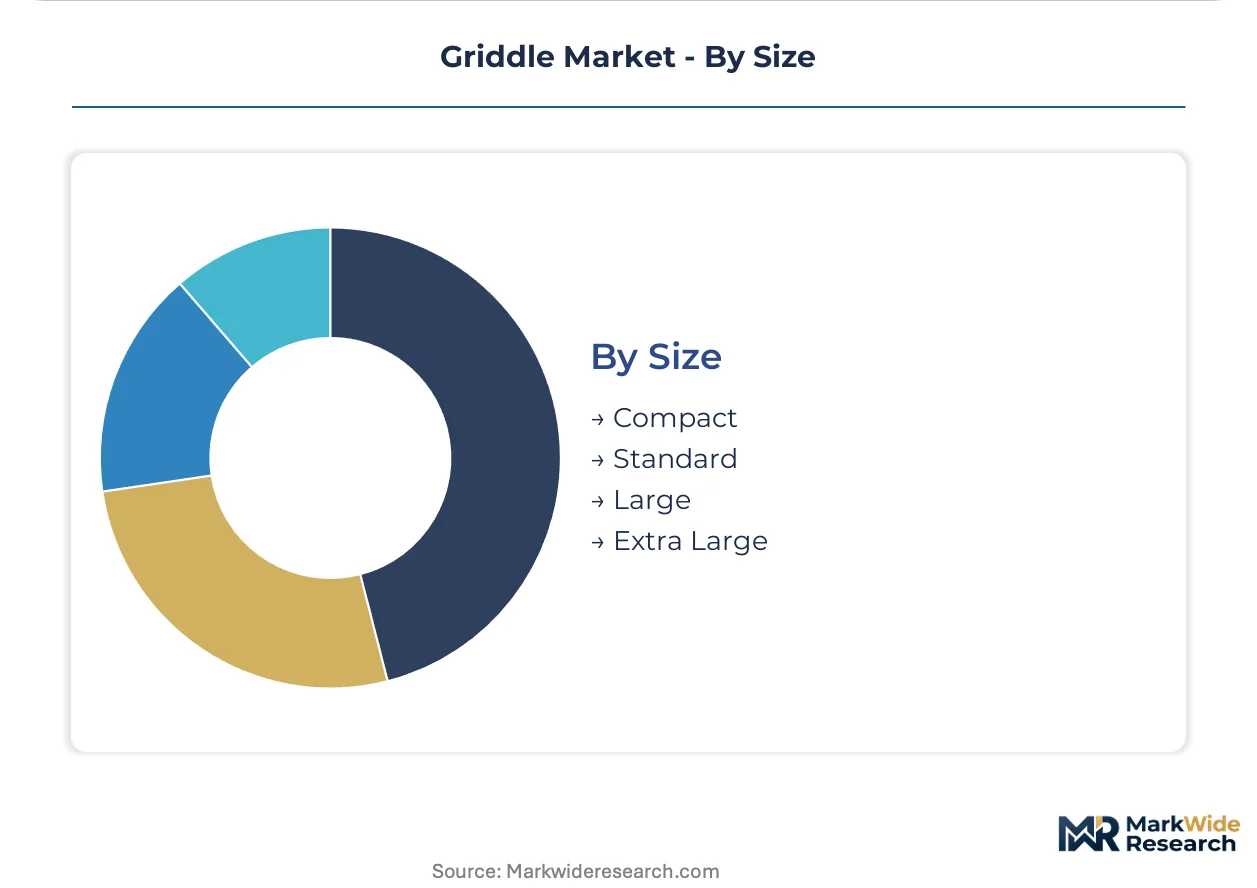
Size:
Real estate constraints and batch volume requirements create distinct specification tiers with minimal crossover purchasing.
- Compact:Under 24-inch cooking surfaces for residential kitchens and food trucks under 150 square feet. Battery-powered induction variants are gaining specification in mobile applications.
- Standard:24-36 inch widths serving independent restaurants and catering operations. This tier faces greatest substitution pressure from combi-oven versatility.
- Large:36-48 inch surfaces for high-volume breakfast chains and hotel buffet lines. Thermal recovery engineering separates premium from commodity offerings.
- Extra Large:Custom-configured modular systems exceeding 60 inches for casino and stadium commissaries. Made-to-order fabrication extends lead times to 16-20 weeks.
Standard sizes maintain volume leadership, though Compact configurations are climbing the fastest as ghost kitchen real estate costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact surface regulations and NSF International sanitation standards anchor equipment procurement in the United States, where quick-service restaurant expansion and food truck proliferation concentrate replacement demand. The analysis spans five national markets where electrification mandates and commercial kitchen infrastructure shape griddle specification patterns.
United States
California, New York, and Washington State electrification mandates compress replacement cycles for gas-fired kitchen equipment, forcing pre-emptive retirements. The US Inflation Reduction Act allocates tax credits for zero-emission cooking equipment retrofits, accelerating induction griddle adoption in full-service restaurants and hotel kitchens. Chicago, Miami, and Austin ghost kitchens standardize on ventless induction configurations to minimize real estate costs.
Germany
Pending EU Ecodesign directive expansion will disqualify low-performance gas models, creating replacement demand across German foodservice markets. REACH chemical restrictions phase out certain non-stick coating formulations, compelling manufacturers to reformulate surfaces with ceramic-based alternatives. Industrial clusters in Bavaria and North Rhine-Westphalia face extended product development cycles and retooling costs for coating applicators.
France
CE marking and EU Ecodesign directives shape efficiency thresholds for electric units sold across French markets. Residential griddle producers serving German and French markets respond with pre-emptive coating transitions ahead of enforcement deadlines. The Île-de-France region concentrates catering operations and hotel breakfast facilities driving compact electric griddle specification.
United Kingdom
Commercial kitchen technician shortages reorganize how operators source griddle equipment and maintenance contracts. NSF certification timeline compression strains third-party testing capacity, delaying market entry for new griddle configurations. London and Southeast England food truck operators face municipal fire codes increasingly prohibiting propane storage on mobile food units.
Japan
METI efficiency standards and JIS certification requirements govern commercial griddle materials and cleanability specifications. Compact countertop induction configurations suit fixed installations with predictable load profiles in dense urban foodservice environments. The Kanto/Tokyo region concentrates high-turnover restaurant concepts prioritizing thermal recovery engineering for breakfast-focused operations.
Griddle Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the griddle market. Electromagnetic induction systems and IoT-enabled predictive diagnostics define premium positioning, while gas-fired fabrication and standardized steel plate construction anchor commodity tiers. Three archetypes dominate: European service-network operators capturing aftermarket revenue, North American direct-to-consumer brands controlling seasonal residential positioning, and diversified industrial conglomerates with captive distribution to chain accounts. Consolidation pressures intensify as single-source vendor agreements displace independent distributors, while capacity expansion in induction coil manufacturing and strategic partnerships for battery-compatible mobile systems emerge as dominant competitive moves.
Among diversified industrial groups, AB Electrolux leverages European service infrastructure for recurring maintenance revenue, while The Middleby Corp. occupies a position within premium commercial segments through chain account relationships. Blackstone anchors the outdoor and residential category with direct channel control. These three exemplify how geographic origin and company structure shape competitive archetype positioning without requiring uniform strategic approaches across heating technologies or end-use segments.
| Leading Market Players |
|---|
| AB Electrolux |
| AccuTemp Products Inc. |
| Ali Group Srl |
| The Middleby Corp. |
| The Vollrath Co. LLC |
| Hatco Corp. |
| Illinois Tool Works Inc. |
| Blackstone |
| Traeger |
| Others |
Value Network & Pricing Analysis
NSF International sanitation standards gate both supply qualification and price differentiation simultaneously, compelling manufacturers to absorb certification costs that stratify equipment tiers while excluding uncertified fabricators from commercial procurement channels entirely. Electrolux and Middleby leverage these compliance barriers to sustain premium positioning against commodity gas-griddle producers lacking third-party validation.
Pricing Analysis
United States pricing for induction griddles runs 40-60% above equivalent gas configurations, with California and New York operators absorbing steeper premiums due to electrification mandate compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels separates IoT-enabled predictive maintenance bundles from basic NSF-listed units and uncertified imports. Cost compression in mid-market electric griddles is intensifying because induction coil manufacturers face copper and nickel price volatility from Chilean and Indonesian supply concentration. Independent restaurants and food truck operators exhibit highest price sensitivity, while casino commissaries and chain hotel groups prioritize thermal recovery specifications over unit cost.
Supply Chain Analysis
Port congestion along Shanghai-to-Long Beach lanes elevates inbound logistics costs for chromium-plated steel surfaces and ceramic coating inputs sourced from East Asian applicators. Induction coil manufacturing draws from concentrated Chilean copper and Indonesian nickel mining operations, while cold-rolled steel plate fabrication centers on United States, Germany, and China production hubs. Single-source vulnerability pervades electromagnetic component supply, where Japanese and German semiconductor fabricators control IGBT transistor availability for precision temperature control modules. Distribution runs through captive dealer networks for chain accounts and independent foodservice equipment distributors serving fragmented restaurant operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits defensive moats rooted in regulatory entrenchment, where NSF certification timelines and electromagnetic repair skill scarcity protect incumbent positions against price-based disruption.
For Market Incumbents: Consolidate aftermarket service revenue through predictive diagnostics subscriptions that capture maintenance spend from technician-scarce operators facing induction system complexity. Add capacity in battery-compatible induction configurations for food truck electrification mandates spreading across Los Angeles, Seattle, and Portland municipal codes. Vertical integration into ceramic coating applicators mitigates REACH-driven reformulation risks for European market access. For New Entrants and Emerging Players: NSF certification fast-track partnerships with third-party testing laboratories compress market entry timelines for ghost kitchen ventless induction configurations. Target United States food truck segments where propane prohibition ordinances create replacement demand without entrenched incumbent relationships. Pursue direct-to-catering-operator digital channels bypassing consolidated chain procurement gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-connected griddle sub-segments as IoT platform development costs amortize across installed bases. Five-to-ten year viability favors manufacturers with captive service networks and induction coil supply agreements rather than pure-play fabricators. Monitor municipal electrification ordinance adoption velocity as inflection indicator for induction equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Predictive maintenance subscriptions capture recurring revenue from AB Electrolux's European service infrastructure. |
| Induction Capacity Expansion | Battery-compatible coil manufacturing addresses Los Angeles and Seattle food truck electrification mandates. |
| Ceramic Coating Transition | REACH-compliant surface reformulation secures German and French residential market access ahead of enforcement. |
| Captive Distribution Consolidation | Single-source vendor agreements with top-50 quick-service chains displace independent equipment dealers. |
| Ghost Kitchen Partnership | Ventless induction specifications minimize real estate costs for Chicago and Miami delivery-only facilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC equipment manufacturer filings, NSF certification registries, and municipal fire code ordinance databases. Interviews with commercial kitchen maintenance directors, chain restaurant procurement managers, food truck operators, and electromagnetic component distributors informed demand-side validation. Customs trade data for steel plate and copper coil imports, combined with ETL and UL safety certification records, anchored supply-side triangulation through bottom-up equipment shipment analysis and top-down foodservice operator expenditure estimation.
Segmentation dimensions modeled span heating technology, end-user application, equipment size tier, and regional regulatory cluster across the projection horizon. CAGRs derive from equipment replacement cycle analysis, electrification mandate adoption curves, and food truck fleet expansion patterns. Forecast inputs incorporate induction coil cost trajectories, REACH chemical restriction implementation schedules, and ghost kitchen real estate development permits.
The analysis sits within stated boundaries; outcomes outside sustained electrification incentive funding and stable copper-nickel supply conditions would require recalibration. Forecasts reflect assumptions regarding technician training program scaling and third-party certification capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
Spray Drying Equipment Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Beer Brewing Equipment Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Food Waste Disposal Equipment Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Brewery Equipment Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Automatic Fish Scaling Machine Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market