
 Commercial Beverage Dispenser Market | 2026-2036
Commercial Beverage Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Beverage Dispenser Market Analysis
The widening gap between stainless-steel premium dispensers and entry-level plastic units is repositioning procurement strategies across foodservice chains. BUNN-O-Matic Corporation leverages its domestic manufacturing footprint to sustain rapid-turn customization for regional operators. Hoshizaki Corporation anchors its position through ice-making integration that reduces countertop footprint in compact kitchen layouts. Cornelius differentiates via proprietary carbonation systems that extend beverage consistency across high-volume entertainment venues.
Commercial beverage dispensers are electromechanical serving systems engineered to store, chill, carbonate, and dispense prepared drinks at controlled temperatures and flow rates, typically operating between 34°F and 40°F with NSF-certified food-contact surfaces. Their primary purpose is to reduce per-serve labor while maintaining portion consistency and sanitation compliance in high-traffic foodservice environments. Coffee dispensers occupy the fastest-expanding margin pool as specialty café formats proliferate, while carbonated drink dispensers retain the largest installed base tied to quick-service fountain contracts. Freestanding models lead in hotels and entertainment venues where floor-space flexibility outweighs counter constraints, whereas countertop units dominate urban cafés with compressed service lines.
NSF International standards govern food-contact surface sanitation and electrical safety certification for all equipment sold into US foodservice channels, while EPA Energy Star thresholds shape utility rebate eligibility and operator total-cost-of-ownership calculations. FDA Food Code provisions at state and local levels further dictate ice handling, temperature maintenance, and cleaning protocols that manufacturers must embed in design documentation. Stakeholders should monitor how state-level energy efficiency mandates beyond federal baselines will filter equipment eligibility for institutional procurement contracts.
Market Dynamics
Quick-service restaurant chains are consolidating procurement around NSF-certified equipment with embedded telemetry, forcing smaller manufacturers to absorb compliance costs or exit institutional channels entirely.
Growth Catalysts
- EPA Energy Star rebate programs:US utilities now tie equipment incentives to verified energy consumption thresholds, accelerating replacement cycles for aging fountain systems in high-traffic venues.
- Specialty coffee format proliferation:Third-wave café chains are specifying precision temperature control dispensers with single-origin bean preservation protocols.
- Stainless steel supply localization:Domestic mill capacity expansion in Ohio and Pennsylvania is compressing lead times for premium dispenser chassis fabrication.
Market Restraints
- Copper and nickel price volatility:Refrigeration coil input costs swing with London Metal Exchange pricing, squeezing margin on mid-tier chiller-integrated units.
- Compressor supply concentration:Three Asian component houses control bulk rotary compressor output, exposing North American assemblers to ocean freight disruption.
- NSF/ANSI 7 certification timelines:Extended third-party testing queues for refrigerated dispenser variants delay product launches by four to six months.
Strategic Opportunities
- India FSSAI modernization push:Food safety authority mandates for commercial kitchen equipment certification are opening institutional procurement channels previously served by informal fabricators.
- Touchless dispensing interfaces:Post-pandemic hygiene protocols are converging with capacitive sensor technology to create premium retrofit markets in healthcare and education foodservice.
- Direct-to-operator e-commerce:Manufacturer-owned digital channels are bypassing traditional foodservice equipment distributors for replacement part and consumables revenue.
Industry Challenges
- Refrigerant technician scarcity:EPA Section 608 certification requirements for handling low-GWP alternatives are outpacing vocational training program output.
- Legacy POS integration friction:Newer IoT-enabled dispensers require API development for compatibility with entrenched point-of-sale systems in franchise networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Beverage Dispenser Market |
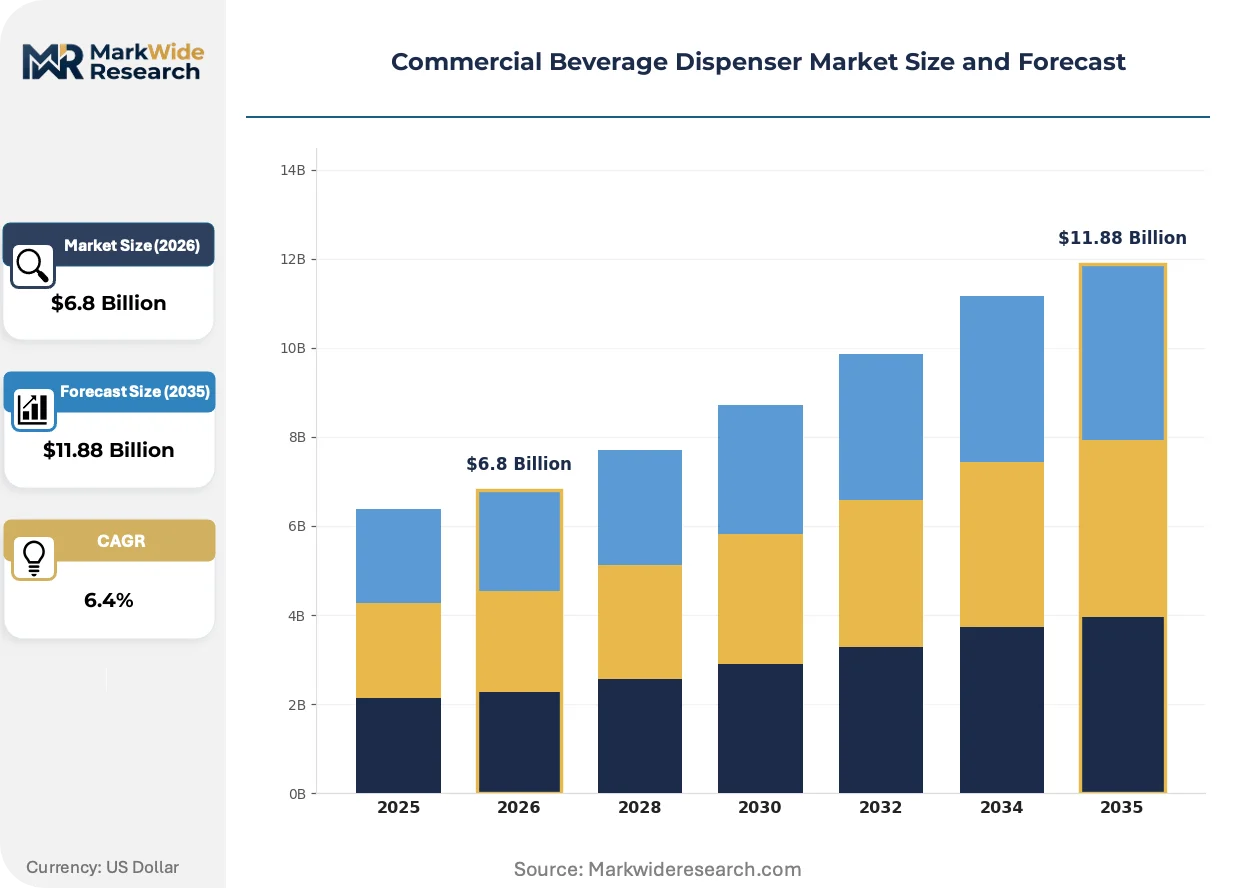
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated Drink Dispensers, Juice Dispensers, Ice Drink Dispensers, Coffee Dispensers End User: Restaurants, Cafés, Hotels, Entertainment Venues Installation Type: Countertop Units, Wall-mounted Systems, Freestanding Models, Inline Dispensers Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Distributors |
| Companies Covered | BUNN-O-Matic Corporation, Hoshizaki Corporation, Cornelius, Elmeco, Multiplex Beverage, Lancer Corporation, FBD Partnership, Middleby Corporation, Manitowoc Beverage Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Beverage Dispenser Market Emerging Trajectories
Equipment intelligence and sanitation automation are compressing the traditional five-year replacement cycle while fragmenting vendor relationships across hardware, software, and consumables suppliers.
Precision carbonation control systems are converging with real-time dissolved CO2 monitoring to maintain beverage consistency across altitude and temperature variations. Regional cinema chains and stadium concessionaires are specifying these units to reduce syrup waste and customer complaints. This convergence is compressing the addressable market for basic mechanical regulators while expanding service contract attach rates.
EU F-Gas Regulation phase-down schedules are mandating lower-global-warming-potential refrigerants in all new commercial refrigeration equipment sold into member states. Manufacturers must redesign chiller architectures around R-290 or R-600a hydrocarbon alternatives with flammability mitigation protocols. German and French institutional buyers are now requiring lifecycle refrigerant impact documentation in tender evaluations.
Leasing and subscription financing are displacing outright equipment purchase in multi-unit restaurant portfolios. Private equity-backed roll-up operators prefer operational expenditure treatment for dispenser fleets to preserve acquisition leverage capacity. This shift is most visible in Texas and Florida metropolitan corridors where franchise development velocity exceeds capital deployment timelines.
Commercial Beverage Dispenser Market Segmentation
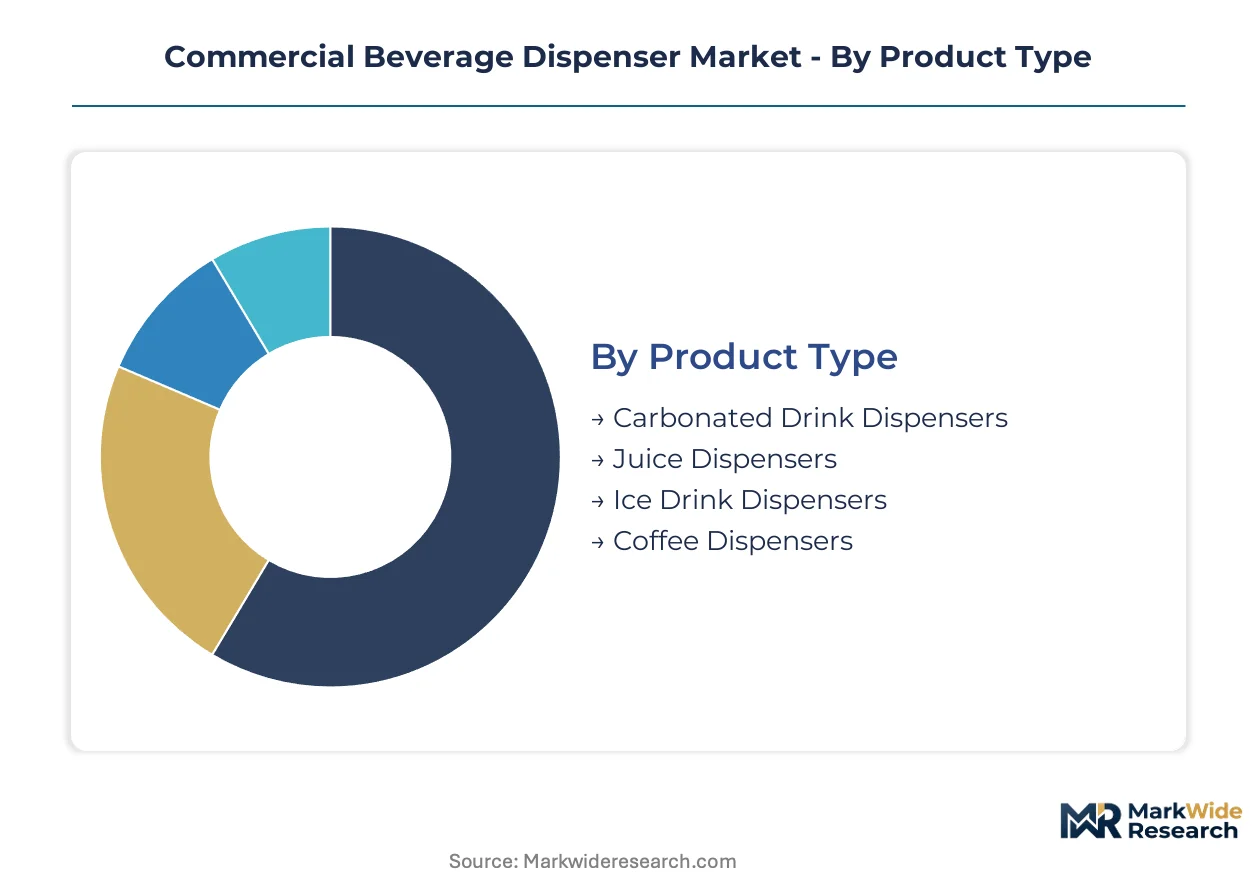
Segmentation in the commercial beverage dispenser market reveals how equipment specifications diverge across operational environments. Procurement patterns cluster around installation constraints, volume throughput requirements, and sanitation compliance tiers that vary sharply by end-use setting.
Product Type:
Supply concentration in refrigeration compressor sourcing favors manufacturers with captive chiller production or long-term component contracts.
- Coffee Dispensers:Precision temperature control systems maintain brewing parameters between 195°F and 205°F for specialty bean preservation. Third-wave café chains in Seattle and Portland specify these units for single-origin programs. Precision thermal management commands premium positioning against commodity alternatives.
- Carbonated Drink Dispensers:Integrated carbonation towers with real-time CO2 monitoring sustain syrup-to-water ratios across altitude variations. Quick-service fountain contracts in Texas and Florida metropolitan corridors anchor volume demand. Post-mix valve reliability determines total cost of ownership calculations for high-turnover operators.
- Juice Dispensers:Refrigerated bowl systems with agitation mechanisms prevent pulp separation in healthcare and education foodservice channels.
- Ice Drink Dispensers:Hoshizaki and Scotsman ice-making integration reduces countertop footprint for compact kitchen layouts in urban cafés.
Coffee dispensers absorb the bulk of installed capacity; coffee dispensers are expanding most quickly.
End User:
Application-specific sanitation protocols create divergent certification requirements across customer types.
- Restaurants:High-volume quick-service chains consolidate procurement around NSF-certified equipment with embedded telemetry for predictive maintenance. Drive-thru throughput demands in Atlanta and Dallas corridors favor dual-tower fountain configurations with redundant compressor systems.
- Cafés:Countertop footprint constraints dominate specification sheets for independent operators in dense urban cores. Precision temperature staging for alternative milk formulations drives equipment refresh cycles.
- Hotels:Breakfast service peak-load capacity determines dispenser sizing for banquet and buffet configurations.
- Entertainment Venues:Stadium concessionaires specify altitude-compensating carbonation systems to reduce syrup waste in Denver and Phoenix markets.
Restaurants absorb the bulk of installed capacity; cafés are climbing the fastest.
Installation Type:
Floor-space economics and service-line architecture dictate equipment form factor selection across venue types.
- Freestanding Models:Self-contained refrigeration and electrical systems enable rapid deployment in hotel lobbies and cinema concourses without plumbing modifications. Floor-space flexibility outweighs unit cost premiums in entertainment venue procurement.
- Countertop Units:Compressed service lines in Manhattan and San Francisco cafés drive demand for under-24-inch chassis widths. Dual-zone temperature control supports simultaneous hot and cold beverage programs.
- Wall-mounted Systems:Sanitation compliance in healthcare foodservice favors suspended configurations that eliminate floor-contact cleaning protocols.
- Inline Dispensers:Central kitchen architectures in casino and resort properties integrate bag-in-box syrup systems with remote refrigeration.
Freestanding models absorb the bulk of installed capacity; countertop units are gaining share fastest.
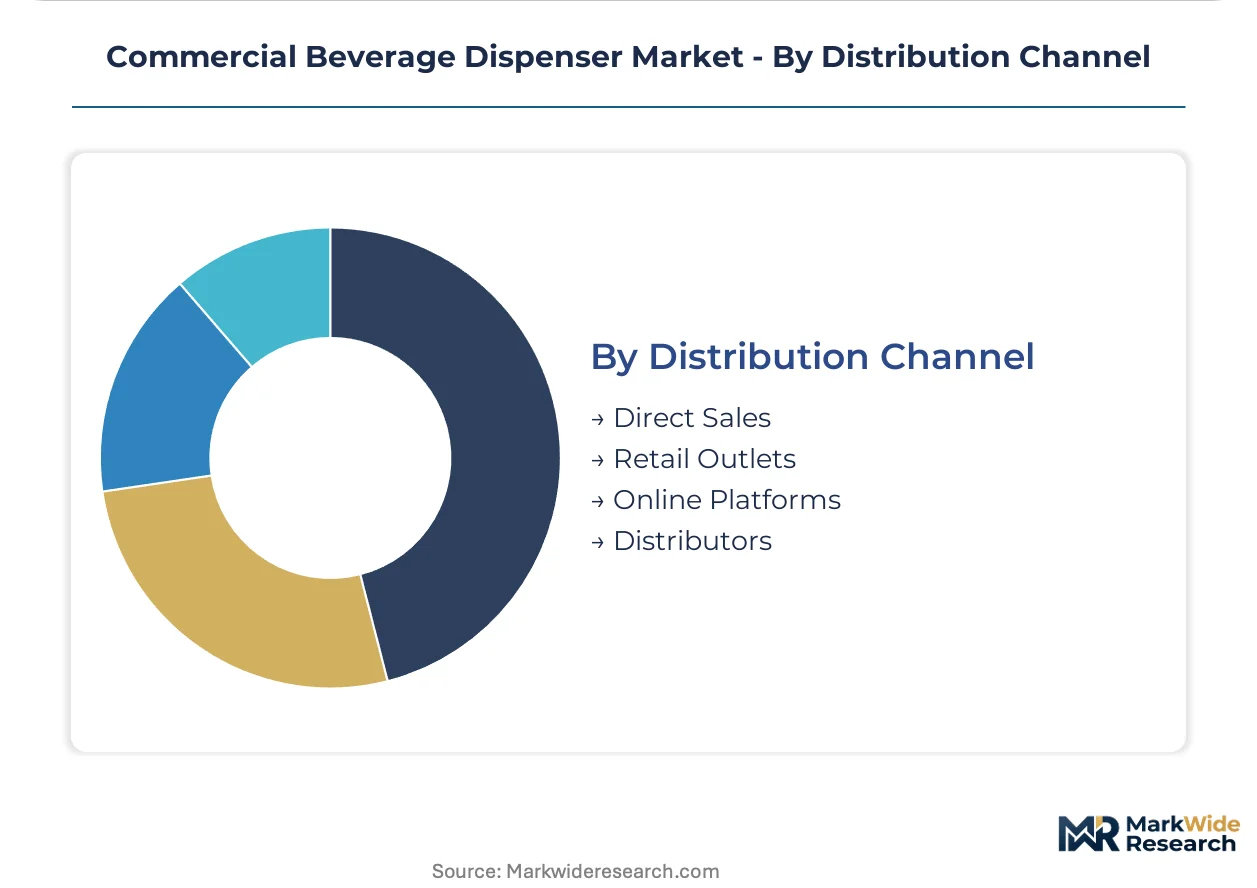
Distribution Channel:
Customer scale and replacement part dependency shape channel preference across operator segments.
- Direct Sales:National account teams service multi-unit restaurant portfolios with fleet-standardization programs and consolidated invoicing. Private equity-backed roll-up operators in Texas and Florida prefer operational expenditure treatment through leasing structures.
- Distributors:Regional equipment houses maintain local technician networks for warranty service and emergency compressor replacement. Independent operators in secondary markets rely on distributor inventory for same-day availability.
- Online Platforms:Manufacturer-owned digital channels bypass traditional foodservice equipment distributors for replacement part and consumables revenue.
- Retail Outlets:Limited SKU availability constrains penetration to small independent operators with immediate equipment failure scenarios.
Distributors absorb the bulk of installed capacity; direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlanta and Dallas corridors anchor North American demand through quick-service fountain deployments, while German institutional buyers reshape procurement criteria around lifecycle refrigerant documentation.
United States
Quick-service chains in Texas and Florida metropolitan corridors drive volume procurement for dual-tower fountain configurations. EPA Energy Star rebate programs accelerate replacement cycles for aging equipment in high-traffic venues. Atlanta and Dallas corridors concentrate drive-thru throughput demand with redundant compressor specifications.
Germany
Institutional buyers mandate lifecycle refrigerant impact documentation in tender evaluations for new equipment. EU F-Gas Regulation phase-down schedules force redesign around R-290 hydrocarbon alternatives with flammability protocols. Bavarian and North Rhine-Westphalia foodservice operators lead compliance adoption for chiller-integrated units.
India
FSSAI modernization mandates open institutional procurement channels previously served by informal fabricators. Food safety authority certification requirements reshape commercial kitchen equipment standards. Maharashtra and Karnataka urban clusters absorb initial compliance-driven replacement demand.
France
Cinema chains and stadium concessionaires specify altitude-compensating carbonation systems to reduce syrup waste. ANSM and CNIL oversight extends to connected dispenser telemetry for data handling compliance. Île-de-France and Provence-Alpes-Côte d'Azur entertainment venues anchor premium equipment specification.
Japan
Precision temperature control demand from third-wave café formats drives specialty dispenser procurement. METI efficiency standards and JIS certification requirements shape equipment import eligibility. Tokyo and Osaka metropolitan cores concentrate countertop footprint-constrained installations.
Commercial Beverage Dispenser Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and refrigeration integration depth. The vendor base stratifies between domestic manufacturers with captive fabrication capacity and import-dependent assemblers exposed to component supply concentration. Three archetypes dominate: stainless-steel chassis specialists, ice-making integration providers, and proprietary carbonation system developers. Competitive moves center on domestic mill partnerships for lead-time compression and telemetry-enabled service contract expansion.
Among North American fabricators, BUNN-O-Matic Corporation exemplifies the domestic manufacturing archetype with rapid-turn customization capabilities. Hoshizaki Corporation occupies a position within the ice-making integration tier, anchoring compact kitchen layout solutions. Cornelius represents the proprietary carbonation system archetype, serving high-volume entertainment venue specifications. These three illustrate how geographic origin and structural specialization map to distinct margin pools and procurement channel access.
| Leading Market Players |
|---|
| BUNN-O-Matic Corporation |
| Hoshizaki Corporation |
| Cornelius |
| Elmeco |
| Multiplex Beverage |
| Lancer Corporation |
| FBD Partnership |
| Middleby Corporation |
| Manitowoc Beverage Systems |
| Others |
Supply Flow & Price Mechanics
EPA Section 608 certified refrigeration technicians in the Ohio and Pennsylvania manufacturing corridor command wage premiums that compress margin pools for mid-tier dispenser assemblers, widening spreads between premium stainless-steel units and entry-level plastic alternatives.
Pricing Analysis
Throughput-based pricing anchors equipment valuation, with quick-service chains calculating total cost of ownership around drive-thru serve rates and predictive maintenance uptime guarantees. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified telemetry-embedded units from basic mechanical alternatives. Cost compression in the standard tier is intensifying because copper and nickel price volatility feeds directly into refrigeration coil input costs. Independent operators in secondary markets exhibit highest price sensitivity, while private equity-backed roll-up portfolios prioritize operational expenditure treatment over unit economics.
Supply Chain Analysis
Regional distribution centers in Texas and Florida metropolitan corridors buffer against compressor supply concentration, though three Asian component houses still control bulk rotary compressor output for North American assembly operations. Domestic mill capacity expansion in Ohio and Pennsylvania draws from localized stainless steel feedstock, while refrigeration coils rest on London Metal Exchange copper and nickel pricing. Single-source vulnerability in compressor sourcing exposes assemblers to ocean freight disruption. Distribution runs through regional equipment houses maintaining local technician networks for warranty service and emergency replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NSF/ANSI 7 certification timelines function as a cost-of-compliance moat, forcing smaller manufacturers to absorb extended third-party testing queues or exit institutional channels entirely.
For Market Incumbents: Anchor market position through captive domestic mill partnerships for stainless steel chassis fabrication in Ohio and Pennsylvania, compressing lead times against import-dependent competitors. Invest in telemetry-enabled service contract expansion to capture recurring revenue streams as leasing structures displace outright purchase. Refrigerant technician scarcity represents the critical vulnerability requiring backward integration into vocational training partnerships or certified technician network acquisition. For New Entrants and Emerging Players: FSSAI modernization in India opens a window for compliant equipment penetration into institutional procurement channels previously served by informal fabricators. Target Maharashtra and Karnataka urban clusters with certification-first positioning against legacy unorganized suppliers. Direct-to-operator e-commerce for replacement parts and consumables offers a channel-bypass go-to-market angle with lower customer acquisition costs than traditional distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with domestic manufacturers possessing captive fabrication capacity given EPA Energy Star rebate program acceleration driving replacement cycle velocity. Focus acquisition screening on stainless-steel chassis specialists with rapid-turn customization capabilities and established NSF certification documentation. Watch for state-level energy efficiency mandates beyond federal baselines as the inflection signal for institutional procurement contract eligibility tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Mill Partnership | Captive stainless steel supply from Ohio and Pennsylvania compresses lead times for premium chassis fabrication. |
| Telemetry-Enabled Service Contract | IoT predictive maintenance capabilities lock in recurring revenue from quick-service fountain deployments. |
| FSSAI Certification Investment | Compliance positioning captures institutional procurement channels in Maharashtra and Karnataka urban clusters. |
| Direct-to-Operator E-Commerce | Manufacturer-owned digital channels bypass traditional foodservice equipment distributors for replacement part revenue. |
| Hydrocarbon Refrigerant Redesign | R-290 and R-600a architectures with flammability mitigation protocols satisfy EU F-Gas Regulation phase-down schedules. |
Methodological Framework
Independent corroboration across foodservice equipment procurement managers, NSF certification testing laboratory directors, and regional distributor operations heads underwrites the qualitative findings. Primary interviews with quick-service chain engineering executives, commercial kitchen facility managers, and aftermarket service technicians combined with secondary validation from EPA Energy Star equipment databases, NSF International certification registries, and state-level utility rebate program filings. Bottom-up unit deployment estimates triangulated against top-down foodservice construction spending data.
Comparable-period anchoring to historical fountain system replacement cycles and quick-service restaurant development velocity calibrated the projection horizon. Segmentation modeling across product type, end user, installation configuration, and distribution channel dimensions generated volume and value outputs. CAGRs derived from equipment replacement cycle compression rates and regulatory-driven procurement standardization trends. Forecast inputs incorporated EPA Section 608 technician certification pipeline constraints and EU F-Gas refrigerant phase-down compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for touchless capacitive sensor interfaces would alter the outlook if post-pandemic hygiene protocols shift faster than embedded telemetry integration rates. Forecast outputs reflect documented assumptions regarding certification timeline normalization and compressor supply diversification. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Beverage Vending Machine Market
Food Service
Thailand Food Service Market
Food Service
Middle East and Africa Online Grocery Delivery Market
Food Service
Switzerland Food Service Market
Food Service
Turkey Food Service Market
Food Service
Plates Market
Food Service
Global Vending Machine Market
Food Service
Restaurants in Belgium Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
Global Online Food Ordering Market
Food Service
Retail Bubble Tea Kits Market
Food Service
United States Online Food Delivery Market
Food Service
Commercial Tandoor Oven Market
Food Service
Netherlands Food Service Market
Food Service
Shaker Bottles Market