
 Smoker Grill Market | 2026-2036
Smoker Grill Market Size, Share, and Industry Trends Forecast 2026-2036
Smoker Grill Market Insights
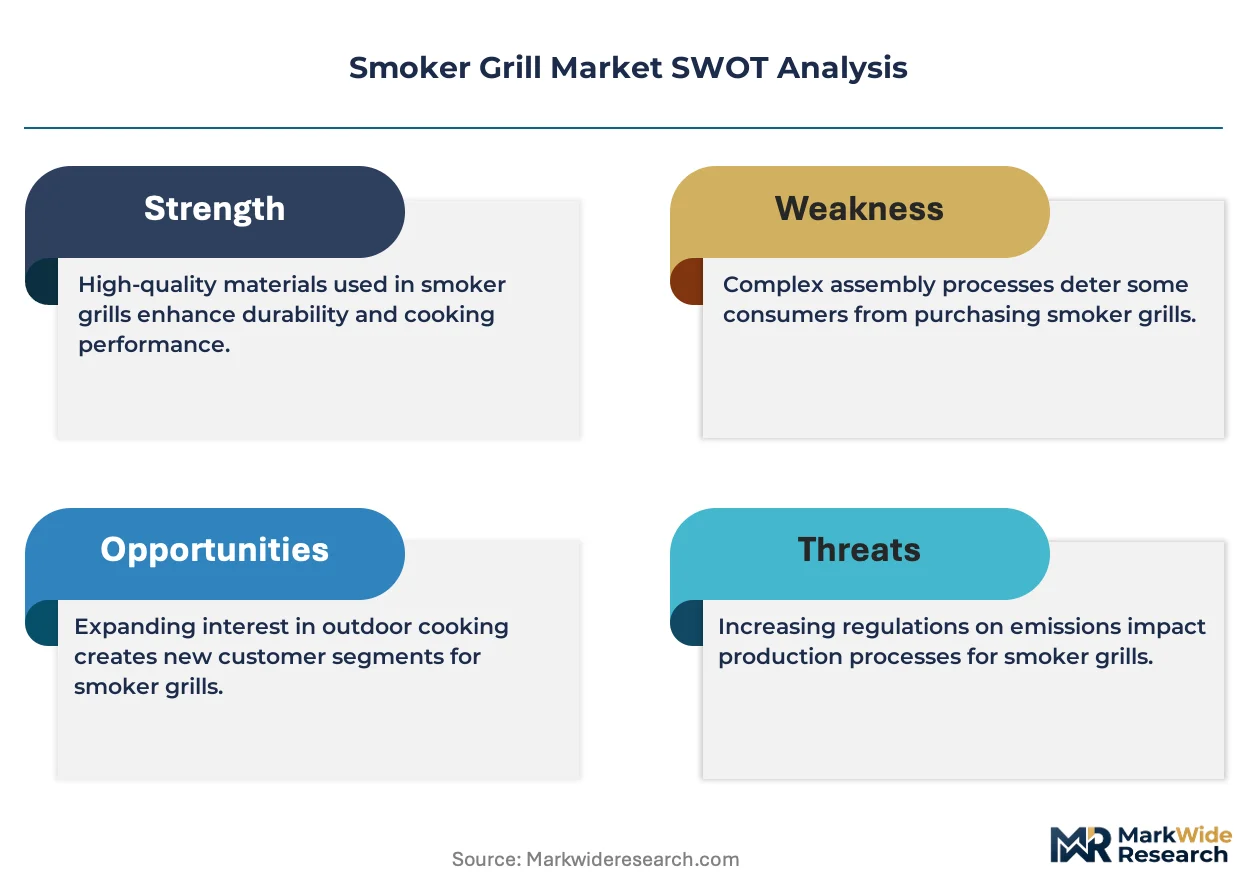
Asset-light leasing and subscription-based financing for outdoor cooking equipment is reconfiguring competitive entry barriers across the smoker grill landscape. Traeger Grills leverages its direct-to-consumer channel and proprietary WiFIRE technology to sustain recurring accessory revenue. Weber-Stephen Products anchors its position through broad retail distribution and in-house production of cast-aluminum components. Masterbuilt Manufacturing competes on electric and digital smoker specialization, occupying the entry-to-mid price band with programmable temperature controls.
A smoker grill is a thermally insulated cooking chamber designed to maintain low temperatures between 90°F and 275°F for extended periods, using indirect heat and controlled smoke circulation to transform collagen into gelatin while depositing lignin-derived flavor compounds on protein surfaces. Pellet grills, which automate fuel delivery via auger-fed hardwood sawdust, lead product-type revenue due to convenience positioning and digital integration. Charcoal smokers retain structural importance in competition barbecue and purist residential segments where flavor authenticity commands premium positioning. Commercial users and restaurants represent the fastest-growing end-user category as ghost kitchens and fast-casual chains adopt centralized smoking operations for menu differentiation.
The US EPA regulates particulate emissions from residential wood heaters under New Source Performance Standards, while the Consumer Product Safety Commission oversees thermal safety and tip-over stability requirements for outdoor cooking appliances. California's Air Resources Board imposes additional restrictions on wood-burning equipment in designated air quality management districts, forcing manufacturers to certify low-emission designs for access to the country's largest state market. Stakeholders must monitor evolving state-level emissions frameworks and building-code integrations for outdoor kitchens that will determine which fuel technologies retain install-base eligibility.
Market Dynamics
The US EPA's updated particulate emissions guidelines for residential wood-burning equipment are compressing install-base eligibility for charcoal and wood-fuel units while privileging pellet systems with automated combustion controls. This regulatory pivot is reconfiguring manufacturer R&D priorities and retail inventory composition simultaneously.
Growth Catalysts
- Texas barbecue culture:Competition circuits and regional retail density sustain premium equipment turnover through recurring replacement cycles and social-media-driven aspirational purchasing.
- WiFIRE-enabled pellet systems:Automated fuel delivery and smartphone temperature monitoring reduce operator skill barriers, expanding addressable demand among casual backyard cooks.
- California Air Resources Board low-emission certification:Mandatory for access to the country's largest state market, forcing design investments that subsequently export to other air quality management districts.
Market Restraints
- Hardwood pellet supply concentration:Domestic sawdust sourcing clusters in Pacific Northwest timber regions, exposing manufacturers to wildfire-disrupted feedstock availability and freight cost volatility.
- Cast-aluminum component tariffs:In-house foundry capacity at major producers insulates against import duty exposure that elevates landed costs for assembly-dependent competitors.
- Charcoal flavor authenticity preference:Competition barbecue segments resist pellet automation, capping addressable share in high-visibility influencer and professional user categories.
Strategic Opportunities
- Ghost kitchen centralized smoking operations:Fast-casual chains adopt dedicated smokehouses for menu differentiation, creating commercial-grade equipment demand with service-contract attach rates.
- Subscription-based accessory financing:Asset-light leasing models reduce consumer upfront commitment while locking in recurring revenue from wood pellet and cover replenishment.
- EU F-Gas Regulation alignment:European import standards for refrigerant-free thermal systems create certification pathways for electric smoker exports to German and Dutch outdoor hospitality markets.
Industry Challenges
- Pitmaster skill scarcity:Commercial ghost kitchen operators lack traditional barbecue expertise, forcing manufacturers to simplify controls while maintaining output consistency across unskilled labor pools.
- Multi-jurisdiction certification timelines:Simultaneous EPA, CARB, and state-level air quality district approvals extend product launch windows and freeze inventory deployment capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoker Grill Market |
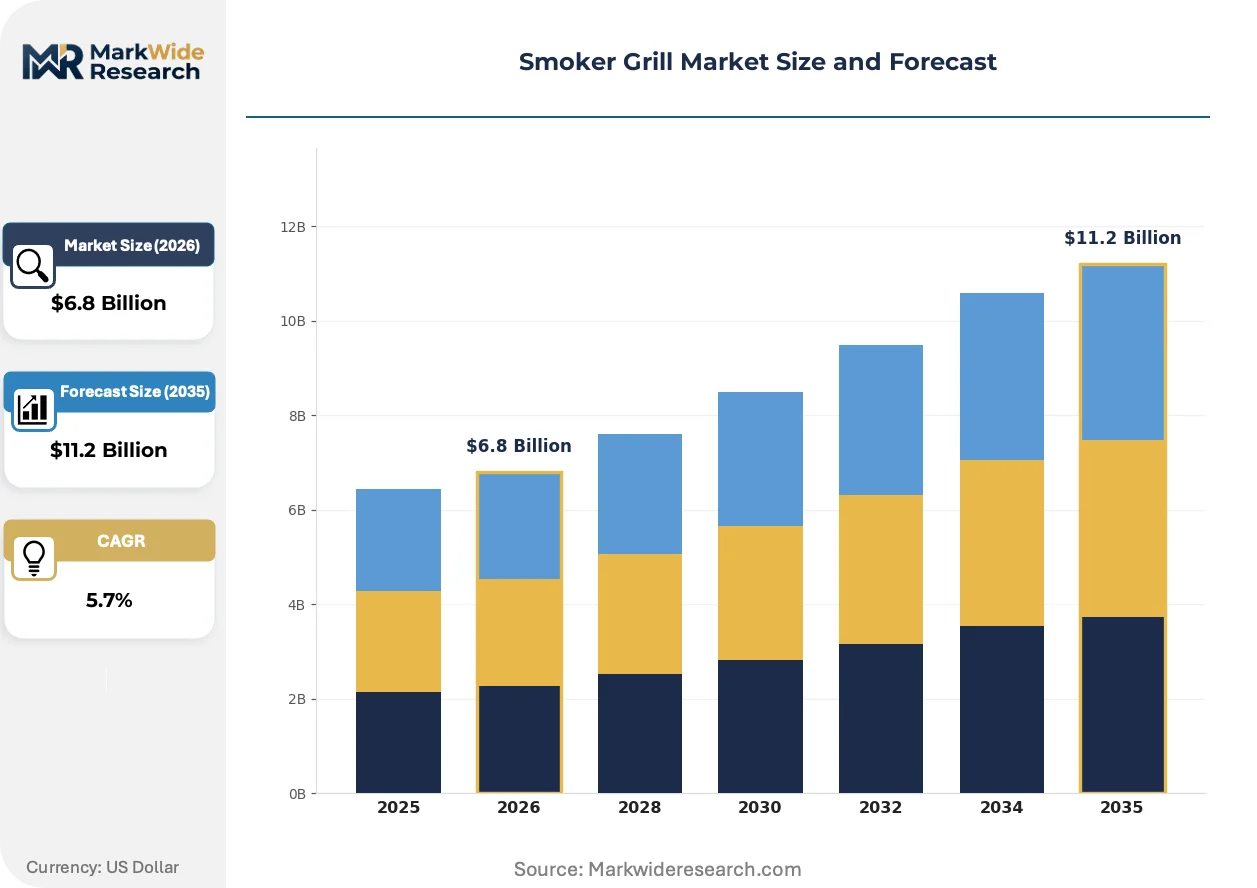
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Smokers, Pellet Grills, Charcoal Smokers, Gas Smokers End User: Residential Users, Commercial Users, Catering Services, Restaurants Fuel Type: Wood, Charcoal, Gas, Electricity Capacity: Portable, Small, Medium, Large |
| Companies Covered | Traeger Grills, Weber-Stephen Products, Char-Broil, Blackstone Products, Pit Boss Grills, Napoleon Grills, Masterbuilt Manufacturing, Camp Chef, Green Mountain Grills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoker Grill Market Trends and Innovations
Connected hardware and automated fuel systems are displacing manual fire management as the default expectation across residential price tiers. This shift compresses the skill premium historically commanded by charcoal purists while opening subscription revenue streams.
Pellet grill technology is digitizing combustion control through auger-fed hardwood delivery married to PID temperature algorithms. Ghost kitchen operators and backyard enthusiasts alike adopt these systems for set-and-forget reliability. The technology is digitizing operator judgment into sensor-driven feedback loops that standardize output quality regardless of user experience.
The US EPA New Source Performance Standards for residential wood heaters are tightening particulate emission thresholds in manufacturing states. Foundries and assembly plants must certify low-emission designs or forfeit access to California and northeastern air quality districts. Pellet and electric categories capture shelf space as charcoal units face delisting risk in regulated municipalities.
Commercial procurement now favors centralized smokehouse infrastructure over distributed grill fleets. Fast-casual chains contract dedicated smoking capacity with service-level agreements covering maintenance and fuel supply. This pattern concentrates most visibly in Texas and California urban corridors where labor costs and real estate premiums reward operational consolidation.
Smoker Grill Market Segmentation
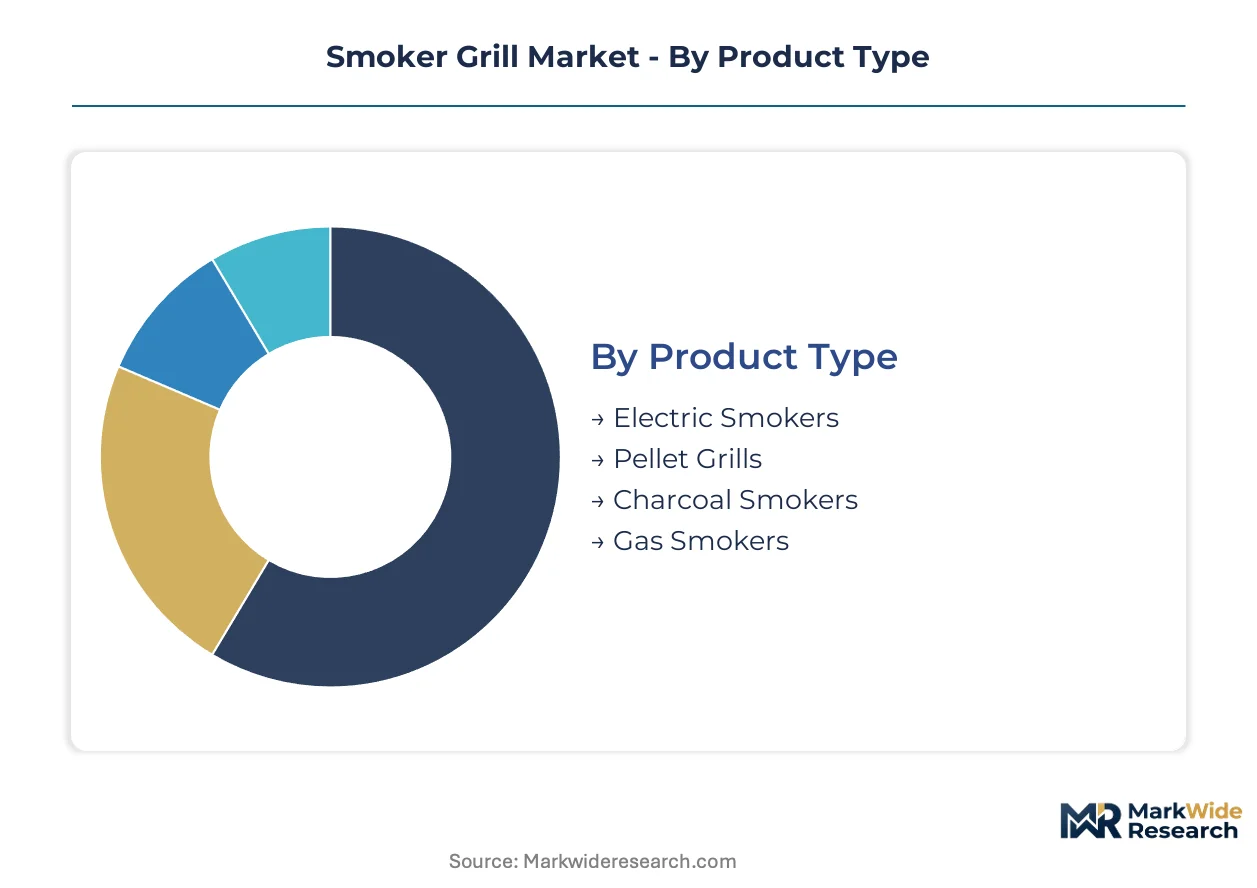
Smoker grill segmentation reveals how fuel technology, operator skill, and cooking scale partition purchasing behavior. Manufacturers must align R&D investment and distribution strategy with the distinct performance expectations and regulatory exposure of each category.
Product Type:
Pellet grills occupy the emerging technology tier with digitized combustion control, while charcoal smokers anchor the mature traditionalist segment.
- Pellet Grills:Auger-fed hardwood sawdust delivery married to PID temperature algorithms automates fuel combustion and smoke density. Demand concentrates in suburban Texas and California residential markets where WiFi-enabled monitoring reduces pitmaster skill requirements. The EPA's particulate emissions guidelines favor these systems for their automated combustion controls.
- Charcoal Smokers:Thermally insulated steel chambers relying on manual fire management and hardwood lump fuel. Competition barbecue circuits in Kansas City and Memphis sustain premium pricing for offset and vertical drum configurations where lignin-derived flavor authenticity commands judge preference.
- Electric Smokers:Heating-element-based systems with chip trays for supplemental smoke generation, targeting apartment dwellers and municipalities with open-flame restrictions.
- Gas Smokers:Propane-fueled cabinets with burner-generated heat and wood chip boxes, serving entry-level residential users prioritizing ignition convenience over smoke intensity.
Pellet grills retain volume leadership; electric smokers hold the steepest expansion curve in regulated municipalities.
End User:
Application context separates hobbyist replacement cycles from commercial equipment depreciation schedules and service-contract economics.
- Restaurants:Fast-casual chains and barbecue-focused independents deploy centralized smokehouse infrastructure with dedicated exhaust systems and NSF-certified construction. Ghost kitchen operators in Austin and Dallas adopt these systems for menu differentiation without traditional pitmaster labor.
- Commercial Users:Hotels, resorts, and corporate campus dining operations with outdoor hospitality programming. Procurement favors stainless-steel construction and multi-year service agreements covering burner replacement and auger maintenance.
- Residential Users:Backyard enthusiasts purchasing through big-box retail and direct-to-consumer channels, with replacement cycles tied to housing turnover and outdoor kitchen renovation projects.
- Catering Services:Mobile operators requiring trailer-mounted or towable configurations for competition circuits and private event execution.
Residential users retain volume leadership; restaurants hold the steepest expansion curve as centralized smoking operations displace distributed grill fleets.
Fuel Type:
Regulatory exposure and flavor chemistry partition fuel selection across geographic air quality districts and operator preference segments.
- Wood:Traditional stick-burning with split logs in offset smokers, delivering maximum smoke ring formation and bark development. California Air Resources Board restrictions compress install-base eligibility in designated air quality management districts.
- Charcoal:Lump hardwood and briquette combustion in kamado and barrel configurations. Texas competition circuits sustain demand despite EPA particulate scrutiny.
- Electricity:Resistance-element heating with optional chip supplementation, exempt from wood-burning emissions regulations and permitted in multi-family housing with balcony restrictions.
- Gas:Propane combustion with secondary smoke generation, dominating entry price tiers where fuel convenience outweighs flavor intensity preferences.
Charcoal retains volume leadership; electricity holds the steepest expansion curve in coastal regulatory jurisdictions.
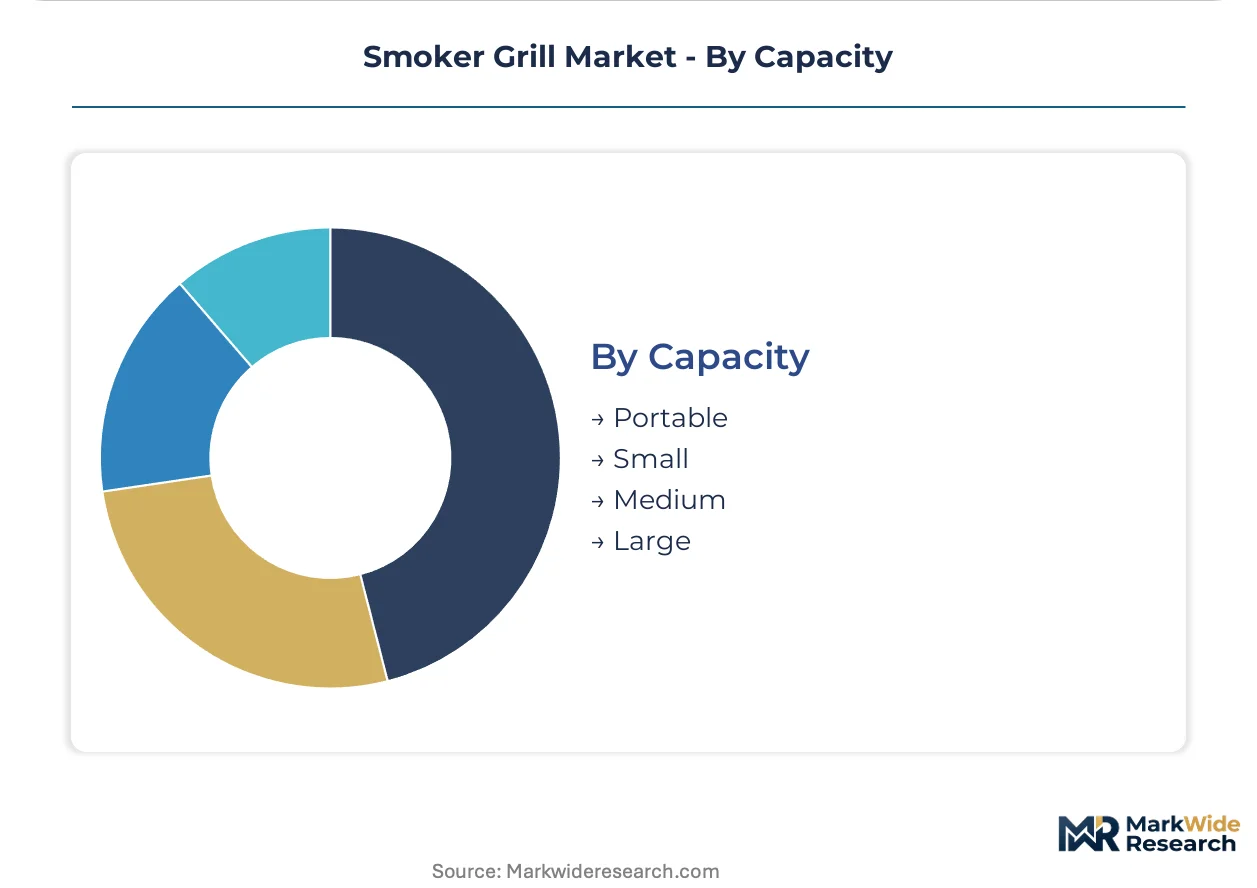
Capacity:
Physical scale determines thermal mass, fuel consumption rates, and mobility constraints across residential and commercial deployment contexts.
- Large:Cabinet and trailer-mounted systems exceeding 500 square inches of cooking surface, serving competition teams and dedicated smokehouse operations with whole-hog and multi-rack capacity.
- Medium:Freestanding vertical or horizontal units between 300-500 square inches, capturing the replacement-cycle core of suburban residential demand.
- Small:Tabletop and compact vertical designs under 300 square inches, targeting apartment balconies and tailgating applications with storage constraints.
- Portable:Collapsible or briefcase-style units with sub-150 square inch capacity, serving camping and RV markets with weight-minimized construction.
Medium capacity retains volume leadership; portable configurations hold the steepest expansion curve in outdoor recreation and mobility-oriented segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stringent particulate emissions standards in California and Texas barbecue culture are reshaping equipment demand across national markets. Regulatory divergence between air quality districts and competition circuit density creates geographic specialization in product mix.
United States
Texas barbecue culture sustains premium equipment turnover through competition circuits in Austin and Dallas. The US EPA's New Source Performance Standards for residential wood heaters tighten particulate thresholds, compressing charcoal unit eligibility. California's Air Resources Board mandates low-emission certification for market access, privileging pellet systems with automated combustion controls in Los Angeles and San Francisco air quality districts.
Germany
Outdoor hospitality operators in Bavaria and North Rhine-Westphalia are expanding pellet grill procurement for beer garden and hotel programming. The EU F-Gas Regulation alignment creates certification pathways for electric smoker exports, with TÜV standards governing thermal safety. Industrial fabrication clusters in Stuttgart and Hamburg supply precision auger and control module components to European manufacturers.
China
Domestic sawdust sourcing concentrates in Pacific Northwest timber regions, exposing supply chains to wildfire-disrupted feedstock availability. The country's national environmental regulator enforces industrial emissions standards for foundry operations producing cast-aluminum components. Manufacturing agglomeration in Guangdong and Zhejiang provinces supports OEM assembly for export markets.
Australia
Barbecue-focused residential culture in New South Wales and Victoria sustains steady replacement cycles for mid-capacity units. State-level environmental protection agencies impose wood-burning restrictions in designated air quality zones, favoring electric and gas alternatives in Sydney and Melbourne metropolitan areas. Camping and RV markets in Queensland drive portable configuration demand.
United Kingdom
Urban balcony restrictions in London and Manchester elevate electric smoker penetration among apartment dwellers. The country's product safety regulator oversees thermal stability and tip-over requirements for outdoor cooking appliances. Garden center retail chains in the Southeast and Midlands regions anchor distribution for entry-to-mid price band equipment.
Smoker Grill Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price bands defined by fuel technology and digital integration. The vendor base organizes around three strategic archetypes: direct-to-consumer connected hardware specialists, broad retail distributors with captive component production, and electric-digital specialists occupying entry-to-mid positioning. Consolidation pressure intensifies as EPA compliance costs favor scaled R&D investment and multi-jurisdiction certification capabilities. Geographic expansion and technology licensing represent dominant competitive moves for accessing regulated district markets.
Within the connected hardware tier, Traeger Grills exemplifies direct-to-consumer channel control with proprietary WiFIRE technology integration. Weber-Stephen Products anchors the broad retail distribution archetype through in-house cast-aluminum component production. Masterbuilt Manufacturing occupies the electric-digital specialization position with programmable temperature control systems. These three entities represent distinct strategic vectors: subscription-recurring revenue, manufacturing scale insulation, and entry-point automation respectively.
| Leading Market Players |
|---|
| Traeger Grills |
| Weber-Stephen Products |
| Char-Broil |
| Blackstone Products |
| Pit Boss Grills |
| Napoleon Grills |
| Masterbuilt Manufacturing |
| Camp Chef |
| Green Mountain Grills |
| Others |
Pricing and Supply Chain Analysis
Cast-aluminum component tariffs from overseas foundries compress margin structures across mid-tier manufacturers while simultaneously rewarding domestic in-house production capacity. This tariff exposure widens pricing spreads between import-dependent assemblers and vertically integrated producers, reshaping procurement decisions toward captive supply and regional sourcing clusters.
Pricing Analysis
Certification level creates the primary spread across product tiers, with EPA New Source Performance Standards and California Air Resources Board low-emission certifications commanding substantial premiums over uncertified charcoal alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by digital integration depth, WiFi-enabled PID control systems occupying the premium band while manual charcoal units anchor entry positioning. Pricing pressure stems from hardwood pellet feedstock volatility in Pacific Northwest timber regions, compressing margins for auger-fed system manufacturers. Residential backyard enthusiasts exhibit highest price sensitivity, whereas commercial ghost kitchen operators prioritize output consistency over unit economics.
Supply Chain Analysis
Export-control restrictions on precision auger and control module technologies limit component flows from German industrial fabrication clusters in Stuttgart and Hamburg to non-aligned manufacturers. Geographic supply concentration centers on China for cast-aluminum foundry operations, the United States for domestic sawdust pellet production, and Germany for precision control electronics. Raw material dependencies include Pacific Northwest hardwood sawdust, cast-aluminum alloy stock, and PID temperature algorithm chipsets. Single-source vulnerability in hardwood pellet feedstock exposes manufacturers to wildfire-disrupted availability and freight cost spikes. Distribution runs through big-box retail partnerships, direct-to-consumer channels, and commercial foodservice equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smoker grill market approaches a platform-economics inflection as WiFIRE-enabled ecosystems and subscription-based accessory replenishment transform transactional hardware sales into recurring revenue architectures. Interoperability between pellet auger systems, smartphone monitoring applications, and automated fuel delivery networks is consolidating competitive advantage around connected infrastructure control.
For Market Incumbents: Build certification moats around multi-jurisdiction EPA and CARB compliance capabilities to freeze out capital-constrained competitors facing extended approval timelines. Deepen backward integration into cast-aluminum foundry capacity to insulate against tariff exposure that elevates landed costs for assembly-dependent rivals. Prioritize R&D investment in simplified control interfaces for unskilled ghost kitchen labor pools, addressing the pitmaster expertise scarcity threatening commercial output consistency.
For New Entrants and Emerging Players: Mid-market electric smokers for apartment-dwelling consumers in coastal regulatory jurisdictions represent the most penetrable entry point, bypassing entrenched competition in Texas barbecue strongholds. Portable configurations for camping and RV markets in Queensland and the American Southwest offer white-space expansion with lower certification burden than fixed residential installations. Direct-to-consumer channel control with subscription financing models reduces upfront consumer commitment while capturing recurring pellet and cover replenishment revenue.
For Investors and Strategic Acquirers: EPA New Source Performance Standards tightening particulate thresholds reshapes the acquisition landscape toward pellet and electric specialists with compliant product portfolios. Long-term viability favors targets with multi-jurisdiction certification capabilities and captive component production insulating against tariff volatility. Monitor state-level air quality district delisting actions against charcoal units as early signals of accelerated category shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Investment | EPA and CARB approvals unlock California and northeastern air quality district access, the country's largest state market. |
| Backward Integration into Foundry Capacity | In-house cast-aluminum production insulates against import tariff exposure compressing competitor margins. |
| Subscription-Based Accessory Financing | Recurring pellet and cover replenishment transforms transactional hardware sales into predictable revenue streams. |
| Ghost Kitchen Commercial Partnership | Centralized smokehouse service contracts with fast-casual chains capture high-visibility menu differentiation demand. |
| EU F-Gas Regulation Alignment | Refrigerant-free thermal system certification opens electric smoker exports to German and Dutch outdoor hospitality markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, CARB certification databases, SEC 10-K disclosures from publicly traded manufacturers, and customs import records for cast-aluminum components. Primary interviews engaged product development directors at pellet grill manufacturers, procurement leads at commercial foodservice operators, category buyers at big-box retail chains, and aftermarket service heads at regional distribution networks. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions derived from retail audit data and channel inventory turns.
Forecast inputs incorporate fuel technology adoption curves, regulatory compliance timeline projections, and commercial end-user penetration rates across ghost kitchen and fast-casual chain segments. Segmentation dimensions modeled include product type, end-user category, fuel technology, and geographic air quality regulatory cluster. CAGRs were derived from fitted growth curves anchored to housing turnover patterns, outdoor kitchen renovation cycles, and replacement-rate assumptions by equipment tier. Industry-specific inputs include hardwood pellet supply elasticity and wildfire disruption frequency in Pacific Northwest sourcing regions.
Practitioners should monitor EPA enforcement actions against non-compliant wood-burning equipment, state-level air quality district expansion of charcoal restrictions, and hardwood pellet supply disruptions from Pacific Northwest wildfire seasons for early signals of forecast deviation. Material shifts in federal tariff policy on cast-aluminum components, CARB certification requirement stringency, or commercial ghost kitchen adoption velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Beverage Napkins Market
Food Service
Global Virtual Restaurant and Ghost Kitchens Market
Food Service
South Africa Fast Food Market
Food Service
China Inflight Catering Market
Food Service
Philippines Quick Service Restaurants Market
Food Service
Charbroiler Market
Food Service
Portable Buffet and Drop-In Ranges Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
North America Online Food Delivery Market
Food Service
Global Online Food Ordering Market
Food Service
Cloud Kitchen Market
Food Service
United States Cafes & Bars Market
Food Service
Restaurants and Mobile Food Services Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Onboard Rail Catering Market