
 Saudi Arabia Foodservice Market | 2026-2036
Saudi Arabia Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Foodservice Market Analytics
Food delivery platform architecture is fragmenting as third-party aggregators and native restaurant apps compete for order volume in Saudi Arabia's foodservice landscape. Gulf Catering Company leverages its institutional contract base to sustain recurring revenue from oil-sector and government clients. Tamimi Global anchors its position through vertically integrated supply chains spanning procurement, central kitchens, and on-site service delivery. Saudi Airlines Catering Company dominates airport and inflight segments, extending its logistics capabilities into event and remote-site catering.
Foodservice encompasses the commercial preparation, assembly, and distribution of meals outside residential settings, operating through centralized kitchens with HACCP-compliant cold chains, standardized portion controls, and real-time inventory tracking systems to ensure consistency across high-volume outlets. The sector serves hospitality, corporate, healthcare, and educational institutions requiring scalable, regulated meal provision. Full-Service Restaurants and Fast Casual formats lead revenue generation as experiential dining and premium local concepts capture family spending and tourist flows. Delivery Services channel growth outpaces dine-in expansion, with aggregator platforms reshaping customer acquisition economics and kitchen utilization rates across Riyadh and Jeddah.
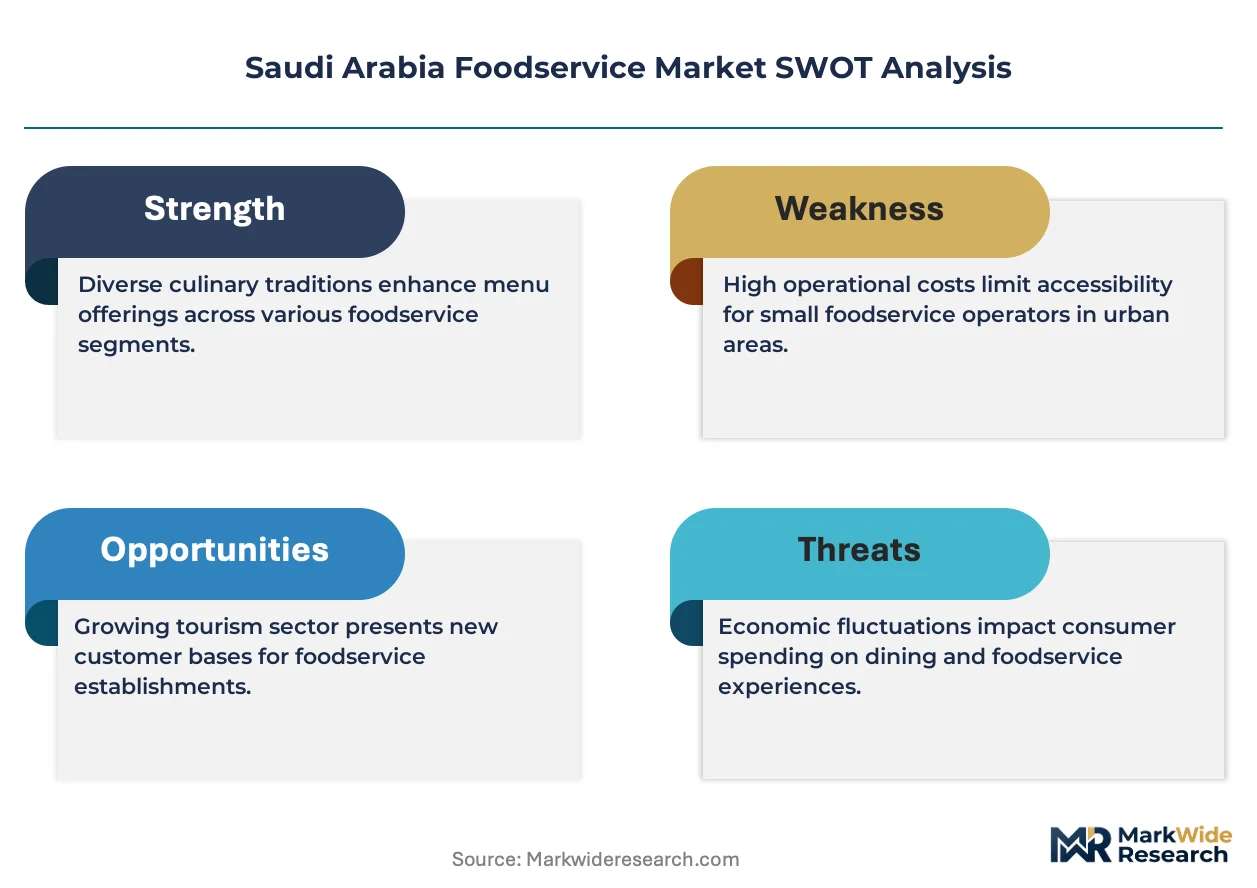
SFDA food safety licensing, SASO quality certification requirements, and MOHAP hospitality sector standards collectively elevate operational barriers and compliance costs for new entrants. These frameworks mandate kitchen inspection frequencies, ingredient traceability, and staff hygiene training that shape capital deployment and technology investment priorities. Stakeholders must monitor regulatory enforcement intensity and alignment with Vision 2030 tourism targets to calibrate expansion timing and format selection.
Market Dynamics
SFDA's updated food safety protocols are digitizing kitchen compliance across Saudi Arabia, forcing operators to deploy real-time monitoring systems and cold-chain traceability platforms that reshape capital allocation and vendor selection criteria.
Growth Catalysts
- Vision 2030 entertainment infrastructure:Riyadh and Jeddah hospitality clusters are expanding venue capacity to capture inbound tourism flows and domestic leisure spending.
- Quick-service restaurant format proliferation:Young professionals in urban centers are driving order volume through aggregator platforms and native restaurant apps.
- SFDA digital licensing mandates:Food safety protocol digitization is accelerating technology adoption among mid-scale operators seeking compliance certification.
Market Restraints
- Imported protein input volatility:Beef and poultry supply concentration in Brazilian and Australian export markets exposes operators to currency and shipping cost fluctuations.
- Central kitchen capex intensity:HACCP-compliant cold chain infrastructure requires substantial upfront investment that fragments operator scale economics.
- MOHAP hospitality licensing friction:Multi-agency permit requirements across municipal and federal layers extend venue opening timelines.
Strategic Opportunities
- Secondary city penetration:Dammam and Khobar foodservice density remains below Riyadh-Jeddah levels, creating whitespace for format replication.
- Corporate catering contract expansion:Oil-sector and government institutional clients are consolidating vendor relationships toward multi-year service agreements.
- Cloud kitchen convergence with delivery logistics:Dark kitchen facilities paired with aggregator platform data are optimizing kitchen utilization rates in high-rent districts.
Industry Challenges
- HACCP auditor talent scarcity:Certified food safety professionals command premium wages that compress operator margin structures.
- Legacy POS integration complexity:Inventory tracking systems require reconfiguration to interface with SFDA-mandated digital submission portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Foodservice Market |
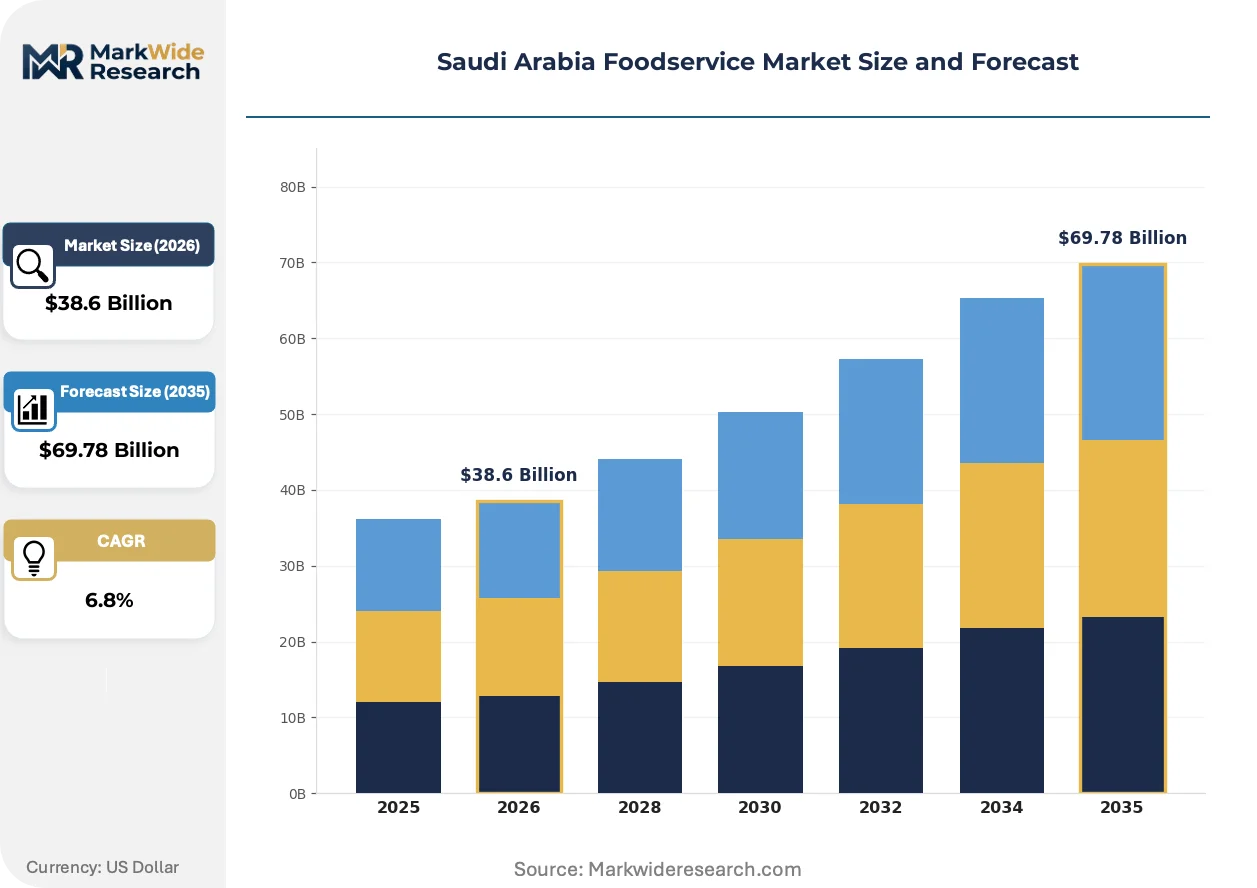
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Fast Casual, Cafés, Food Trucks Customer Type: Families, Young Professionals, Tourists, Business Travelers Food Type: Traditional Cuisine, International Cuisine, Fast Food, Healthy Options Delivery Channel: Dine-In, Takeaway, Delivery Services, Online Booking |
| Companies Covered | Algosaibi Services Co. Ltd., Gulf Catering Company, Tamimi Global, Al-Karam Al-Arabi for Catering Services Limited, Gulf Mahmal Support Services Company, Saudi Airlines Catering Company, Al-Suwaidi Services Company Limited, Unique Catering Services, Nesma United Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Foodservice Market Evolving Landscape
Digital infrastructure deployment and regulatory compliance automation are converging to reshape how Saudi foodservice operators manage kitchen operations, customer acquisition, and supply chain transparency.
Kitchen display systems integrated with IoT temperature sensors are digitizing HACCP documentation workflows across full-service and fast-casual formats. Mid-scale restaurant groups in Riyadh are deploying these platforms to reduce manual logging labor and accelerate health inspection readiness. Real-time cold chain monitoring is compressing spoilage losses and enabling dynamic supplier scorecards based on delivery temperature integrity.
SFDA's 2023 food traceability mandates require ingredient batch tracking from supplier receipt through final service. Restaurant operators are restructuring procurement relationships to secure blockchain-enabled documentation from protein and dairy vendors. Smaller independent outlets in Jeddah face disproportionate compliance burdens as they lack dedicated technology procurement functions.
Aggregator platform economics are restructuring customer acquisition patterns across Saudi urban centers. Quick-service brands are diverting marketing spend from physical location premiums toward in-app visibility and loyalty program integration. Family dining segments in Riyadh's entertainment districts show the strongest platform dependency, with delivery order share now exceeding dine-in volume during weekday lunch periods.
Saudi Arabia Foodservice Market Segmentation
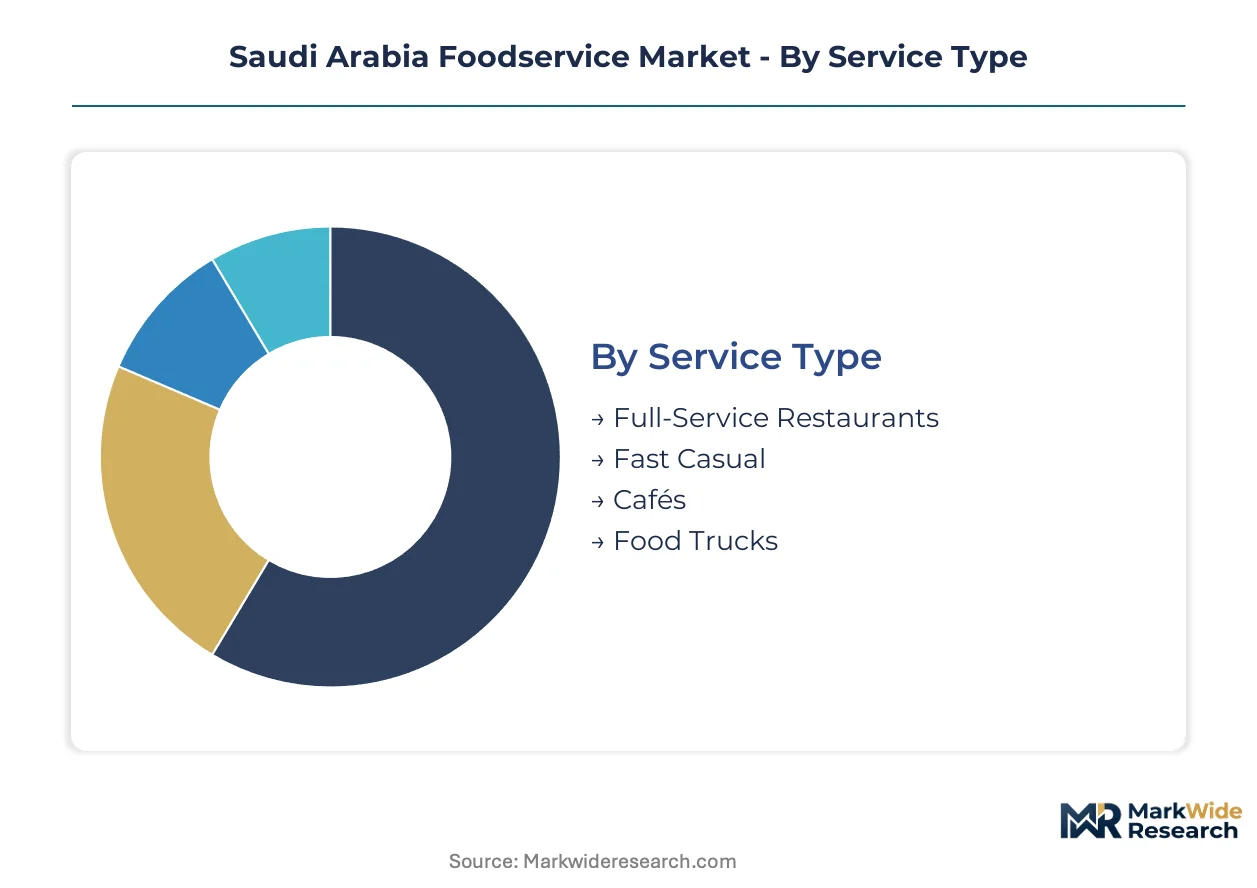
Foodservice segmentation in Saudi Arabia reflects distinct consumption occasions, regulatory compliance requirements, and capital intensity levels that shape operator format selection and geographic deployment strategies.
Service Type:
Service formats span from labor-intensive full-service dining to asset-light mobile operations, each carrying different SFDA compliance burdens and real estate cost structures.
- Full-Service Restaurants:Table-service formats with on-premise kitchen operations and front-of-house staffing dominate family spending occasions and entertainment district clustering. Riyadh's hospitality corridor concentrates premium full-service development as Vision 2030 venue construction accelerates.
- Fast Casual:Counter-service models with limited table service and standardized menu execution capture young professional lunch demand and aggregator platform order flow. Jeddah's commercial districts show the steepest fast casual expansion trajectory as operators optimize kitchen throughput for delivery-native consumption.
- Cafés:Beverage-forward formats with light food preparation and extended dwell-time seating target remote work patterns and social meeting occasions.
- Food Trucks:Mobile kitchen units with municipal permit requirements and event-based revenue concentration serve festival circuits and construction site catering.
The dominant share belongs to Full-Service Restaurants, while Fast Casual is closing the gap fastest.
Customer Type:
Customer archetypes determine daypart mix, average transaction value, and platform dependency, with each segment carrying distinct loyalty economics and acquisition cost profiles.
- Families:Multi-generational dining groups with high per-check spending and weekend occasion concentration drive full-service restaurant capacity planning in Riyadh and Jeddah entertainment clusters.
- Young Professionals:Time-constrained urban workers with high aggregator platform penetration and weekday lunch demand dominate fast casual order volume.
- Tourists:Inbound leisure travelers with experiential dining preferences and international cuisine exposure expand premium positioning opportunities.
- Business Travelers:Corporate transient demand with expense-account elasticity and hotel proximity requirements sustains airport and central business district outlet performance.
Families command the largest revenue pool, though Young Professionals are expanding most quickly.
Food Type:
Menu positioning reflects supply chain sourcing capabilities, kitchen equipment specialization, and local palate adaptation requirements that differentiate operator investment profiles.
- Traditional Cuisine:Kabsa, mandi, and regional preparation methods with protein-centric menus and shared-plate service formats anchor family dining occasions and cultural authenticity positioning.
- International Cuisine:Asian, European, and Levantine formats with imported ingredient dependencies and specialized chef requirements target expatriate communities and tourist demand in Jeddah's Red Sea corridor.
- Fast Food:Standardized global brands with frozen supply chains and limited menu complexity dominate mall-based locations and drive-through development.
- Healthy Options:Calorie-conscious and dietary-restriction-friendly formats with fresh procurement intensity and shorter shelf-life management target wellness-oriented young professionals.
Traditional Cuisine retains the deepest consumer penetration, while Healthy Options is gaining share fastest.
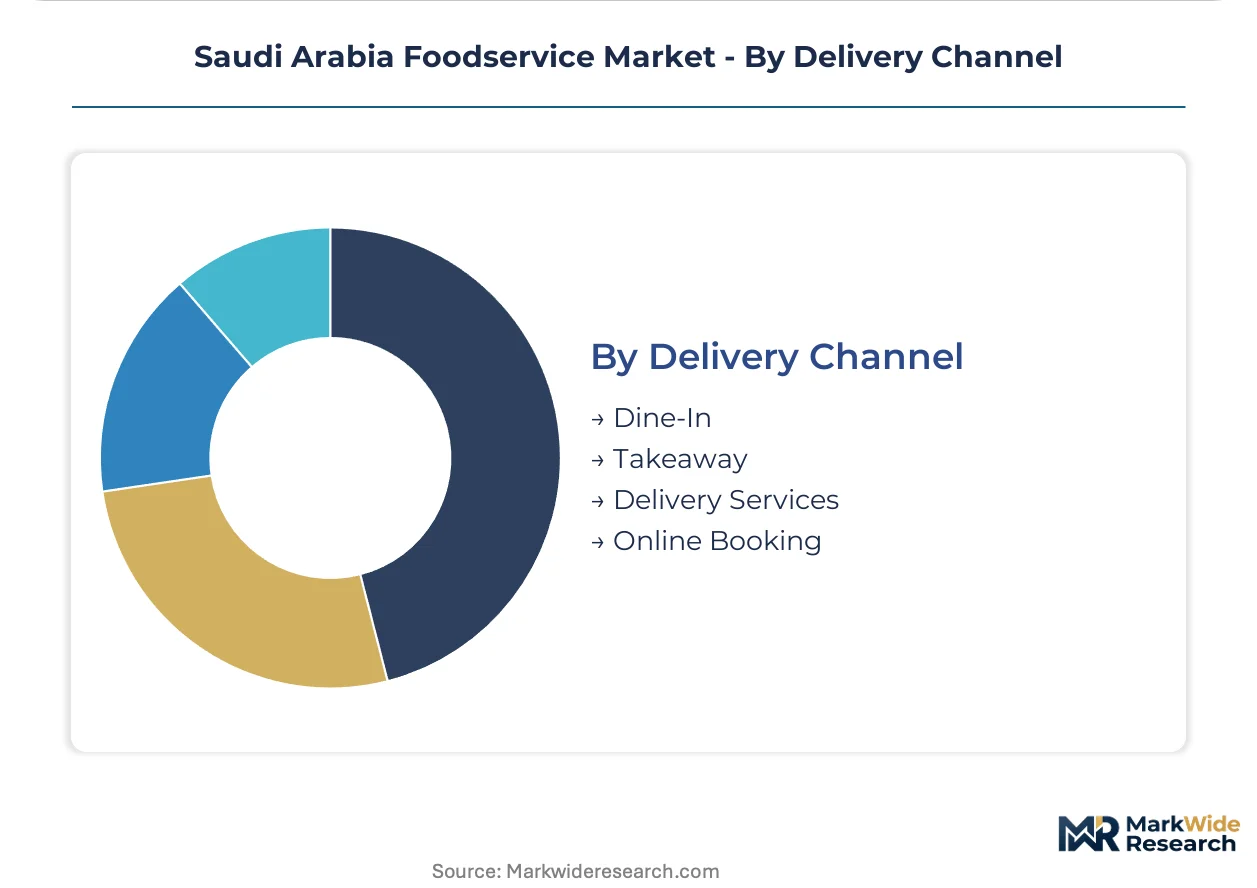
Delivery Channel:
Channel mix determines kitchen design, labor allocation, and technology stack requirements as operators balance dine-in experience investment against delivery-native operational efficiency.
- Dine-In:On-premise consumption with service labor intensity and ambiance capital requirements sustains premium pricing power in entertainment and hospitality districts.
- Takeaway:Customer-collected orders with packaging optimization and queue management systems capture convenience-oriented demand without last-mile logistics costs.
- Delivery Services:Aggregator-platform-fulfilled orders with commission structures and kitchen utilization compression reshape urban operator economics most dramatically in Riyadh's dense residential zones.
- Online Booking:Reservation systems with table management integration and deposit mechanisms reduce no-show losses for high-demand full-service formats.
Delivery Services now captures the steepest volume growth, though Dine-In maintains the highest margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Abdulaziz Port in Dammam anchors the Eastern Province's foodservice distribution network, channeling imported protein and equipment into the kingdom's largest industrial corridor.
Riyadh
Vision 2030 entertainment district construction and sovereign wealth venue development are compressing restaurant opening timelines. SFDA digital licensing mandates are accelerating technology procurement among mid-scale operators in the capital's hospitality corridor. The King Abdullah Financial District and Diriyah Gate cluster concentrate premium full-service development targeting inbound tourism flows.
Jeddah
Red Sea cruise terminal operations and religious tourism infrastructure are expanding institutional catering contract volumes. MOHAP hospitality licensing harmonization with municipal permits is reducing venue approval friction in the Western Region's commercial districts. The Jeddah Economic City and Al-Balad redevelopment zone anchor fast casual format proliferation.
Eastern Province
Aramco workforce housing and remote site operations sustain recurring revenue for industrial catering specialists. SASO quality certification requirements for imported kitchen equipment are elevating procurement standards across Dammam and Khobar. The King Fahd Industrial City cluster concentrates central kitchen development serving oil-sector client bases.
NEOM Northwest
The LINE linear city construction workforce is generating temporary foodservice demand exceeding permanent population projections. NEOM Authority regulatory sandbox provisions are testing alternative compliance frameworks for automated kitchen formats. The Oxagon industrial zone and Sindalah island development anchor hospitality pre-opening procurement cycles.
Saudi Arabia Foodservice Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in procurement, cold chain, and on-site service delivery. The Saudi foodservice market structures around three archetypes: vertically integrated catering conglomerates with institutional contract bases, airport and logistics specialists leveraging captive infrastructure, and regional service providers with municipal permit expertise. Competitive moves concentrate on multi-year contract consolidation and central kitchen capacity expansion.
Within the institutional contract tier, Gulf Catering Company and Saudi Airlines Catering Company exemplify scale-driven platform operators. Tamimi Global occupies a position representing vertically integrated supply chain control. These three anchors demonstrate how compliance depth and logistics infrastructure determine competitive position under SFDA's digitized regulatory framework.
| Leading Market Players |
|---|
| Algosaibi Services Co. Ltd. |
| Gulf Catering Company |
| Tamimi Global |
| Al-Karam Al-Arabi for Catering Services Limited |
| Gulf Mahmal Support Services Company |
| Saudi Airlines Catering Company |
| Al-Suwaidi Services Company Limited |
| Unique Catering Services |
| Nesma United Industries |
| Others |
Value Network & Pricing Analysis
Imported protein input volatility from Brazilian and Australian export markets compresses margin structures across operator tiers while simultaneously forcing supply chain restructuring toward diversified sourcing agreements and long-term contract lock-ins.
Pricing Analysis
Volume-discount tiering structures separate institutional catering contracts from single-outlet operators, with Gulf Catering Company and Saudi Airlines Catering Company capturing 15-20% procurement cost advantages through consolidated protein purchasing. Price differentiation hinges on SFDA certification grade and HACCP compliance depth, with fully digitized operators commanding premium positioning. Pricing pressure intensifies in the fast casual segment as aggregator commission structures compress kitchen-level margins. Family dining formats show lowest price sensitivity due to occasion-based spending, while young professional lunch demand exhibits highest elasticity to delivery fee fluctuations.
Supply Chain Analysis
Contract-manufacturing concentration sits with Tamimi Global's central kitchen network and Gulf Catering Company's protein processing facilities, which together anchor domestic production capacity. Geographic supply concentration draws from Brazil, Australia, and New Zealand for beef and poultry inputs, with wheat and dairy feeds from European Union and Black Sea origins. Raw material dependencies center on frozen protein shipments, specialized kitchen equipment, and cold-chain refrigerants. Supply chain risk manifests as shipping cost volatility through the Red Sea corridor. Distribution runs through King Abdulaziz Port in Dammam for Eastern Province industrial clients and Jeddah Islamic Port for Western Region hospitality clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud kitchen formats and aggregator-native brands threaten incumbent full-service operators by capturing young professional demand with asset-light economics and data-optimized menu engineering.
For Market Incumbents: Insulate institutional contract relationships through multi-year service agreements with Aramco and government clients, locking in recurring revenue against cloud kitchen displacement. Deepen backward integration into protein processing and cold-chain logistics to defend margin structures from import cost volatility. Prioritize SFDA digital compliance certification as a competitive moat that smaller operators cannot replicate. For New Entrants and Emerging Players: Build out cloud kitchen infrastructure in Riyadh's dense residential zones and Jeddah's commercial districts, where real estate costs favor dark kitchen economics over full-service formats. Target the healthy options segment, which shows fastest share growth among wellness-oriented young professionals. Deploy native app ordering with loyalty program integration to reduce aggregator dependency and capture customer data. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated catering conglomerates with compliance depth and logistics infrastructure. Long-term viability rests on exposure to Vision 2030 entertainment venue construction and tourism infrastructure buildout. Acquisition candidates should demonstrate SFDA digital licensing completion and central kitchen capacity in Riyadh-Jeddah corridor. Monitor SFDA enforcement intensity and aggregator platform commission rate changes as early signals of margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Central Kitchen Capacity Expansion | Tamimi Global's facility investments compress per-unit costs for institutional contract bidding. |
| SFDA Digital Compliance Certification | Blockchain-enabled traceability systems satisfy 2023 ingredient batch tracking mandates for premium positioning. |
| Aggregator Platform Partnership | Quick-service brands redirect marketing spend toward in-app visibility to capture young professional order flow. |
| Corporate Catering Contract Consolidation | Multi-year agreements with oil-sector clients generate recurring revenue insulated from tourism volatility. |
| Cloud Kitchen Network Deployment | Dark kitchen facilities in high-rent districts optimize kitchen utilization rates through delivery-native operations. |
Research Methodology
Desk research of SFDA regulatory filings, SASO quality certification databases, and Vision 2030 infrastructure procurement records preceded structured interviews with foodservice operations directors, HACCP compliance officers, institutional catering procurement managers, and aggregator platform commercial leads. Secondary validation drew from hospitality sector trade publications, customs import data for protein shipments, and municipal licensing records across Riyadh, Jeddah, and Dammam. Bottom-up outlet counting and top-down GDP expenditure allocation were triangulated to construct market sizing.
Assumption sets held Vision 2030 entertainment venue construction timelines and SFDA digitization mandates fixed while varying tourism arrival scenarios and protein import cost trajectories. The analytical framework modeled service type, customer archetype, food positioning, and delivery channel segmentation across the projection horizon. CAGRs were derived from trend extrapolation with regulatory inflection adjustments. Industry-specific forecast inputs included aggregator platform commission structures and central kitchen capacity utilization rates.
Practitioners should monitor SFDA enforcement intensity, Red Sea shipping cost indices, and aggregator platform market share shifts for early signals of forecast revision. Quarterly review of institutional catering contract renewal rates and cloud kitchen permit issuance volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Sandwich Toasters Market
Food Service
Hospital Food Services Market
Food Service
Supermarkets Market
Food Service
Kamado Grill Market
Food Service
Food Service Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
North America Cafes & Bars Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Latin America Online Grocery Delivery Market
Food Service
Steam Stew Pot Market
Food Service
Pizza Foodservice Market
Food Service
Food Service Dairy Products Market
Food Service
Commercial Tandoor Oven Market
Food Service
Vietnam Online Food Delivery Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
Aquarium Protein Skimmers Market