
 Virtual Kitchen Market | 2026-2036
Virtual Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Kitchen Market Intelligence
The availability of chefs and operational staff skilled in high-volume, delivery-centric food production is redrawing the industry's unit economics. This specialized labor pool allows for greater efficiency and menu diversification. Kitopi leverages a managed kitchen-as-a-service model to scale partner brands, while CloudKitchens specializes in providing the underlying real estate and infrastructure. Kitchen United operates shared kitchen spaces supporting multiple food concepts under one roof.
A virtual kitchen is a professional cooking facility designed exclusively for delivery-only food service, lacking a traditional storefront or dining area. These operations rely on integrated digital ordering systems and third-party logistics to fulfill customer orders. The Ghost Kitchen model, which involves a single brand operating from a non-public location, is seeing significant uptake due to lower overhead costs. Critical investments in Technology, particularly in Order Management Software and Kitchen Display Systems, are essential for managing order flow and ensuring operational efficiency.
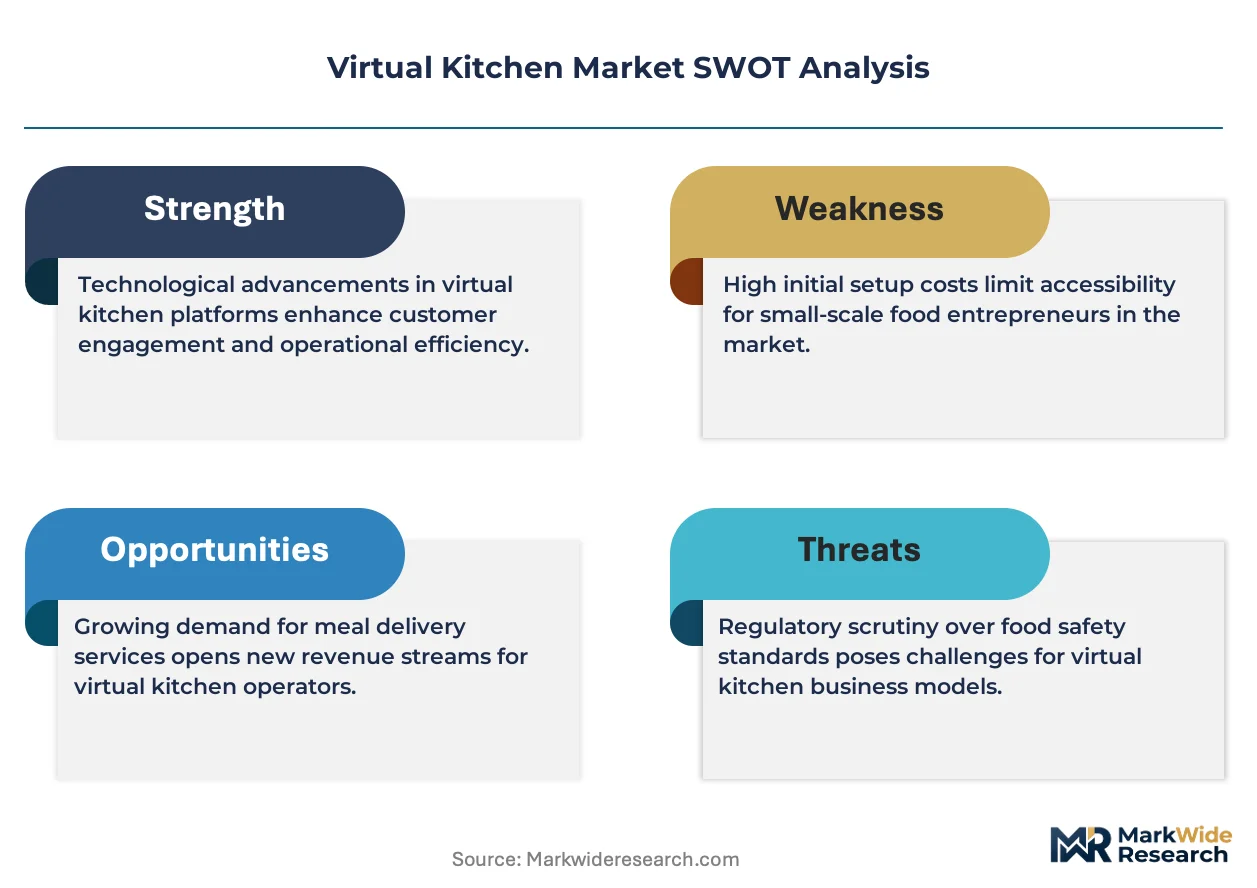
Food safety regulations from bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate stringent hygiene and handling standards. Local municipal health departments in cities such as New York and London also impose specific licensing and inspection requirements for these delivery-only facilities. Success for operators will depend on their ability to navigate complex zoning laws and rising urban real estate costs while maintaining strict compliance.
Market Dynamics
The convergence of on-demand digital platforms and specialized real estate models defines the virtual kitchen market's structure. This dynamic enables rapid scaling for food brands by separating food production from the traditional, capital-intensive restaurant storefront and dining experience.
Growth Catalysts
- Delivery Optimization Software:The integration of advanced software for route planning and order batching improves delivery times and reduces operational costs for Food Delivery Platforms, directly stimulating virtual kitchen viability.
- Urban Consumer Behavior:High population density and consumer preference for convenience in metropolitan areas like the United States' urban centers create concentrated demand that sustains the delivery-only business model.
- Lower Overhead Model:The Ghost Kitchen format, which eliminates front-of-house staff and customer-facing real estate, significantly reduces startup and operational costs, attracting new entrants and single-brand operators.
Market Restraints
- Urban Real Estate Costs:Intense competition for suitable industrial and commercial space in dense urban centers drives up lease and acquisition costs, compressing operator margins and creating significant barriers to entry.
- Complex Zoning Laws:Operators face a patchwork of municipal zoning regulations not originally designed for delivery-only facilities, leading to lengthy approval processes and uncertainty in cities from New York to London.
- Specialized Labor Scarcity:A limited pool of chefs and kitchen staff with verifiable experience in high-volume, multi-brand, delivery-focused food production constrains operational efficiency and menu complexity.
Strategic Opportunities
- Suburban Market Penetration:Extending virtual kitchen networks into less-saturated suburban areas and secondary cities presents a significant growth vector as delivery habits become more widespread beyond dense urban cores.
- Kitchen Automation Technology:Investing in robotics and AI for food preparation, cooking, and packaging can mitigate labor shortages, improve consistency, and increase throughput for high-volume concepts.
- Menu Diversification:Launching virtual brands in niche but growing categories, such as plant-based foods or specialized ethnic cuisines, allows operators to capture new consumer segments with minimal additional capital expenditure.
Industry Challenges
- Regulatory Compliance Burden:Adhering to stringent and evolving food safety standards from national bodies like the U.S. Food and Drug Administration (FDA) and local health departments requires continuous investment in training and monitoring.
- Technology Integration:Managing a fragmented technology stack, including multiple third-party delivery apps, Order Management Software, and Kitchen Display Systems, creates significant operational complexity and data silos.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Kitchen Market |
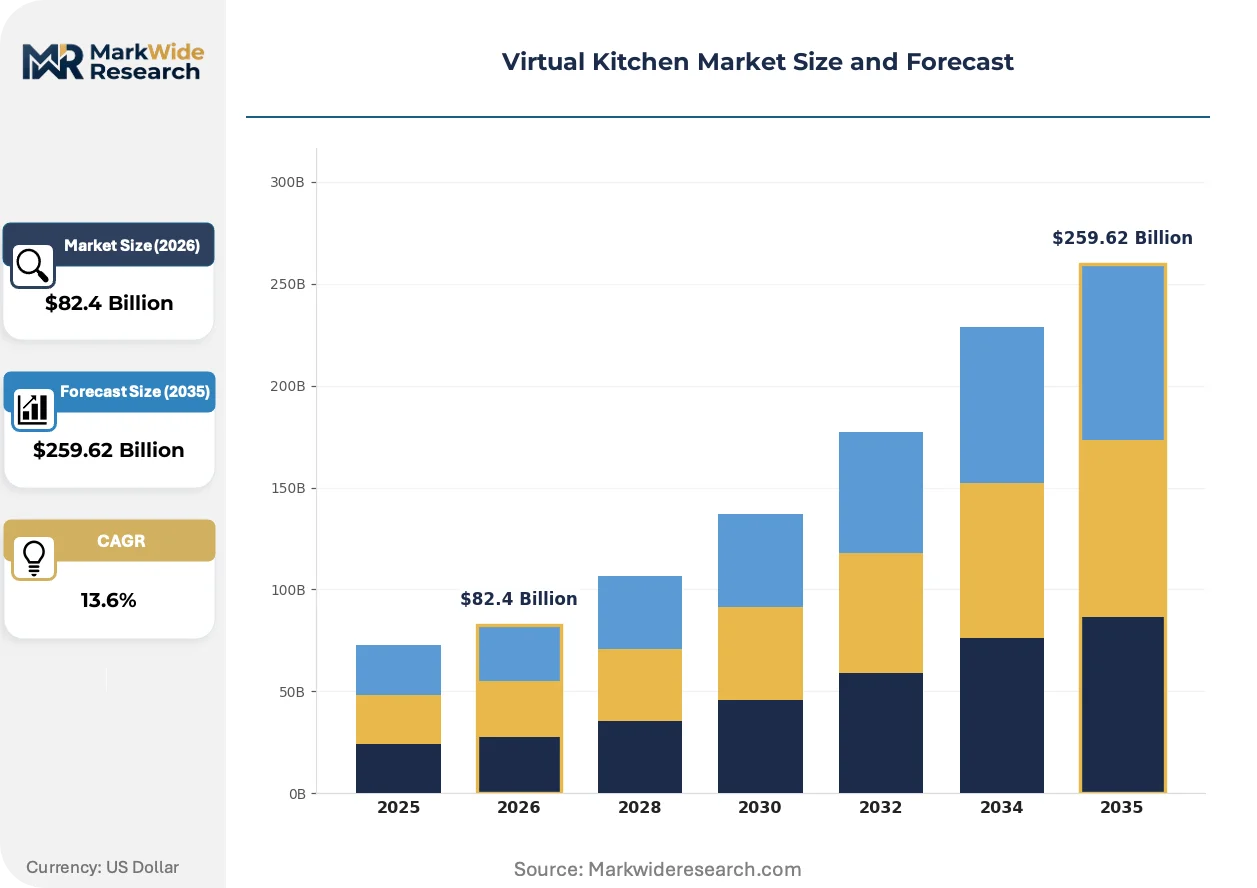
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $259.62 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Kitchen Model: Cloud Kitchen, Ghost Kitchen, Delivery-Only Kitchen, Commissary Kitchen, Satellite Kitchen Technology: Order Management Software, Kitchen Display Systems, Inventory Tracking, Delivery Optimization, Contactless Payment Application: Food Delivery Platforms, Meal Subscription Services, Catering Services, Corporate Dining, Event Catering Customer Type: Food Service Providers, Restaurants, Startups, Catering Companies, Meal Kit Producers |
| Companies Covered | Kitopi, Zuul Kitchens, CloudKitchens, Virturant, Nextrbite, Kitchen United, REEF Technology, Franklin Junction, Rebel Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Kitchen Market Strategic Shifts & Innovations
Automation and data analytics are transforming virtual kitchens from simple rental spaces into highly optimized food production facilities. This evolution prioritizes efficiency, consistency, and the ability to rapidly adapt to changing consumer tastes through data-driven menu engineering.
Modular kitchen automation systems provide robotic solutions for specific, repetitive tasks like frying, dispensing, or bowl assembly. High-volume virtual kitchen operators adopt this technology to increase throughput and ensure product consistency across multiple locations and brands. The adoption of these systems is fragmenting the traditional, linear kitchen workflow into a series of independent, automated cells that can be reconfigured for different menus.
Heightened regulatory scrutiny on food traceability is compelling operators to adopt more sophisticated digital tools. Mandates from agencies like the European Food Safety Authority (EFSA) regarding farm-to-fork tracking push the industry toward blockchain and IoT sensors for supply chain visibility. Small, independent virtual kitchen operators are most affected, as the capital investment for these compliance technologies can be substantial.
A behavioral shift toward direct brand engagement is altering how virtual kitchens acquire and retain customers. Operators are developing proprietary ordering websites and mobile apps to bypass third-party delivery aggregators, thereby owning the customer relationship and data. This trend is most prominent in competitive urban markets, where customer loyalty is a key differentiator against a sea of competing digital storefronts.
Virtual Kitchen Market Segmentation
Market segmentation provides a granular view of the virtual kitchen industry, highlighting distinct operational models, technological requirements, and target customer groups. Understanding these divisions is crucial for operators to tailor strategies and capitalize on specific growth vectors within the delivery-only food service landscape.
Kitchen Model:
The virtual kitchen market's operational models dictate how food production integrates with various delivery channels, influencing both scale and brand visibility.
- Ghost Kitchen:This model involves a single brand operating from a non-public location, designed for delivery-only service. Demand concentrates in dense urban centers within the United States, where lower overheads attract new entrants.
- Cloud Kitchen:These professional cooking facilities are exclusively for delivery-only food service, lacking a traditional storefront or dining area. Growth is prominent within Food Delivery Platforms, driven by advanced Delivery Optimization software.
- Delivery-Only Kitchen:These facilities focus solely on food preparation for off-premise consumption, optimizing for speed.
- Commissary Kitchen:Centralized production hubs prepare food for multiple brands, streamlining supply chains and reducing overhead.
- Satellite Kitchen:Smaller, decentralized units extend a main kitchen's reach, handling final assembly or localized delivery for specific zones.
Cloud Kitchen dominates installed base. Ghost Kitchen is where expansion concentrates.
Technology:
Technology adoption within virtual kitchens focuses on enhancing operational efficiency and streamlining the entire order-to-delivery workflow.
- Order Management Software:This critical investment manages the entire order flow from multiple digital ordering systems, integrating with third-party delivery platforms. Demand concentrates in high-volume operations where timely fulfillment is paramount.
- Delivery Optimization:Advanced software for route planning and order batching improves delivery times and reduces operational costs for Food Delivery Platforms. Its integration stimulates virtual kitchen viability in congested urban environments.
- Kitchen Display Systems:These digital screens replace paper tickets, displaying orders to kitchen staff for efficient preparation.
- Inventory Tracking:Systems monitor ingredient stock levels, automate reordering, and minimize waste for continuous supply.
- Contactless Payment:Secure digital payment solutions facilitate seamless transactions, enhancing customer experience and operational speed.
Order Management Software remains foundational. Delivery Optimization represents the fastest-growing trajectory for competitive advantage.
Application:
Virtual kitchen applications extend across various service models, leveraging digital platforms to reach diverse customer segments.
- Food Delivery Platforms:This application involves virtual kitchens fulfilling orders placed through major third-party aggregators, forming the primary revenue channel. Demand concentrates in dense urban centers within the United States, supporting the delivery-only model.
- Meal Subscription Services:Virtual kitchens prepare and package pre-ordered meals on a recurring basis, offering convenience and dietary customization. This segment gains traction in suburban markets where consistent meal planning appeals to busy households.
- Catering Services:Virtual kitchens fulfill bulk orders for businesses or private events, leveraging high-volume production without a physical storefront.
- Corporate Dining:These operations provide daily meal solutions for corporate clients, often through managed service contracts, focusing on efficiency.
- Event Catering:Specialized virtual kitchens handle food preparation for large-scale events, requiring flexible menu options and robust logistical support.
Food Delivery Platforms drive significant market share. Meal Subscription Services are expanding most quickly due to changing consumer habits.
Customer Type:
The virtual kitchen market serves a broad spectrum of customer types, each with distinct operational needs and growth strategies.
- Restaurants:Established restaurant brands utilize virtual kitchens to expand their delivery footprint without significant capital expenditure on new physical locations. This customer type concentrates in competitive urban markets, where increasing delivery volume is a strategic priority.
- Food Service Providers:These entities manage large-scale food operations for institutions or corporate clients, leveraging virtual kitchens for efficient centralized production. Their demand is driven by consistent quality and cost control.
- Startups:New food concepts and entrepreneurs enter the market with lower overheads through virtual kitchen models, testing new menus and scaling rapidly.
- Catering Companies:These businesses use virtual kitchens to streamline food preparation for events, enhancing capacity and reducing the need for dedicated event kitchen space.
- Meal Kit Producers:Companies assembling pre-portioned ingredient kits utilize virtual kitchen infrastructure for efficient ingredient handling, assembly, and packaging.
Restaurants represent a dominant customer segment. Startups are a key growth area, leveraging the low-cost entry model.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Food and Drug Administration (FDA) food safety regulations anchor operational standards for virtual kitchens across the United States. These stringent guidelines ensure hygiene and proper handling, directly influencing business models nationwide. Demand for delivery-only services consistently thrives in major urban areas.
United States
Consumer preference for convenience and high population density in urban centers drives significant demand for virtual kitchens. The U.S. Food and Drug Administration (FDA) dictates stringent hygiene standards for all food service operations. New York City's municipal health department imposes specific licensing requirements, impacting numerous delivery-only facilities.
United Kingdom
On-demand digital platforms and the growth in delivery-centric food production sustain the virtual kitchen market. The Food Standards Agency (FSA) enforces comprehensive food safety and hygiene protocols across the country. London's local municipal health departments impose specific inspection requirements, driving compliance efforts among operators.
Germany
Expanding digital platform usage and urban consumer demand for diverse food options characterize the German market. The European Food Safety Authority (EFSA) mandates traceability, influencing supply chain visibility requirements for all operators. Berlin's vibrant startup ecosystem fosters new virtual kitchen concepts, testing innovative delivery models.
China
Massive urban populations and the rapid adoption of food delivery applications generate substantial market activity. China's State Administration for Market Regulation (SAMR) oversees food safety, requiring strict adherence to operational guidelines. Shanghai's dense metropolitan area sees significant investment in cloud kitchen infrastructure, supporting rapid brand scaling.
India
A growing middle class, increasing smartphone penetration, and convenience-seeking consumers fuel market expansion. The Food Safety and Standards Authority of India (FSSAI) sets hygiene and handling standards for food service operations. Bengaluru's tech-savvy population supports the expansion of delivery-only models, with many startups leveraging shared kitchen spaces.
Virtual Kitchen Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the virtual kitchen market. This market structure exhibits a blend of consolidation at the platform level and fragmentation among individual kitchen operators. Strategic archetypes include real estate providers, managed kitchen-as-a-service operators, and technology solution developers. Capacity expansion and strategic partnerships are dominant competitive moves.
Within the managed kitchen-as-a-service tier, Kitopi exemplifies scaling partner brands through its operational expertise. CloudKitchens occupies a position as a primary provider of underlying real estate and infrastructure for delivery-only operations. Kitchen United anchors the shared kitchen space model, supporting multiple food concepts under one roof. These entities collectively represent the diverse operational approaches defining the market landscape. Their business models address different facets of virtual kitchen development and deployment.
| Leading Market Players |
|---|
| Kitopi |
| Zuul Kitchens |
| CloudKitchens |
| Virturant |
| Nextrbite |
| Kitchen United |
| REEF Technology |
| Franklin Junction |
| Rebel Foods |
| Others |
Cost & Logistics Intelligence
Capacity reservation contracts for virtual kitchen spaces secure operational continuity and price predictability for food brands. These agreements mitigate volatility in real estate costs and ensure access to specialized cooking facilities.
Pricing Analysis
Regional disparities in urban real estate costs create significant price spreads for virtual kitchen rentals. The market primarily operates on a contract-based model for kitchen space and a SaaS-tiered model for essential software. Geographic location and volume scale drive price differentiation, with prime urban centers commanding higher rates. Pricing softness reflects intense competition among kitchen providers and pressure from third-party delivery aggregators. Startups exhibit high price sensitivity, while established restaurant brands prioritize consistent service and location.
Supply Chain Analysis
Efficient inventory management and short lead times are critical for virtual kitchens to maintain food freshness and operational agility. Supply for specialized virtual kitchen facilities concentrates heavily in dense urban centers across the United States and major European cities like London. Operations draw from local fresh produce markets and specialized food packaging suppliers. Specialized labor scarcity represents a key structural risk, impacting kitchen throughput and service quality. Distribution primarily runs through third-party food delivery platforms and operator-owned digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The virtual kitchen market represents a high-growth disruption, transforming food service economics through specialized delivery-only models. Advanced Delivery Optimization software integration acts as a key technological inflection, enabling rapid scalability and efficiency.
For Market Incumbents: Fortify core market positions by investing heavily in kitchen automation technology to counter rising labor costs and improve consistency. Consolidate smaller, tech-enabled kitchen operators to expand geographic reach and reduce competitive fragmentation. This strategy helps mitigate threats from new entrants leveraging lower overheads and addresses technology integration complexity. Prioritize stringent food safety certification to differentiate against less regulated competitors.
For New Entrants and Emerging Players: Unmet demand for specialized ethnic cuisines in suburban markets presents a significant service-layer gap for new entrants. Target under-served secondary cities and less saturated suburban areas with unique menu offerings, such as plant-based foods. Leverage low overhead Ghost Kitchen models to test new concepts quickly and scale efficiently. A direct-to-consumer go-to-market angle, using proprietary ordering apps, cultivates customer loyalty and bypasses aggregator fees.
For Investors and Strategic Acquirers: Managed kitchen-as-a-service providers with proprietary technology platforms represent attractive acquisition targets for long-term sustainable growth. These entities offer established operational expertise and scalable infrastructure, driving efficiency gains across the value chain. Focus on companies demonstrating strong integration capabilities with diverse food brands. Watch for increased regulatory clarity regarding zoning laws and food safety standards for delivery-only facilities as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Kitchen Automation | Reduces labor costs and increases throughput for high-volume delivery operations. |
| Develop Proprietary Ordering Platforms | Bypasses third-party aggregator fees and owns the customer relationship and data. |
| Expand into Suburban Markets | Captures new consumer segments as delivery habits spread beyond urban cores. |
| Acquire Delivery Optimization Software Firms | Enhances route planning and order batching, improving delivery efficiency and costs. |
| Pursue Niche Menu Diversification | Addresses specific dietary preferences and captures new consumer demand with minimal capital. |
Research Approach
Operator-level perspectives from virtual kitchen executives, food delivery platform leaders, and restaurant owners anchored the qualitative base for this analysis. Primary interviews were triangulated with extensive secondary validation from regulatory bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). Industry association publications and financial disclosures further informed the bottom-up and top-down data triangulation.
Sensitivity analysis informed the quantitative modeling framework, assessing the impact of various market dynamics across the analysis window. Segmentation dimensions included Kitchen Model, Technology, Application, Customer Type, and key geographic regions. Compound annual growth rates were derived from historical trends and projected impacts of identified growth catalysts. Urban population density and digital platform penetration served as critical forecast inputs.
Material uncertainties — primarily evolving food safety regulations and rapid kitchen automation shifts — sit outside the modeled envelope. Forecasts reflect a specific set of assumptions regarding market development and adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Online Grocery Market
Food Service
Sandwich Toasters Market
Food Service
Turkey Food Service Market
Food Service
Australia Foodservice Market
Food Service
Haute Cuisine Market
Food Service
Food Service Disposables Market
Food Service
Food Trucks Market
Food Service
Train Catering Service Market
Food Service
Egypt Food Service Market
Food Service
Contract Blending Services Market
Food Service
Fast Food Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Plates Market
Food Service
Saudi Arabia Inflight Catering Market
Food Service
Japan Foodservice Market
Food Service
Cutting Boards Market