
 Global Food Retail Market | 2026-2036
Global Food Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Retail Market Analysis
The restaurant and food service vertical is shifting a larger share of procurement toward digital wholesale platforms and direct supplier relationships. Walmart leverages its grocery supercenter network to sustain price leadership in North American fresh produce. Schwarz Gruppe anchors its competitive position through private-label dominance and discount-format density across Europe. Amazon.com competes on fulfillment speed, extending same-day grocery delivery to dense urban corridors.
Food retail encompasses the commercial sale of edible goods through physical and digital channels, involving temperature-controlled logistics, shelf-life management, and inventory turnover optimization to preserve nutritional integrity and safety. Supermarkets and hypermarkets occupy the core volume channel, though margin pools are thinning as discount formats capture price-sensitive households. Online retail represents the fastest-growing distribution channel, driven by algorithmic personalization and last-mile infrastructure investments. Fresh produce commands premium positioning due to perishability constraints and shorter replenishment cycles.
FDA food safety standards, EU Green Deal sustainability frameworks, and China's SAMR food labeling rules collectively elevate compliance costs while restricting market access for non-compliant suppliers. REACH chemical restrictions on food-contact materials and FDA traceability mandates are forcing upstream investments in digital supply chain visibility. Stakeholders must monitor regulatory divergence between major trading blocs when allocating capital across sourcing networks and format expansion.
Market Dynamics
Digital wholesale procurement is compressing traditional distributor margins while EU Green Deal packaging mandates and FDA traceability rules force simultaneous compliance investments across multi-jurisdictional supply chains.
Growth Catalysts
- Urban Middle-Class Expansion:Households in China, India, and Brazil are reallocating discretionary spending toward protein-rich and convenience-oriented food categories, expanding addressable market volume for modern retail formats.
- EU Green Deal Packaging Rules:Mandatory recyclability targets and extended producer responsibility frameworks are accelerating retailer investment in sustainable private-label development and circular supply chain partnerships.
- Cold Chain Digitization:IoT-enabled temperature monitoring and predictive spoilage algorithms are reducing fresh produce loss rates and enabling longer distribution radii for perishable categories.
Market Restraints
- Input Cost Volatility:Fertilizer and energy price swings transmit directly into fresh produce procurement costs, compressing gross margins for retailers without backward integration into agricultural sourcing.
- Supply Concentration Risk:Brazil, Argentina, and Ukraine collectively dominate global grain and oilseed export volumes, creating vulnerability to climate-driven harvest disruptions and export restriction cascades.
- Regulatory Friction:Divergent FDA and EFSA approval timelines for novel food ingredients and cultivated proteins fragment product launch strategies and delay cross-border assortment standardization.
Strategic Opportunities
- Underpenetrated Rural India:Organized retail penetration in India's tier-3 and tier-4 cities remains below 10 percent, creating first-mover advantages for format-adapted small-store networks and regional distribution partnerships.
- Regulatory Tailwind from China's SAMR:Enhanced food labeling transparency mandates and e-commerce platform liability rules are elevating compliance barriers that favor scaled retailers with dedicated quality assurance infrastructure.
- Quick Commerce Convergence:Integration of dark store micro-fulfillment with ride-hailing platform last-mile networks is collapsing grocery delivery windows to under 30 minutes in dense urban corridors.
Industry Challenges
- Cold Chain Engineering Talent Scarcity:Refrigeration system design and perishable inventory optimization require specialized expertise that outpaces current vocational training pipeline output in emerging markets.
- Legacy ERP Integration Friction:Real-time inventory visibility systems must interface with decades-old warehouse management architectures, delaying unified demand forecasting and automated replenishment deployment.
- Multi-Jurisdictional Certification Timelines:Organic, halal, and carbon-neutral claim verifications require 12-24 month approval cycles that mismatch seasonal product development calendars and competitor response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Retail Market |
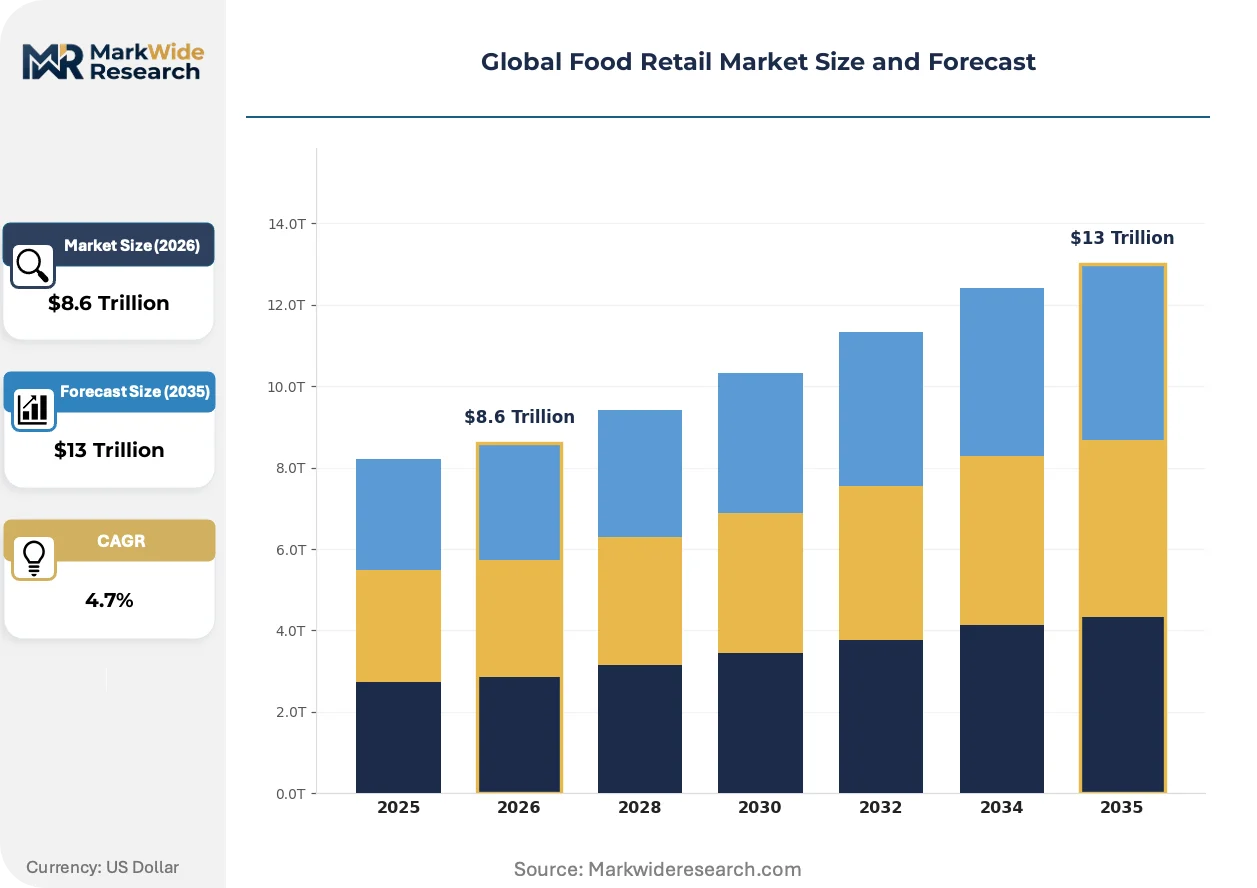
| Market Size in 2026 | $8.6 Trillion |
| Market Size in 2035 | $13 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Produce, Packaged Goods, Dairy Products, Frozen Foods Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Hypermarkets Customer Type: Households, Restaurants, Food Service Providers, Institutions Price Tier: Premium, Mid-Range, Discount, Value |
| Companies Covered | Walmart, Amazon.com, Schwarz Gruppe, Aldi, Carrefour, The Kroger Company, Costco Wholesale, Tesco, AEON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Retail Market Emerging Trajectories
Algorithmic demand forecasting and automated fulfillment infrastructure are compressing replenishment cycles while regulatory transparency mandates reshape supplier qualification protocols across major trading blocs.
Computer vision shelf-monitoring systems equipped with edge AI processors are electrifying in-store inventory management by automating gap detection, price label verification, and planogram compliance audits. Discounters in Germany and France are deploying these systems at scale to sustain labor productivity in high-SKU-density formats. The technology is compressing restocking response times from hours to minutes while reducing phantom inventory discrepancies that previously distorted replenishment signals.
REACH chemical restrictions on food-contact materials are forcing upstream reformulation of packaging films, coatings, and adhesives used across European retail private-label portfolios. Suppliers must submit comprehensive safety dossiers to ECHA for substances above threshold tonnages, extending qualification timelines for new packaging innovations. Fresh produce and ready-meal categories face the steepest compliance burden given their direct food-contact surface area and temperature-dependent migration risk profiles.
Restaurant and food service buyers are consolidating procurement through verticalized digital platforms that disintermediate traditional broadline distributors. These platforms aggregate demand across independent operators to extract volume-tier pricing previously reserved for national chain accounts. The shift is most visible in Brazil and Mexico, where fragmented independent restaurant density supports platform network effects and supplier onboarding velocity.
Global Food Retail Market Segmentation
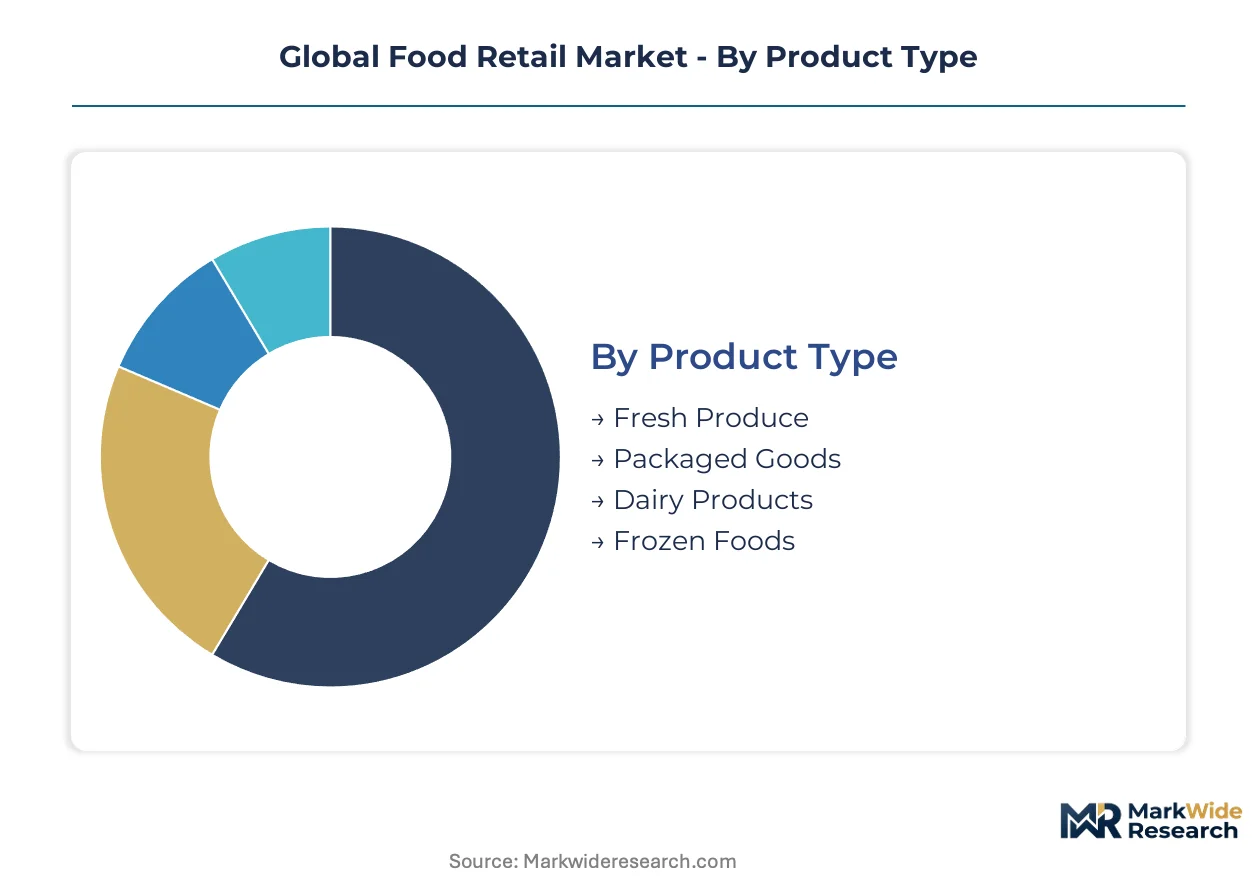
Food retail segmentation reveals how procurement priorities diverge across temperature sensitivity, purchase frequency, and buyer sophistication. Each axis exposes distinct margin structures and capital intensity requirements that shape format strategy and supply chain design.
Product Type:
Buyers prioritize shelf-life certainty and nutritional integrity differently depending on household composition and meal preparation habits.
- Fresh Produce:Temperature-controlled logistics preserve organoleptic properties through cold chain handoffs from farm to shelf. Demand concentrates in China's tier-1 cities and India's metropolitan corridors where dual-income households trade preparation time for convenience.
- Packaged Goods:Extended shelf stability enables centralized manufacturing and long-haul distribution economics. Brazil's expanding middle class drives volume growth for fortified and convenience-oriented SKUs.
- Dairy Products:Chilled distribution mandates constrain sourcing radii and favor regional processing consolidation.
- Frozen Foods:Deep-freeze infrastructure requirements limit format penetration to hypermarkets and scaled supermarkets with dedicated freezer aisles.
Packaged goods leads volumes today; fresh produce is gaining share fastest.
Distribution Channel:
Format economics hinge on real estate productivity, labor intensity, and inventory velocity tradeoffs.
- Supermarkets:Mid-size footprints balance SKU breadth with neighborhood accessibility. Germany's discounters compress operating costs through limited assortment and private-label concentration.
- Online Retail:Algorithmic personalization and micro-fulfillment infrastructure collapse delivery windows in dense urban corridors. India's quick-commerce platforms are scaling dark store networks to serve 30-minute delivery expectations.
- Convenience Stores:High-frequency, small-basket trips favor impulse categories and ready-to-eat positioning.
- Hypermarkets:Destination formats anchor one-stop shopping with parking-adjacent locations and bulk pricing.
Supermarkets anchor current volume; online retail climbs the fastest.
Customer Type:
Procurement scale and specification rigor separate institutional buyers from household purchasers.
- Households:Fragmented demand aggregates through retail intermediaries with preference for assortment breadth and price transparency.
- Restaurants:Independent operators in Brazil and Mexico consolidate purchasing through digital wholesale platforms that disintermediate traditional distributors.
- Food Service Providers:Contract catering and institutional feeding operations require HACCP-compliant supply chains with documented traceability.
- Institutions:Schools, hospitals, and government facilities mandate competitive bidding and certified supplier qualification.
Households dominate absolute spend; restaurants are expanding procurement most aggressively.
Price Tier:
Income stratification and occasion-based tradeoffs segment willingness-to-pay across identical product categories.
- Premium:Organic, provenance-certified, and specialty-positioned SKUs command shelf space in affluent urban precincts.
- Mid-Range:Branded national products balance quality signaling with accessible pricing for mainstream households.
- Discount:Hard discounters in France and Germany deploy private-label exclusivity to strip out marketing and packaging costs.
- Value:Entry-price positioning captures price-sensitive segments through streamlined assortment and bulk formats.
Mid-range holds the largest wallet share; premium tier shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between the FDA's traceability mandates and the EU Green Deal's packaging rules is creating compliance-cost arbitrage that favors scaled retailers with dedicated quality infrastructure. Producers and distributors are reallocating capacity toward jurisdictions where regulatory clarity reduces certification friction.
United States
Urban households in New York, Los Angeles, and Chicago are consolidating weekly shopping into fewer, larger-format trips that favor supercenter density. The FDA's Food Safety Modernization Act traceability rules are forcing upstream investments in digital lot-tracking systems. Walmart leverages its Bentonville, Arkansas headquarters and distribution network to sustain price leadership in fresh produce procurement.
Germany
Price-sensitive consumers in Berlin, Hamburg, and Munich cluster around hard-discount formats with private-label concentration. The EU Green Deal's extended producer responsibility frameworks accelerate retailer investment in recyclable packaging portfolios. Schwarz Gruppe anchors its competitive position through Lidl and Kaufland banner density across the Rhine-Ruhr and Bavarian industrial corridors.
China
Tier-1 city households in Shanghai, Beijing, and Shenzhen trade preparation time for convenience-oriented fresh and ready-meal categories. SAMR's enhanced food labeling transparency mandates elevate compliance barriers that favor scaled retailers with dedicated quality assurance infrastructure. Alibaba and JD.com compete on fulfillment speed, extending same-day grocery delivery through dark-store networks in the Yangtze River Delta cluster.
Brazil
Expanding middle-class households in São Paulo, Rio de Janeiro, and Belo Horizonte are reallocating discretionary spending toward protein-rich and convenience-oriented food categories. ANVISA's food safety certification requirements restrict market access for non-compliant suppliers while favoring organized retail expansion. Independent restaurant operators in São Paulo state consolidate purchasing through digital wholesale platforms that disintermediate traditional broadline distributors.
India
Dual-income households in Mumbai, Delhi-NCR, and Bangalore drive demand for fresh produce with shorter replenishment cycles. FSSAI's food safety and labeling regulations are tightening traceability requirements for modern retail formats. Organized retail penetration in tier-3 and tier-4 cities remains below 10 percent, creating first-mover advantages for format-adapted small-store networks and regional distribution partnerships in Gujarat and Tamil Nadu.
Global Food Retail Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with scale-driven retailers dominating volume channels while regional operators capture niche positioning. The vendor base concentrates around three strategic archetypes: discount-format specialists with private-label exclusivity, omnichannel platforms with fulfillment infrastructure, and wholesale clubs with membership-based purchasing power. Dominant competitive moves include M&A-driven format expansion and backward integration into agricultural sourcing to control input cost volatility.
Within the discount-format tier, Schwarz Gruppe and Aldi exemplify the private-label-dominant archetype through limited-assortment efficiency. Walmart represents the scale-driven supercenter model with grocery-anchored one-stop shopping. Amazon.com occupies the omnichannel fulfillment vector, competing on algorithmic personalization and last-mile speed rather than price leadership alone.
| Leading Market Players |
|---|
| Walmart |
| Amazon.com |
| Schwarz Gruppe |
| Aldi |
| Carrefour |
| The Kroger Company |
| Costco Wholesale |
| Tesco |
| AEON |
| Others |
Supply Flow & Price Mechanics
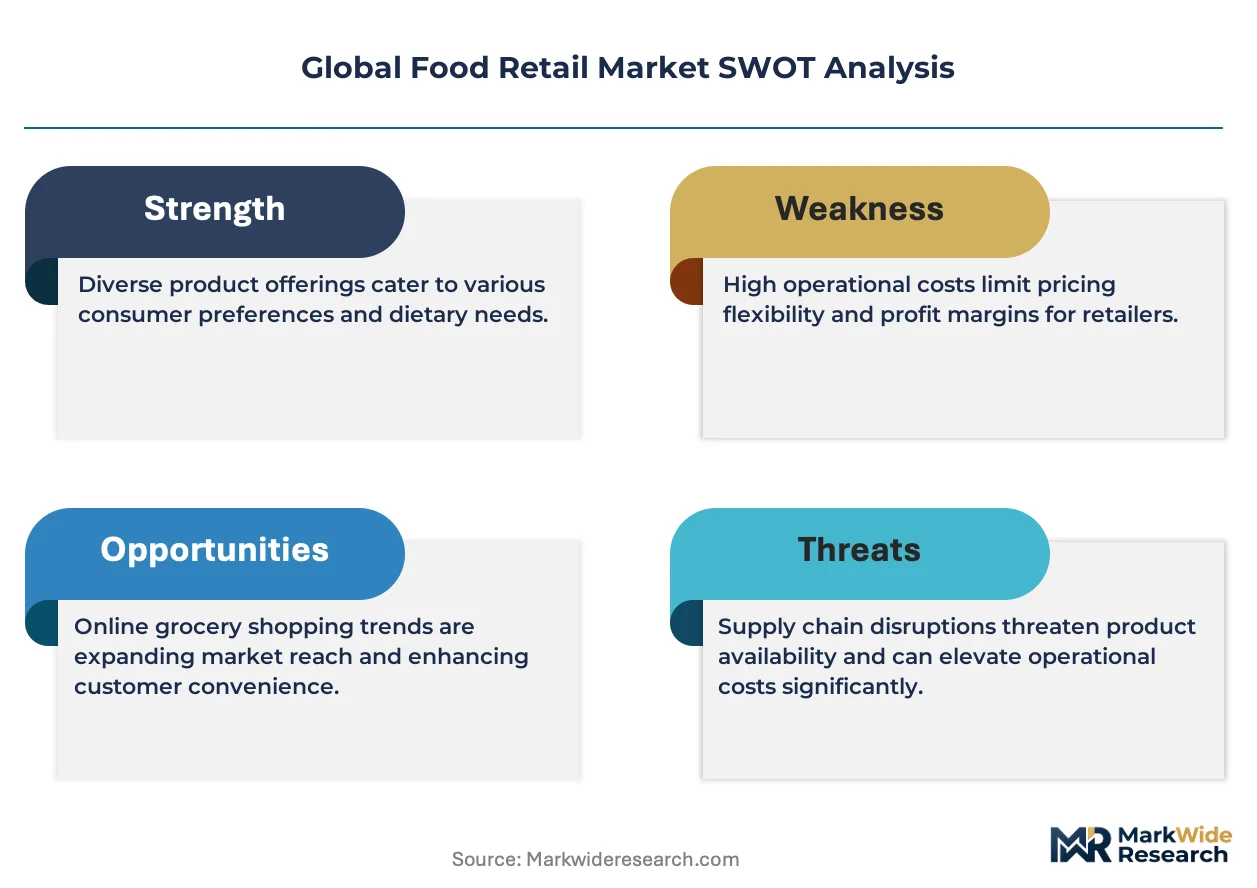
Global grain price indices cascade through food retail supply chains into three distinct pricing tiers, with fertilizer and energy cost volatility compressing margins at the discount end while premium organic positioning captures pricing power in affluent urban corridors across China, India, and Brazil.
Pricing Analysis
Retailer markup layers stratify across premium, standard, and economy tiers based on certification grade and volume scale. Organic and provenance-certified SKUs command shelf space premiums in Shanghai, Beijing, and Shenzhen supermarkets. Cost compression in the discount tier intensifies as hard discounters strip out marketing expenditure through private-label exclusivity. Price sensitivity concentrates among dual-income households in India's tier-3 and tier-4 cities, while least sensitivity sits with urban professionals trading preparation time for convenience-oriented fresh and ready-meal categories.
Supply Chain Analysis
Refrigerated freight costs anchor distribution economics for temperature-sensitive categories across Brazil, Argentina, and Ukraine grain corridors. Cold chain infrastructure draws from specialized refrigeration system design expertise that outpaces vocational training pipeline output in emerging markets. Single-source vulnerability concentrates in Brazilian and Argentine oilseed export volumes exposed to climate-driven harvest disruptions. Distribution runs through scaled supermarket and hypermarket networks in Germany and France, with quick-commerce dark stores collapsing last-mile delivery windows in dense urban clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food retail margin expansion hinges on backward integration into agricultural sourcing that captures input cost volatility, alongside premium-tier acceleration in organic and provenance-certified positioning.
For Market Incumbents: Deepen private-label concentration to defend against digital wholesale platform disintermediation threatening traditional distributor relationships. Invest in cold chain digitization with IoT-enabled temperature monitoring to reduce fresh produce loss rates. Add regional processing consolidation capacity in India's Gujarat and Tamil Nadu to control dairy distribution radii. For New Entrants and Emerging Players: Quick-commerce platform partnerships offer the lowest barrier entry path into India's underpenetrated tier-3 and tier-4 cities where organized retail sits below 10 percent penetration. Target independent restaurant operators in São Paulo state consolidating purchasing through digital wholesale platforms. Deploy format-adapted small-store networks with regional distribution partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with scaled retailers possessing dedicated quality assurance infrastructure capable of absorbing EU Green Deal packaging compliance costs and China's SAMR labeling mandates. Long-term viability favors operators with captive cold chain engineering talent and unified demand forecasting systems. Watch for regulatory divergence between FDA traceability timelines and EFSA approval windows as the inflection indicator for cross-border assortment standardization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Sourcing | Captures fertilizer and energy cost volatility that otherwise compresses fresh produce gross margins. |
| Cold Chain Digitization Investment | IoT-enabled temperature monitoring reduces spoilage rates and extends distribution radii for perishables. |
| Quick-Commerce Dark Store Expansion | Collapses delivery windows to under 30 minutes in dense urban corridors across China's Yangtze River Delta. |
| Sustainable Packaging Portfolio Reformulation | REACH chemical restrictions on food-contact materials force upstream safety dossier submissions to ECHA. |
| Regional Distribution Partnership Formation | First-mover advantages accrue in India's tier-3 and tier-4 cities below 10 percent organized retail penetration. |
Methodological Framework
Direct dialogue with supermarket category buyers, cold chain logistics directors, restaurant procurement managers, and food safety compliance officers combined with secondary validation from FDA filings, EU Green Deal regulatory texts, SAMR labeling directives, and customs trade data. Bottom-up and top-down triangulation cross-checks volume estimates against channel shipment data and retail audit records.
Bottom-up modeling aggregates segment-level demand across product type, distribution channel, customer type, and price tier dimensions. Top-down validation benchmarks aggregate market size against macroeconomic food expenditure trends. CAGRs derive from trend extrapolation moderated by regulatory impact assessment and technology adoption curves. Forecast inputs include urban middle-class household formation rates and cold chain infrastructure investment pipelines.
Climate-driven harvest disruptions, export restriction cascades, and regulatory approval timeline divergence are the dominant revision risks that could compress or extend growth trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Flat Top Grills Market
Food Service
Food Trucks Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Food Away from Home Market
Food Service
Contract Blending Services Market
Food Service
Snack Subscription Box Service Market
Food Service
Haute Cuisine Market
Food Service
Bahrain Food Service Market
Food Service
Latin America Inflight Catering Market
Food Service
Europe Pizza Oven Market
Food Service
Italy Foodservice Market
Food Service
Mexico Foodservice Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Commercial Pizza Oven Market
Food Service
Germany Foodservice Market
Food Service
Lunch Takeout Market