
 Onboard Rail Catering Market | 2026-2036
Onboard Rail Catering Market Size, Share, and Industry Trends Forecast 2026-2036
Onboard Rail Catering Market Analytics
A shift from in-house kitchens toward outsourced meal provisioning is recalibrating how rail operators structure food service contracts. Deutsche Bahn AG leverages centralized procurement hubs across its Intercity network to standardize ingredient sourcing. Newrest Group Services SAS anchors its competitive position through long-term concession agreements with European high-speed operators. IRCTC Limited dominates India's vast onboard catering ecosystem through integrated kitchen infrastructure and vendor accreditation systems.
Onboard rail catering encompasses the preparation, packaging, and distribution of food and beverage products consumed during train journeys, typically involving chilled-chain logistics, halal or kosher certification compliance, and tray-set assembly for seat-back or buffet delivery. Meal Service commands the largest revenue share among service types due to fixed-menu obligations on overnight and long-haul routes, while Pre-Order Service via mobile platforms represents the fastest-expanding delivery mode as operators digitize passenger touchpoints. Business Travelers generate premium pricing pools through demand for dietary-specific menus and express turnaround times, whereas Rail Operators as direct clients increasingly bundle catering into total service concession packages.
EFSA hygiene protocols and the EU Green Deal packaging mandates shape product specifications across European cross-border services, while India's FSSAI licensing requirements govern kitchen infrastructure and vendor hygiene ratings for all IRCTC-affiliated suppliers. The US FDA and USDA jointly regulate interstate rail catering through HACCP-aligned food safety plans for Amtrak's Northeast Corridor operations. Stakeholders must monitor how digital pre-order penetration reshapes kitchen capacity planning and whether regulatory packaging timelines accelerate capital deployment into compostable container supply chains.
Market Dynamics
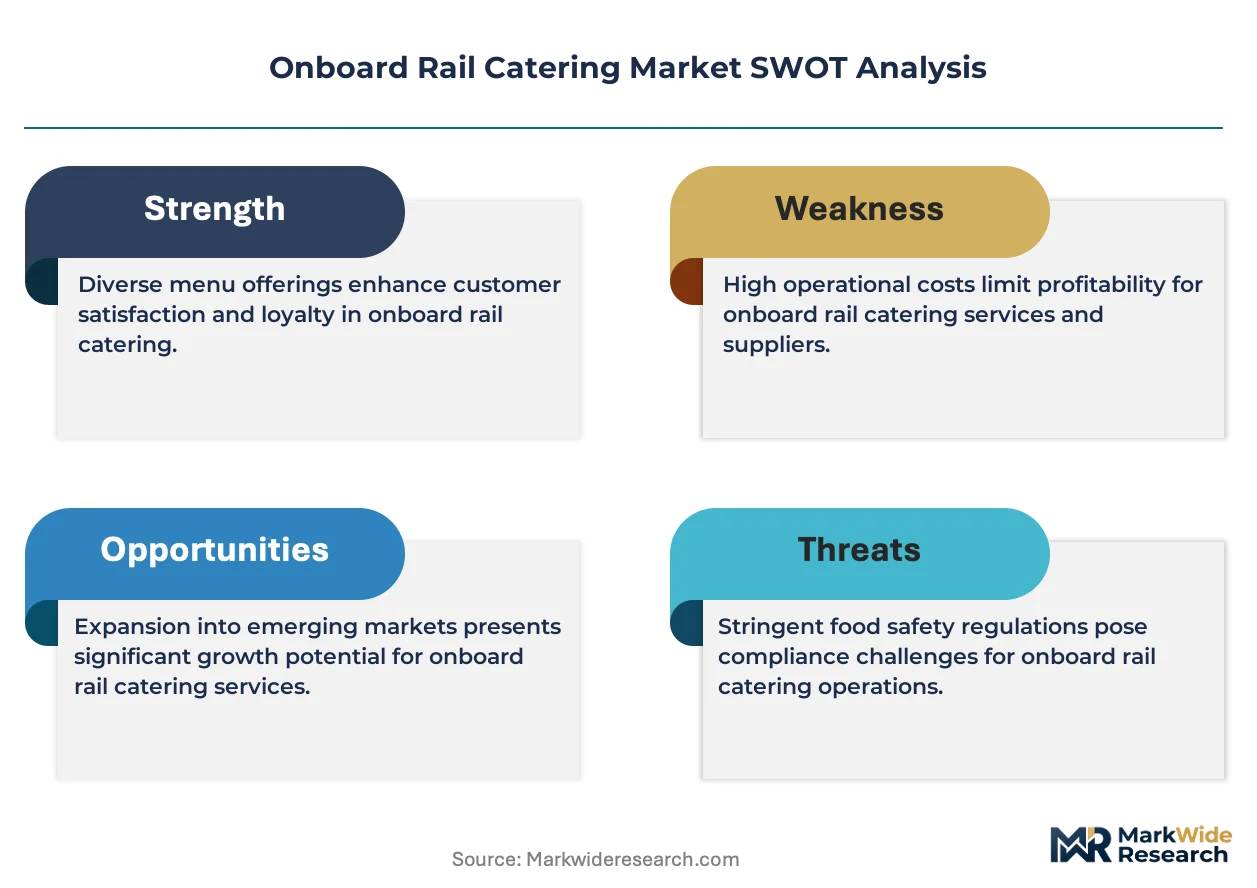
Long-distance rail operators are dismantling in-house catering infrastructure in favor of concession-based outsourcing, forcing specialized food service providers to absorb capital-intensive kitchen networks and regulatory compliance burdens previously borne by state railways.
Growth Catalysts
- EFSA Hygiene Mandates:Standardized food safety protocols across EU cross-border routes compel rail operators to consolidate catering contracts with certified specialists capable of pan-European compliance documentation.
- Halal Certification Expansion:Muslim-majority travel corridors through Malaysia, Indonesia, and Turkey require dedicated supply chains, creating specialized provisioning demand that generalist caterers cannot fulfill.
- Mobile Pre-Order Platforms:Seat-back QR codes and app-based meal scheduling compress kitchen production windows while expanding per-passenger revenue capture on premium routes.
Market Restraints
- Single-Use Plastic Bans:EU Green Deal packaging timelines force premature capital redeployment into compostable container supply chains before unit economics mature.
- Chilled-Chain Energy Costs:Refrigerated logistics from central kitchens to rolling stock consume disproportionate operating budgets, particularly on electrified corridors with limited auxiliary power.
- Route Fragmentation:National rail networks maintain incompatible procurement standards, preventing economies of scale across what should be contiguous European corridors.
Strategic Opportunities
- FSSAI-Accredited Vendor Networks:India's state-level food safety ratings create tiered supplier qualification systems that favor early movers in kitchen infrastructure consolidation.
- Kosher-Halal Dual Certification:Overlapping dietary compliance requirements on Middle Eastern and North American routes enable single-kitchen, multi-standard production efficiency.
- Subscription Meal Programs:Frequent traveler loyalty integrations with pre-paid catering credits lock in recurring revenue streams independent of ticket pricing volatility.
Industry Challenges
- HACCP Documentation Burden:Continuous temperature logging and batch traceability requirements demand dedicated compliance personnel at every kitchen node, inflating fixed costs.
- Tray-Set Assembly Labor:Manual packaging of seat-back meal components resists automation due to route-specific menu variation and fragile presentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Onboard Rail Catering Market |
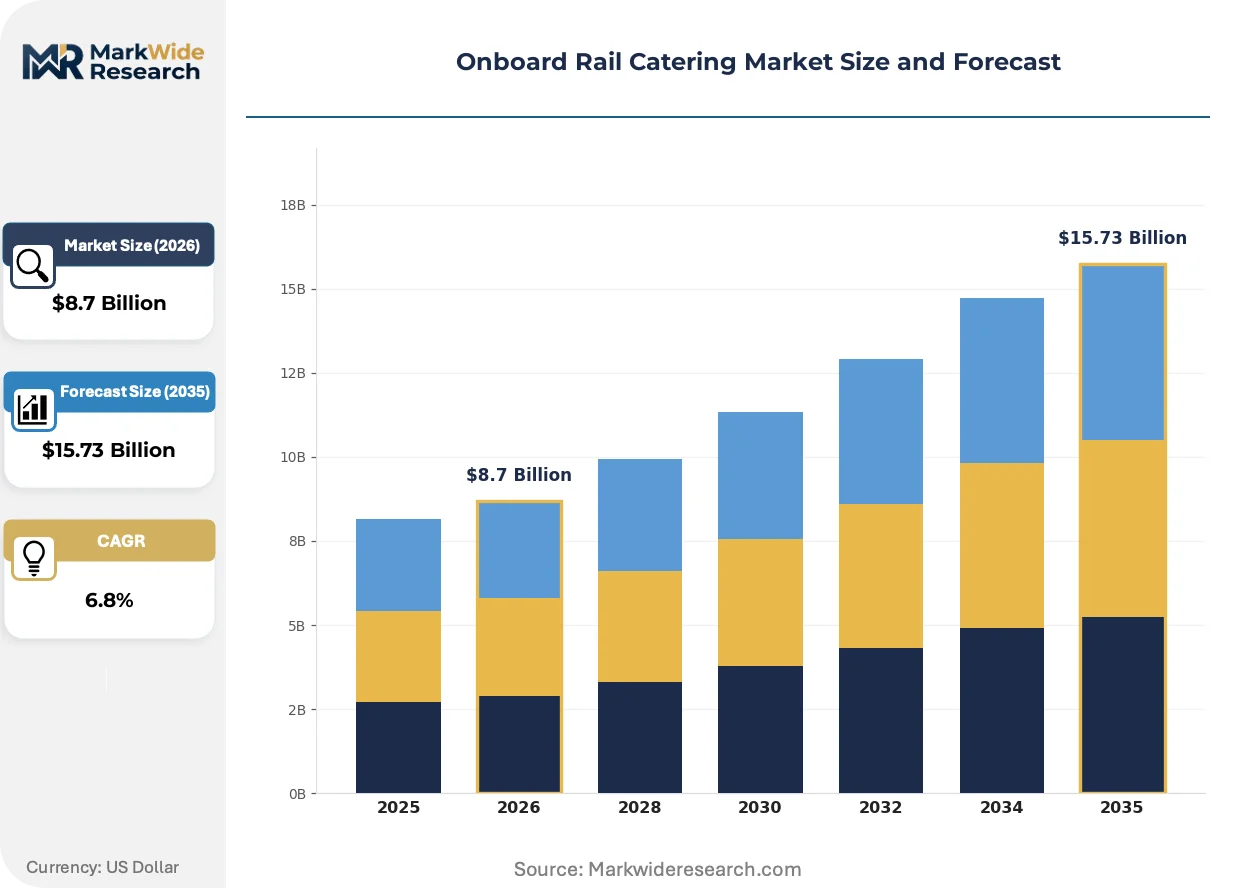
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meal Service, Snack Service, Beverage Service, Catering Packages Customer Type: Business Travelers, Leisure Travelers, Rail Operators, Catering Companies Menu Type: Vegetarian, Non-Vegetarian, Vegan, Gluten-Free Delivery Mode: In-Train Delivery, Pre-Order Service, Buffet Service, Self-Service |
| Companies Covered | IRCTC Limited, Newrest Group Services SAS, Deutsche Bahn AG, Amtrak, Eurostar, Great Western Railways, Trenitalia, Swiss Federal Railways, SNCF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Onboard Rail Catering Market Evolving Landscape
Digital passenger touchpoints and sustainability mandates are compressing traditional catering procurement cycles while fragmenting production across distributed micro-kitchens rather than centralized commissaries.
Reusable container tracking systems using RFID-tagged stainless steel meal cassettes is modularizing how operators manage inventory rotation and deposit-return logistics across international borders. Scandinavian rail networks have pioneered closed-loop washing partnerships at terminal stations, cutting single-use packaging volumes by half while creating new asset-tracking service revenue. The technology is modularizing supplier relationships from pure food provision into integrated equipment-leasing arrangements.
REACH-compliant food-contact material certifications now govern silicone seals, heating-element coatings, and antimicrobial surfaces in galley equipment across EU-operated services. Manufacturers must submit full chemical dossiers to ECHA before components enter revenue service, extending procurement timelines by eight to twelve months. High-speed operators in France and Spain have responded by pre-qualifying component suppliers against 2027 substance restriction horizons.
Business travelers now specify dietary requirements through integrated booking platforms rather than post-purchase call centers, compressing menu-planning lead times from seventy-two hours to same-day production. This pattern concentrates demand volatility onto kitchen capacity planners who must maintain buffer stock for unannounced allergen restrictions. The shift is most pronounced on Germany's Intercity Express network, where corporate travel management systems drive over half of all pre-orders.
Onboard Rail Catering Market Segmentation
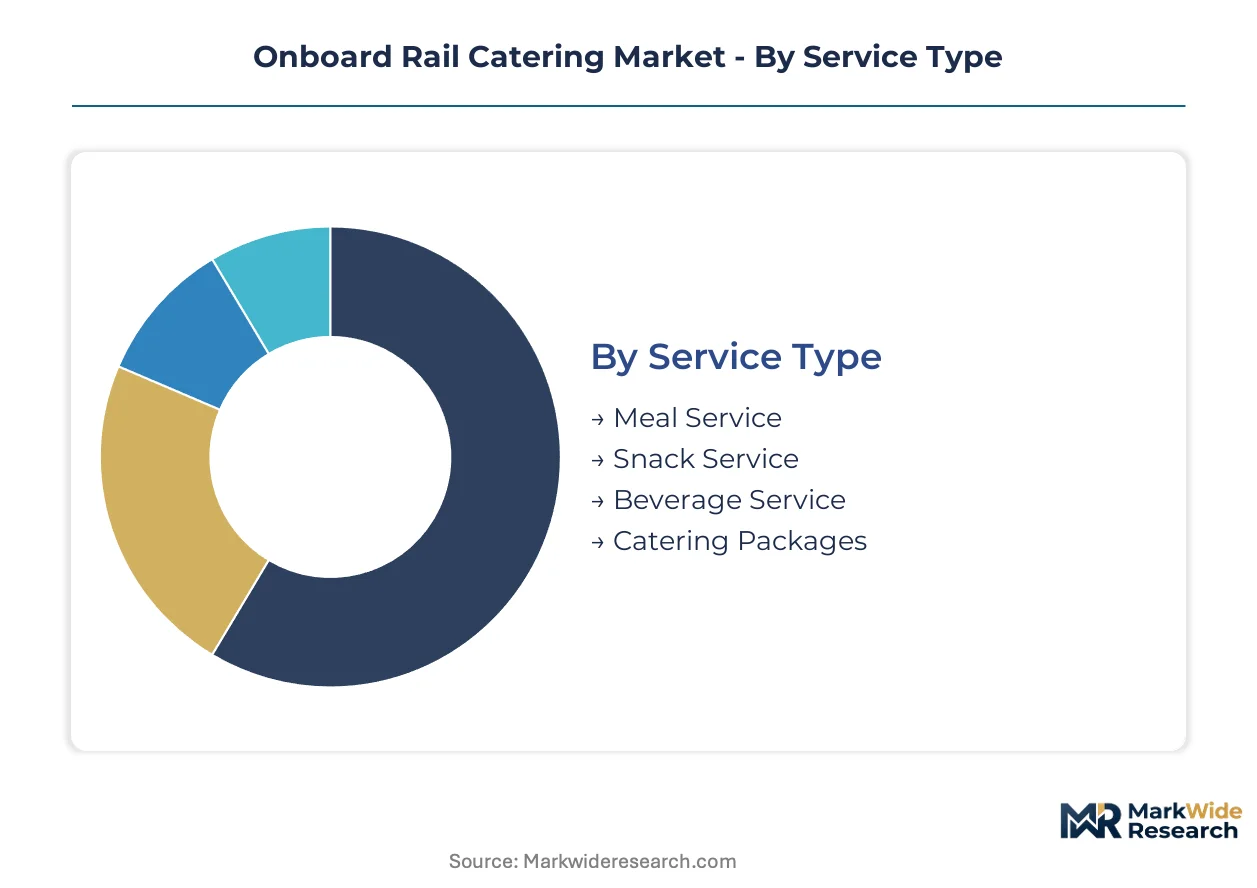
Onboard rail catering segments fragment across service intensity, passenger profile, dietary specification, and fulfillment logistics. Each dimension shapes kitchen infrastructure requirements, pricing architecture, and vendor qualification thresholds differently.
Service Type:
Upgrade cycles in galley equipment and tray-set configurations drive contract restructuring every four to seven years as operators refresh rolling stock interiors.
- Meal Service:Full hot and cold meal provisioning with fixed-menu obligations on overnight and long-haul routes. Deutsche Bahn AG's Intercity network concentrates demand through centralized procurement hubs that standardize ingredient sourcing across multiple kitchen nodes.
- Snack Service:Pre-packaged light refreshments and grab-and-go items requiring minimal galley preparation. India's IRCTC dominates this segment through integrated kitchen infrastructure and vendor accreditation systems that manage one of the world's largest onboard food distribution networks.
- Beverage Service:Hot and cold drink distribution via trolley or seat-back delivery.
- Catering Packages:Bundled meal-plus-beverage combinations for tour groups and corporate accounts.
Meal Service sits at the top of the volume ranking, with Pre-Order Service climbing the fastest.
Customer Type:
Cost tier differentiation separates premium contract terms from commodity procurement, with business accounts commanding dedicated menu development resources.
- Business Travelers:Premium pricing pools through demand for dietary-specific menus and express turnaround times. Newrest Group Services SAS anchors its competitive position through long-term concession agreements with European high-speed operators serving this segment.
- Rail Operators:Direct clients increasingly bundle catering into total service concession packages, transferring capital-intensive kitchen networks and regulatory compliance burdens to specialized providers.
- Leisure Travelers:Price-sensitive demand concentrated in family and tour group segments.
- Catering Companies:Intermediate buyers consolidating multi-operator contracts.
Business Travelers generate the highest margin per passenger, while Rail Operators as direct clients are expanding their contract scope fastest.
Menu Type:
Application-specific certification requirements—halal, kosher, organic—create supplier tiering that favors accredited specialists over generalist food service providers.
- Vegetarian:Plant-based meal options requiring segregated preparation surfaces and ingredient traceability. Muslim-majority travel corridors through Malaysia, Indonesia, and Turkey require dedicated supply chains that generalist caterers cannot fulfill.
- Gluten-Free:Allergen-controlled production with batch testing and cross-contamination protocols. EFSA hygiene protocols and EU Green Deal packaging mandates shape product specifications across European cross-border services for this segment.
- Non-Vegetarian:Standard meat-inclusive menus with conventional supply chains.
- Vegan:Strict plant-based exclusion of all animal derivatives including honey and dairy.
Vegetarian options hold the largest volume share among specialized menus, with Vegan offerings gaining share fastest.
Delivery Mode:
Passenger touchpoint digitization is fragmenting production across distributed micro-kitchens rather than centralized commissaries, compressing fulfillment windows.
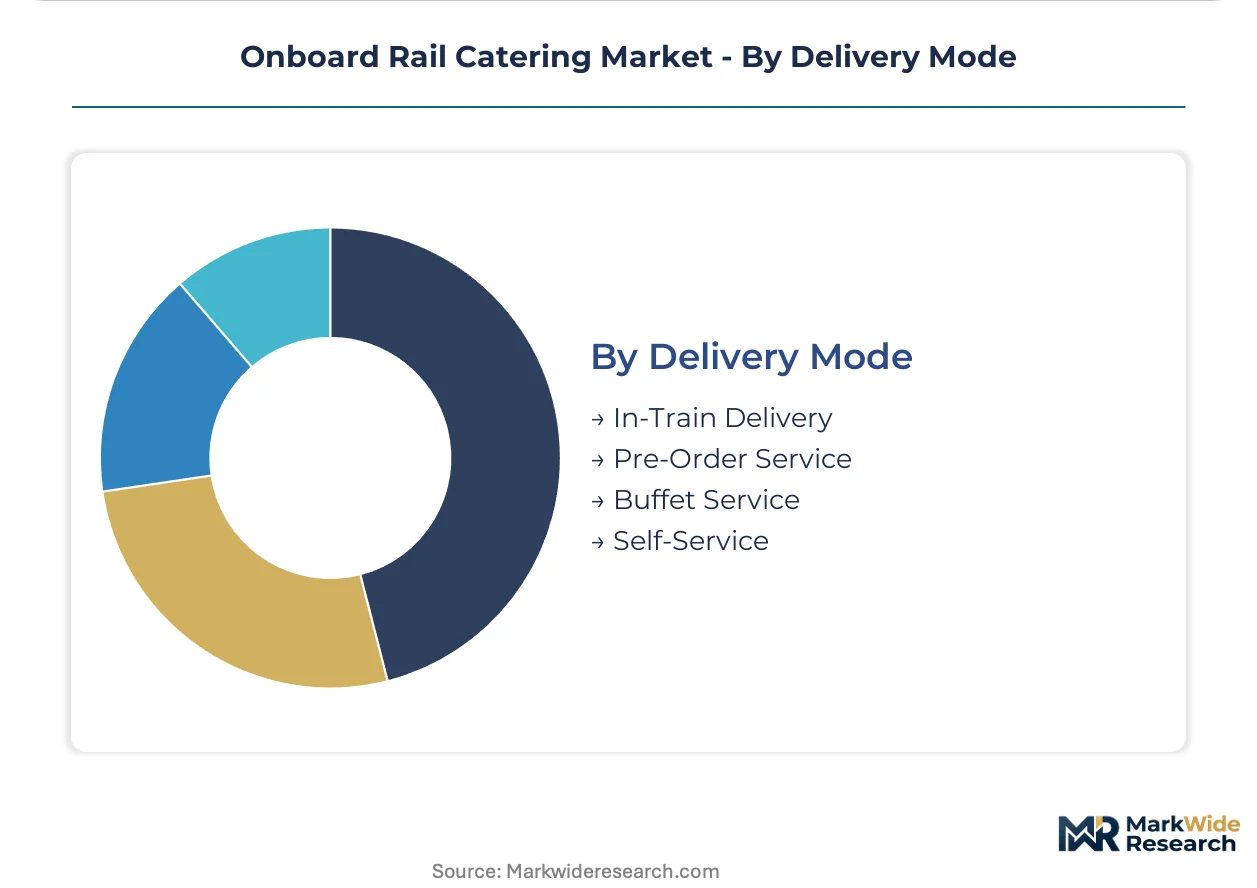
- Pre-Order Service:Mobile platform-based meal scheduling with seat-back QR codes and app-based ordering. Germany's Intercity Express network exemplifies this shift, where corporate travel management systems drive over half of all pre-orders and compress menu-planning lead times from seventy-two hours to same-day production.
- In-Train Delivery:Attendant-served meals at passenger seats with tray-set assembly. Manual packaging of seat-back meal components resists automation due to route-specific menu variation and fragile presentation requirements.
- Buffet Service:Self-select meal components from galley or dining car counters.
- Self-Service:Unattended pickup from designated collection points at stations or onboard.
In-Train Delivery maintains volume leadership, with Pre-Order Service expanding most quickly as operators digitize passenger touchpoints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's IRCTC network anchors the global onboard rail catering infrastructure through integrated kitchen systems and vendor accreditation programs spanning one of the world's largest food distribution operations for rail passengers.
India
IRCTC manages centralized kitchen facilities across 16 zonal railways with FSSAI-mandated hygiene ratings governing vendor selection. The national food safety regulator requires real-time temperature monitoring and batch traceability for all suppliers. Mumbai and Delhi serve as primary catering hubs where private operators compete for station-based concession contracts under IRCTC's tiered accreditation framework.
Germany
Deutsche Bahn AG operates centralized procurement hubs across its Intercity network, consolidating ingredient sourcing for overnight and long-haul routes. EFSA hygiene protocols and EU Green Deal packaging mandates shape cross-border service specifications. Berlin and Munich anchor kitchen infrastructure where specialized caterers absorb regulatory compliance burdens previously managed by state railways.
United States
Amtrak's Northeast Corridor generates concentrated demand for HACCP-aligned food safety plans jointly regulated by FDA and USDA. Business travelers drive premium pre-order volumes through corporate travel management system integrations. Chicago and Washington D.C. host commissary operations where chilled-chain logistics consume disproportionate operating budgets on electrified corridors.
France
SNCF and Eurostar operations face REACH-compliant food-contact material certifications governing silicone seals and heating-element coatings in galley equipment. ECHA pre-qualification requirements extend procurement timelines by eight to twelve months. Paris and Lyon concentrate high-speed catering contracts where long-term concession agreements with specialized providers predominate.
Switzerland
Swiss Federal Railways pioneered RFID-tagged stainless steel meal cassettes with closed-loop washing partnerships at terminal stations. The national network cut single-use packaging volumes by half while creating asset-tracking service revenue. Zurich and Geneva anchor reusable container logistics that modularize supplier relationships into integrated equipment-leasing arrangements.
Onboard Rail Catering Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital pre-order platform integration and sustainable packaging certification. The vendor base concentrates around railway-affiliated operators and specialized food service concessionaires rather than fragmented independent suppliers. Three archetypes predominate: state-linked railway caterers with captive infrastructure, multinational concession specialists with pan-regional compliance capabilities, and technology-enabled platform operators compressing fulfillment windows. Competitive moves center on long-term concession agreement renewal and backward integration into compostable container supply chains.
Within the state-linked tier, IRCTC Limited exemplifies integrated kitchen infrastructure ownership with vendor accreditation systems. Among European concession specialists, Newrest Group Services SAS occupies a position representing long-term contract anchoring with high-speed operators. Deutsche Bahn AG sits within the hybrid archetype, combining centralized procurement hub operation with selective outsourcing to certified specialists capable of pan-European compliance documentation.
| Leading Market Players |
|---|
| IRCTC Limited |
| Newrest Group Services SAS |
| Deutsche Bahn AG |
| Amtrak |
| Eurostar |
| Great Western Railways |
| Trenitalia |
| Swiss Federal Railways |
| SNCF |
| Others |
Value Network & Pricing Analysis
State-backed railway caterers with sovereign financing capacity anchor supply-side discipline through captive kitchen infrastructure ownership, compressing margin recovery timelines for private concessionaires while sustaining three-tier pricing stratification across premium, standard, and economy service levels. IRCTC's integrated procurement networks and Deutsche Bahn's centralized hub operations demonstrate how public capital deployment shapes competitive pricing floors that specialist providers must match through operational efficiency rather than scale leverage.
Pricing Analysis
Input-cost pass-through from chilled-chain energy expenditures and compostable packaging materials is reshaping contract economics across European cross-border routes. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by halal-kosher certification grade and after-sales service bundling including loyalty program integration. Cost compression in the standard tier is intensifying because EU Green Deal packaging mandates force premature capital redeployment before compostable unit economics mature. Leisure travelers exhibit highest price sensitivity, while business travelers on corporate accounts demonstrate lowest elasticity due to expensed procurement policies.
Supply Chain Analysis
Reverse-logistics flows for RFID-tagged stainless steel meal cassettes create closed-loop asset-tracking revenue streams that modularize supplier relationships beyond pure food provision. Geographic supply concentration centers on India, Germany, and Switzerland for integrated kitchen infrastructure, with raw material dependencies on food-contact silicone seals, antimicrobial heating-element coatings, and REACH-compliant container substrates. Single-source vulnerability in ECHA-certified component supply chains extends procurement timelines eight to twelve months. Distribution runs through centralized commissary hubs feeding distributed micro-kitchens at terminal stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where passenger demand is concentrating toward premium specifications with dietary certification requirements and digital pre-order convenience. The shift from commodity snack service toward accredited meal provisioning with real-time traceability documentation favors operators with sunk-cost infrastructure and regulatory compliance capabilities.
For Market Incumbents: Acquire FSSAI-accredited kitchen networks in India to consolidate vendor tiering advantages before private operators scale competing infrastructure. Absorb regulatory compliance documentation burdens from state railways through long-term concession renewals, anchoring position against emerging platform-based entrants with asset-light models. Prioritize backward integration into compostable container supply chains to capture margin compression from EU Green Deal packaging timelines.
For New Entrants and Emerging Players: Digital platform operators with mobile pre-order capabilities represent the most penetrable channel partner type for white-space entry. Target India's tier-two railway zones where IRCTC accreditation frameworks remain underdeveloped, and pursue corporate travel management system integrations as the primary go-to-market angle for premium route access. Leverage subscription meal programs with loyalty credit pre-payment to lock recurring revenue independent of ticket pricing volatility.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialist caterers with pan-European EFSA compliance capabilities and stranded kitchen assets from state railway divestitures. Long-term viability over the five-to-ten year horizon hinges on concession renewal success and digital platform integration depth. Monitor digital pre-order penetration rates as the critical inflection signal for kitchen capacity planning stress and micro-kitchen network expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Concession Agreement Renewal | Long-term contracts with Deutsche Bahn and SNCF transfer regulatory compliance burdens to specialized providers. |
| Backward Integration into Packaging | Captive compostable container production defends margins against EU Green Deal mandate-driven cost inflation. |
| Digital Platform Integration | Corporate travel management system partnerships on Germany's Intercity Express compress fulfillment windows. |
| Dual Certification Investment | Kosher-halal kitchen accreditation enables single-facility production for Middle Eastern and North American routes. |
| Reusable Container Tracking | RFID-tagged stainless steel cassettes create asset-tracking revenue streams at Swiss Federal Railways terminals. |
Research Methodology
Coverage spans India, Germany, France, Switzerland, and the United States, with primary inputs from each regional cluster combining structured interviews with railway catering procurement directors, FSSAI compliance officers, corporate travel managers, and concession operations executives alongside secondary validation. Trade data from Indian Railways annual reports, EFSA hygiene protocol documentation, EU Green Deal regulatory filings, and Amtrak procurement disclosures support bottom-up volume estimates triangulated against top-down market sizing from rail passenger traffic databases.
Rate-of-change decomposition across the projection horizon segments the market by service type, customer archetype, menu specification, and delivery mode, with additional granularity on certification tier and digital penetration. CAGRs derive from trend extrapolation of concession contract values, kitchen capacity utilization rates, and pre-order platform adoption curves modeled against rolling stock refresh cycles and regulatory packaging timeline enforcement.
Revisions become necessary when EFSA or FSSAI regulatory timelines accelerate, sovereign railway divestiture programs stall, or chilled-chain energy cost volatility disrupts contract economics beyond modeled buffers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Full Service Restaurants Market
Food Service
Global Meal Kit Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Shaker Bottles Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
India Online Grocery Market
Food Service
Singapore Food Service Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Smokeless Grill Market
Food Service
Food & Beverage in Asia Market
Food Service
Global Online Food Delivery Services Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Global Food Retail Market
Food Service
United Kingdom Full Service Restaurants Market
Food Service
Brazil Foodservice Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market