
 Wok Market | 2026-2036
Wok Market Size, Share, and Industry Trends Forecast 2026-2036
Wok Market Analysis
Restaurant operators and cloud kitchen chains is rotating toward induction-ready and high-heat-compatible wok formats as commercial kitchen electrification advances. Le Creuset sustains premium positioning through enameled cast iron woks targeting European and North American home cooks. HexClad differentiates via hybrid stainless steel surfaces that bridge professional durability with consumer accessibility. Zwilling J.A. Henckels leverages German engineering heritage to anchor credibility in stainless steel wok segments across multiple continents.
A wok is a round-bottomed or flat-bottomed cooking vessel with high, sloping sides engineered for rapid, high-temperature stir-frying, typically constructed from carbon steel, cast iron, or layered metals with thicknesses between 1.5 mm and 2.5 mm to achieve optimal heat conductivity and thermal mass. Traditional woks require seasoning to build polymerized oil layers that create natural non-stick surfaces, while modern manufacturing applies ceramic or PTFE coatings to reduce maintenance barriers for home users. Carbon steel woks dominate professional kitchens due to superior heat response and lightweight handling, whereas cast iron variants command margin pools in premium retail channels where thermal retention and aesthetic presentation drive purchase decisions. Non-stick woks represent the fastest-growing product type as home cooks prioritize convenience, though ceramic-coated aluminum faces structural constraints in maximum operating temperatures compared to bare metal alternatives.
The EU F-Gas Regulation and CE marking requirements for commercial cooking equipment shape product development trajectories by mandating compatibility with induction and energy-efficient heat sources. China's GB standards for food-contact materials and the US FDA's oversight of non-stick coating safety create layered compliance obligations that filter market access for imported and domestically produced woks alike. Stakeholders must monitor evolving electrification standards in commercial kitchen codes across multiple geographies, as compatibility certifications increasingly determine procurement eligibility for institutional buyers.
Market Dynamics
Commercial kitchen electrification mandates are compressing the addressable market for gas-compatible wok designs while simultaneously expanding induction-ready product lines, forcing manufacturers to reconfigure material specifications and thermal engineering approaches.
Growth Catalysts
- EU F-Gas Regulation:Mandates for energy-efficient commercial cooking equipment accelerate procurement of induction-compatible woks by European restaurant operators and institutional foodservice buyers.
- Cloud kitchen proliferation:Stir-fry formats spread through delivery-optimized ghost kitchen chains, expanding wok demand beyond traditional brick-and-mortar restaurant footprints.
- Carbon steel thermal performance:Professional chefs continue specifying bare carbon steel woks for superior heat response and wok hei development in high-volume operations.
Market Restraints
- Raw material volatility:Cold-rolled carbon steel and iron ore price swings compress margin stability for mid-tier manufacturers dependent on commodity inputs.
- Coating temperature limitations:PTFE and ceramic non-stick surfaces degrade above 260°C, constraining authentic stir-fry technique adoption in coated wok segments.
- Seasoning skill barriers:Traditional carbon steel wok maintenance requirements deter home cooks accustomed to dishwasher-safe cookware alternatives.
Strategic Opportunities
- India foodservice expansion:Quick-service restaurant chains and street food modernization programs create unmet demand for durable, high-heat cooking vessels in urban centers.
- Induction-conversion retrofit kits:Adapter rings and flat-bottom modifications enable existing round-bottom wok inventories to function on induction cooktops.
- US Inflation Reduction Act incentives:Commercial kitchen electrification tax credits lower effective procurement costs for induction-ready equipment in foodservice establishments.
Industry Challenges
- Cross-certification complexity:Simultaneous compliance with China's GB standards, US FDA coating safety requirements, and CE marking for electromagnetic compatibility extends product launch timelines.
- Skilled wok craftsmanship scarcity:Hand-hammered carbon steel wok production depends on declining numbers of trained metalworkers in traditional manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wok Market |
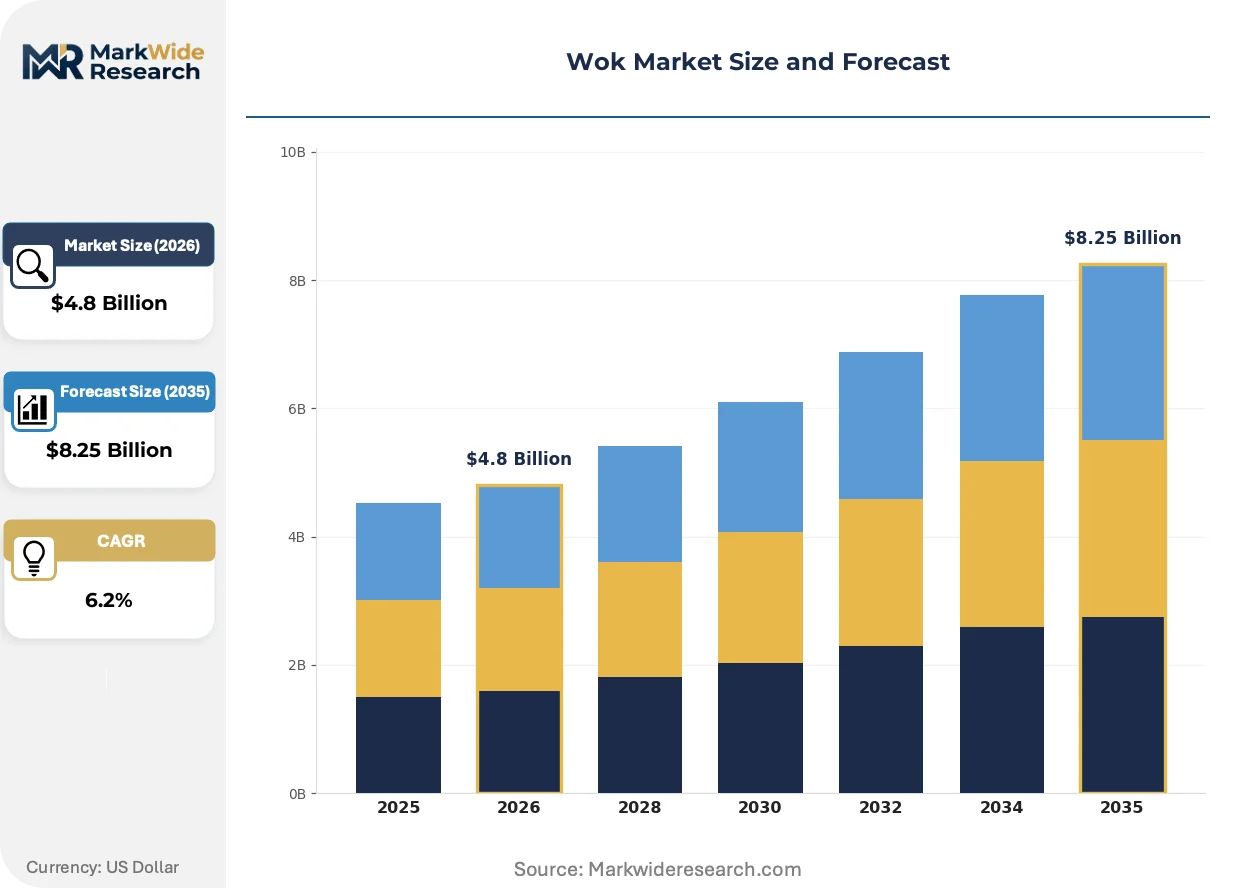
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Wok, Non-Stick Wok, Carbon Steel Wok, Cast Iron Wok Material: Aluminum, Stainless Steel, Copper, Ceramic Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | NUWAVE, Le Creuset, Zwilling J.A. Henckels, Kuhn Rikon, HexClad, Nordic Ware, Staub, Craft Wok, Anolon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wok Market Emerging Trajectories
Material science advances and regulatory pressure on commercial kitchen emissions are converging to reshape wok design priorities, with thermal efficiency and multi-source compatibility replacing single-fuel optimization as the dominant engineering paradigm.
Hybrid composite wok construction is decomposing the traditional trade-off between thermal responsiveness and durability. Restaurant chains in Singapore and Hong Kong are specifying five-ply stainless steel-copper-aluminum laminates for induction-gas dual compatibility. This layered approach is decomposing the historic segmentation between professional carbon steel and consumer non-stick categories.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating ceramic-silica coating development for European home cookware markets. Manufacturers reformulating surface treatments face re-certification costs that favor larger producers with dedicated compliance teams. Premium retail channels in Germany and France are responding by emphasizing bare metal and enameled cast iron alternatives.
Direct-to-restaurant equipment leasing is displacing traditional distributor networks for cloud kitchen operators. Ghost kitchen chains in Dubai and London are sourcing wok inventories through subscription models bundling maintenance and replacement. This procurement pattern shift concentrates buying power with kitchen infrastructure platforms rather than individual chef-operators.
Wok Market Segmentation
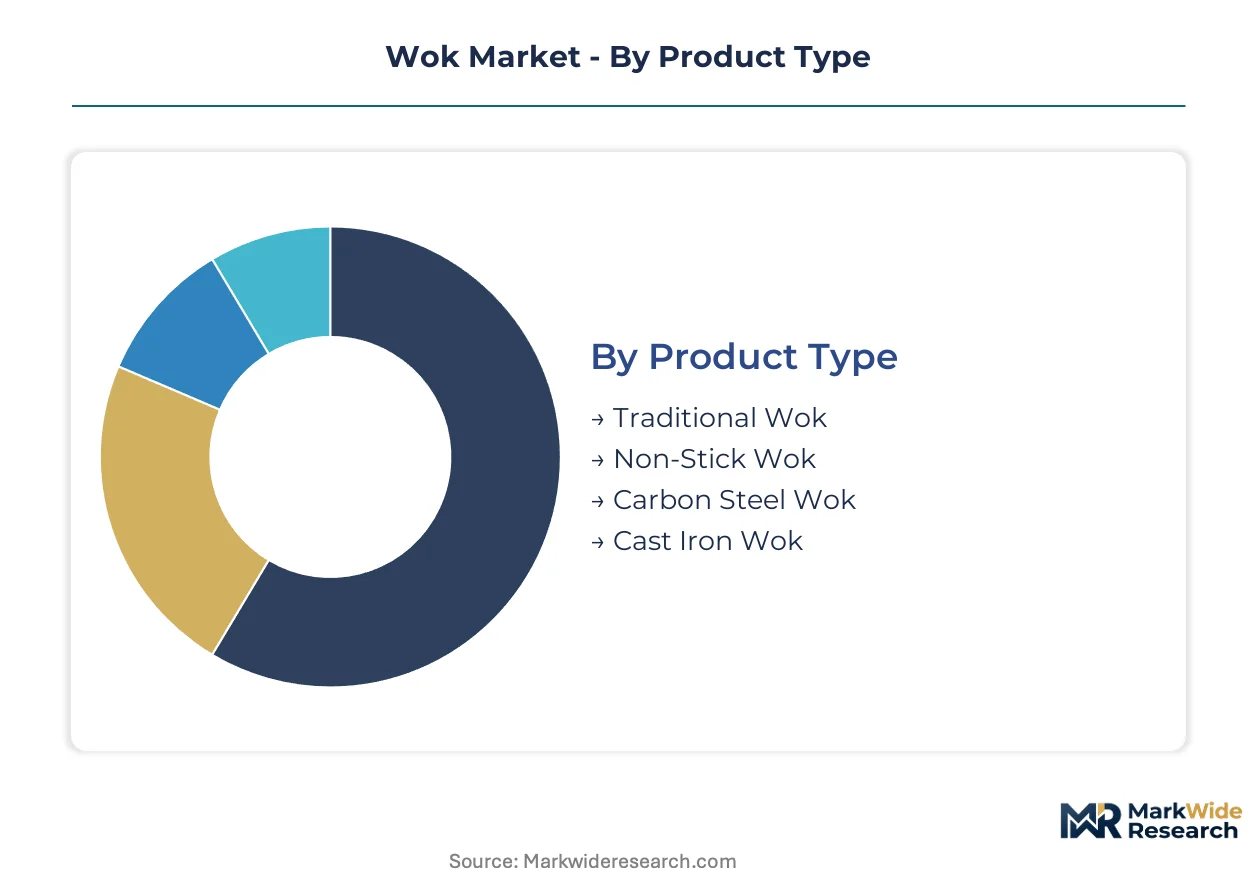
Wok segmentation reveals divergent engineering priorities between commercial foodservice and residential applications. Material specifications and heat-source compatibility now override traditional form-factor distinctions in procurement decisions.
Product Type:
EU F-Gas Regulation and commercial kitchen electrification codes are bifurcating product development paths between induction-ready and legacy gas-compatible formats.
- Traditional Wok:Round-bottomed carbon steel construction with 1.5-2.5 mm wall thickness optimized for open-flame heat distribution. Chinese restaurant operators in Guangdong and Sichuan provinces sustain demand for hand-hammered variants despite declining craftsman supply.
- Non-Stick Wok:PTFE or ceramic-coated aluminum substrates prioritizing residential convenience over thermal ceiling performance. REACH restrictions on perfluorinated compounds are forcing coating reformulations that favor larger manufacturers with dedicated ECHA compliance teams.
- Carbon Steel Wok:Cold-rolled construction delivers superior thermal responsiveness for wok hei development in high-volume stir-fry operations.
- Cast Iron Wok:Enameled variants command premium retail positioning through thermal retention and aesthetic presentation in European home kitchens.
Traditional woks handle the majority of throughput in professional kitchens; non-stick woks are expanding most quickly in residential channels.
Material:
Cost tier stratification separates commodity aluminum from engineered multi-ply laminates in commercial specifications.
- Aluminum:Lightweight substrate with rapid thermal conductivity, typically anodized or coated for residential non-stick applications. Price volatility in alumina refining constrains margin stability for mid-tier producers.
- Stainless Steel:Austenitic grades (304, 316) form the structural backbone of induction-compatible wok designs. Five-ply copper-core laminates specified by Singapore and Hong Kong restaurant chains achieve dual gas-induction compatibility.
- Copper:Exceptional thermal conductivity drives use in high-performance bonded-core constructions rather than solid-form woks.
- Ceramic:Silica-based coatings applied as non-stick surface treatments face temperature degradation constraints above 450°C in authentic stir-fry applications.
Stainless steel dominates commercial procurement volumes; aluminum maintains broadest residential penetration.
Size:
Customer type and installation footprint dictate dimensional specifications across foodservice and residential segments.
- Small:10-12 inch diameter formats suited to compact residential kitchens and single-portion cooking.
- Medium:14-inch standard for family-scale home use and small restaurant operations.
- Large:16-18 inch diameters specified by cloud kitchen chains and quick-service restaurant formats for batch efficiency.
- Extra Large:20+ inch commercial formats deployed in institutional catering and high-volume street food operations.
Medium sizes anchor residential revenue; extra large formats are climbing fastest on cloud kitchen expansion.
Distribution Channel:
Procurement patterns are shifting from distributor networks toward direct equipment leasing for ghost kitchen operators.
- Online Retail:Direct-to-consumer platforms capture residential purchases with specification transparency and review aggregation. Amazon and specialized cookware portals dominate North American and European home cook acquisition.
- Supermarkets:Mass-market retail placement for entry-level aluminum and coated wok formats. Seasonal promotional cycles align with Lunar New Year demand spikes in Asian markets.
- Specialty Stores:Sur La Table and Williams Sonoma curate premium enameled cast iron and hand-forged carbon steel selections.
- Wholesale:Restaurant supply distributors and equipment leasing platforms serve institutional buyers with volume pricing and maintenance bundling.
Wholesale channels process the highest transaction values; online retail is gaining share fastest on residential convenience preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturing clusters supply carbon steel woks to European restaurant operators adapting to EU F-Gas Regulation mandates. Export flows concentrate through Guangdong and Zhejiang provinces toward institutional buyers in Germany, France, and the United Kingdom.
China
Domestic consumption absorbs the majority of carbon steel and cast iron production from Guangdong and Zhejiang manufacturing belts. GB standards for food-contact materials regulate coating safety and metal composition for both domestic sale and export certification. Hand-hammered wok production persists in Chaozhou and Wuyi County despite declining craftsman numbers.
Germany
Restaurant operators under EU F-Gas Regulation pressure are replacing gas-fired wok stations with induction-compatible equipment. ECHA REACH restrictions on perfluorinated compounds block certain non-stick coating formulations from import. Commercial kitchen equipment distributors in Hamburg and Frankfurt coordinate procurement for cloud kitchen chains expanding across the Rhine-Ruhr metropolitan region.
United States
Inflation Reduction Act tax credits for commercial kitchen electrification lower effective acquisition costs for induction-ready wok inventories. FDA oversight of non-stick coating safety applies to imports from Asian manufacturing centers. Ghost kitchen operators in Los Angeles and New York City specify large-format woks through direct equipment leasing platforms.
India
Quick-service restaurant chains and street food modernization programs in Mumbai and Delhi generate demand for durable high-heat cooking vessels. FSSAI food-contact material standards regulate metal composition and surface treatments for commercial foodservice equipment. Tamil Nadu and Gujarat manufacturing clusters are expanding stainless steel fabrication capacity for domestic institutional buyers.
United Kingdom
London-based cloud kitchen operators source induction-compatible wok formats to comply with tightening commercial building electrification codes. CE marking requirements for electromagnetic compatibility filter procurement eligibility for institutional buyers. Birmingham and Manchester distribution hubs serve as consolidation points for restaurant supply chains across the Midlands and Northern England.
Wok Market Vendor Landscape
Player mix skews toward heritage cookware brands with established retail distribution and specialized carbon steel fabricators serving professional foodservice. Market structure exhibits tiered concentration: premium enameled cast iron and hybrid stainless steel lines occupy branded retail channels, while unbranded carbon steel volumes flow through restaurant supply networks. Strategic archetypes include European heritage brands leveraging manufacturing origin credibility, direct-to-consumer hybrid surface innovators, and Chinese craft-scale producers of hand-forged professional equipment. Competitive moves center on coating reformulation to meet REACH compliance and induction compatibility engineering for European commercial buyers.
Within the heritage European tier, Le Creuset and Zwilling J.A. Henckels occupy positions anchored by manufacturing origin associations. HexClad exemplifies the direct-to-consumer hybrid surface archetype bridging professional durability claims with residential accessibility. Among specialized carbon steel producers, Craft Wok represents the craft-scale fabrication segment serving chef-operators who prioritize thermal performance over brand recognition.
| Leading Market Players |
|---|
| NUWAVE |
| Le Creuset |
| Zwilling J.A. Henckels |
| Kuhn Rikon |
| HexClad |
| Nordic Ware |
| Staub |
| Craft Wok |
| Anolon |
| Others |
Supply Flow & Price Mechanics
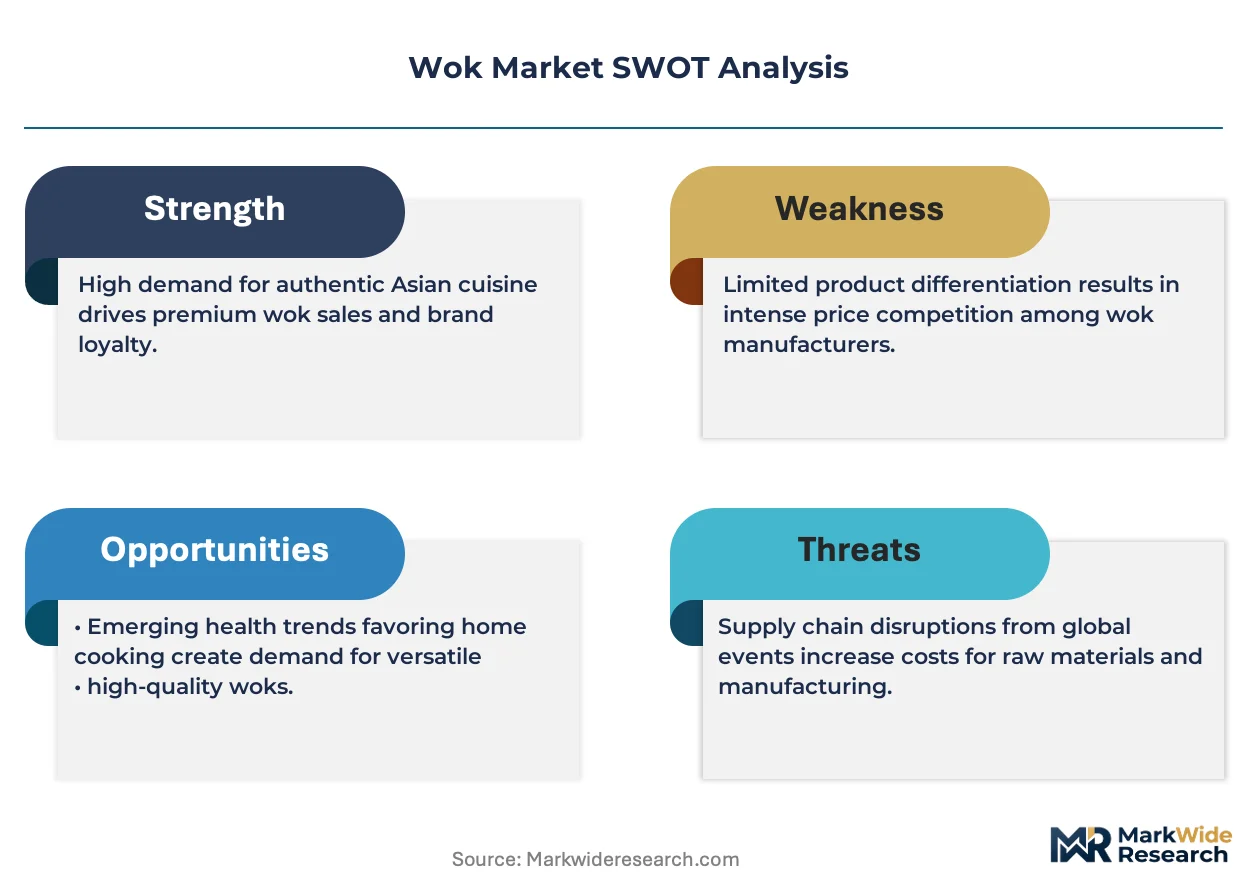
EU F-Gas Regulation certification gates both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb compliance costs or retreat from commercial foodservice channels where induction compatibility commands procurement eligibility. The regulation bifurcates the supplier base into certified premium tiers and excluded commodity producers, compressing margins at the mid-market intersection where price competition remains most intense.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hand-forged carbon steel from hybrid stainless steel laminates and mass-market aluminum formats. Price differentiation rests on certification grade and brand heritage, with CE-marked induction-compatible lines capturing institutional premiums while unbranded carbon steel volumes compete on raw material efficiency. Cost compression in mid-tier aluminum non-stick segments is intensifying because REACH coating reformulation expenses disproportionately burden smaller manufacturers. Cloud kitchen operators exhibit highest price sensitivity due to equipment leasing bundling, whereas heritage brand collectors in European residential channels demonstrate lowest sensitivity.
Supply Chain Analysis
China and India anchor global wok fabrication, with Guangdong and Zhejiang provinces dominating carbon steel output and Tamil Nadu expanding stainless steel capacity for domestic institutional buyers. Raw material dependencies draw from cold-rolled carbon steel coil, iron ore, and alumina refining, with price volatility in steel inputs tethered to energy-intensive smelting economics. Single-source vulnerability concentrates in hand-hammered craft production clusters where trained metalworker scarcity threatens continuity. Distribution runs through restaurant supply distributors and direct equipment leasing platforms serving ghost kitchen operators, bypassing traditional retail intermediaries for institutional volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial kitchen electrification represents an early-cycle expansion story, with cloud kitchen proliferation and induction mandate compliance creating durable procurement tailwinds across foodservice infrastructure. Penetration depth in residential non-stick segments remains shallow relative to authentic stir-fry technique adoption potential.
For Market Incumbents: Fortify certification moats by accelerating CE marking and FDA coating safety investments ahead of REACH restriction tightening. Deepen backward integration into cold-rolled carbon steel supply to buffer raw material volatility. Anchor channel control through direct equipment leasing partnerships with ghost kitchen infrastructure platforms, neutralizing distributor disintermediation threats from cloud kitchen procurement centralization. For New Entrants and Emerging Players: Differentiate on induction-gas dual compatibility engineering, exploiting the technology gap between legacy round-bottom designs and flat-bottom retrofit demand. Target India quick-service restaurant chains and street food modernization programs as the most penetrable geography-application intersection. Pursue a go-to-market angle bundling maintenance services with durable high-heat vessel supply, mirroring subscription models displacing traditional distributor networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid multi-ply laminate fabrication as five-ply copper-core specifications proliferate in Singapore and Hong Kong restaurant chains. Long-term viability favors scaled manufacturers with dedicated ECHA compliance teams capable of absorbing coating reformulation costs. Target acquisition archetype: mid-tier stainless steel fabricators with latent induction engineering capacity and underutilized CE marking pathways. Watch cloud kitchen equipment leasing platform consolidation as the signal indicating procurement power concentration and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Compatibility Engineering | CE marking and EU F-Gas Regulation compliance unlock institutional procurement eligibility across German and French foodservice. |
| Coating Reformulation Investment | ECHA REACH ceramic-silica development displaces PTFE-dependent competitors lacking dedicated compliance infrastructure. |
| Direct Equipment Leasing | Subscription bundling with maintenance captures cloud kitchen volume concentrated in Dubai and London ghost kitchen chains. |
| Backward Integration into Steel Supply | In-house cold-rolled carbon steel production insulates margin stability against iron ore price volatility. |
| Craftsmanship Preservation Programs | Hand-hammered wok training pipelines in Chaozhou and Wuyi County sustain premium positioning as artisan scarcity intensifies. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, restaurant equipment distributor filings, and food-contact material safety registrations. Primary interviews engaged commercial kitchen equipment procurement managers, cloud kitchen infrastructure platform operators, carbon steel fabrication plant managers, and ceramic coating R&D directors. Secondary validation drew from ECHA substance restriction databases, FDA non-stick coating safety guidance, and GB standards documentation for food-contact metals. Bottom-up volume estimates triangulated against top-down spending projections across foodservice and residential channels.
Segmentation dimensions modeled span product type, material substrate, size format, and distribution channel across the projection horizon. The analytical framework incorporated heat-source compatibility evolution, coating technology substitution dynamics, and regional electrification policy trajectories. CAGRs derived from installed base turnover rates, replacement cycle compression, and penetration elasticity in emerging foodservice formats. Industry-specific forecast inputs included cloud kitchen station deployment rates and commercial kitchen code amendment timelines.
Material uncertainties — raw material price volatility, regulatory restriction acceleration, and craft production continuity — sit outside the modeled envelope. Forecasts reflect assumptions regarding induction infrastructure rollout pace and chef-operator technique preference stability. Recalibration cycles align with material shifts in EU F-Gas Regulation enforcement stringency and cloud kitchen platform consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
Global Online Food Ordering Market
Food Service
Undercounter Ice Makers Market
Food Service
Spain Food Service Market
Food Service
Europe Pizza Oven Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
US Food Service Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Portion Cups Market
Food Service
North America Online Grocery Delivery Market
Food Service
Commercial Ice Dispenser Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Commercial Air Fryer Market
Food Service
United States Foodservice Market
Food Service
Beverage Vending Machine Market