
 UAE Food Service Market | 2026-2036
UAE Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Food Service Market Insights
Subscription-based loyalty programs and app-first ordering is pivoting how UAE chains monetize repeat visits. McDonald's Corporation leverages its Golden Arches Rewards ecosystem to drive frequency across Dubai and Abu Dhabi locations. Alamar Foods Company anchors the Pizza Hut and Taco Bell franchise network across the Gulf with localized menu engineering. Kitopi dominates the cloud kitchen infrastructure layer, operating delivery-native brands from centralized production facilities without traditional storefront overhead.
Food service encompasses the commercial preparation, sale, and delivery of ready-to-consume meals through organized outlets, with operational parameters spanning HACCP temperature controls, halal certification compliance, and throughput metrics measured in covers per labor hour. The sector serves tourism, corporate catering, and residential consumption with standardized quality assurance protocols. Fast Food and Casual Dining segments lead transaction volume due to affordability and speed alignment with commuter and family dining patterns. Online Delivery channels capture the fastest expansion as aggregator platforms and native apps reconfigure last-mile logistics. Luxury price tier outlets cluster in Dubai's hotel and entertainment districts, concentrating margin pools where experiential dining commands premium positioning.
MOHAP enforces food safety standards through mandatory digital traceability systems, while municipal authorities in Dubai and Abu Dhabi regulate commercial kitchen licensing and outdoor dining permits. BSI halal certification requirements shape supplier selection and cross-border ingredient sourcing for multinational operators. Stakeholders must monitor how delivery platform commission structures and evolving labor visa policies reshape unit economics across emirate-level jurisdictions.
Market Dynamics
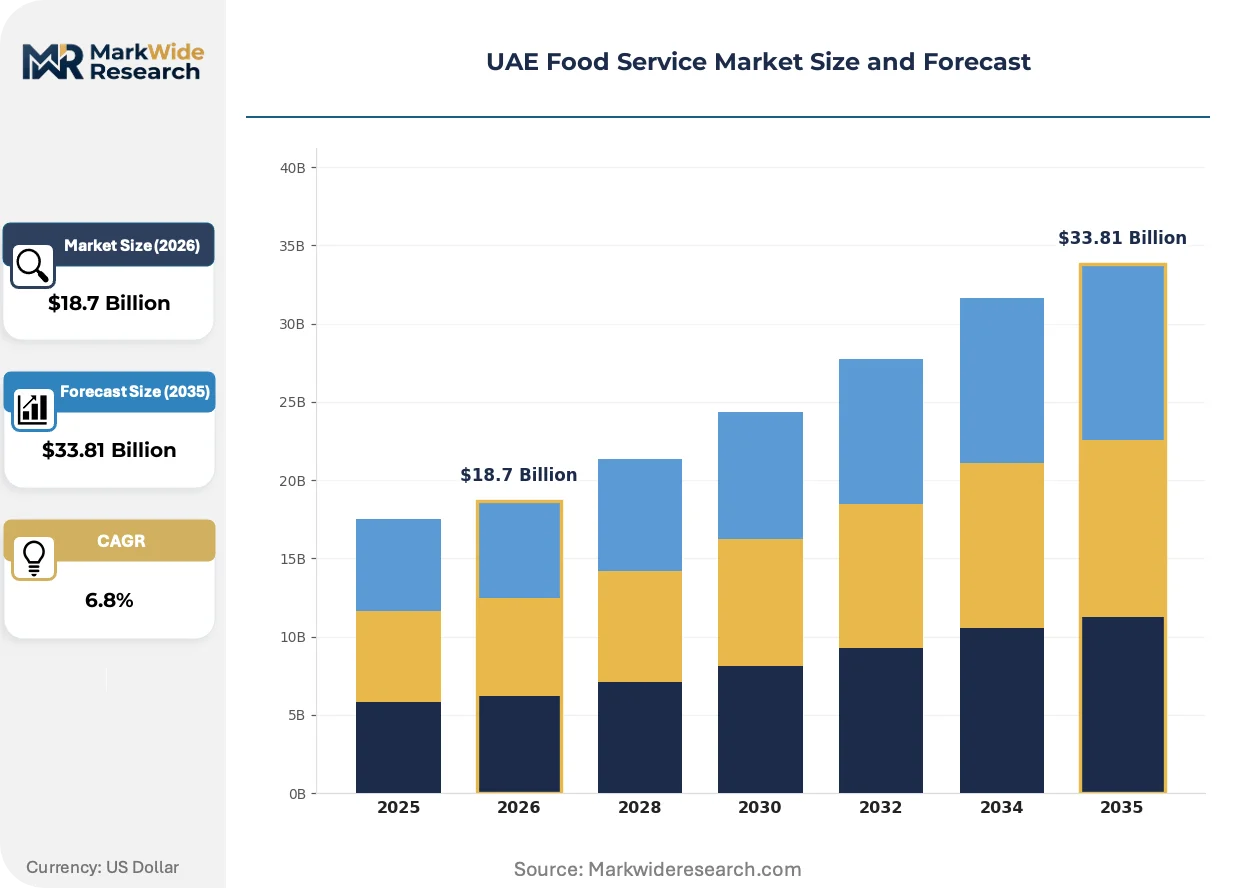
Cloud kitchen infrastructure is compressing real estate costs while MOHAP's digitization mandates force traceability investments that reshape operator economics across Dubai and Abu Dhabi.
Growth Catalysts
- Aggregator Platform Commission Structures:Delivery-native brands bypass traditional storefront overhead by operating through centralized production facilities. This model reduces capital requirements for market entry.
- Halal Certification Harmonization:BSI standards streamline cross-border ingredient sourcing for multinational operators, reducing supplier qualification timelines and enabling menu standardization.
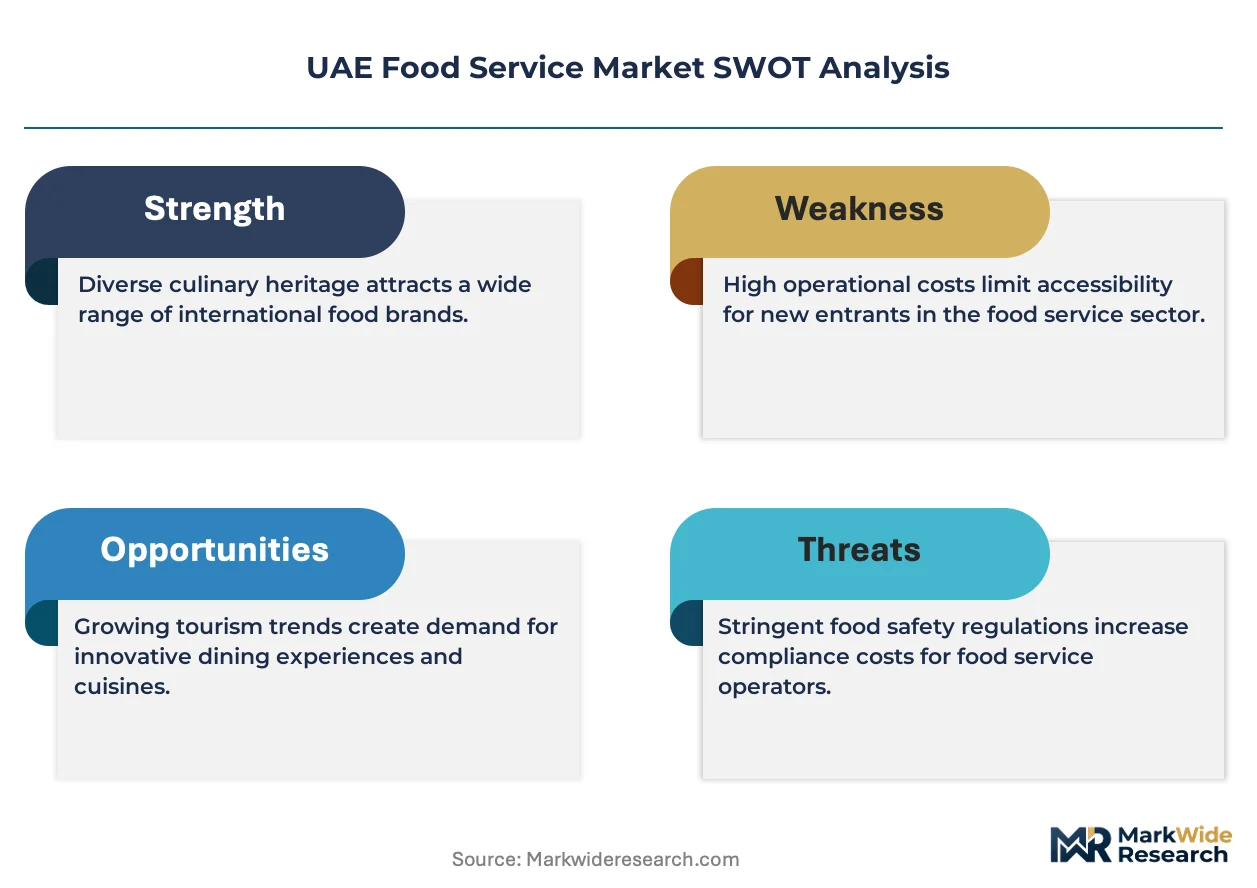
- Tourism Corridor Development:Dubai's hospitality corridor concentrates new outlet openings near entertainment districts, creating demand density that supports premium positioning.
Market Restraints
- Labor Visa Policy Volatility:Evolving work permit regulations in Abu Dhabi and Dubai create workforce planning uncertainty for chains dependent on expatriate kitchen staff.
- Delivery Platform Dependency:Concentrated aggregator market power in the UAE compresses operator margins through non-negotiable commission tiers.
- Commercial Kitchen Licensing Friction:Municipal authorities in each emirate maintain separate permitting timelines, complicating multi-location rollout strategies.
Strategic Opportunities
- Subscription Loyalty Monetization:App-first ordering ecosystems create recurring revenue streams beyond transaction fees, locking in commuter and family dining patterns.
- Sharjah and Northern Emirates Expansion:Underpenetrated markets outside Dubai-Abu Dhabi corridor offer first-mover positioning before infrastructure saturation.
- Digital Traceability Compliance Services:MOHAP's mandatory food safety digitization creates vendor opportunity in HACCP temperature monitoring and supply chain visibility tools.
Industry Challenges
- Cloud Kitchen Site Selection:Last-mile logistics optimization requires precise proximity to delivery demand clusters, with mislocation carrying high sunk-cost risk.
- Halal Supply Chain Integrity:Cross-border ingredient provenance verification demands documentation systems that integrate with MOHAP's traceability platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Food Service Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fast Food, Fine Dining, Casual Dining, Cafés Customer Type: Individual Consumers, Corporates, Institutions, Tourists Distribution Channel: Online Delivery, Food Trucks, Dine-in, Takeaway Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Yum! Brands, Restaurant Brands International, McDonald's Corporation, Alamar Foods Company, Apparel Group, Al Khaja Group of Companies, Kamal Osman Jamjoom Group, Al Futtaim Group, Kitopi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Food Service Market Trends and Innovations
Native app ecosystems and centralized production facilities are displacing traditional dine-in dependency across UAE food service, with regulatory digitization accelerating operational transparency requirements.
AI-powered demand forecasting is rewriting inventory management protocols for cloud kitchen operators. Delivery-native brands deploy machine learning models to predict order patterns by hour and zone. This compression of waste and stockout risk is enabling thinner margin structures that undercut traditional storefront economics.
MOHAP's mandatory digital traceability systems tighten food safety accountability across commercial kitchens. The regulation requires real-time temperature logging and ingredient provenance documentation. Quick-service operators in Dubai are responding by integrating IoT sensors directly into production workflows to automate compliance reporting.
Commuter consumption patterns are fragmentizing daypart concentration away from traditional lunch and dinner peaks. Remote work normalization spreads ordering across midday and late-evening windows. This demand diffusion is most visible in Abu Dhabi's residential zones, where operators adjust staffing models to capture off-peak volume without eroding labor productivity metrics.
UAE Food Service Market Segmentation
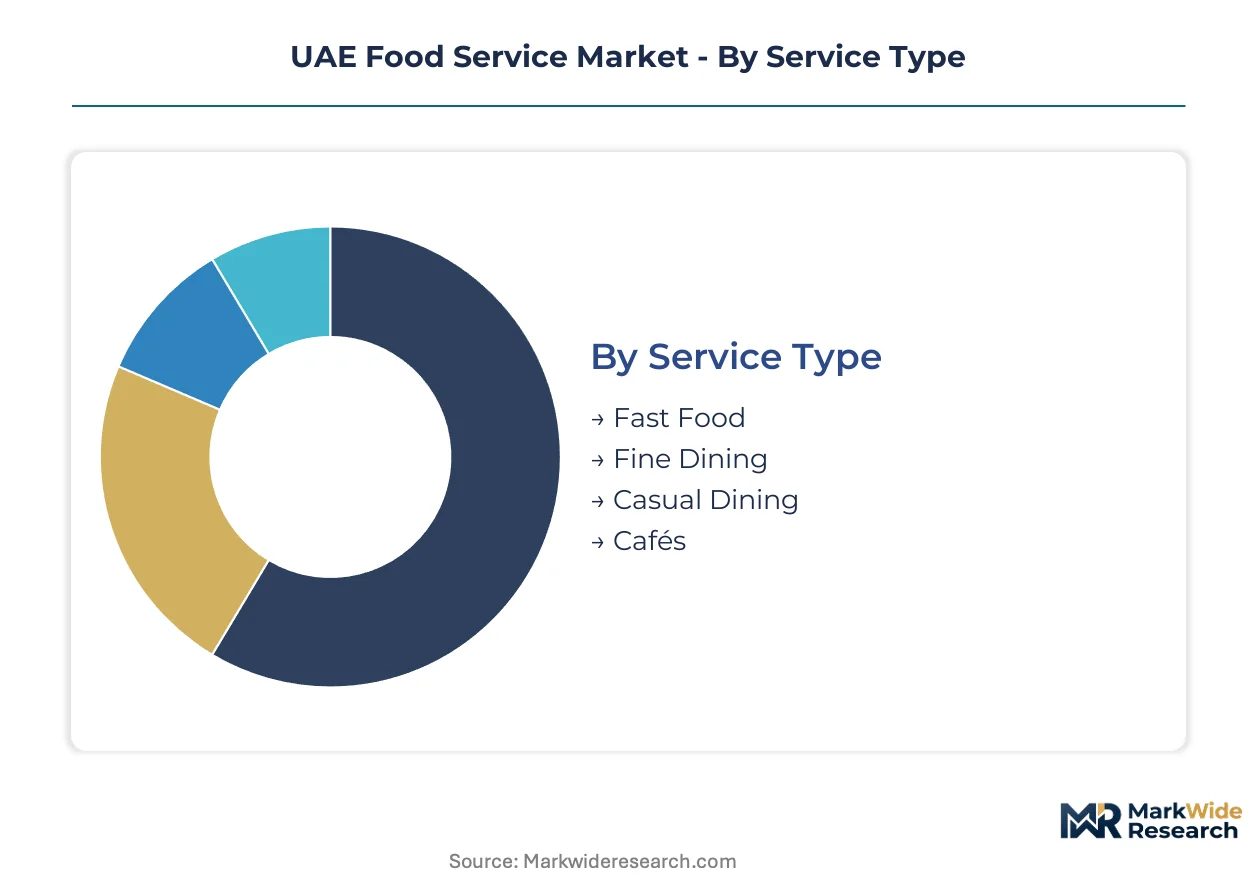
Segmentation in UAE food service reveals how operational models and consumption contexts fragment revenue pools. Service format, customer identity, channel preference, and price positioning each create distinct margin profiles and capital requirements for operators across Dubai, Abu Dhabi, and Sharjah.
Service Type:
Standalone formats dominate transaction volume while embedded hospitality concepts anchor premium positioning within mixed-use developments.
- Fast Food:High-throughput production systems with standardized menu engineering target commuter corridors and family dining occasions. Dubai's metro-adjacent clusters and Abu Dhabi's industrial zones concentrate demand density where speed and affordability align with traffic patterns.
- Fine Dining:Experience-driven service protocols with chef-led kitchen operations command premium positioning through ingredient provenance and theatrical presentation. Dubai's hotel and entertainment districts concentrate these outlets where tourism expenditure pools justify elevated price architecture.
- Casual Dining:Full-service formats balancing speed with sit-down experience capture family and social occasion demand across mall-based and standalone locations.
- Cafés:Beverage-forward formats with limited food menus serve remote work and social meeting occasions in residential and commercial districts.
Volume placements concentrate in Fast Food; the faster expansion belongs to Casual Dining as family dining patterns shift toward experience-per-dirham optimization.
Customer Type:
Cost tier and procurement rhythm separate institutional contracts from discretionary individual spend, reshaping how operators configure kitchen capacity and staffing models.
- Individual Consumers:Discretionary spend patterns drive demand volatility across dayparts, with remote work normalization fragmenting traditional lunch and dinner peaks into distributed ordering windows throughout Abu Dhabi's residential zones.
- Tourists:Experience-seeking visitors concentrate expenditure in Dubai's hospitality corridor, where entertainment district proximity supports premium positioning and extended operating hours.
- Corporates:Contracted catering relationships with predictable volume and negotiated pricing terms provide base-load kitchen utilization for business district operators.
- Institutions:Long-term concessions in education and healthcare facilities require HACCP-compliant production at scale with limited menu flexibility.
Margin stability concentrates in Corporates; the steepest expansion trajectory belongs to Tourists as Dubai's visitor volume recovers and entertainment district development accelerates.
Distribution Channel:
Channel selection determines real estate overhead structure and last-mile cost absorption, with cloud-native models compressing capital requirements relative to traditional storefront dependency.
- Online Delivery:Aggregator-dependent fulfillment with centralized production facilities eliminates dine-in footprint costs. Kitopi's infrastructure layer enables delivery-native brand launches without storefront investment, though platform commission structures compress operator margins.
- Dine-in:Experience-dependent formats require location premiums for foot traffic access, with Dubai Mall and Yas Mall corridors commanding rent structures that demand high table turnover efficiency.
- Takeaway:Counter-service formats with minimal seating reduce front-of-house labor costs while capturing commuter demand through proximity to transit and office clusters.
- Food Trucks:Mobile permits enable demand testing and event-based revenue with lower fixed cost exposure than permanent locations.
Capital efficiency concentrates in Takeaway; the fastest share gain belongs to Online Delivery as aggregator platform penetration deepens across Sharjah and Northern Emirates.
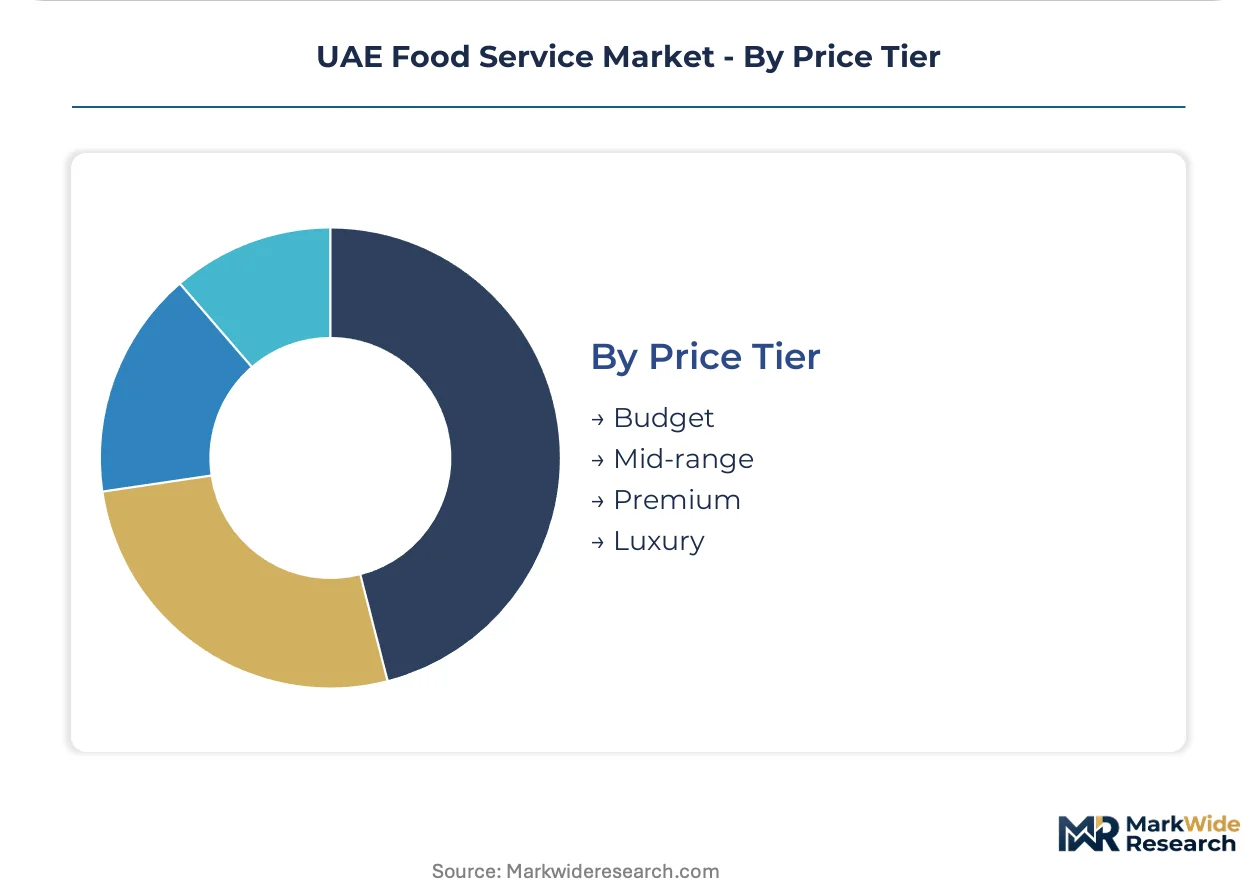
Price Tier:
Certification requirements and ingredient sourcing protocols separate tiers, with halal supply chain integrity costs distributed unevenly across positioning levels.
- Budget:Value-engineered menus with limited ingredient complexity target price-sensitive segments through volume-driven procurement and labor-minimal production formats.
- Mid-range:Quality-perception optimization balances ingredient upgrade with accessibility, capturing family dining occasions where occasion significance justifies modest premium over budget alternatives.
- Premium:Branded ingredient provenance and service differentiation support elevated pricing in competitive corridors where experience quality drives repeat visitation.
- Luxury:Exclusive locations and chef reputation command price architecture detached from ingredient cost ratios, concentrating in Dubai's hotel and waterfront districts where tourism expenditure pools enable margin structures unavailable elsewhere.
Transaction frequency concentrates in Mid-range; the margin expansion belongs to Luxury as experiential dining demand strengthens in Dubai's entertainment district development pipeline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai generates the dominant share of food service consumption while production infrastructure clusters across emirate-level commercial zones. Abu Dhabi and Sharjah concentrate distinct demand profiles shaped by government, tourism, and residential density patterns. Northern Emirates remain underpenetrated relative to infrastructure investment flows.
Dubai
Entertainment district development and hospitality corridor expansion concentrate premium outlet openings near Burj Khalifa and Dubai Marina clusters. MOHAP enforces digital traceability mandates through mandatory HACCP temperature logging systems. Downtown Dubai and Business Bay host the densest cloud kitchen aggregations as Kitopi scales centralized production facilities.
Abu Dhabi
Government district catering contracts and corporate headquarters clusters generate predictable institutional demand across the capital's business zones. Municipal commercial kitchen licensing maintains separate permitting timelines from Dubai's framework. Yas Island and Saadiyat Island concentrate luxury hospitality developments where experiential dining commands elevated price positioning.
Sharjah
Family-centric residential consumption patterns sustain mid-range casual dining formats across mall-based and standalone locations. The emirate's municipal authorities regulate outdoor dining permits with distinct compliance requirements from neighboring Dubai. University City and industrial corridor zones attract first-mover cloud kitchen operators seeking lower real estate costs than Dubai-Abu Dhabi corridor premiums.
Northern Emirates
Ajman, Umm Al Quwain, Ras Al Khaimah, and Fujairah present underpenetrated markets with limited delivery infrastructure relative to population density. Federal-level halal certification harmonization through BSI standards enables cross-emirate supplier qualification for multinational operators. Ras Al Khaimah's tourism development pipeline and Fujairah's port logistics corridor concentrate emerging hospitality investment outside the dominant Dubai-Abu Dhabi axis.
UAE Food Service Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the UAE food service landscape. Full-service restaurant operators with permanent dine-in footprints face margin pressure from delivery-native brands operating through centralized cloud kitchen infrastructure. Three archetypes dominate: multinational quick-service franchisors with established brand equity, regional franchise holding companies with localized menu engineering capabilities, and cloud kitchen operators with asset-light expansion models. Competitive moves center on aggregator platform partnership negotiations and subscription loyalty program deployment to lock in repeat visitation patterns.
Within the multinational franchisor tier, McDonald's Corporation and Yum! Brands exemplify scale-driven operators leveraging global supply chain integration. Alamar Foods Company represents the regional holding company archetype, anchoring franchise networks with Gulf-specific operational adaptations. Kitopi occupies a distinct position as the cloud kitchen infrastructure layer, enabling delivery-native brand launches without traditional storefront capital requirements.
| Leading Market Players |
|---|
| Yum! Brands |
| Restaurant Brands International |
| McDonald's Corporation |
| Alamar Foods Company |
| Apparel Group |
| Al Khaja Group of Companies |
| Kamal Osman Jamjoom Group |
| Al Futtaim Group |
| Kitopi |
| Others |
Pricing and Supply Chain Analysis
Expatriate kitchen labor concentration in Dubai's hospitality corridor compresses wage differentials between emirates, widening pricing-tier spreads as operators pass differential labor costs through to menu architecture across budget, mid-range, and luxury positioning levels.
Pricing Analysis
Margin tightening in the budget tier reflects aggregator platform commission compression and cloud kitchen density saturation. Three-tier pricing structure across premium, standard, and economy levels segments by service format and location premium, with luxury outlets in Dubai's hotel districts commanding experiential markups detached from ingredient ratios. Price differentiation stems from halal certification tier and real estate proximity to entertainment clusters. Corporate catering contracts exhibit lowest price sensitivity due to volume predictability; individual delivery orders face highest elasticity as platform comparison tools transparentize options.
Supply Chain Analysis
BSI halal certification mandates are reshaping sourcing toward verified supplier networks with integrated documentation systems. Ingredient provenance concentrates in Saudi Arabia, India, and Australia for protein inputs; UAE domestic production supplies dairy and select produce categories. Cross-border logistics hinge on Jebel Ali port throughput and cold-chain integrity across last-mile distribution. Single-source vulnerability persists in specialty spice and premium protein categories where BSI-approved alternatives remain limited. Distribution runs through centralized cloud kitchen aggregators and traditional broadline foodservice distributors serving multi-unit operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive supply chains and proprietary delivery infrastructure anchors competitive durability as operators seek margin defense against platform dependency and regulatory compliance cost escalation.
For Market Incumbents: Anticipate cloud kitchen oversupply in Dubai's downtown corridor by diversifying production assets across Sharjah and Northern Emirates where real estate costs preserve unit economics. Reinforce halal supply chain integrity through direct supplier qualification partnerships that preempt MOHAP traceability audit failures. Prioritize subscription loyalty program deployment to reduce aggregator platform dependency and recover commission-compressed margins through recurring revenue lock-in.
For New Entrants and Emerging Players: Capture underpenetrated demand in Ras Al Khaimah and Fujairah where tourism development pipelines outpace foodservice infrastructure deployment. Target institutional catering contracts in Abu Dhabi's government district clusters where procurement rhythms favor new entrants with HACCP compliance capabilities. Deploy cloud-native launch models through Kitopi infrastructure to bypass storefront capital requirements and test menu-market fit before permanent location investment.
For Investors and Strategic Acquirers: Re-rating potential sits with regional franchise holding companies given halal certification harmonization enabling cross-border menu standardization and supplier scale economies. Long-term viability favors operators with backward integration into supply chain visibility tools and temperature monitoring compliance infrastructure. Watch MOHAP enforcement intensity as the inflection signal determining which operators absorb digitization costs versus face market exit pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Infrastructure Expansion | Kitopi's centralized production model enables delivery-native brand launches without storefront capital overhead. |
| Halal Supply Chain Certification Investment | BSI-compliant supplier networks reduce cross-border qualification timelines and enable menu standardization. |
| Subscription Loyalty Program Deployment | McDonald's Golden Arches Rewards ecosystem demonstrates recurring revenue capture from commuter dining patterns. |
| Digital Traceability Compliance Integration | MOHAP-mandated temperature logging systems require IoT sensor deployment across production workflows. |
| Sharjah and Northern Emirates Market Entry | Lower real estate costs in University City and industrial corridors support first-mover positioning before saturation. |
Research Methodology
Independent corroboration across franchise operations executives, cloud kitchen infrastructure managers, municipal licensing authorities, and halal certification auditors underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with supply chain directors at multinational quick-service operators, procurement leads at regional franchise holding companies, and compliance officers navigating MOHAP digitization mandates. Secondary validation drew from Dubai Department of Economic Development licensing records, Abu Dhabi Municipal commercial permit databases, BSI halal certification registries, and aggregator platform commission structure disclosures. Bottom-up outlet counting across emirate-level jurisdictions triangulates against top-down tourism expenditure and residential consumption estimates.
Historical reference periods spanning pre-pandemic baseline through recovery-phase normalization anchor the forecast window, with modeling assumptions stress-tested across multiple scenario pathways. Segmentation dimensions include service format, customer type, distribution channel, and price tier, with additional granularity on halal certification compliance level and cloud kitchen versus traditional storefront operational model. CAGRs derive from emirate-level demand density projections, tourism corridor development pipelines, and regulatory compliance cost trajectories. Industry-specific inputs incorporate visa policy volatility assumptions and aggregator market concentration dynamics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to labor visa policy shifts, delivery platform commission renegotiations, and MOHAP enforcement intensity variations across emirate-level jurisdictions. Forecasts reflect documented assumptions regarding tourism recovery trajectories and cloud kitchen infrastructure buildout schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Philippines Foodservice Market
Food Service
Chile Food Delivery Market
Food Service
A La Carte Market
Food Service
Retail Bubble Tea Kits Market
Food Service
Africa Foodservice Market
Food Service
Commercial Steam Table Market
Food Service
Virtual Kitchen Market
Food Service
Vietnam Online Food Delivery Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
Electric Tiffin Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Switzerland Food Service Market
Food Service
United States Online Food Delivery Market
Food Service
Flat Top Grills Market
Food Service
Asia Pacific Food Platform-To-Consumer Delivery Market
Food Service
Beverage Napkins Market