
 Restaurant Glassware Market | 2026-2036
Restaurant Glassware Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurant Glassware Market Analytics
Multi-source procurement toward captive furnace operations is restructuring supply economics for large hospitality networks. Arc International leverages vertical integration across European sand-to-shelf operations. Libbey Inc. anchors North American production with in-house tempering capacity. Sisecam Glassware competes through geographic dominance in Middle Eastern and Asian foodservice channels.
Restaurant glassware encompasses drinking vessels manufactured from soda-lime silica, lead-free crystal, or thermally tempered glass, typically annealed at 500–600°C to achieve mechanical durability for commercial dishwasher cycles and repeated thermal shock. Wine glasses command premium positioning within the product type dimension, while polycarbonate and acrylic alternatives capture fast-casual volume through break-resistance specifications. The end user dimension shows fine dining sustaining margin pools through crystal stemware, whereas fast food channels standardize on stackable tumblers for operational throughput.
EU REACH and F-Gas Regulation frameworks govern furnace emissions and cadmium-lead content thresholds, compelling manufacturers to certify batch compositions or risk market exclusion. FDA and state-level California Proposition 65 requirements impose parallel compliance burdens on imports entering US foodservice distribution. Stakeholders must monitor evolving extended producer responsibility schemes in France and Germany that will reshape end-of-life collection obligations for commercial tableware.
Market Dynamics
Full-service restaurant chains are compressing stemware replacement cycles while EU furnace emissions rules force batch composition recertification, restructuring procurement economics toward captive manufacturing and regional compliance clusters.
Growth Catalysts
- REACH cadmium-lead thresholds:ECHA mandates are accelerating certified lead-free crystal adoption across German hospitality procurement networks, elevating material specifications for durable tableware.
- Tempered glass thermal shock performance:Annealing at 500–600°C enables mechanical durability for commercial dishwasher cycles, expanding replacement demand from high-throughput foodservice operators.
- Fine dining margin pools:Crystal stemware sustains premium positioning within full-service channels, concentrating procurement spend on certified durable specifications.
Market Restraints
- Natural gas input volatility:Glass furnace operations face energy cost pressure from fossil fuel price swings, compressing margins for non-integrated manufacturers.
- F-Gas Regulation compliance friction:EU emissions standards impose capital-intensive furnace retrofits, creating exclusion risk for smaller batch producers.
- Polycarbonate substitution:Fast-casual channels are standardizing on break-resistant acrylic alternatives, limiting volume expansion for traditional soda-lime silica.
Strategic Opportunities
- Extended producer responsibility schemes:France and Germany are mandating end-of-life collection obligations for commercial tableware, creating service-revenue streams for compliant manufacturers.
- California Proposition 65 alignment:FDA parallel requirements on imports enable dual-certification strategies for suppliers accessing US foodservice distribution.
- Fast-casual stackable tumbler standardization:Operational throughput demands in high-volume channels favor uniform specifications, opening volume contracts for tempered glass producers.
Industry Challenges
- Batch composition certification timelines:REACH documentation requirements delay product launches by months, straining R&D-to-market pipelines.
- Commercial dishwasher compatibility testing:Repeated thermal shock validation demands specialized equipment and protocols, raising capex barriers for new entrants.
- Sand-to-shelf integration complexity:Captive furnace operations require coordination across mining, melting, and finishing stages, constraining operational flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurant Glassware Market |
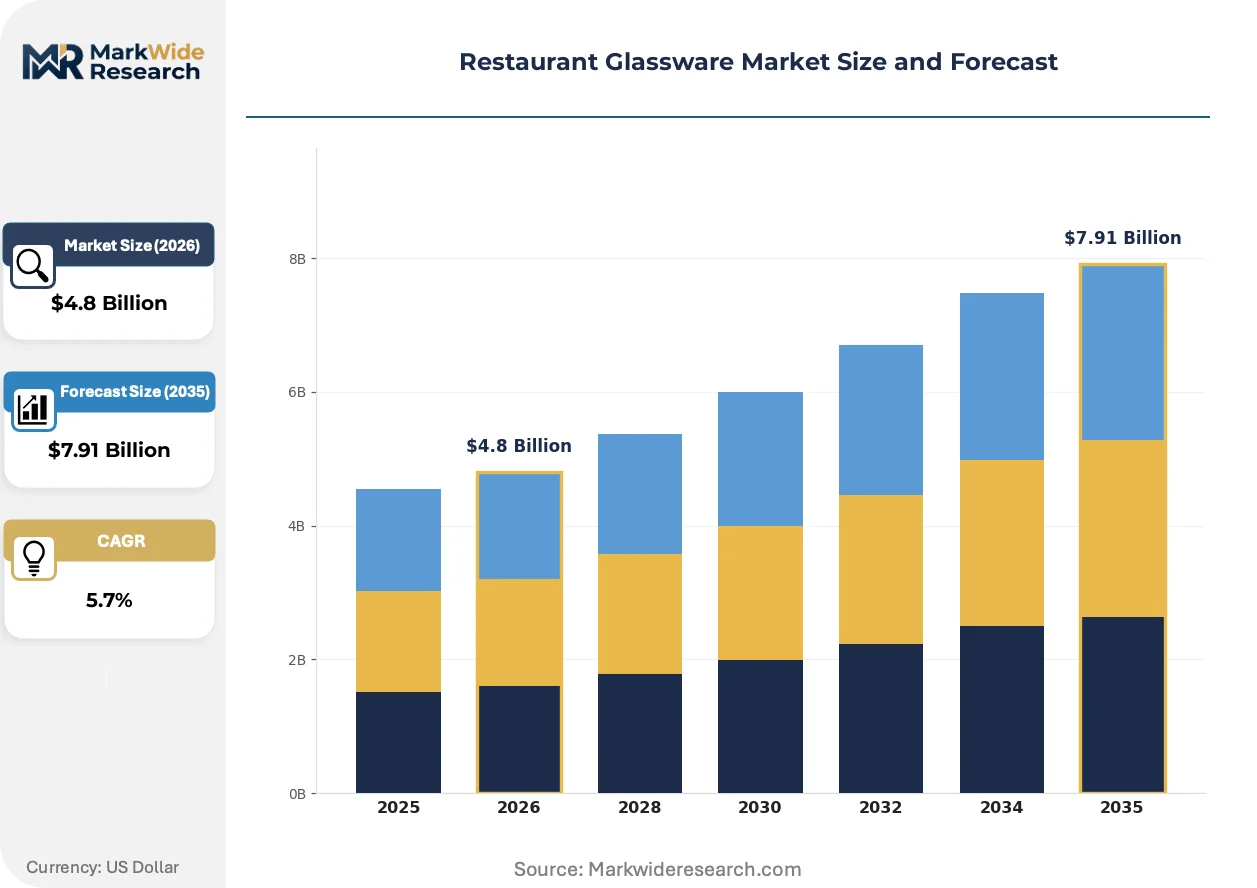
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wine Glasses, Beer Mugs, Tumblers, shot Glasses Material: Crystal, Glass, Polycarbonate, Acrylic End User: Fine Dining, Casual Dining, Fast Food, Bars Size: Standard, Large, Mini, Gigantic |
| Companies Covered | Arc International, Libbey Inc., Bormioli Rocco S.p.A, Sisecam Glassware, Anchor Hocking LLC, Oneida, Villeroy & Boch AG, Steelite International, Ocean Glass Public Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurant Glassware Market Evolving Landscape
Material science advances and regulatory stringency are converging to reshape furnace economics and procurement specifications across hospitality supply chains.
Thermally tempered glass is absorbing mechanical stress requirements previously met by thicker-walled soda-lime vessels. Full-service restaurant chains are adopting these specifications for high-cycle dishwasher environments. The technology is absorbing premium positioning from traditional crystal in mid-tier hospitality procurement.
F-Gas Regulation frameworks are tightening furnace emissions thresholds across EU member states. Batch producers must certify reduced fluorinated gas releases or face market exclusion. German hospitality procurement clusters are prioritizing suppliers with verified low-emission melting operations.
Buyer concentration around durable crystal and tempered specifications is consolidating procurement decisions within centralized hospitality networks. Independent distributors are losing share to direct manufacturer relationships with large restaurant groups. This pattern is most visible in North American full-service channels where replacement cycle standardization dominates sourcing strategy.
Restaurant Glassware Market Segmentation
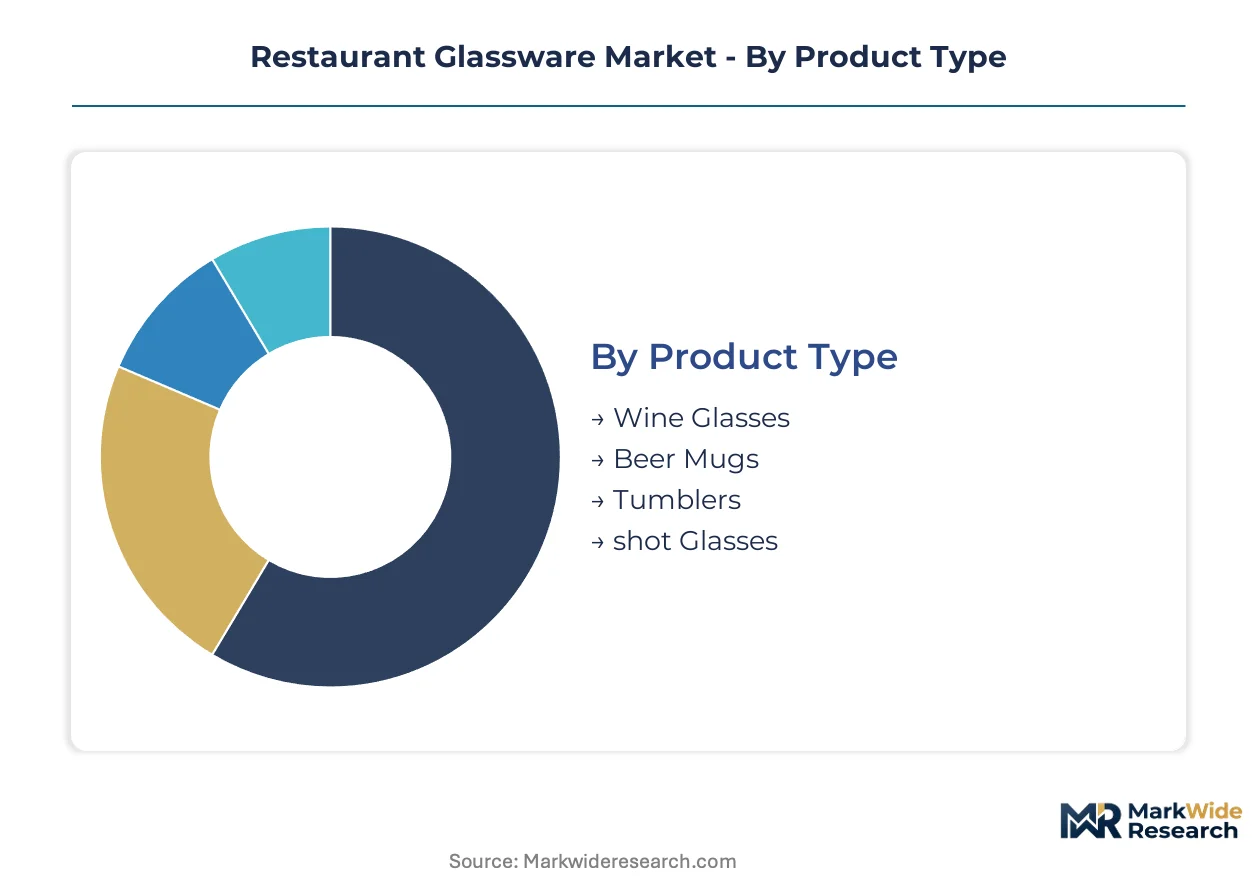
Restaurant glassware procurement clusters around durability certifications and thermal shock specifications that vary sharply by service tier. Material composition and end-use channel dictate which regulatory frameworks apply, creating divergent compliance economics across segment boundaries.
Product Type:
REACH cadmium-lead thresholds and FDA migration limits apply differentially: stemware faces stricter heavy metal scrutiny than stackable serveware.
- Wine Glasses:Lead-free crystal and thermally tempered soda-lime silica dominate fine dining specifications, with annealing at 500–600°C required for commercial dishwasher survival. German hospitality networks concentrate procurement spend here, prioritizing ECHA-certified batch compositions for durability.
- Tumblers:Standardized stackable specifications capture fast-casual volume contracts, with tempered glass displacing thicker-walled alternatives in high-throughput environments. Operational efficiency demands uniform rim diameters and nesting geometry.
- Beer Mugs:Heavy-wall construction and handle durability specifications serve casual dining and bar channels.
- Shot Glasses:Miniature format with thick bases resists breakage in high-velocity service environments.
Leading the category by volume: Tumblers. Growing fastest: Wine Glasses.
Material:
Cost tier stratification separates premium certified grades from commodity alternatives, with energy-intensive furnace operations concentrating in integrated suppliers.
- Crystal:Lead-free formulations meeting ECHA mandates command premium positioning in full-service channels. German procurement clusters specify durable crystal for replacement cycle extension.
- Glass:Soda-lime silica with thermal tempering dominates mid-tier foodservice through mechanical durability and dishwasher compatibility.
- Polycarbonate:Break-resistant polymers capture outdoor and high-velocity casual dining applications.
- Acrylic:Lightweight shatterproof alternative for fast-casual volume channels.
Highest margin concentration: Crystal. Steepest expansion trajectory: Tempered glass.
End User:
Customer type determines replacement cycle velocity and specification stringency, from annual stemware refresh programs to multi-year tumbler deployments.
- Fine Dining:Crystal stemware sustains premium positioning with certified lead-free specifications and extended replacement cycles.
- Fast Food:Standardized tempered tumblers prioritize operational throughput and stackability.
- Casual Dining:Mixed material procurement balances durability cost with aesthetic requirements.
- Bars:High-velocity service demands impact-resistant specifications and rapid replacement protocols.
Procurement spend concentrates: Fine Dining. Volume scales fastest: Fast Food.
Size:
Format dimensions correlate with channel-specific serving protocols and storage constraints across hospitality operations.
- Standard:Universal format compatible with commercial dishwasher racks and universal shelving systems.
- Large:Oversized specifications for craft beverage presentation and shareable formats.
- Mini:Tasting portions and flight service configurations.
- Gigantic:Novelty and promotional applications with limited commercial deployment.
Dominant procurement format: Standard. Emerging specification: Large.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sand deposits in the German Rhineland and Czech Bohemia anchor furnace economics across European glassware production. Hospitality procurement networks in these basins concentrate demand for certified lead-free crystal and thermally tempered specifications. Regulatory pressure from Brussels and national capitals is reshaping where batch melting occurs and which suppliers retain market access.
Germany
Fine dining procurement clusters in Bavaria and North Rhine-Westphalia drive certified crystal demand through centralized hospitality networks. ECHA REACH cadmium-lead thresholds compel batch composition recertification for furnace operators supplying German foodservice channels. The Rhenish sand basin around Cologne anchors captive melting operations for durable tableware specifications.
United States
Full-service restaurant chains compress stemware replacement cycles while fast-casual operators standardize on tempered tumblers for operational throughput. FDA migration limits and California Proposition 65 requirements impose dual compliance burdens on imports entering foodservice distribution. Ohio and Pennsylvania host integrated manufacturing clusters with in-house tempering capacity serving North American hospitality networks.
France
Extended producer responsibility schemes mandate end-of-life collection obligations for commercial tableware, creating service-revenue opportunities for compliant manufacturers. ANSM and environmental ministry frameworks govern cadmium content thresholds in glass batch compositions. The Paris hospitality basin concentrates procurement decisions for premium crystal specifications across Île-de-France restaurant groups.
China
MIIT furnace efficiency standards and GB product safety certifications govern export-oriented glassware production for international foodservice channels. The Yangtze River Delta and Pearl River Delta manufacturing clusters supply tempered glass specifications to fast-casual operators globally. NMPA-aligned testing protocols enable dual-certification strategies for suppliers accessing regulated Western markets.
Italy
Specialized crystal and decorative glass traditions in Lombardy and Veneto sustain premium positioning within European fine dining procurement networks. CE marking requirements and EU Green Deal alignment pressure furnace operators to verify reduced emissions profiles. The Murano-Venice industrial cluster maintains artisanal crystal production alongside scaled tempered glass operations for commercial hospitality.
Restaurant Glassware Market Competitive Landscape
Backward integration into captive furnace operations dominates the current landscape as manufacturers secure sand-to-shelf control over batch composition and compliance certification. The vendor base stratifies across three tiers: integrated multinationals with European and North American melting capacity, regional specialists serving single geographies, and commodity fabricators dependent on third-party glass supply. Strategic archetypes include sand-to-shelf integrators, compliance-certified regional champions, and volume-driven fast-casual suppliers. Capacity expansion and M&A activity concentrate among integrated players seeking furnace control, while technology licensing agreements spread tempered glass specifications to second-tier manufacturers.
Among integrated European operators, Arc International and Libbey Inc. exemplify the sand-to-shelf archetype through captive melting and finishing operations. Sisecam Glassware occupies a position bridging Middle Eastern supply bases with Asian foodservice channel access. These three anchors represent distinct geographic and structural approaches to furnace economics, compliance certification, and hospitality procurement relationships.
| Leading Market Players |
|---|
| Arc International |
| Libbey Inc. |
| Bormioli Rocco S.p.A |
| Sisecam Glassware |
| Anchor Hocking LLC |
| Oneida |
| Villeroy & Boch AG |
| Steelite International |
| Ocean Glass Public Company Limited |
| Others |
Value Network & Pricing Analysis
Family-owned mid-caps across the Czech Bohemian and German Rhenish basins anchor furnace operations with patient capital, enabling batch composition recertification investments that commodity fabricators cannot match. This ownership pattern concentrates pricing power among integrated producers while forcing price discipline on third-party dependent suppliers.
Pricing Analysis
Warranty and breakage-replacement terms separate bundled hospitality contracts from unbundled spot transactions. Three-tier pricing structure across premium crystal, certified tempered glass, and commodity soda-lime tiers reflects ECHA certification status and thermal shock test documentation. Pricing pressure stems from natural gas cost volatility compressing margins at non-integrated furnace operators. Fast-casual chains exhibit highest price sensitivity through standardized tumbler procurement, while fine dining networks absorb premium crystal premiums for replacement cycle extension.
Supply Chain Analysis
Single-source vulnerability sits with high-purity silica sand deposits concentrated in Germany's Rhineland and the Czech Republic's Bohemian region. Captive mining operations draw from these geological basins, while soda ash and limestone feedstocks rest on dispersed chemical industry supply. Tariff exposure on furnace equipment imports from China threatens smaller batch producers. Distribution runs through direct manufacturer relationships with large hospitality networks, bypassing independent distributors losing share to centralized procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where F-Gas Regulation compliance costs force smaller furnace operators toward exit or acquisition by integrated multinationals with capital reserves for emissions retrofitting.
For Market Incumbents: Deepen backward integration into captive sand mining around Cologne and Teplice to secure batch composition control for REACH certification. Expand in-house tempering capacity in Ohio and Pennsylvania to serve North American full-service chains compressing replacement cycles. Polycarbonate substitution in fast-casual channels threatens soda-lime volume, requiring certification investment in lead-free crystal to defend premium positioning. For New Entrants and Emerging Players: Thermally tempered glass with 500–600°C annealing specifications offers entry into mid-tier foodservice procurement previously closed to uncertified suppliers. Target fast-casual tumbler standardization programs in the United States where operational throughput demands uniform rim diameters and nesting geometry. Pursue white-label manufacturing partnerships with established distributors lacking furnace control. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with verified low-emission melting operations in Germany and France facing capital constraints for F-Gas retrofits. Long-term viability hinges on sand-to-shelf integration depth across the analysis window. Monitor extended producer responsibility scheme implementation in France and Germany as inflection indicator for service-revenue model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Furnace Acquisition | Secures batch composition control for ECHA REACH compliance certification. |
| Thermal Tempering Capacity Expansion | Enables mechanical durability specifications for commercial dishwasher cycle survival. |
| Dual-Certification Investment | Aligns FDA migration limits with California Proposition 65 for US market access. |
| Extended Producer Responsibility Compliance | Creates end-of-life collection revenue streams under French and German mandates. |
| Direct Hospitality Network Partnerships | Bypasses distributor intermediaries losing share to centralized procurement clusters. |
Research Methodology
Trade association filings, customs import records, and furnace operator emissions disclosures formed the secondary backbone, cross-referenced against primary interviews with hospitality procurement directors, glass batch chemists, and foodservice distribution executives. Bottom-up volume estimates from tempered glass annealing capacity and top-down value projections from fine dining crystal spend were triangulated for convergence.
Historical trendline analysis tracked replacement cycle compression in full-service chains and polycarbonate substitution rates in fast-casual channels across the analysis window. Segmentation modeling incorporated product type, material composition, end-user channel, and geographic regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves and furnace capacity expansion pipelines, with natural gas price volatility and REACH recertification timelines as key forecast inputs.
Several conditions sit outside the modeled scope, including sovereign trade policy shifts, breakthrough materials displacing soda-lime silica, and hospitality sector demand collapses from macroeconomic contraction. Forecasts reflect documented assumptions about regulatory enforcement intensity and procurement standardization velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Catering Food Warmers Market
Food Service
Europe Food Away from Home Market
Food Service
Portable Buffet and Drop-In Ranges Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Food Away from Home Market
Food Service
Pizza Foodservice Market
Food Service
Restaurants in Belgium Market
Food Service
Gas Floor Fryers Market
Food Service
Bahrain Food Service Market
Food Service
Asia Pacific Airline Catering Services Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Food Service Utensils Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
China Food Service Market
Food Service
UAE Food Service Market