
 Flat Top Grills Market | 2026-2036
Flat Top Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Top Grills Market Analytics
Commercial kitchen buyers is collapsing into food trucks and catering operators as the fastest-growing buyer archetype, while traditional full-service restaurant procurement flattens. Blackstone dominates the residential and portable segments through massive retail distribution. Weber leverages its brand heritage in outdoor cooking to extend into premium flat top configurations. Nexgrill competes aggressively on price at big-box retail, anchoring volume in the entry-level gas segment.
Flat top grills are cooking appliances with broad, level steel or cast-iron cooking surfaces heated by gas burners, electric elements, or charcoal beds, typically maintaining temperatures between 300°F and 600°F for simultaneous preparation of diverse menu items. The primary commercial purpose centers on high-throughput, versatile food preparation where multiple ingredients occupy one continuous surface without falling through grates. Gas configurations lead absolute unit volume due to established infrastructure and rapid heat recovery, while electric variants capture the fastest growth in jurisdictions restricting open-flame commercial equipment. Portable grills concentrate margin pools through premium pricing for compact, high-output designs targeting mobile food service operators.
The US EPA regulates commercial cooking equipment emissions under Clean Air Act frameworks, pushing gas grill manufacturers toward lower-NOx burner designs. NSF International standards govern food equipment sanitation certification, creating a compliance gateway for commercial market access. The EU Ecodesign Directive shapes European product efficiency requirements, affecting export-bound manufacturing programs. Stakeholders must monitor how municipal fire codes and ventilation ordinances in dense urban districts restrict propane storage, as these local rules increasingly determine whether mobile food operators can deploy gas flat tops or must shift to electric alternatives.
Market Dynamics
Mobile food service operators are compressing the buyer base toward portable, high-output equipment configurations, while stationary commercial kitchens face flattening replacement cycles. The EPA's tightening emissions standards for commercial cooking equipment are forcing gas burner redesigns across domestic manufacturing footprints.
Growth Catalysts
- Clean Air Act compliance pathways:The EPA's lower-NOx mandates for commercial cooking equipment are accelerating burner technology upgrades. Manufacturers capturing certification early secure preferential placement with municipal procurement offices.
- Food truck fleet expansion:Urban corridors in Texas, California, and Florida are witnessing concentrated permit issuance for mobile dining operations. These operators prioritize compact, high-BTU flat tops for menu versatility in constrained footprints.
- Electric infrastructure maturation:Jurisdictions restricting open-flame commercial equipment are expanding grid capacity for high-draw electric cooking. NSF-certified electric configurations are penetrating food halls and airport terminals where propane storage faces fire code prohibitions.
Market Restraints
- Steel price volatility:Cold-rolled steel and cast-iron cooking surface inputs face commodity fluctuation. Domestic foundry capacity constraints amplify cost unpredictability for mid-tier manufacturers.
- Propane storage ordinances:Dense urban districts including Manhattan, Chicago, and San Francisco enforce strict ventilation and tank-size restrictions. These municipal fire codes block gas flat top deployment regardless of EPA compliance status.
- Griddle plate performance ceilings:Thermal uniformity across broad steel surfaces degrades at extreme commercial throughput. Recovery lag during peak service windows limits menu expansion for high-volume operators.
Strategic Opportunities
- Induction-convection convergence:Hybrid electric systems combining induction zones with forced-air convection are emerging. Early adopters in airport and stadium concessions report 40% energy reduction versus traditional gas configurations.
- Certification arbitrage:NSF International sanitation certification creates a compliance gateway that uncertified imports cannot cross. Domestic manufacturers with established certification pipelines can command premium positioning in institutional procurement.
- Aftermarket service unbundling:Griddle plate resurfacing, burner calibration, and control system upgrades are separating from equipment sales. Independent service networks in Texas and California are capturing recurring revenue streams previously retained by OEMs.
Industry Challenges
- Cross-trained technician scarcity:Simultaneous gas, electric, and control system expertise is concentrated among aging workforce cohorts. Vocational programs have not scaled to replace retirement-driven attrition in commercial cooking equipment repair.
- Multi-certification timeline compression:NSF sanitation, UL electrical safety, and local fire authority approvals operate on non-aligned review cycles. Product launches face 8-14 month delays when certifications serialize rather than parallelize.
- Legacy ventilation integration:Existing commercial kitchen hood systems are sized for previous equipment heat loads. Electric flat top retrofits trigger expensive HVAC re-engineering that erodes equipment upgrade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Top Grills Market |
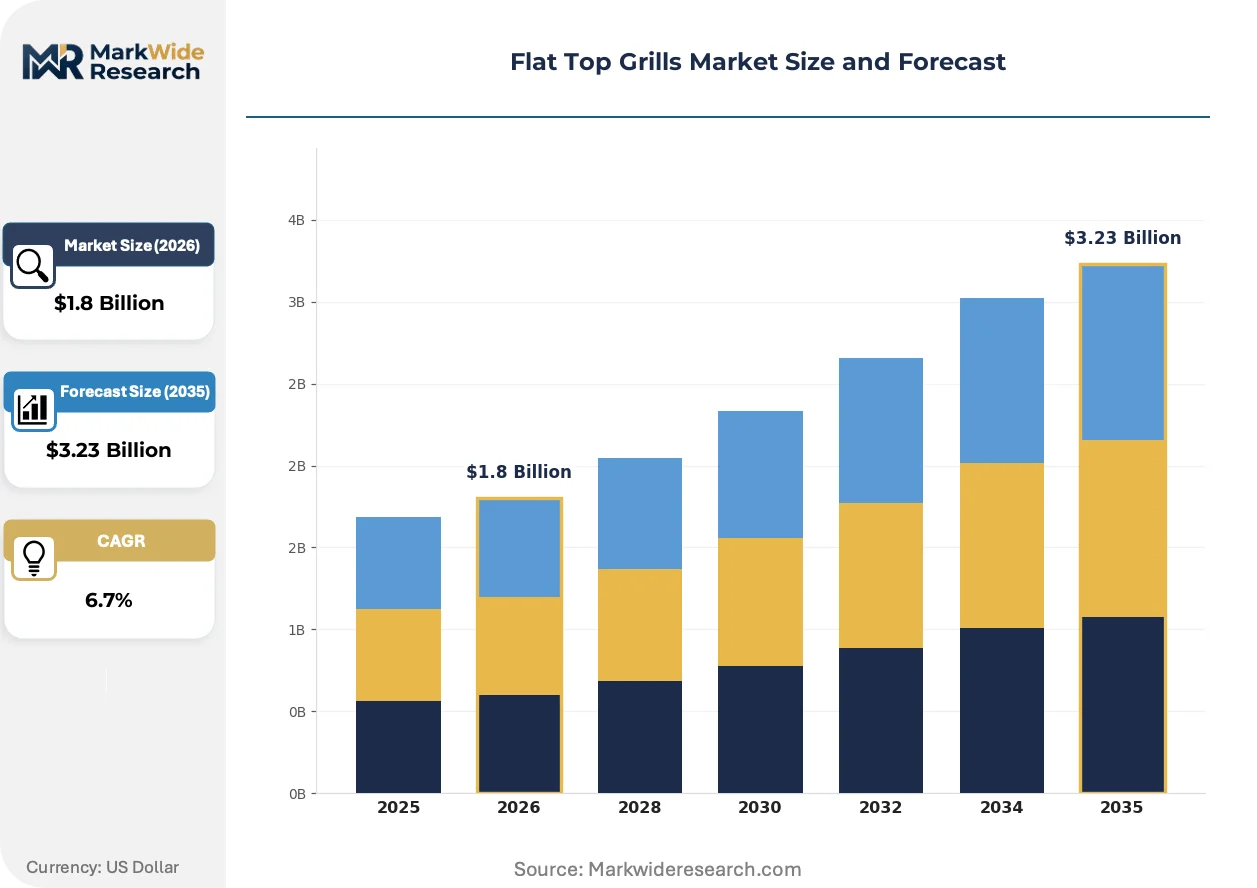
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Grills, Residential Grills, Portable Grills, Outdoor Grills Fuel Type: Gas, Electric, Charcoal, Induction End User: Restaurants, Food Trucks, Home Users, Catering Services Size: Small, Medium, Large, Extra Large |
| Companies Covered | Blackstone, Weber, Nexgrill, Pit Boss, Traeger, Camp Chef, GriddleKing, Royal Gourmet, Monument Grills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Top Grills Market Evolving Landscape
Equipment intelligence and surface material science are converging to reshape competitive positioning across price tiers. Manufacturers are racing to embed monitoring capabilities while re-engineering thermal performance fundamentals.
Modular induction zones are fragmenting the traditional monolithic griddle surface. These segmented heating elements enable precise temperature zoning across a single cooking plane. Food truck operators in Austin and Los Angeles are adopting configurations with six independent zones for simultaneous protein, vegetable, and carbohydrate preparation. The technology is fragmenting equipment specification patterns, as buyers abandon uniform-surface designs in favor of application-specific thermal mapping.
The EPA's commercial cooking equipment emissions standards are mandating burner redesigns with staged combustion and pre-mixed air-fuel ratios. These technical requirements are elevating engineering costs for gas configuration development. Small and mid-tier manufacturers without captive combustion R&D are licensing designs or exiting the gas segment entirely, concentrating gas innovation among vertically integrated producers with EPA pre-certification relationships.
Leasing and equipment-as-service contracts are displacing outright purchase in food truck and catering operator procurement. These arrangements bundle maintenance, certification renewal, and upgrade pathways into monthly payments. The model is most visible in Texas, where outdoor cooking culture supports higher equipment turnover and where fleet operators prioritize operational flexibility over asset ownership. Distributors with captive financing capabilities are capturing account control previously held by manufacturers.
Flat Top Grills Market Segmentation
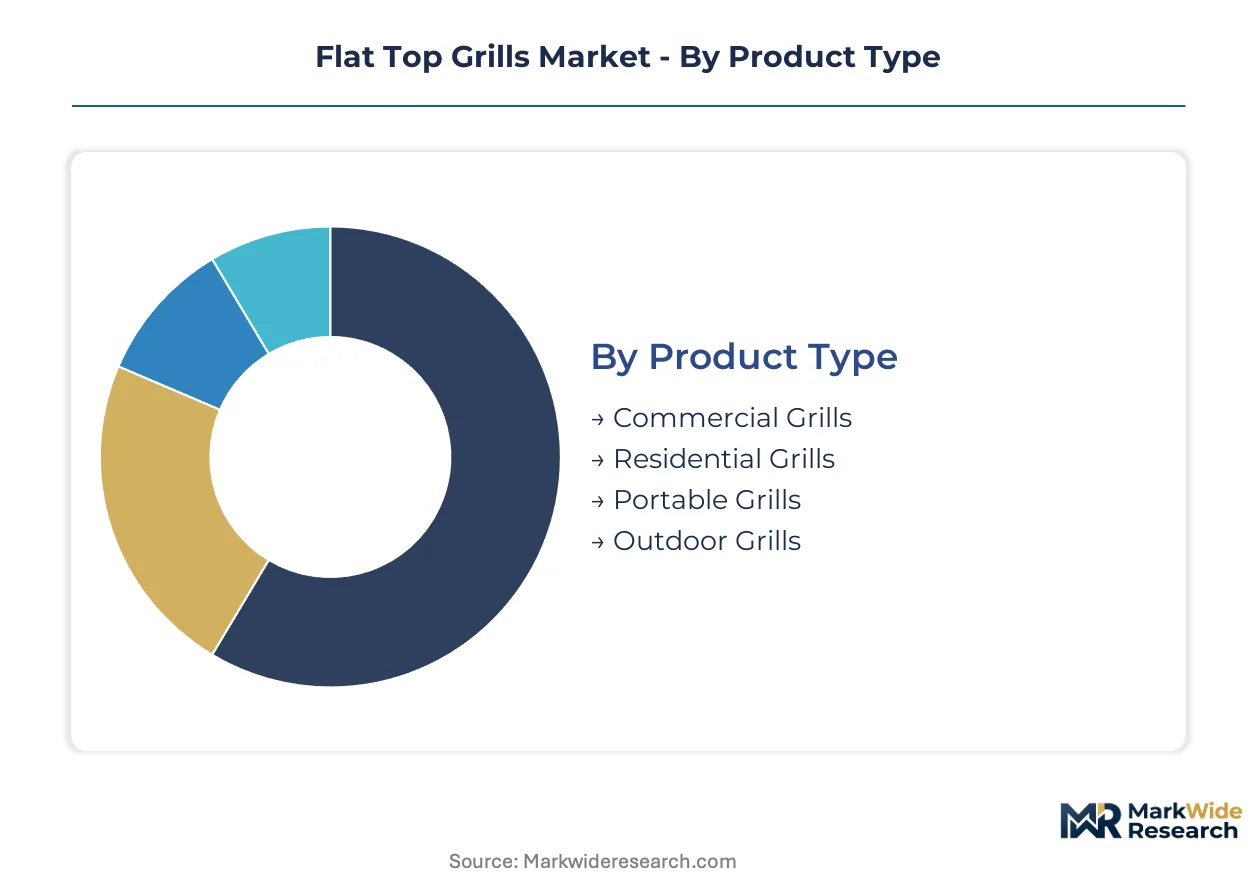
Flat top grill procurement patterns fragment sharply across use environments, with regulatory compliance, mobility requirements, and thermal output needs driving divergent specification paths. Understanding these segment boundaries clarifies where manufacturers must align certification investments with buyer purchasing criteria.
Product Type:
EPA emissions standards and NSF sanitation certification create divergent compliance burdens across stationary versus mobile configurations.
- Commercial Grills:Heavy-gauge steel construction with 36-inch to 72-inch cooking surfaces dominates institutional kitchens. Demand clusters in Texas and California food halls where health department inspections mandate NSF-certified surfaces and integrated grease management.
- Portable Grills:Compact footprints under 30 inches with folding legs or cart-mounted designs serve mobile operators. Food truck fleets in Austin, Houston, and Los Angeles drive specification toward high-BTU output in constrained dimensions, with electric variants gaining share where propane storage faces municipal restrictions.
- Residential Grills:Consumer-grade configurations prioritize ignition reliability and temperature control simplicity over throughput durability. Patio installation in suburban markets favors propane convenience over charcoal handling complexity.
- Outdoor Grills:Weather-resistant construction with stainless steel exteriors and covered burner systems addresses permanent exterior installation. Seasonal operation patterns in northern states concentrate replacement cycles in spring procurement windows.
Established volume favors Commercial Grills; emerging adoption favors Portable Grills.
Fuel Type:
Utility infrastructure maturity and local fire codes determine feasible energy sources across operating environments.
- Gas:Propane and natural gas configurations deliver rapid heat recovery and precise flame control through cast-iron burner arrays. The EPA's lower-NOx mandates are forcing burner redesigns with pre-mixed air-fuel ratios, elevating engineering costs for domestic manufacturers.
- Electric:Resistance-element or induction-based systems eliminate combustion emissions and ventilation requirements. Jurisdictions including Manhattan and San Francisco with strict propane storage ordinances are accelerating electric specification for new commercial installations.
- Charcoal:Lump charcoal or briquette combustion delivers distinct flavor profiles through radiant heat transfer. Regulatory restrictions on particulate emissions limit commercial deployment to exempted outdoor events and specialty barbecue operations.
- Induction:Electromagnetic heating through ferromagnetic griddle plates achieves rapid temperature response with 90-plus percent energy efficiency. Airport terminals and stadium concessions are piloting induction zones for reduced HVAC load and elimination of open-flame insurance surcharges.
Gas retains dominant installed base; induction and electric configurations are climbing the fastest as urban fire codes tighten.
End User:
Capital availability and operating tempo shape equipment durability requirements and financing preferences.
- Restaurants:Full-service and quick-service kitchens specify heavy-duty construction with 100,000-plus BTU output for peak service windows. Replacement cycles are flattening as post-pandemic capital expenditure constraints extend equipment depreciation schedules.
- Food Trucks:Mobile operators prioritize compact dimensions, multi-fuel flexibility, and equipment-as-service leasing arrangements. Texas fleet operators are driving adoption of modular configurations that permit rapid menu format switches between breakfast, lunch, and dinner service.
- Home Users:Residential buyers respond to retail distribution density and brand heritage cues in outdoor cooking. Weekend usage patterns prioritize ignition convenience and surface seasoning simplicity over commercial-grade thermal mass.
- Catering Services:Event-based operators require transportable equipment with rapid setup and breakdown capabilities. Rental and lease-to-own arrangements are displacing outright purchase as operators prioritize balance sheet flexibility for seasonal revenue fluctuations.
Restaurant procurement dominates absolute spend; food truck and catering segments are gaining share fastest through fleet expansion and service model innovation.
Size:
Kitchen footprint constraints and menu complexity determine surface area requirements across buyer categories.
- Small:Cooking surfaces under 24 inches suit compact food trucks, concession carts, and residential balconies. Austin and Los Angeles mobile operators are specifying small-format electric units for compliance with space-constrained permit locations.
- Medium:24-inch to 36-inch surfaces balance throughput and footprint for independent restaurants and catering operations. This configuration captures the broadest cross-section of commercial buyers seeking versatility without dedicated hood system upgrades.
- Large:36-inch to 48-inch surfaces support high-volume protein and vegetable preparation in institutional cafeterias and hotel kitchens. Thermal uniformity engineering becomes critical at this scale to prevent cold zones during peak service.
- Extra Large:Surfaces exceeding 48 inches serve centralized commissary operations and stadium concession preparation. Custom fabrication requirements and specialized ventilation needs limit this segment to dedicated food service contractors with captive facility engineering.
Medium formats anchor procurement volume; small and extra large configurations are expanding most quickly at the segment extremes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 35 corridor through Texas anchors North American flat top grill demand, connecting Dallas-Fort Worth distribution hubs to Austin and San Antonio food truck clusters with dedicated propane supply chains and year-round outdoor cooking conditions.
United States
Texas, California, and Florida food truck fleets drive portable equipment procurement with high-BTU specifications for constrained mobile kitchens. The EPA's lower-NOx mandates for commercial cooking equipment under Clean Air Act frameworks force burner redesigns across domestic manufacturing. Austin mobile operators are adopting modular electric configurations where municipal fire codes restrict propane storage.
Germany
Industrial kitchen equipment buyers prioritize NSF-equivalent sanitation certification for food hall and institutional procurement. The EU Ecodesign Directive shapes efficiency requirements for export-bound manufacturing programs. Bavarian commercial kitchen distributors are consolidating procurement relationships with certified electric configuration suppliers.
China
Domestic foundry capacity supports cold-rolled steel cooking surface production for mid-tier global supply. The country's national environmental regulator enforces industrial emissions standards affecting steel input costs. Guangdong manufacturing clusters are specializing in compact electric griddle assemblies for Southeast Asian export markets.
Japan
High-efficiency induction heating technology development concentrates among precision electronics manufacturers. METI energy efficiency guidelines accelerate electric cooking equipment specification in commercial sectors. Osaka-Kobe industrial corridors are piloting hybrid induction-convection systems for stadium concession applications.
Australia
Outdoor cooking culture sustains residential and commercial premium equipment demand across temperate coastal populations. State-level environmental regulators enforce ventilation standards for open-flame commercial installations. Queensland food service operators are expanding electric flat top fleets in response to bushfire season restrictions on propane storage.
Flat Top Grills Market Competitive Landscape
Concentration sits with vertically integrated outdoor cooking specialists and retail-distributed mass-market brands. The vendor base separates into three tiers: heritage brands commanding premium positioning through distribution control, price-competitive manufacturers anchoring big-box volume, and emerging specialists capturing mobile food service niches. Strategic moves center on certification pipeline acceleration and equipment-as-service financing arrangements that displace outright purchase.
Within the heritage brand tier, Blackstone and Weber exemplify divergent positioning strategies. Blackstone represents retail-distributed mass-market penetration through compact portable configurations. Weber occupies a position translating outdoor cooking brand equity into premium flat top extensions. Nexgrill anchors the price-competitive vector at entry-level gas segments. These three exemplify how distribution density, brand heritage, and cost engineering separate competitive outcomes across buyer archetypes.
| Leading Market Players |
|---|
| Blackstone |
| Weber |
| Nexgrill |
| Pit Boss |
| Traeger |
| Camp Chef |
| GriddleKing |
| Royal Gourmet |
| Monument Grills |
| Others |
Value Network & Pricing Analysis
NSF International sanitation certification gates both supplier qualification and price differentiation simultaneously, forcing uncertified imports into discount positioning while domestic manufacturers with established pipelines capture premium placement in institutional procurement channels.
Pricing Analysis
Volume-discount tiering structures separate NSF-certified commercial configurations from uncertified economy imports, with premium-mid-economy pricing differentiation anchored in certification grade and burner technology sophistication. Food truck and catering operators exhibit highest price sensitivity due to equipment-as-service financing preferences, while institutional buyers prioritize total cost of ownership over upfront capital outlay. Cost compression in the mid-tier gas segment is intensifying because EPA lower-NOx mandates elevate engineering expenses for burner redesigns.
Supply Chain Analysis
Inventory lead times for cold-rolled steel cooking surfaces have extended due to domestic foundry capacity constraints, amplifying cost unpredictability for manufacturers without captive metalworking operations. Production gravity centers on China for compact electric griddle assemblies, the United States for heavy-gauge commercial configurations, and Germany for precision burner components. Raw material dependencies include cold-rolled steel, cast-iron cooking plates, and high-BTU burner arrays. Single-source vulnerability in specialized foundry capacity represents the primary structural risk. Distribution runs through big-box retail for residential segments and dedicated food service distributors for commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward food truck fleet operators and equipment-as-service aggregators, consolidating procurement volume among mobile dining specialists and compressing margins for manufacturers dependent on fragmented restaurant replacement cycles.
For Market Incumbents: Compound certification advantages by accelerating NSF pipeline throughput and securing EPA pre-certification relationships before lower-NOx mandates harden compliance barriers. Vertical integration into burner R&D protects margin pools as licensing costs escalate for mid-tier competitors without captive combustion engineering. For New Entrants and Emerging Players: Anchor in modular electric configurations for airport terminals and stadium concessions where propane storage ordinances block gas equipment deployment regardless of price positioning. Leasing infrastructure partnerships with Texas-based fleet operators offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric and induction configuration development as hybrid system engineering demands precision electronics integration. Acquisition targets should display established certification pipelines and regional distributor relationships rather than pure manufacturing scale. The signal to watch is municipal fire code expansion restricting propane storage in dense urban districts.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certification Pipeline Expansion | Creates compliance gateway that uncertified imports cannot cross in institutional procurement. |
| Equipment-as-Service Financing Launch | Captures recurring revenue streams and account control previously retained by OEMs. |
| Hybrid Induction-Convection Development | Addresses airport and stadium demand for reduced HVAC load and eliminated open-flame insurance surcharges. |
| Aftermarket Service Network Buildout | Griddle plate resurfacing and burner calibration separate from equipment sales in Texas and California. |
| Regional Distributor Consolidation | Strengthens channel control as food truck fleet operators concentrate procurement among fewer partners. |
Research Methodology
Cross-validation between primary fieldwork with food truck operators, commercial kitchen equipment distributors, and NSF certification consultants anchors the qualitative findings against secondary validation from EPA regulatory filings, commercial cooking equipment trade publications, and food service procurement databases. Bottom-up demand modeling triangulates against top-down market sizing across product type, fuel configuration, end-user category, and geographic cluster dimensions.
Sensitivity analysis frameworks test forecast robustness across steel price volatility scenarios, regulatory timeline acceleration assumptions, and electric infrastructure buildout pace variations. Segmentation dimensions modeled include product type, fuel source, end-user category, and equipment size tier. CAGRs derive from installed base growth, replacement cycle compression, and penetration rate assumptions for emerging electric configurations. Industry-specific forecast inputs incorporate food truck permit issuance trends and municipal fire code evolution patterns.
Decision-makers should treat outputs as directional under assumptions of steady EPA enforcement trajectory and continued steel supply normalization; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Cafes & Bars Market
Food Service
Europe Online Grocery Delivery Market
Food Service
Asia-Pacific Online Grocery Delivery Market
Food Service
Workplace Service Market
Food Service
Chinese Takeout Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
Air Fryer Meal Kits Market
Food Service
Mexico Foodservice Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Pasteurized Eggs Market
Food Service
Online Food Delivery Market
Food Service
Cutting Boards Market
Food Service
United States Online Food Delivery Market
Food Service
Global Online Food Delivery Services Market
Food Service
Global Dark Store Market
Food Service
South Africa Fast Food Market