
 Resistivity Meters Market | 2026-2036
Resistivity Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Resistivity Meters Market Intelligence
Demand from semiconductor manufacturers requiring high-precision inline units is bifurcating the market from its traditional base in research laboratories using general-purpose benchtop models. Mettler Toledo leverages its extensive portfolio in industrial process analytics to capture this shift. Concurrently, HORIBA sustains its leadership in high-sensitivity instruments for scientific applications. Hioki differentiates through its specialized meters for electronics testing and component characterization.
A resistivity meter is an instrument designed to measure a material's opposition to the flow of an electric current, typically expressed in ohm-meters (Ω·m). It operates using principles like the four-electrode method to minimize contact resistance errors, providing a precise assessment of material purity or composition. Portable and handheld models command the geophysical survey and field water analysis applications. However, inline systems are gaining share, driven by automation needs in electronics testing and chemical processing.
Regulatory frameworks directly influence instrument specifications and market access. The US EPA sets standards for water quality monitoring, while the EU's RoHS directive mandates material testing in electronics, creating demand for precise resistivity measurement. In Asia, standards from bodies like China's SAMR and Japan's METI guide usage in industrial settings. Success now depends on aligning product development with either high-volume industrial automation or specialized, high-margin scientific instrumentation.
Market Dynamics
The central force is the exacting demand from semiconductor fabrication for ultra-pure water. This requirement, codified by SEMI standards, drives adoption of high-precision, automated inline monitoring to ensure process integrity and yield.
Growth Catalysts
- SEMI Standards:The mandate for ultra-pure water in semiconductor fabrication, governed by SEMI F63, necessitates continuous resistivity monitoring to prevent contamination and ensure high device yields.
- Fabrication Plant Expansion:Construction of new advanced semiconductor foundries, particularly in hubs like South Korea and Taiwan, directly translates to demand for new inline resistivity measurement systems.
- Process Automation:The chemical and pharmaceutical industries are increasingly adopting automated process control, creating demand for inline meters to ensure consistent product quality and regulatory compliance.
Market Restraints
- High Capital Cost:The significant initial investment for high-precision, automated inline resistivity systems acts as a barrier for smaller research labs and budget-constrained facilities.
- Technical Sensitivity:High-purity measurements are susceptible to interference from temperature fluctuations and electromagnetic noise, requiring specialized installation and stable operating environments, which limits deployment.
- Low-End Substitution:For general-purpose water quality checks, lower-cost conductivity and total dissolved solids (TDS) meters provide a sufficient, though less precise, alternative, capping growth in some applications.
Strategic Opportunities
- Battery Manufacturing:The electric vehicle sector creates demand for resistivity meters to assess electrolyte purity and electrode material quality during battery production.
- Pharmaceutical Growth in India:Production-Linked Incentive (PLI) schemes are spurring pharmaceutical manufacturing expansion, creating new demand for resistivity meters to meet water-for-injection (WFI) standards.
- Multi-Parameter Platforms:Integrating resistivity sensors with other analytical monitors, such as pH and TOC, into a single platform addresses the need for comprehensive water quality analysis in treatment plants.
Industry Challenges
- Legacy System Integration:Connecting modern, digital inline resistivity meters with older, analog-based SCADA or distributed control systems in existing industrial facilities presents significant compatibility and software challenges.
- Calibration Expertise Gap:A shortage of technicians with the specialized skills to accurately calibrate and maintain high-sensitivity, multi-electrode systems is a key operational bottleneck for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resistivity Meters Market |
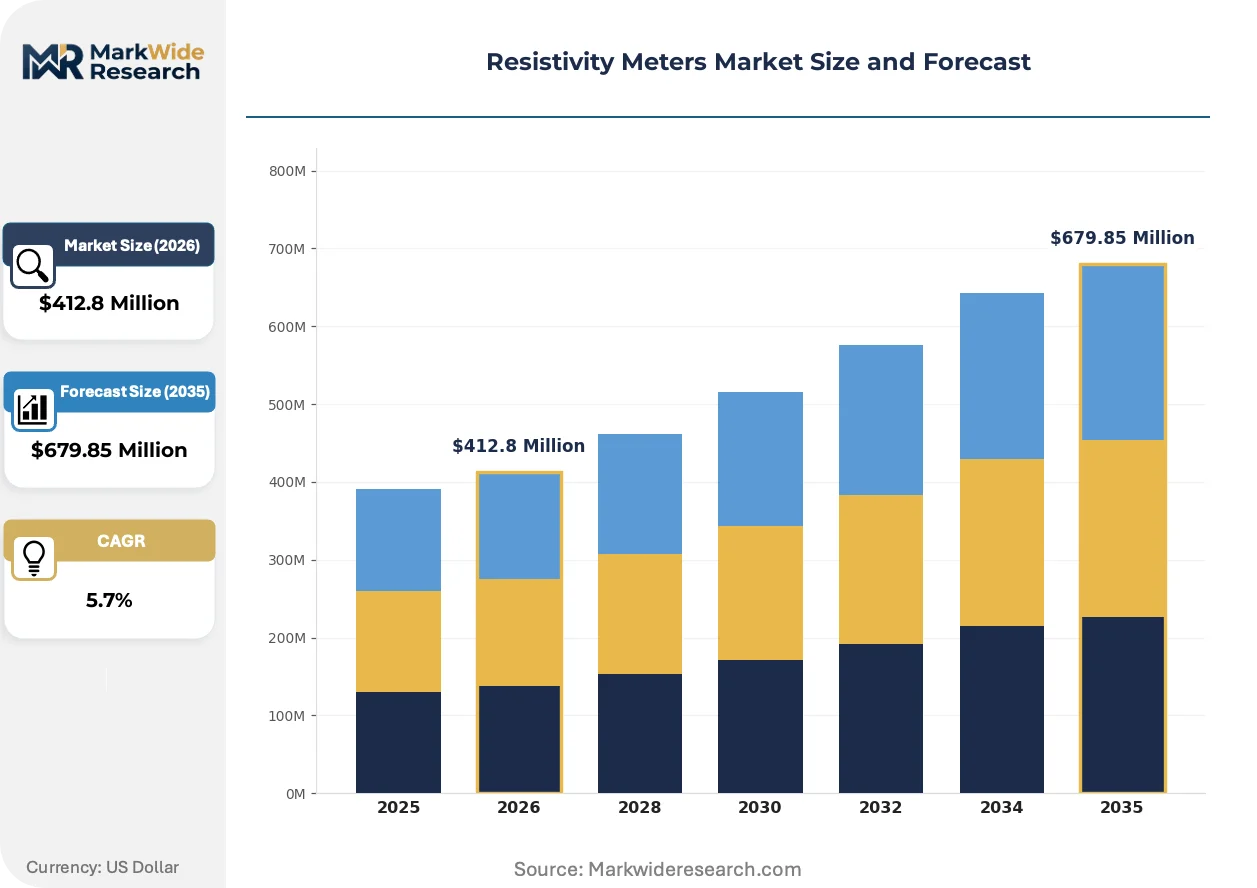
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $679.85 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Portable, Inline, Handheld Technology: Four-Electrode, Two-Electrode, Surface Resistivity, Volume Resistivity Application: Water Quality Analysis, Electronics Testing, Geophysical Surveys, Chemical Processing End User: Research Laboratories, Semiconductor Manufacturers, Petrochemical Plants, Environmental Agencies |
| Companies Covered | Mettler Toledo, HORIBA, Hioki, ACL Staticide, Omega, IRIS Instrument, Fann Instrument Company, IET Labs, Myron L, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resistivity Meters Market Strategic Shifts & Innovations
The market is diverging into two distinct value propositions. One path leads toward high-volume industrial automation, while the other focuses on high-sensitivity, specialized instrumentation for scientific and research applications.
Inline, multi-channel resistivity monitoring systems provide real-time data for automated process control. Semiconductor and pharmaceutical manufacturers are rapidly adopting these systems to comply with stringent purity standards set by bodies like SEMI. This adoption is bifurcating the market, creating a distinct, high-volume industrial segment separate from traditional, single-measurement laboratory instruments used in research.
Compliance with the EU's RoHS directive, which restricts hazardous substances in electronics, is a significant driver. The directive compels manufacturers to verify material purity for components like solders and substrates, a task well-suited for resistivity measurement. The automotive and consumer electronics sectors are most affected, increasing their use of benchtop meters for quality assurance and component characterization.
A shift from outright capital equipment purchase towards managed services or leasing models is emerging for water quality monitoring. This approach displaces the traditional direct sales channel with long-term contracts that bundle instrument calibration, maintenance, and data management. This trend is most visible in municipal water treatment facilities and pharmaceutical plants in North America seeking to convert capital expenditures to operational expenditures.
Resistivity Meters Market Segmentation
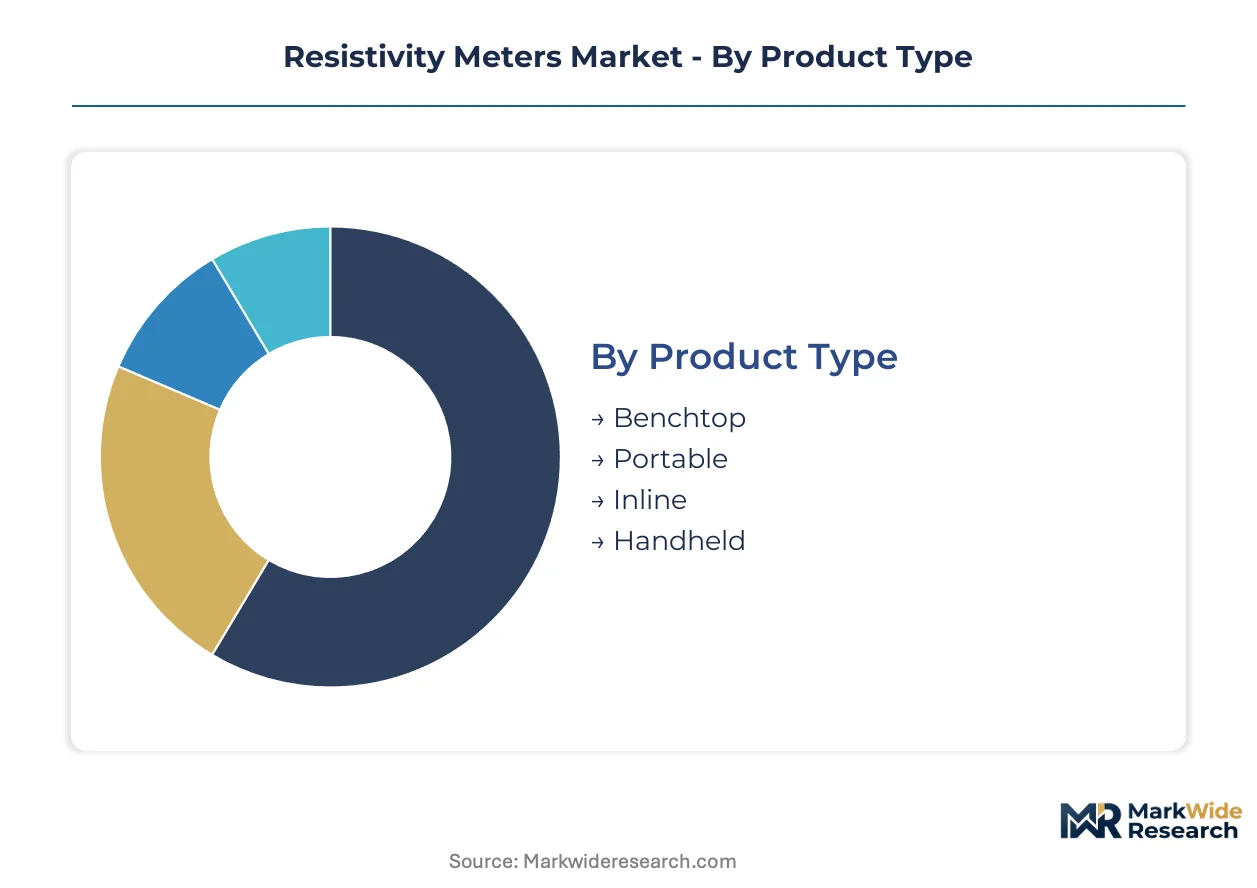
The Resistivity Meters Market is segmented by product type, technology, application, and end user, revealing varied demand patterns and competitive pressures. Understanding these segments helps manufacturers align product development with specific industry requirements and user needs. Distinct technical specifications and regulatory compliance drive purchasing decisions across these categories.
Product Type:
The market experiences substitution pressure from lower-cost alternatives for general water quality checks, particularly impacting basic benchtop and handheld models. However, specialized inline systems face less direct substitution due to their critical role in automated processes.
- Inline:These systems provide continuous, real-time resistivity monitoring directly within process lines. Semiconductor manufacturers in Taiwan and South Korea extensively deploy inline units for ultra-pure water monitoring, ensuring process integrity and high device yields.
- Benchtop:Laboratory-grade instruments offer high precision and versatility for a wide range of analytical tasks. Research laboratories and quality control departments in pharmaceutical companies utilize benchtop meters for detailed sample analysis and method development.
- Portable:Compact and battery-operated devices allow for on-site measurements in diverse environments. Environmental agencies and field service technicians use portable meters for water quality assessments in remote locations.
- Handheld:These basic, entry-level meters provide quick and convenient spot checks. Educational institutions and small industrial facilities employ handheld units for routine water quality verification.
Benchtop units anchor the volume base while inline systems gain share at the steepest rate.
Technology:
Application requirements largely dictate technology adoption, with specific industries favoring methods optimized for their materials and measurement precision. Different technologies offer varying levels of accuracy and sensitivity, influencing their suitability for critical processes.
- Four-Electrode:This method minimizes electrode contact resistance errors, providing highly accurate measurements for conductive materials. Semiconductor fabrication relies on four-electrode systems for precise characterization of silicon wafers and other electronic components.
- Surface Resistivity:Designed to measure the resistance across a material's surface, this technology is crucial for assessing antistatic properties and contamination. Electronics manufacturers use surface resistivity meters to ensure compliance with ESD standards for PCBs and packaging materials.
- Two-Electrode:A simpler and more cost-effective method suitable for basic resistivity measurements in solutions. Water treatment plants often employ two-electrode systems for general water quality monitoring.
- Volume Resistivity:This technology measures the electrical resistance through the bulk of a material. Material science laboratories use volume resistivity meters for polymer and composite characterization.
The Four-Electrode method concentrates significant market value, while Surface Resistivity technology expands most quickly.
Application:
Customer type and regulatory mandates strongly influence the demand for specific resistivity meter applications. Each application requires instruments tailored to unique environmental conditions and measurement parameters.
- Water Quality Analysis:This application focuses on measuring the purity of water in various industrial and municipal settings. Pharmaceutical companies in India utilize resistivity meters for water-for-injection (WFI) standards, driven by PLI schemes.
- Electronics Testing:Involves assessing the electrical properties of electronic components, materials, and assemblies. Automotive electronics manufacturers use resistivity meters for quality assurance of conductive inks and substrates to meet RoHS directives.
- Chemical Processing:Resistivity meters monitor the concentration and purity of chemical solutions during manufacturing. Specialty chemical plants deploy inline meters to maintain consistent product quality in reaction vessels.
- Geophysical Surveys:These applications use resistivity measurements to map subsurface geological structures. Mining companies and civil engineering firms employ portable meters for groundwater exploration and soil characterization.
Water Quality Analysis applications capture the largest segment of demand, and Electronics Testing applications exhibit the steepest expansion trajectory.
End User:
Margin structures vary significantly across end-user segments, with high-volume industrial users often requiring robust, automated solutions, while research institutions prioritize precision and versatility. Each end-user group has distinct purchasing criteria and operational needs.
- Semiconductor Manufacturers:These users require highly precise, automated inline systems for ultra-pure water monitoring and material characterization. New fabrication plants in South Korea and Taiwan are driving substantial demand for advanced resistivity solutions.
- Research Laboratories:These facilities primarily use benchtop and specialized instruments for fundamental scientific inquiry and new material development. Academic institutions and corporate R&D centers rely on high-sensitivity instruments for experimental validation.
- Petrochemical Plants:Resistivity meters monitor process water and chemical purity to prevent corrosion and ensure product specifications. Refineries in the Middle East implement continuous monitoring systems for process optimization.
- Environmental Agencies:These organizations utilize portable and handheld meters for field assessments of water bodies and soil contamination. US EPA standards for water quality monitoring guide instrument specifications for these agencies.
Research Laboratories represent a stable demand base, while Semiconductor Manufacturers are driving the fastest growth in value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-precision resistivity meter trade flows primarily from advanced manufacturing nations to semiconductor fabrication hubs in Asia. Demand for sophisticated inline monitoring systems is particularly strong in regions with significant investments in new industrial facilities. Regulatory mandates for water purity and material quality also shape regional market dynamics.
South Korea
New advanced semiconductor foundries in South Korea drive substantial demand for continuous resistivity monitoring systems. SEMI standards for ultra-pure water are strictly enforced, necessitating high-precision inline units. Major investments in Gyeonggi Province, particularly in Pyeongtaek and Hwaseong, focus on expanding fabrication capacity.
Taiwan
Taiwan's robust semiconductor manufacturing sector requires constant upgrades and expansion, fueling demand for resistivity meters. Strict adherence to SEMI standards ensures process integrity and high device yields in advanced facilities. The Hsinchu Science Park and Tainan are key centers for ongoing fab construction and modernization projects.
United States
US EPA standards for water quality monitoring create consistent demand for resistivity meters in environmental and industrial applications. Electronics testing for compliance with material purity directives also contributes significantly to market growth. Silicon Valley and the Boston-area biotech cluster are major hubs for both R&D and advanced manufacturing requiring precise measurements.
India
India's Production-Linked Incentive (PLI) schemes are spurring pharmaceutical manufacturing expansion, increasing the need for resistivity meters to meet water-for-injection (WFI) standards. This growth extends to general water quality analysis in chemical processing. Major pharmaceutical production centers in Hyderabad and Gujarat are experiencing heightened demand for these instruments.
Germany
German automotive electronics manufacturers and chemical processing plants require advanced resistivity meters for quality assurance and process control. The EU's RoHS directive mandates rigorous material testing in the electronics sector, driving instrument adoption. Bavaria and North Rhine-Westphalia house significant industrial clusters emphasizing automation and high-precision measurement.
Resistivity Meters Market Key Industry Players
Listed leaders compete with private specialists across product innovation and market reach within the resistivity meters market. The industry exhibits a tiered structure, with established players offering comprehensive portfolios alongside niche providers focusing on specific applications. Strategic archetypes include broad industrial solution providers, high-sensitivity scientific instrument makers, and specialized electronics testing equipment manufacturers. Competitive moves primarily involve portfolio diversification and geographic expansion into high-growth industrial hubs.
Specialists in distinct application areas define competitive dynamics. Mettler Toledo, for instance, represents a broad industrial process analytics provider, leveraging an extensive portfolio. HORIBA exemplifies leadership in high-sensitivity instruments, particularly for scientific and research applications. Hioki occupies a specialized position, focusing on meters tailored for electronics testing and component characterization, addressing niche industry requirements.
| Leading Market Players |
|---|
| Mettler Toledo |
| HORIBA |
| Hioki |
| ACL Staticide |
| Omega |
| IRIS Instrument |
| Fann Instrument Company |
| IET Labs |
| Myron L |
| Others |
Cost & Logistics Intelligence
Typical lead times for high-precision inline resistivity systems, often extending several months, directly reflect the specialized component supply chain and influence project-based pricing models for industrial end-users.
Pricing Analysis
The pricing gap between current-generation automated inline systems and prior-generation benchtop models remains significant. Project-based pricing dominates for complex inline installations, while per-unit transactional pricing applies to portable and handheld devices. Customization level and after-sales service represent key price differentiation drivers. Pricing pressure stems from the availability of lower-cost conductivity meters for general-purpose applications. Small research labs exhibit the highest price sensitivity, whereas semiconductor manufacturers prioritize precision and reliability over cost.
Supply Chain Analysis
Specialized sensor component manufacturing, largely concentrated in East Asia, underpins the resistivity meter supply chain. Geographic supply concentration centers on countries like Taiwan, South Korea, and Japan for high-precision electronics. Raw material dependencies include specialized electrodes and high-purity electronic-grade plastics. Single-source vulnerability for critical sensor technology poses a structural risk. Distribution runs through direct sales channels for complex inline systems and a network of specialized distributors for benchtop and portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, particularly against lower-cost conductivity and TDS meters for general water quality applications that threaten traditional segments.
For Market Incumbents:
Fortify core product lines by investing in multi-parameter platforms, integrating resistivity measurement with pH and TOC sensors. Develop robust software for seamless integration with existing industrial control systems to address legacy system challenges. Expand service offerings to include managed services and leasing models, converting capital expenditures to operational expenditures for clients. This counters the threat of low-end substitution and strengthens customer loyalty through comprehensive solutions.
For New Entrants and Emerging Players:
Achieving rapid SEMI F63 compliance certification presents a crucial fast-track opportunity for new entrants. Target the rapidly expanding battery manufacturing sector and pharmaceutical production in India, driven by PLI schemes, for specialized inline solutions. Focus on a go-to-market strategy centered on offering flexible managed services and data analytics bundles, reducing initial capital outlay for budget-constrained facilities and emphasizing operational efficiency.
For Investors and Strategic Acquirers:
Carve-out targets emerge from larger industrial analytics conglomerates seeking to divest non-core precision measurement assets. The market demonstrates long-term viability, driven by stringent purity standards in semiconductor and pharmaceutical industries. Target specialized sensor technology developers or software integration firms that enhance automation capabilities. The signal to watch is an increase in strategic partnerships between sensor manufacturers and industrial automation providers, indicating market consolidation and technological convergence.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Multi-Parameter Platforms | Integrates resistivity with other critical measurements, offering comprehensive water quality analysis for advanced industrial processes. |
| Geographic Expansion in Asia | Captures demand from new semiconductor fabrication plants in South Korea and Taiwan, aligning with regional growth. |
| Offer Managed Services Models | Addresses high capital cost restraints by converting CAPEX to OPEX, appealing to municipal and pharmaceutical clients. |
| Invest in Advanced Sensor R&D | Enhances measurement precision and stability, crucial for ultra-pure water monitoring in semiconductor manufacturing. |
| Strategic Partnerships for Integration | Facilitates seamless connectivity with legacy SCADA systems, overcoming integration challenges for existing industrial facilities. |
Research Approach
The analysis maps key sub-sectors, including inline, benchtop, portable, and handheld resistivity meters, each validated through extensive primary interviews with industry stakeholders. We engaged with semiconductor process engineers, pharmaceutical quality control managers, environmental agency officials, and R&D lab directors. Secondary validation drew from SEMI standards, US EPA reports, EU RoHS directives, and industry association publications, triangulating data for robust market insights.
Forecast outputs were consistently checked against macro-economic indicators and historical market performance across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end user, and regional economic growth. Compound annual growth rates were derived from a detailed analysis of historical trends and projected future demand. Industry-specific forecast inputs included semiconductor fab expansion plans and pharmaceutical PLI scheme investments.
Decision-makers should treat outputs as directional under current base assumptions; material deviation in regulatory frameworks or technological advancements would warrant model refresh. Forecasts reflect assumptions regarding market dynamics and competitive landscape. Practitioners should keep alternative scenarios live as geopolitical trade tensions and shifts in water quality standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Bend Testing Machine Market
Test and Measurement
Data Center Testing Market
Test and Measurement
Density Tester Market
Test and Measurement
Wireless Network Test Equipment Market
Test and Measurement
Hardware-Assisted Verification Market
Test and Measurement
Air Leak Testing Market
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market
Test and Measurement
Circuit Breaker Test Devices Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
Psophometer Market
Test and Measurement
Drop Weight Testers Market
Test and Measurement
Surface Measurement Equipment and Tools Market