
 Test and Measurement Equipment Market | 2026-2036
Test and Measurement Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Test and Measurement Equipment Market Intelligence
The capability gap between captive semiconductor test divisions and independent instrument vendors is unwinding as foundries internalize probe station development. Keysight Technologies leverages its PNA-X vector network analyzer architecture to dominate 5G mmWave characterization workflows. Rohde & Schwarz anchors European defense and aerospace calibration contracts through its accredited metrology laboratories. Yokogawa Electric Corporation specializes in precision power measurement for electric drivetrain development, competing with broader-portfolio rivals.
Test and measurement equipment comprises electronic instruments that quantify electrical, physical, or RF parameters with specified accuracy, bandwidth, and resolution, serving validation, compliance verification, and production screening across industrial value chains. Oscilloscopes with bandwidths exceeding 100 GHz now enable real-time signal integrity analysis for 112 Gbps PAM4 interconnects. Spectrum analyzers capture the fastest growth as Open RAN deployments force multi-band interference testing. Digital technology platforms generate the deepest margin pools through software-defined measurement routines that reduce hardware refresh cycles.
The FCC's Part 15 rules govern unintentional radiators in the US, while the EU's Radio Equipment Directive mandates CE marking for electromagnetic compatibility across member states. China's GB standards, administered by SAMR, specify metrological traceability for instruments used in state-mandated calibration services. Stakeholders must weigh the capital allocation between generational instrument platforms and subscription-based measurement software that decouples revenue from hardware replacement cycles.
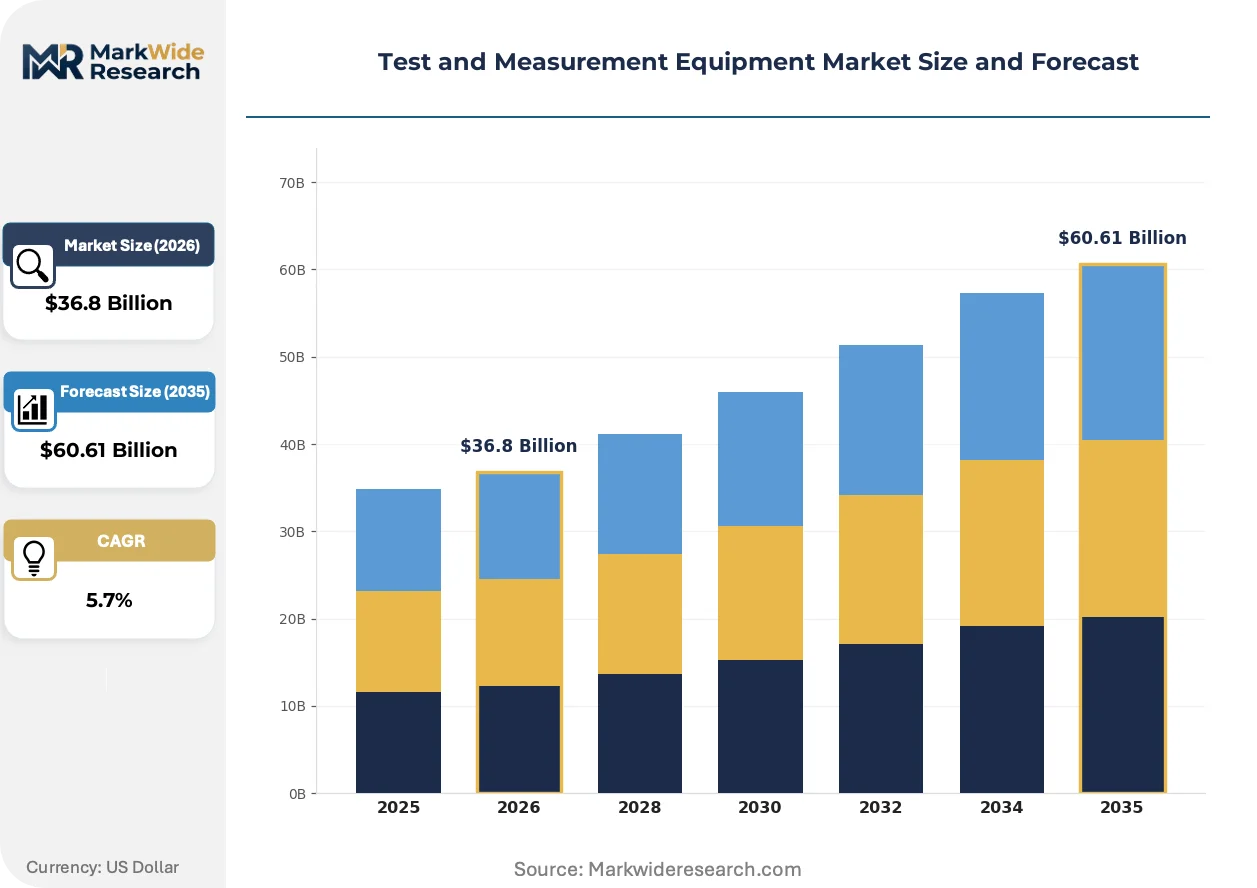
Market Dynamics
The migration from hardware-centric instrumentation toward software-defined measurement architectures is fragmenting traditional vendor lock-ins and compressing replacement cycles across industrial test workflows.
Growth Catalysts
- Advanced node semiconductor validation:Taiwan and South Korea fabs are expanding probe station capacity for 3nm and 2nm process verification, pulling demand for high-bandwidth oscilloscopes and vector network analyzers into foundry captive operations.
- EU Cyber Resilience Act electromagnetic compatibility mandates:Networked industrial equipment must now undergo standardized EMC testing before CE marking, forcing retrofit campaigns across legacy manufacturing infrastructure in member states.
- Electric vehicle battery impedance testing:China's cell manufacturers require precision analyzers for electrode characterization, creating concentrated demand clusters in Fujian and Jiangsu provinces.
Market Restraints
- High-purity sapphire substrate cost volatility:Specialized probe cards and contact substrates depend on synthetic sapphire supply concentrated in limited production facilities, creating input cost instability for precision instrument manufacturers.
- Foundry captive test division expansion:TSMC and Samsung internalization of probe station development erodes addressable market for independent instrument vendors in advanced semiconductor segments.
- Technical bandwidth ceiling in real-time acquisition:112 Gbps PAM4 signal integrity analysis pushes against fundamental limits of analog-to-digital converter sampling rates, constraining oscilloscope evolution without radical architectural shifts.
Strategic Opportunities
- Open RAN multi-band interference testing:Disaggregated radio access network deployments create demand for portable spectrum analyzers capable of simultaneous sub-6 GHz and mmWave characterization, opening white space for modular instrument platforms.
- Subscription-based measurement software:Decoupling revenue from hardware refresh cycles through cloud-native test sequencing allows vendors to penetrate mid-tier industrial users previously priced out of capital-intensive instrument ownership.
- India PLI scheme test infrastructure:Production-linked incentives for electronics manufacturing are driving greenfield fab and assembly investments requiring localized calibration and compliance verification capabilities.
Industry Challenges
- RF/mmWave calibration technician scarcity:5G and 6G test workflows require expertise in vector error correction and TRL calibration methods that outpaces university pipeline output in multiple geographies.
- Legacy GPIB/LXI integration friction:Brownfield manufacturing facilities operate mixed-vendor instrument fleets with incompatible interface generations, complicating unified test automation deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Test and Measurement Equipment Market |
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $60.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oscilloscopes, Multimeters, Signal Analyzers, Spectrum Analyzers Technology: Digital, Analog, Automated, Mixed Signal End User: Telecommunications, Aerospace, Automotive, Education Application: Calibration, Research & Development, Production Testing, Quality Assurance |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Fortive, National Instruments, AMETEK, Tektronix, Teledyne Technologies, Yokogawa Electric Corporation, Anritsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Test and Measurement Equipment Market Strategic Shifts & Innovations
Software-defined measurement architectures are actively displacing fixed-function hardware platforms, enabling remote reconfiguration and algorithmic test optimization without physical instrument replacement.
Modular PXIe and AXIe chassis architectures are decomposing traditional benchtop instrument form factors into swappable digitizer, signal generator, and analysis modules. Automotive drivetrain developers in Germany and Japan are adopting these platforms for rapid test cell reconfiguration between EV inverter and battery validation workflows. This decomposition is compressing capital deployment timelines and enabling shared resource pools across multiple product lines.
The EU's Radio Equipment Directive harmonization with the Cyber Resilience Act is tightening electromagnetic compatibility documentation requirements for industrial IoT devices. Manufacturers must now maintain traceable test records spanning design validation through production screening. Medical device and automotive sensor suppliers in the Netherlands and Italy are investing in accredited metrology partnerships to preempt regulatory rejection at notified body review stages.
Equipment-as-a-service contracting is displacing outright purchase for mid-scale electronics manufacturers. Contract test houses in Vietnam and Mexico are expanding capacity through operational lease arrangements that bundle instruments, calibration services, and software updates into per-test pricing. This model concentrates most visibly among contract manufacturers serving Apple and Tesla supply chains, where volume volatility makes fixed asset ownership structurally unattractive.
Test and Measurement Equipment Market Segmentation
Segmentation in test and measurement equipment reveals how margin pools concentrate in high-bandwidth digital platforms while analog instruments serve cost-sensitive validation workflows. Understanding these divides exposes where vendors can escape hardware refresh commoditization.
Product Type:
Margin pools sit deepest in instruments capturing GHz-class signals where semiconductor foundries and 5G infrastructure builders pay premiums for measurement certainty.
- Oscilloscopes:Real-time acquisition instruments with bandwidths exceeding 100 GHz enable 112 Gbps PAM4 signal integrity analysis for advanced node interconnect validation. Taiwan and South Korea fabs pull demand for these platforms as they expand 3nm and 2nm probe station capacity.
- Spectrum Analyzers:Frequency-domain instruments capture multi-band interference signatures across sub-6 GHz and mmWave ranges. Open RAN deployments in Germany and Japan are forcing simultaneous characterization requirements that favor portable modular architectures.
- Multimeters:Precision voltage and current measurement devices serve calibration laboratories and production screening stations with established accuracy specifications.
- Signal Analyzers:Vector measurement platforms quantify modulation quality and error vector magnitude for wireless communications conformance testing.
Oscilloscopes hold installed capacity. Spectrum analyzers are rotating up the share rankings.
Technology:
Cost tier stratification separates subscription-capable digital platforms from capital-intensive analog hardware that mid-tier manufacturers struggle to justify.
- Digital:Software-defined measurement architectures enable remote reconfiguration and algorithmic test optimization without physical replacement. Cloud-native test sequencing from vendors like Keysight allows per-test pricing models that penetrate mid-tier industrial users.
- Automated:Programmable instrument fleets with LXI and GPIB integration support unified test automation across brownfield manufacturing facilities. Contract test houses in Vietnam and Mexico expand capacity through operational lease arrangements bundling instruments and calibration services.
- Mixed Signal:Hybrid platforms combining analog front-ends with digital processing serve power electronics validation where precision and speed must coexist.
- Analog:Fixed-function hardware platforms persist in educational laboratories and low-throughput production screening where capital constraints block digital migration.
Digital platforms command the steepest expansion trajectory. Analog maintains residual presence in training and entry-tier applications.
End User:
Application intensity varies sharply across sectors, with electric vehicle supply chains and Open RAN infrastructure demanding validation density that education and legacy aerospace cannot match.
- Automotive:Electric drivetrain developers in Germany and Japan require precision power measurement for inverter and battery validation workflows. China's cell manufacturers in Fujian and Jiangsu provinces pull concentrated demand for impedance analyzers.
- Telecommunications:5G mmWave characterization and multi-band interference testing force investment in portable spectrum analyzers. The FCC's Part 15 rules and EU Radio Equipment Directive create compliance verification pipelines that sustain instrument utilization.
- Aerospace:Defense and aerospace calibration contracts anchor European demand through accredited metrology laboratories requiring traceable measurement chains.
- Education:University laboratories and training facilities operate lower-specification instrument fleets with extended replacement cycles and price-sensitive procurement.
Automotive absorbs the fastest volume growth. Telecommunications sustains premium pricing power.
Application:
Customer type stratification separates capital-heavy production screening from research-phase flexibility where rental and subscription models penetrate most effectively.
- Production Testing:High-throughput screening of manufactured units requires hardened instruments with guaranteed uptime and rapid calibration turnaround. Equipment-as-a-service contracting displaces outright purchase among Apple and Tesla supply chain manufacturers facing volume volatility.
- Research & Development:Pre-production validation workflows demand reconfigurable platforms that adapt to evolving specifications. Modular PXIe and AXIe chassis enable rapid test cell reconfiguration between product lines.
- Calibration:Metrology-grade instruments maintain traceability chains for regulatory compliance under EU Cyber Resilience Act EMC mandates and China's GB standards administered by SAMR.
- Quality Assurance:Final verification stations confirm conformance before shipment, integrating with manufacturing execution systems for documentation retention.
Production testing dominates hardware shipment volumes. Research and development is rotating toward software-defined and subscription-based consumption models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Contract manufacturers in Vietnam and Mexico prioritize operational lease arrangements, while semiconductor foundries in Taiwan and South Korea absorb premium pricing for advanced node validation instruments.
United States
Defense and aerospace calibration contracts anchor demand through accredited metrology laboratories requiring traceable measurement chains. The FCC's Part 15 rules govern unintentional radiators, mandating electromagnetic compatibility verification for networked industrial equipment. Greater Boston hosts precision instrument development clusters serving 5G mmWave characterization workflows.
Germany
Automotive drivetrain developers require precision power measurement for inverter and battery validation workflows. The EU's Cyber Resilience Act harmonizes with the Radio Equipment Directive, tightening EMC documentation requirements for industrial IoT devices. Bavaria concentrates metrology partnerships serving medical device and automotive sensor suppliers.
China
Battery cell manufacturers in Fujian and Jiangsu provinces pull concentrated demand for precision impedance analyzers. SAMR-administered GB standards specify metrological traceability for instruments used in state-mandated calibration services. The Yangtze River Delta hosts expanding probe station capacity for advanced node semiconductor validation.
South Korea
Foundry captive test divisions are internalizing probe station development for 3nm and 2nm process verification. The national semiconductor strategy supports domestic instrument ecosystem development. Seoul Capital Area fabs are expanding high-bandwidth oscilloscope and vector network analyzer deployment.
Japan
Automotive manufacturers adopt modular PXIe and AXIe chassis for rapid test cell reconfiguration between EV product lines. METI industrial standardization programs influence measurement protocol adoption. Nagoya and Osaka industrial corridors concentrate precision power measurement demand for electric drivetrain development.
Test and Measurement Equipment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with consolidated players dominating 5G mmWave and advanced semiconductor validation while mid-scale vendors compete on modular portability and subscription pricing. The competitive landscape fragments between hardware-centric incumbents with deep calibration service networks and software-defined challengers decoupling revenue from instrument refresh cycles. Two dominant competitive moves are reshaping positioning: foundry captive division expansion eroding addressable market for independent vendors, and equipment-as-a-service contracting displacing outright purchase among volume-volatile manufacturers.
Within the integrated instrumentation tier, Keysight Technologies and Rohde & Schwarz exemplify full-stack measurement platform providers with accredited metrology laboratory networks. Yokogawa Electric Corporation occupies a position among precision power measurement specialists competing against broader-portfolio rivals in electric vehicle supply chain applications.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Fortive |
| National Instruments |
| AMETEK |
| Tektronix |
| Teledyne Technologies |
| Yokogawa Electric Corporation |
| Anritsu |
| Others |
Cost & Logistics Intelligence
Long-term calibration service contracts lock in both probe station access and price visibility for semiconductor fabs in Taiwan and South Korea, insulating instrument vendors from spot-market volatility while binding buyers to multi-year maintenance commitments under China's GB standards and the EU's Cyber Resilience Act mandates.
Pricing Analysis
After-sales calibration and software subscription tiers drive lifetime value for instrument vendors, with three-tier pricing structure across premium, standard, and economy levels separating metrology-grade certification from production-screening units. Price differentiation rests on bandwidth specification and EMC compliance tier, with CE-marked instruments commanding premiums over uncertified alternatives. Cost compression in economy-tier oscilloscopes is intensifying because contract manufacturers in Vietnam and Mexico prioritize per-test operational leases over capital ownership. Education and training facilities exhibit highest price sensitivity, while foundry captive divisions absorb premium positioning.
Supply Chain Analysis
Strategic stockpiling of high-purity synthetic sapphire substrates dominates inventory strategy among precision probe card manufacturers, buffering against supply interruptions from limited production facilities. Component sourcing concentrates in Japan, Germany, and the United States for ADC digitizers, RF front-ends, and precision mechanical assemblies. Single-source vulnerability in synthetic sapphire feedstock creates input cost instability for contact substrate fabrication. Distribution runs through direct OEM relationships for advanced semiconductor validation instruments and regional distributor networks for mid-tier industrial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Test and Measurement Equipment Market constitutes a high-growth disruption as software-defined architectures displace fixed-function hardware, with the EU's Cyber Resilience Act mandating standardized EMC testing that forces retrofit investment across legacy industrial infrastructure.
For Market Incumbents: Fortify accredited metrology laboratory networks against foundry captive division expansion by embedding calibration services into long-term service contracts. Deepen backward integration into probe station development to retain advanced semiconductor validation share against TSMC and Samsung internalization. Prioritize cloud-native test sequencing platforms that decouple recurring revenue from hardware refresh cycles. For New Entrants and Emerging Players: Differentiate on modular PXIe/AXIe portability for Open RAN multi-band interference testing, where disaggregated radio access network deployments create white space absent incumbent lock-in. Target India's PLI scheme test infrastructure as the most penetrable geography, leveraging production-linked incentive-driven fab investments requiring localized calibration capabilities. Pursue equipment-as-a-service contracting with Apple and Tesla supply chain manufacturers facing volume volatility. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined measurement specialists with cloud-native architectures and recurring revenue models that escape hardware commoditization cycles. Long-term viability over the projection horizon favors vendors bridging semiconductor validation and automotive power electronics applications. Watch for inflection when foundry captive divisions externalize non-core probe station development.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Test Sequencing Platform | Enables per-test pricing models that penetrate mid-tier industrial users previously priced out of instrument ownership. |
| Accredited Metrology Partnership Expansion | Preempts EU Cyber Resilience Act regulatory rejection for medical device and automotive sensor suppliers in the Netherlands and Italy. |
| Modular PXIe/AXIe Chassis Development | Supports rapid test cell reconfiguration between EV inverter and battery validation workflows for German and Japanese automotive developers. |
| Synthetic Sapphire Supply Security Program | Mitigates input cost instability for precision probe cards dependent on limited high-purity substrate production facilities. |
| India Calibration Infrastructure Localization | Captures PLI scheme-driven demand from greenfield fab and assembly investments requiring compliance verification capabilities. |
Research Approach
The analysis maps oscilloscope, spectrum analyzer, multimeter, and signal analyzer sub-sectors, each validated through primary interviews with semiconductor test engineers, automotive validation directors, metrology laboratory managers, and contract manufacturing procurement leads, combined with secondary triangulation against SEC filings, SAMR GB standard publications, EU Cyber Resilience Act implementation guidance, and customs trade data for instrument imports, with bottom-up segment sizing cross-checked against top-down market aggregation.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures for 5G infrastructure buildout, foundry equipment spending reports from Taiwan and South Korea, and automotive R&D expenditure patterns from German and Japanese OEMs, with CAGRs derived from instrument shipment trajectories across bandwidth tiers, technology platforms, and end-user applications modeled over the projection horizon.
Forecasts assume regulatory continuity in EU CE marking regimes, FCC Part 15 enforcement, and China's SAMR-administered metrological traceability requirements; material policy shifts in electromagnetic compatibility mandates or semiconductor export controls would require re-modeling. Revision becomes warranted when foundry captive test division internalization crosses thresholds that structurally compress independent vendor addressable market.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Radio Frequency Test Equipment Market
Test and Measurement
Quantum Key Distribution System Performance and Security Test Equipment Market
Test and Measurement
Telecom Testing Equipment Market
Test and Measurement
One-Box Testers Market
Test and Measurement
High Voltage Testing Market
Test and Measurement
Test Rig Market
Test and Measurement
Tribometer Market
Test and Measurement
Ethernet Test Equipment Market
Test and Measurement
Torsion Tester Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
Melt Flow Tester Market
Test and Measurement
Permeation Testing Machines Market
Test and Measurement
Battery Testing Market