
 Bend Testing Machine Market | 2026-2036
Bend Testing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Bend Testing Machine Market Analysis
Multi-source procurement is pivoting toward captive testing infrastructure as tier-one suppliers seek direct control over materials certification cycles. Instron leverages its installed base of universal testing platforms to cross-sell dedicated bend systems into automotive OEM labs. ZwickRoell sustains dominance in European aerospace compliance through its alignment with EASA material qualification frameworks. MTS Systems Corporation anchors its position in high-capacity hydraulic segments serving North American defense contractors.
A bend testing machine applies controlled force to a specimen supported at two points, measuring flexural strength, yield point, and fracture behavior under three-point or four-point loading configurations with load capacities ranging from fractional newtons to meganewtons. These systems serve as gatekeeping equipment for construction rebar, automotive chassis components, and medical implant materials before production release. Electronic machines now lead the product type hierarchy where precision and data traceability outweigh raw force requirements, while hydraulic systems retain their grip on high-capacity custom configurations for heavy-gauge steel and composite beam validation. Digital technology segments are capturing the fastest expansion as laboratories replace analog dial indicators with automated deflection measurement and cloud-connected compliance reporting.
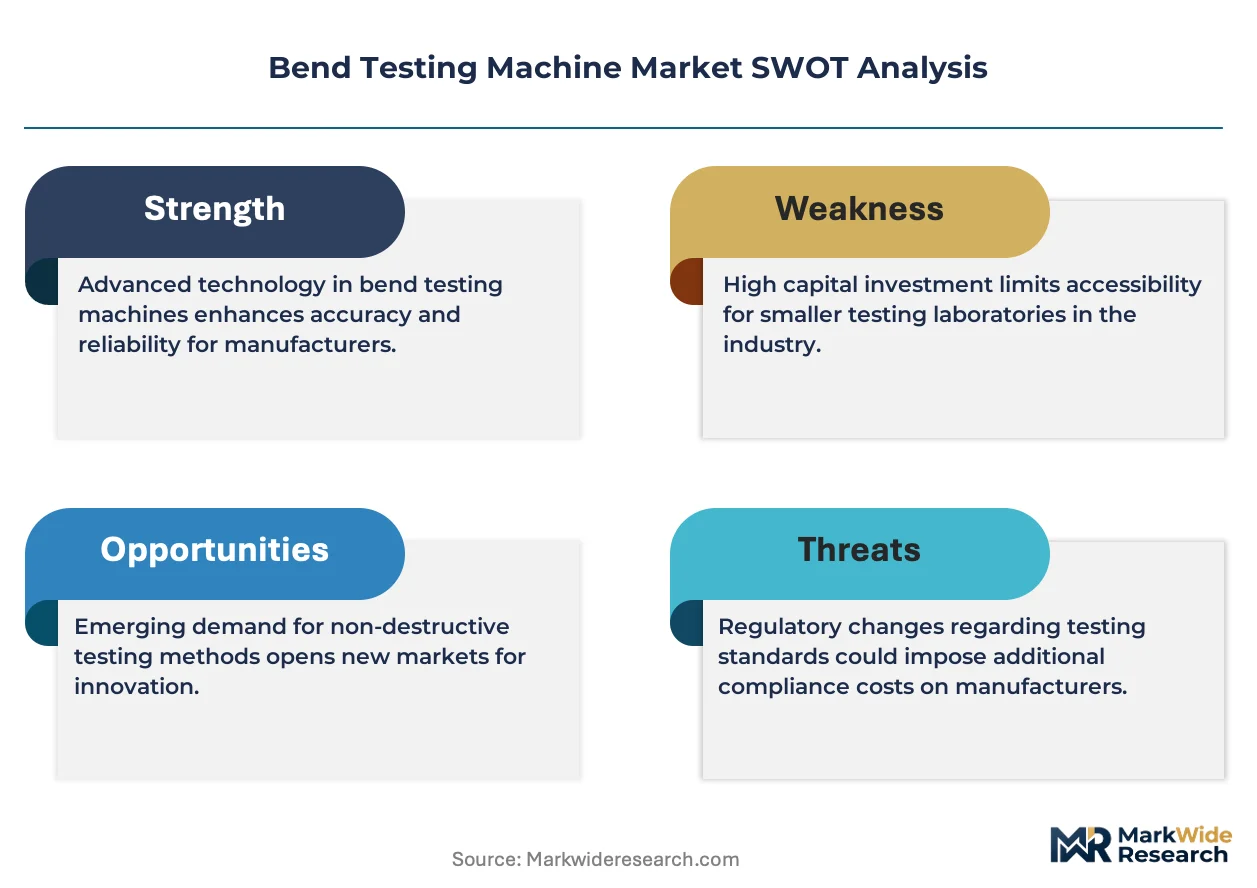
ASTM International governs bend test methodologies in the United States through E290 and A370 standards, while ISO 7438 and ISO 8491 shape European and Asian qualification protocols for metallic materials. China's SAMR enforces GB/T 232 national standards that increasingly reference ISO harmonization, creating dual-compliance obligations for multinational equipment vendors. Stakeholders must monitor how regional certification divergence affects equipment configuration costs and service attach rates.
Market Dynamics
Aerospace manufacturers in Germany and the United States are consolidating materials validation programs under captive laboratory infrastructure, compressing procurement cycles and displacing third-party testing services with direct ownership of bend testing assets.
Growth Catalysts
- ISO 7438 Harmonization:European aerospace qualification frameworks are tightening structural metal validation protocols, mandating expanded bend testing capacity across tier-one supplier networks.
- China's Eastern Industrial Corridor:Domestic equipment suppliers in Jiangsu and Zhejiang provinces are capturing replacement demand from multinational vendors through localized service networks.
- ASTM E290 Alignment:North American defense contractors are retrofitting legacy universal testing platforms with dedicated bend fixtures to meet refreshed A370 rebar certification requirements.
Market Restraints
- High-Capacity Hydraulic Component Concentration:Precision servo valves and load cell assemblies for meganewton-class systems concentrate among German and Japanese specialty suppliers, creating input bottlenecks.
- Calibration Infrastructure Scarcity:ISO/IEC 17025-accredited calibration laboratories for bend testing machines remain sparse in Brazil, Mexico, and Southeast Asian manufacturing zones.
- Digital-Analog Transition Friction:Laboratories with substantial investments in dial-indicator-based deflection measurement resist full automation retrofits due to capital recovery timelines.
Strategic Opportunities
- Saudi Arabia's Giga-Project Pipeline:NEOM and Red Sea tourism developments are triggering steel rebar qualification demand that outpaces domestic testing infrastructure capacity.
- Medical Implant Convergence:Orthopedic manufacturers are integrating bend testing into additive manufacturing quality loops for titanium lattice structures, creating equipment specification gaps.
- Cloud-Connected Compliance Reporting:Equipment vendors can capture recurring revenue through automated ASTM E290 and ISO 7438 documentation workflows replacing manual certificate generation.
Industry Challenges
- Metrology Technician Shortage:Laboratories struggle to recruit personnel proficient in both mechanical testing mechanics and digital data integrity protocols under FDA 21 CFR Part 11.
- Legacy System Integration Complexity:Automated bend testing cells must interface with 1990s-era laboratory information management systems prevalent in North American automotive proving grounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bend Testing Machine Market |
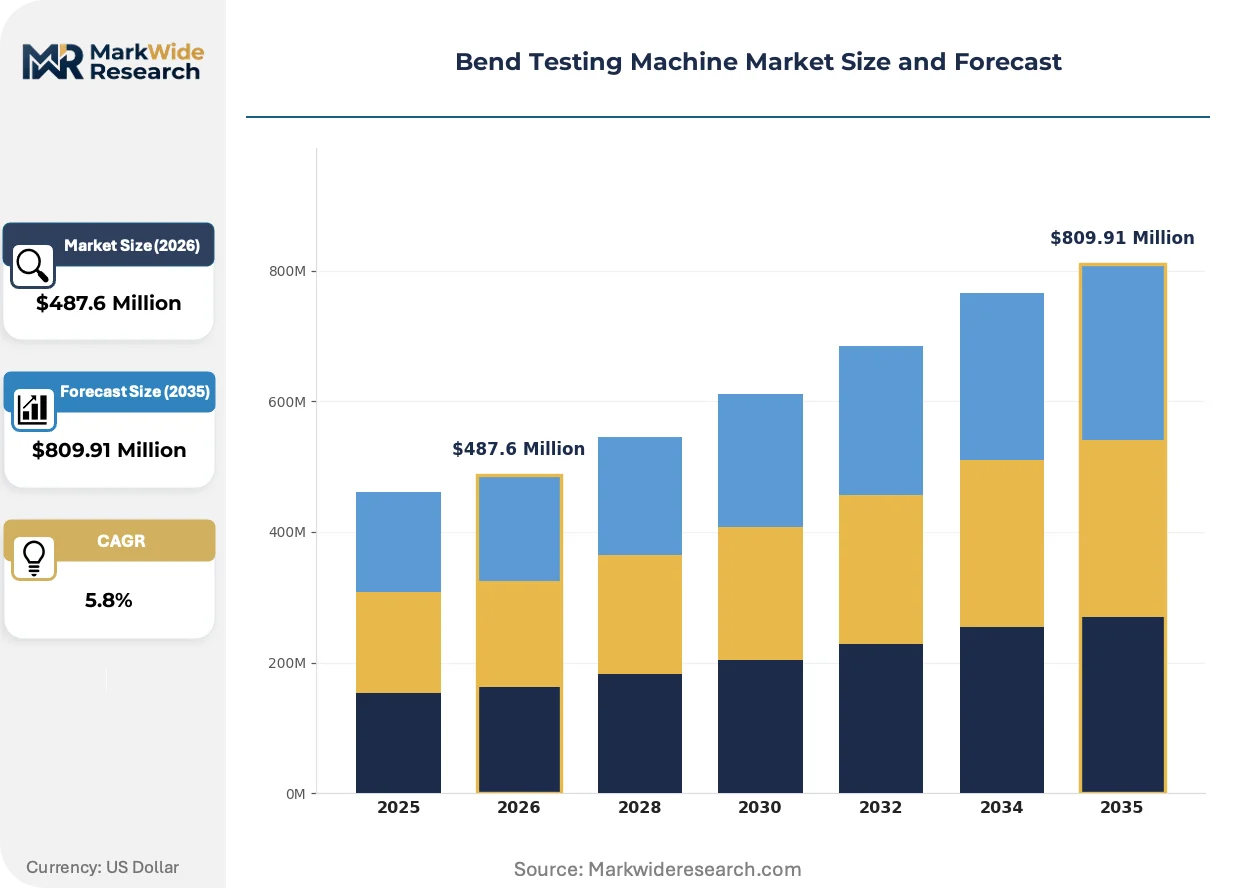
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electronic, Manual, Universal End User: Manufacturing, Research Labs, Educational Institutions, Quality Control Technology: Digital, Analog, Computerized, Hybrid Capacity: Low, Medium, High, Custom |
| Companies Covered | ADMET, Instron, ZwickRoell, Qualitest, TestResources, UTECH ROLLS Equipment, MTS Systems Corporation, Shimadzu Corporation, Tinius Olsen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bend Testing Machine Market Emerging Trajectories
Digital measurement architectures are compressing test cycle times while cloud connectivity restructures how compliance documentation flows between laboratories and certifying authorities.
Electronic bend testing platforms are electrifying materials validation workflows through integrated load-deflection data acquisition that eliminates manual dial indicator reading. Automotive OEM laboratories in Stuttgart and Detroit are replacing hydraulic universal testers with electromechanical bend systems for chassis component validation. This electrification is compressing test throughput from hours to minutes while embedding automatic modulus calculation that previously required offline spreadsheet processing.
REACH substance restrictions on hydraulic fluids are forcing equipment manufacturers to redesign high-capacity systems around biodegradable synthetic alternatives or all-electric actuation. European aerospace suppliers face dual compliance pressure from EASA material qualification frameworks and EU Green Deal embodied carbon reporting requirements. The regulatory stack is accelerating demand for energy-recuperating drive systems in bend testing equipment across French and German manufacturing clusters.
Multi-source procurement contracts are fragmenting as tier-one suppliers establish captive testing infrastructure to compress materials certification cycles. Third-party testing houses in China's Yangtze River Delta are losing volume to in-house laboratories at domestic EV battery manufacturers and wind turbine producers. This behavioral shift is most visible in Ningbo and Suzhou, where equipment vendors report shortened sales cycles for single-unit purchases replacing historical multi-year service agreements.
Bend Testing Machine Market Segmentation
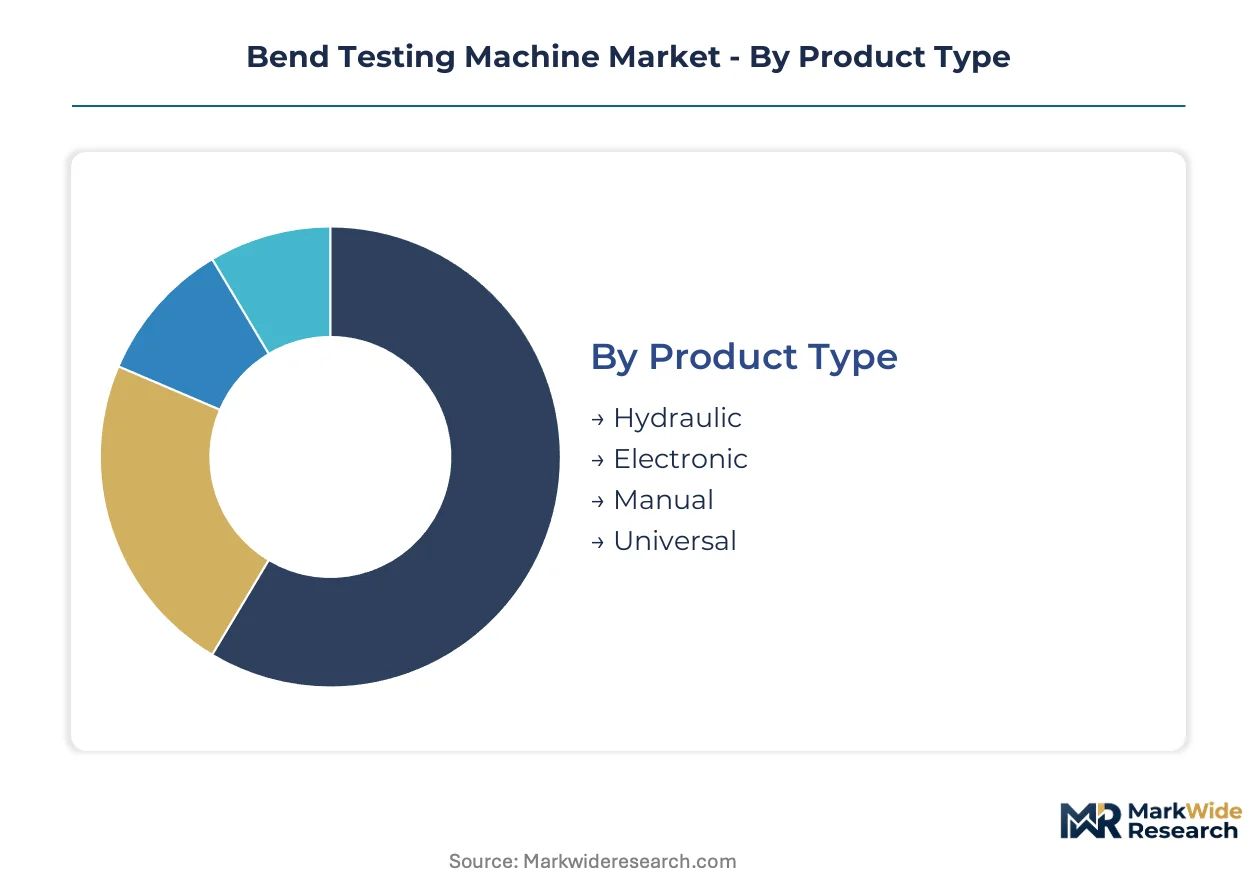
Bend testing machine procurement varies sharply by operational scale and compliance burden. Capital allocation decisions cluster around force capacity requirements and data integrity mandates rather than generic equipment specifications.
Product Type:
Capital intensity escalates with force capacity and control precision, separating commodity manual systems from precision electronic platforms and heavy-duty hydraulic installations.
- Electronic:Servo-electric actuation delivers closed-loop load control with deflection resolution below one micrometer. Stuttgart automotive OEMs and Detroit chassis suppliers are replacing legacy hydraulic units to compress test cycle times and embed automatic modulus calculation.
- Hydraulic:Megaton-class force generation through precision servo valves serves heavy-gauge steel and composite beam validation. German and Japanese specialty suppliers concentrate critical valve and load cell assemblies, creating procurement bottlenecks for North American defense contractors.
- Manual:Dial-indicator-based systems serve educational demonstrations and low-volume rebar spot checks.
- Universal:Modular platforms accept bend fixtures alongside tensile and compression attachments for laboratories with constrained floor space.
Most installed capacity flows through Electronic systems. Expansion is steepest in Hydraulic configurations for aerospace composite validation.
End User:
Application urgency and compliance exposure shape procurement patterns across operational environments with divergent certification obligations.
- Manufacturing:Captive testing infrastructure at tier-one suppliers compresses materials certification cycles and displaces third-party services. Ningbo and Suzhou EV battery producers and wind turbine manufacturers are consolidating validation under direct laboratory ownership.
- Quality Control:Gatekeeping functions for construction rebar, automotive chassis, and medical implant release demand ISO/IEC 17025 traceability and FDA 21 CFR Part 11 data integrity protocols.
- Research Labs:Method development for novel alloys and additive manufacturing lattices requires programmable loading profiles and multi-channel data acquisition.
- Educational Institutions:Training demonstrations prioritize mechanical simplicity and operator safety over throughput or precision.
Procurement volume concentrates in Manufacturing. Climbing the fastest are Quality Control installations at orthopedic additive manufacturing facilities.
Technology:
Digital architecture penetration correlates with laboratory automation maturity and cloud compliance reporting requirements.
- Digital:Automated deflection measurement and cloud-connected ASTM E290 and ISO 7438 documentation workflows replace manual certificate generation. European aerospace suppliers face dual pressure from EASA material qualification and EU Green Deal embodied carbon reporting, accelerating energy-recuperating drive adoption.
- Computerized:PC-based control with programmable test sequences bridges legacy analog installations and full digital automation.
- Analog:Dial-indicator-based deflection measurement persists where capital recovery timelines delay full automation retrofits.
- Hybrid:Mixed-signal architectures preserve analog load cells while digitizing data acquisition for transitional laboratories.
Deployment share tilts toward Digital systems. Gaining share fastest are Computerized platforms in mid-capacity automotive proving grounds.
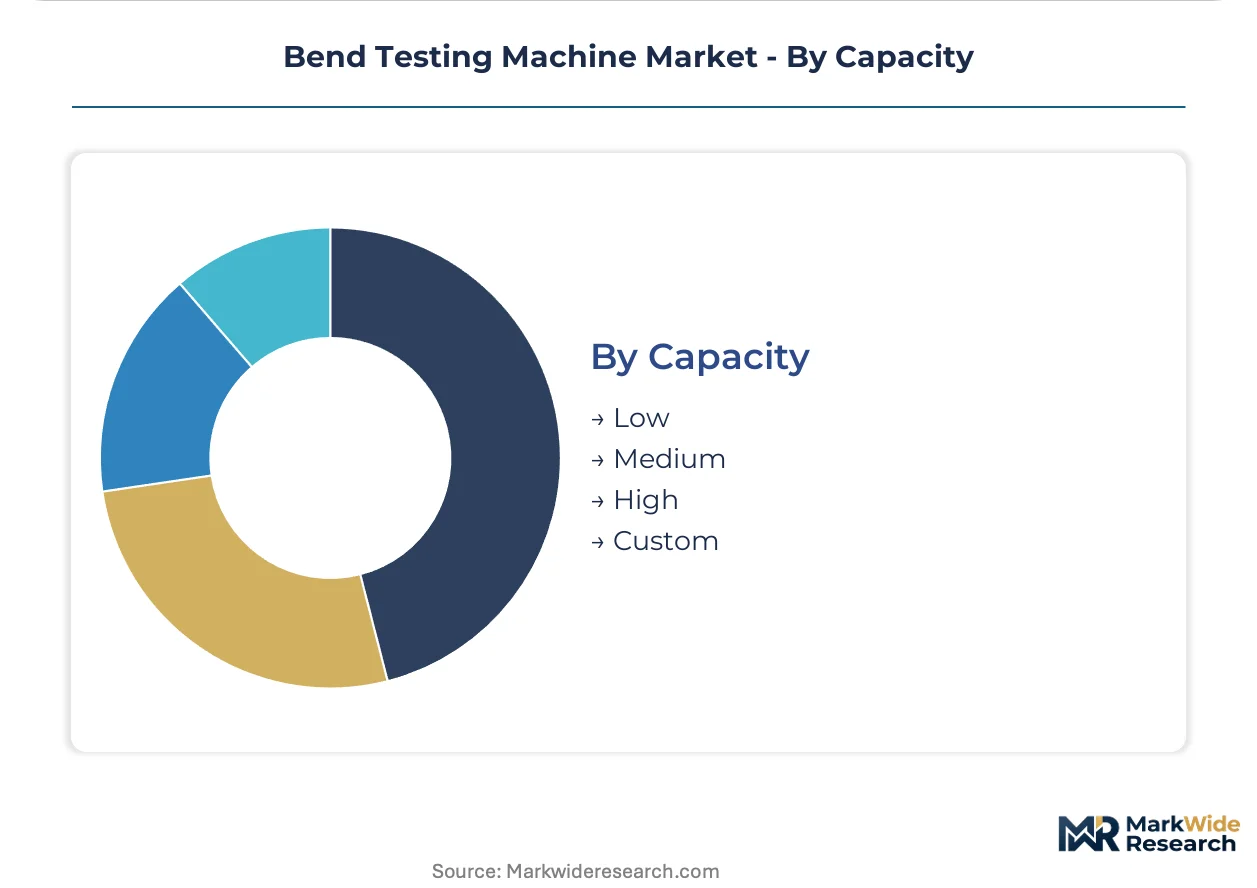
Capacity:
Force range selection locks laboratories into specific specimen geometries and material classes with limited retrofit flexibility.
- High:Megaton-class systems validate structural steel beams, bridge components, and wind turbine root sections. REACH substance restrictions on hydraulic fluids are forcing redesign around biodegradable synthetics or all-electric actuation.
- Custom:Non-standard span lengths and fixture configurations serve aerospace composite panels and medical implant lattices with geometries outside standardized test protocols.
- Medium:General-purpose chassis components and construction rebar dominate procurement for commercial laboratories serving multiple industries.
- Low:Fractional-newton systems test thin-film electronics, medical stents, and microelectromechanical structures.
Equipment value concentrates in High capacity installations. Steepest expansion trajectory appears in Custom configurations for orthopedic additive manufacturing quality loops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping equipment procurement as manufacturers migrate validation capacity toward jurisdictions with harmonized standards and localized service networks. Cost-of-compliance gaps between imported and domestic systems are accelerating captive laboratory investments in select industrial corridors.
United States
Defense contractors in Ohio and Texas are retrofitting legacy universal platforms with dedicated bend fixtures to meet refreshed ASTM A370 rebar certification requirements. FAA and NHTSA material qualification protocols are tightening structural validation obligations for aerospace and automotive suppliers. The Detroit-Windsor automotive corridor is consolidating chassis component testing under direct OEM laboratory ownership.
Germany
EASA material qualification frameworks are mandating expanded bend testing capacity across tier-one aerospace supplier networks. REACH substance restrictions on hydraulic fluids are forcing equipment redesign around biodegradable synthetics or all-electric actuation. The Stuttgart automotive cluster is replacing hydraulic universal testers with electromechanical bend systems for precision chassis validation.
China
SAMR enforcement of GB/T 232 national standards is creating dual-compliance obligations for multinational equipment vendors serving domestic manufacturers. Domestic suppliers in Jiangsu and Zhejiang provinces are capturing replacement demand through localized service networks. The Ningbo-Suzhou EV battery and wind turbine manufacturing belt is consolidating materials validation under captive laboratory infrastructure.
Saudi Arabia
NEOM and Red Sea tourism giga-projects are triggering steel rebar qualification demand that outpaces domestic testing infrastructure capacity. The country's national construction regulator is tightening structural material certification protocols for mega-development frameworks. The Eastern Province industrial zone is attracting equipment vendors to establish service presence for petrochemical and infrastructure validation needs.
Japan
METI industrial standards alignment with ISO harmonization is compressing procurement cycles for precision electronic bend systems. JIS certification requirements for automotive and electronics materials are driving laboratory automation investments. The Nagoya automotive manufacturing cluster is integrating cloud-connected compliance reporting into materials validation workflows.
Bend Testing Machine Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital automation and regional service density as differentiation vectors. The vendor base stratifies across three tiers: precision electronic system specialists, high-capacity hydraulic fabricators, and modular universal platform providers. Two dominant competitive moves are reshaping positioning: backward integration into load cell and servo valve manufacturing to secure input supply, and geographic expansion through localized calibration and service networks in underserved manufacturing zones.
Among precision electronic system specialists, Instron and ZwickRoell occupy positions exemplifying the premium-tier archetype focused on closed-loop control and automated compliance documentation. MTS Systems Corporation represents the high-capacity hydraulic segment serving defense and infrastructure validation requirements. These three anchors illustrate how competitive positioning diverges between precision-electronic and force-generation specializations.
| Leading Market Players |
|---|
| ADMET |
| Instron |
| ZwickRoell |
| Qualitest |
| TestResources |
| UTECH ROLLS Equipment |
| MTS Systems Corporation |
| Shimadzu Corporation |
| Tinius Olsen |
| Others |
Supply Flow & Price Mechanics
Tier-one aerospace OEMs in Germany and the United States dominate procurement volume and command project-based pricing with embedded calibration service bundles. Their consolidation of captive testing infrastructure compresses sales cycles and shifts negotiation leverage toward total-cost-of-ownership frameworks rather than equipment list prices.
Pricing Analysis
Distributor margins of 15-25% separate factory-direct transactions from regional equipment resellers serving mid-cap commercial laboratories. Three-tier pricing structure across precision electronic, standard hydraulic, and economy manual systems reflects ISO/IEC 17025 certification grade and force capacity range. Pricing pressure stems from domestic Chinese suppliers undercutting multinational vendors on equivalent GB/T 232 compliance packages. Small educational institutions exhibit highest price sensitivity, while defense contractors prioritize traceability over unit cost.
Supply Chain Analysis
China's domestic-content requirements under SAMR enforcement are redirecting component sourcing for multinational vendors establishing local assembly operations. Precision servo valves and meganewton-class load cells concentrate in Germany and Japan, creating single-source vulnerability for North American hydraulic system fabricators. Raw material dependencies span specialty steel alloys, high-purity aluminum castings, and ceramic-coated actuator components. Distribution runs through authorized service networks with ISO/IEC 17025-accredited calibration attach rates determining lifetime value capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where cost-of-compliance gaps between EASA-aligned European aerospace suppliers and SAMR-regulated Chinese domestic manufacturers create divergent equipment specification premiums.
For Market Incumbents: Cement dominance in precision electronic segments through backward integration into load cell manufacturing, eliminating German and Japanese component bottlenecks. Expand calibration service density in China's Jiangsu and Zhejiang provinces before domestic suppliers close the service gap. Prioritize EASA qualification framework alignment to defend margin position against emerging cloud-compliance reporting entrants. For New Entrants and Emerging Players: Mid-cap orthopedic additive manufacturers in Stuttgart and Detroit represent the most penetrable buyer archetype, as their titanium lattice validation requirements outstrip incumbent specification catalogs. Target Saudi Arabia's Eastern Province industrial zone where NEOM-related rebar testing demand exceeds established service infrastructure. Lead with automated ASTM E290 documentation workflows as the primary go-to-market wedge against legacy dial-indicator installations. For Investors and Strategic Acquirers: Precision metrology specialists with captive servo valve production are the most active acquirer in this space, consolidating input supply security. Long-term viability hinges on digital compliance reporting attach rates replacing transactional equipment sales. Monitor cloud-connected calibration certificate generation penetration as the inflection signal for recurring revenue model transition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Load Cell Manufacturing | Eliminates German and Japanese component concentration for hydraulic system builders serving defense contractors. |
| Cloud-Connected Compliance Reporting Launch | Captures recurring revenue from EASA and ASTM E290 documentation automation replacing manual certificate workflows. |
| Localized Service Network Expansion | Establishes ISO/IEC 17025 calibration density in China's Ningbo-Suzhou corridor ahead of domestic supplier consolidation. |
| Energy-Recuperating Drive System Development | Aligns with EU Green Deal embodied carbon reporting requirements tightening across French and German aerospace clusters. |
| Additive Manufacturing Quality Loop Integration | Addresses specification gaps for titanium lattice bend validation emerging in Stuttgart and Detroit orthopedic facilities. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors at tier-one automotive OEMs, aerospace materials qualification leads, commercial laboratory procurement managers, and aftermarket service heads were cross-validated against secondary sources including customs trade data, SEC 10-K filings of listed equipment vendors, SAMR GB/T 232 regulatory notices, and EASA material qualification framework updates.
Historical trendline analysis of electronic versus hydraulic system procurement patterns informed segmentation-level growth trajectory calibration across the projection horizon. Modeled dimensions span product type, capacity tier, technology architecture, and end-use vertical with particular attention to captive laboratory infrastructure buildout rates. CAGRs were derived from equipment replacement cycle compression observed in China's eastern industrial corridor and North American defense contractor retrofit activity.
Underlying measurement precision varies by segment; digital technology and high-capacity hydraulic installations carry tighter precision than manual and analog legacy categories. Forecasts embed assumptions regarding ISO 7438 harmonization timelines and REACH substance restriction enforcement trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Whiteness Meter Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Leak Testing Machine Market
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Non Destructive Testers (NDT) Equipment Market
Test and Measurement
Electrical Conductivity Meters Market
Test and Measurement
AI-Enabled Testing Tools Market