
 Global Conductivity Meters Market | 2026-2036
Global Conductivity Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Conductivity Meters Market Analysis
Sensor calibration and cloud-connected diagnostics is rebalancing how vendors monetize conductivity instrumentation. Thermo Fisher Scientific leverages its service infrastructure to lock in long-term laboratory contracts. Endress+Hauser anchors its position through dense coverage of process automation channels. Hach Company specializes in water quality applications where regulatory compliance drives replacement cycles.
Conductivity meters measure the ability of a solution to conduct electrical current, typically expressed in microsiemens or millisiemens per centimeter, using alternating current at specific frequencies to minimize polarization effects. Portable meters command the largest installed base due to field deployment flexibility, while inline meters capture the fastest expansion as continuous process monitoring replaces manual sampling. Digital and smart technologies are displacing analog architectures across municipal water and chemical processing installations.
EPA discharge monitoring in the United States, REACH chemical safety protocols in Europe, and GB water quality standards in China collectively tighten performance requirements for measurement accuracy and data logging. FDA process analytical technology guidelines for pharmaceutical manufacturing extend demand for validated conductivity systems. Stakeholders must weigh sensor interoperability against proprietary cloud ecosystems when specifying next-generation instrumentation platforms.
Market Dynamics
The conductivity meters sector is undergoing a platform shift as analog sensor architectures give way to digital and smart systems with cloud-native diagnostics, fundamentally altering how vendors capture lifetime value from instrumentation fleets.
Growth Catalysts
- EPA discharge monitoring mandates:United States water treatment utilities face tightening effluent standards that demand higher measurement accuracy and automated data logging, accelerating replacement of legacy handheld units.
- Inline process monitoring adoption:Chemical processing plants are abandoning manual sampling protocols in favor of continuous real-time conductivity measurement to reduce batch variability and labor costs.
- Pharmaceutical process analytical technology:FDA guidelines for validated manufacturing systems extend demand for high-precision conductivity instrumentation with full audit trails and calibration documentation.
Market Restraints
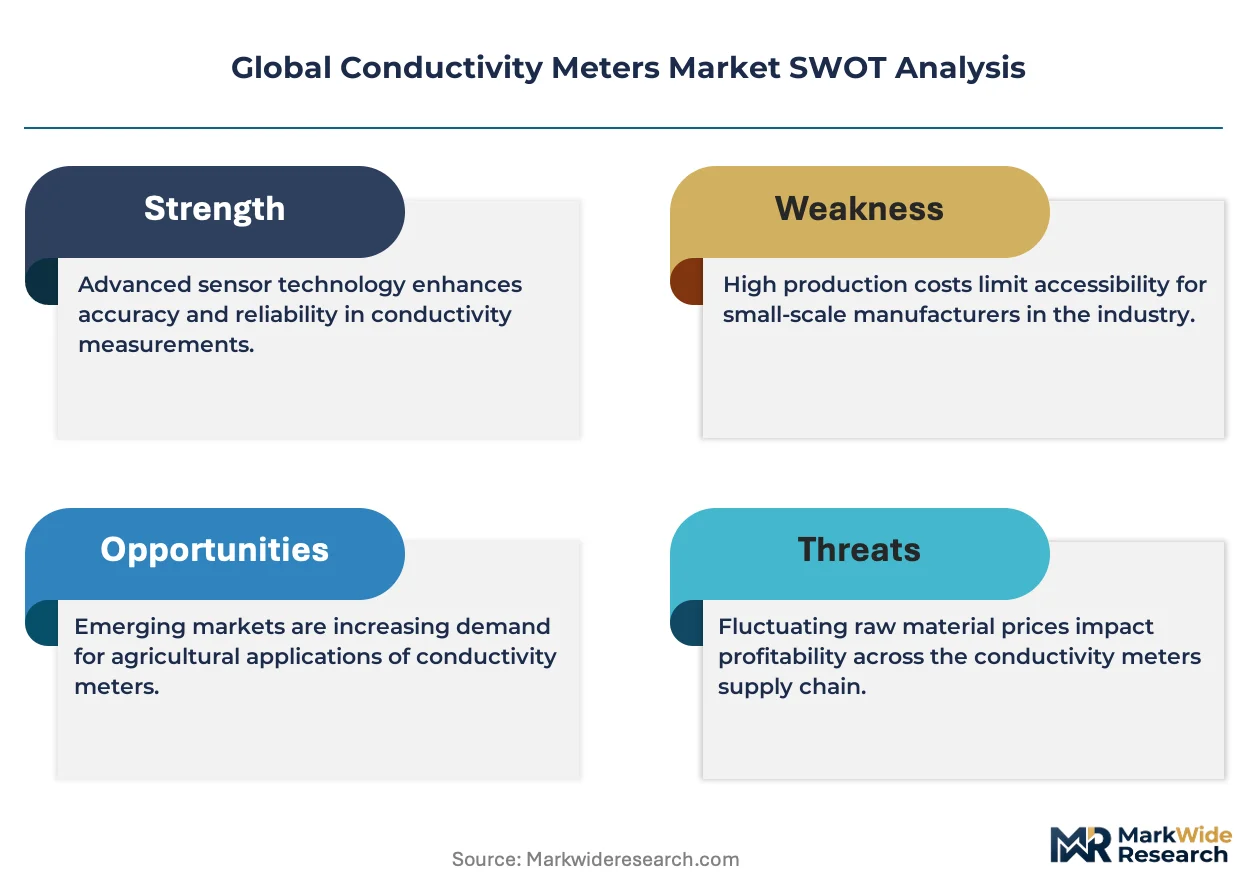
- Platinum electrode cost volatility:Sensor manufacturing depends on platinum-group metal coatings whose price swings compress margin stability for mid-tier instrument producers.
- Proprietary cloud ecosystem lock-in:Leading vendors bundle diagnostics platforms with hardware, creating switching costs that deter price-sensitive municipal buyers from multi-vendor procurement.
- Optical dissolved oxygen substitution:Emerging optical sensing technologies for water quality monitoring threaten to displace conductivity-based methods in select environmental monitoring applications.
Strategic Opportunities
- India municipal water infrastructure:Central government Jal Jeevan Mission funding creates procurement windows for smart conductivity monitoring in rural and semi-urban distribution networks.
- Electrochemical sensor fusion:Convergence of conductivity, pH, and temperature measurement into single probe architectures opens premium positioning in pharmaceutical and food processing verticals.
- EU Green Deal industrial water reuse targets:Member state incentives for closed-loop manufacturing systems expand addressable market for inline conductivity instrumentation in process water recycling.
Industry Challenges
- Metrology technician scarcity:Field calibration and sensor maintenance require specialized electrochemical expertise that utilities and industrial operators struggle to recruit and retain.
- Legacy system integration complexity:Brownfield installations with analog 4-20mA control loops demand costly signal conditioning hardware to interface with digital smart sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Conductivity Meters Market |
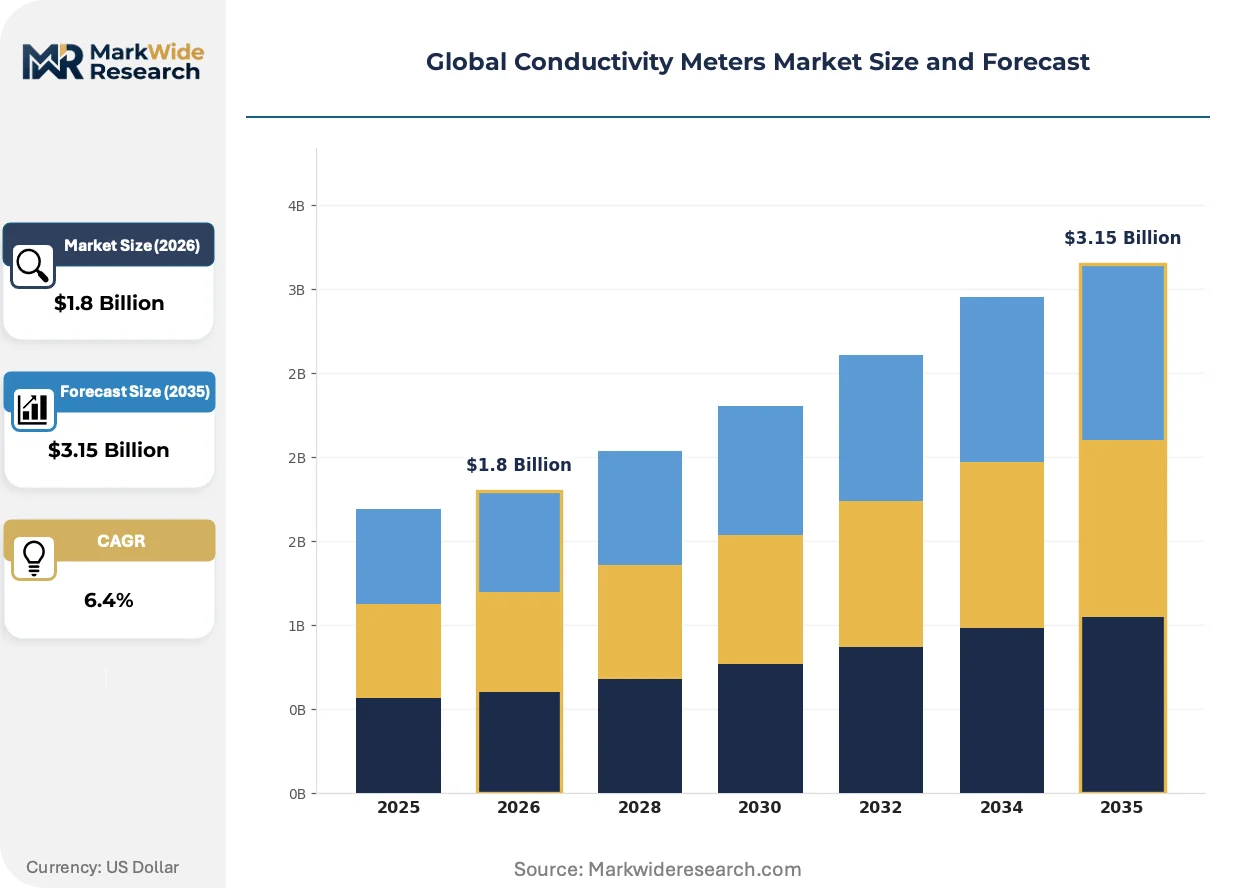
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Benchtop Meters, Inline Meters, Waterproof Meters Technology: Analog, Digital, Smart, Advanced Sensor End User: Water Treatment, Agriculture, Food & Beverage, Chemical Processing Application: Environmental Monitoring, Laboratory Research, Industrial Use, Aquaculture |
| Companies Covered | Thermo Fisher Scientific Inc., Mettler-Toledo International Inc., Endress+Hauser Group, Yokogawa Electric Corporation, Hach Company, Emerson Electric Co., ABB Ltd., Metrohm, HORIBA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Conductivity Meters Market Emerging Trajectories
Digital sensor architectures with embedded microprocessors and wireless connectivity are compressing the traditional service model for conductivity instrumentation, shifting vendor economics toward recurring software and calibration revenue streams.
Smart conductivity probes with integrated temperature compensation and self-diagnostic algorithms are electrifying the transition from laboratory benchtop units to distributed process networks. Pharmaceutical manufacturers and power plant operators are adopting these systems fastest, driven by FDA and EPA documentation requirements. The technology is electrifying vendor business models by embedding predictive maintenance capabilities that extend replacement intervals while locking in long-term service contracts.
REACH chemical safety protocols in Europe now require substance registration and risk assessment documentation that depends on precise conductivity measurement for aqueous solution characterization. Industrial chemical producers must upgrade instrumentation to achieve the data granularity demanded by ECHA compliance timelines. Specialty chemical manufacturing in Germany and the Netherlands faces the steepest compliance burden, prompting accelerated fleet modernization.
Buying patterns among municipal water utilities are compressing procurement cycles as federal infrastructure funding creates concentrated deployment windows. Traditional distributor relationships are giving way to direct vendor engagement for large-scale smart sensor rollouts. This behavioral shift is most pronounced in United States metropolitan water districts managing combined sewer overflow monitoring mandates.
Global Conductivity Meters Market Segmentation
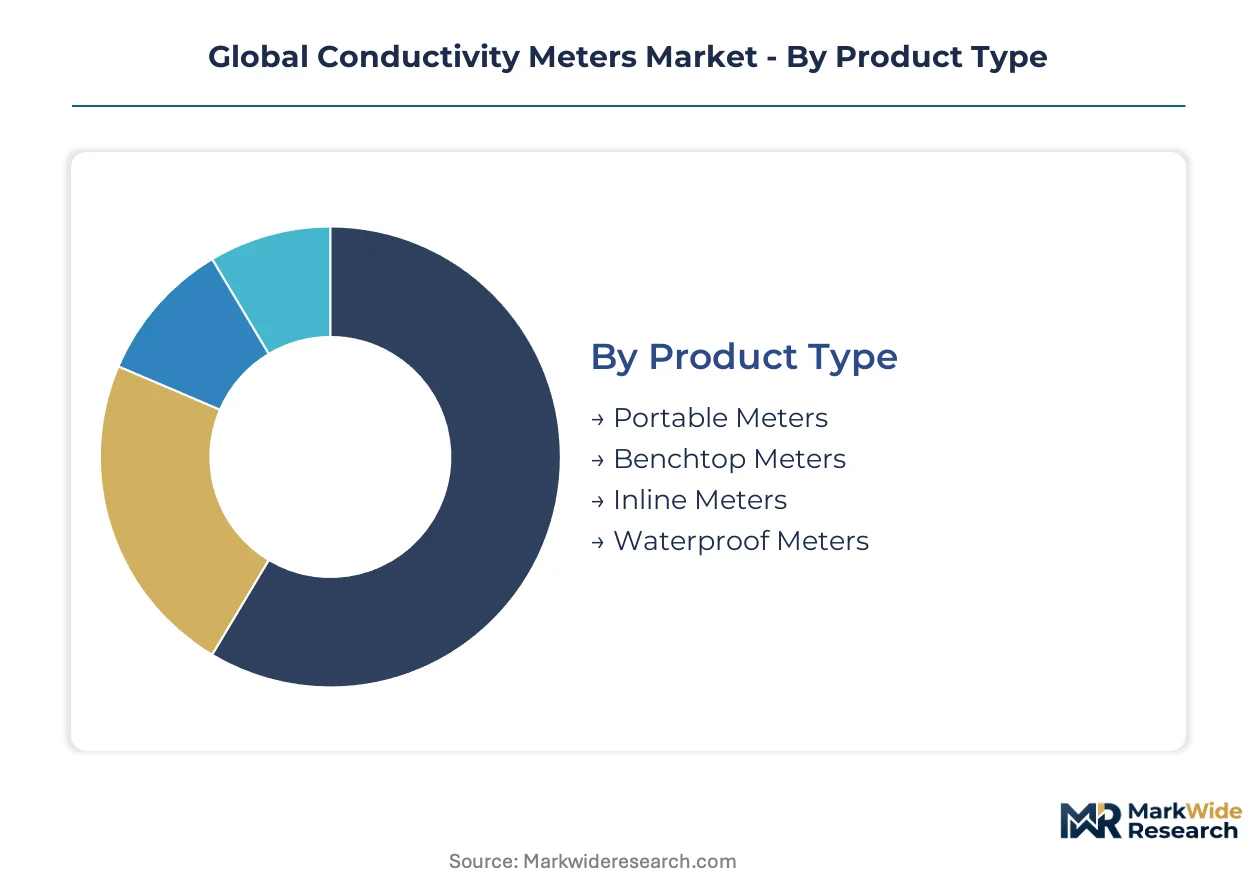
Conductivity meter procurement splits sharply between field-portable flexibility and fixed-installation precision requirements. Buyers prioritize calibration stability in regulated environments versus ruggedized durability in remote deployment scenarios.
Product Type:
Cost tier differentiation separates budget-conscious municipal utilities from pharmaceutical manufacturers demanding validated accuracy.
- Portable Meters:Battery-operated handheld units with interchangeable probe heads dominate field inspection workflows. Water treatment utilities in Germany and the United States deploy these for EPA-mandated discharge spot-checks where laboratory access is impractical.
- Inline Meters:Continuous-process sensors with 4-20mA or digital outputs integrate directly into chemical processing lines. Food & beverage manufacturers in China adopt these fastest to meet GB standards for real-time quality verification without production interruption.
- Benchtop Meters:Laboratory-grade instruments with temperature compensation algorithms serve analytical validation needs.
- Waterproof Meters:IP67-rated enclosures withstand aquaculture pond immersion and agricultural runoff monitoring.
Portable meters lead volumes today; inline meters are gaining share fastest.
Technology:
Application maturity determines whether buyers accept legacy analog architectures or mandate cloud-native diagnostics.
- Digital:Microprocessor-based signal processing with automatic temperature correction and stored calibration curves. Chemical processing plants in the Netherlands favor these for REACH-compliant data logging with minimal operator intervention.
- Smart:Embedded wireless connectivity and predictive maintenance algorithms shift vendor economics toward recurring service revenue. Pharmaceutical manufacturers adopt these under FDA process analytical technology guidelines requiring full audit trails.
- Analog:Traditional potentiometric circuits persist in price-sensitive agricultural monitoring.
- Advanced Sensor:Multi-parameter fusion probes combining conductivity with pH and dissolved oxygen measurement.
Digital architectures dominate current installations; smart systems show the steepest expansion trajectory.
End User:
Regulatory enforcement intensity shapes procurement specifications across vertical markets.
- Water Treatment:Municipal utilities and industrial effluent operators face tightening discharge standards. United States metropolitan districts replace legacy fleets to satisfy EPA combined sewer overflow monitoring mandates with automated data transmission.
- Chemical Processing:Specialty chemical manufacturers require explosion-proof housings and hazardous area certifications. German producers upgrade instrumentation fastest to meet ECHA registration deadlines under REACH protocols.
- Agriculture:Irrigation water quality monitoring drives demand for cost-effective handheld units.
- Food & Beverage:Hygienic design requirements and CIP compatibility constrain sensor selection.
Water treatment commands the largest installed base; chemical processing shows the fastest upgrade cycle.
Application:
Customer type fragmentation separates institutional researchers from industrial operators with divergent service expectations.
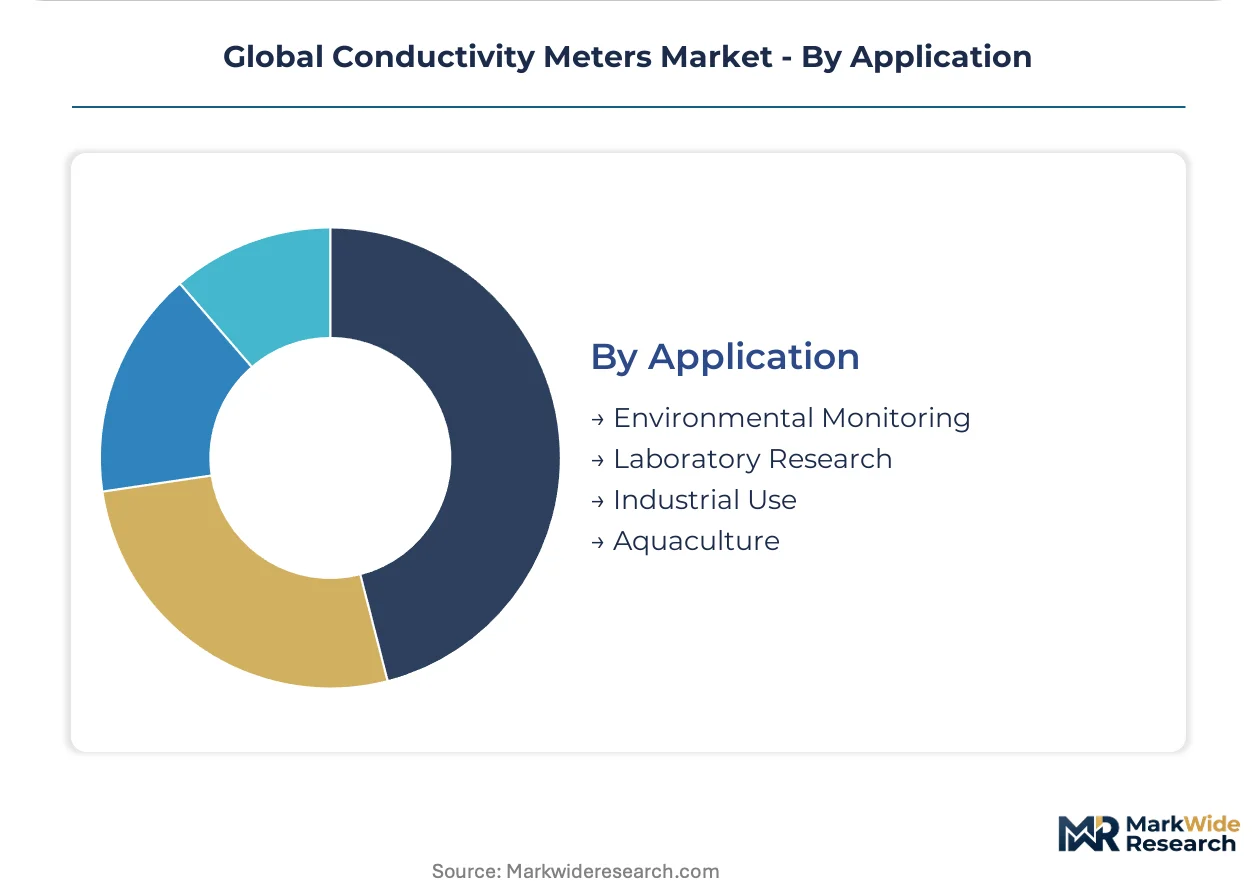
- Industrial Use:Process control integration demands 24/7 reliability with minimal calibration drift. Power plant operators in China deploy redundant inline sensors to prevent boiler scaling under MIIT energy efficiency directives.
- Environmental Monitoring:Field-deployed units withstand temperature extremes and biological fouling. EPA watershed monitoring programs in the United States specify these for long-term deployment without site access.
- Laboratory Research:High-precision benchtop systems serve academic and pharmaceutical R&D validation.
- Aquaculture:Salinity monitoring for shrimp and fish farming operations in coastal regions.
Industrial use anchors current revenue; environmental monitoring is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China operate divergent procurement cycles for conductivity instrumentation, with German chemical manufacturers front-loading compliance-driven replacements while Chinese utilities scale municipal monitoring networks. The United States anchors laboratory-grade demand through pharmaceutical validation requirements. India and Japan round out the concentration map through infrastructure funding and precision manufacturing respectively.
United States
Metropolitan water districts in Chicago and Los Angeles deploy smart conductivity sensors for EPA combined sewer overflow monitoring mandates. The Clean Water Act enforcement timeline accelerates fleet replacement cycles beyond typical depreciation schedules. Boston-area pharmaceutical clusters adopt FDA-validated inline systems for process analytical technology compliance.
Germany
Specialty chemical producers in Ludwigshafen and Leverkusen upgrade instrumentation to meet ECHA registration deadlines under REACH protocols. The EU Green Deal industrial water reuse targets create procurement windows for closed-loop manufacturing systems. Bavarian food processors specify hygienic-design conductivity probes for CIP-compatible installations.
China
Power plant operators in Jiangsu and Guangdong provinces install redundant inline sensors under MIIT energy efficiency directives to prevent boiler scaling. GB water quality standards tighten performance requirements for measurement accuracy in municipal treatment facilities. Yangtze River Delta chemical parks drive demand for explosion-proof housings with hazardous area certifications.
India
The Jal Jeevan Mission channels central government funding into rural and semi-urban distribution network instrumentation. State water boards in Maharashtra and Gujarat issue tenders for portable meters supporting field inspection workflows. Tamil Nadu textile clusters adopt cost-effective handheld units for effluent discharge spot-checks.
Japan
Precision equipment manufacturers in Osaka and Nagoya integrate multi-parameter fusion probes into pharmaceutical production lines. METI industrial efficiency guidelines promote continuous process monitoring over manual sampling protocols. Tokyo Bay aquaculture operations deploy IP67-rated waterproof meters for salinity monitoring in shrimp farming.
Global Conductivity Meters Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with laboratory-grade instrumentation consolidating around precision-focused incumbents while process automation hardware fragments across regional system integrators. The vendor map organizes into three strategic archetypes: diversified analytical conglomerates anchoring premium laboratory contracts, dedicated process automation houses capturing chemical plant retrofits, and mid-tier specialists penetrating price-sensitive municipal tenders. Competitive moves concentrate on sensor interoperability certification and predictive maintenance platform bundling.
Among diversified analytical conglomerates, Thermo Fisher Scientific Inc. and Mettler-Toledo International Inc. occupy positions exemplifying the laboratory-validation tier, while Endress+Hauser Group anchors the process automation specialist archetype through dense coverage of industrial channel partnerships. These three entities represent contrasting geographic and structural profiles—Thermo Fisher Scientific Inc. as a U.S.-based corporation, Mettler-Toledo International Inc. as a Swiss precision equipment house, and Endress+Hauser Group as a Swiss-German family-owned enterprise—each capturing value through distinct service infrastructure configurations rather than hardware differentiation alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Mettler-Toledo International Inc. |
| Endress+Hauser Group |
| Yokogawa Electric Corporation |
| Hach Company |
| Emerson Electric Co. |
| ABB Ltd. |
| Metrohm |
| HORIBA |
| Others |
Supply Flow & Price Mechanics
Municipal water utilities in the United States and Germany concentrate procurement volumes through centralized tender programs, anchoring contract-based pricing with multi-year calibration service bundles. This buyer concentration grants volume leverage that compresses hardware margins while elevating recurring revenue streams for vendors with dense service networks.
Pricing Analysis
Capacity additions in China are reshaping price floors for entry-level portable meters, forcing mid-tier vendors toward premium positioning through smart sensor architectures. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from REACH-compliant industrial units and basic agricultural handhelds. Price differentiation hinges on certification grade and after-sales service density. Cost compression in the economy tier is intensifying because of commoditized probe manufacturing. Municipal utilities exhibit highest price sensitivity; pharmaceutical manufacturers show lowest sensitivity due to validation requirements.
Supply Chain Analysis
Refurbishment flows for platinum-coated electrodes create secondary supply channels that moderate raw material cost spikes for sensor manufacturers. Manufacturing concentrates in China, Germany, and Switzerland, with probe assembly drawing from Japanese precision electronics and United States microprocessor sourcing. Platinum-group metal coatings, glass electrode substrates, and wireless communication modules constitute critical input dependencies. Single-source vulnerability in platinum supply from South African mining operations presents structural risk. Distribution runs through process automation integrators and laboratory equipment distributors with regional service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The conductivity meters market functions as a regulatory compounder where EPA discharge mandates and REACH registration deadlines generate predictable replacement cycles regardless of macroeconomic conditions.
For Market Incumbents: Deepen vertical integration into platinum electrode coating capabilities to insulate margin stability from commodity volatility. Anchor position through captive calibration service networks in metropolitan water districts facing EPA combined sewer overflow deadlines. Defend against optical dissolved oxygen substitution by embedding multi-parameter fusion into core probe architectures. For New Entrants and Emerging Players: Enter via India's Jal Jeevan Mission procurement windows for rural distribution network instrumentation, the most penetrable geography given infrastructure funding concentration. Target cost-optimized portable meters for Tamil Nadu textile cluster effluent monitoring. Pursue direct vendor engagement models that bypass traditional distributor relationships in United States metropolitan districts. For Investors and Strategic Acquirers: Process automation conglomerates are the most active acquirer in this space, seeking sensor interoperability platforms to complete digital transformation portfolios. Long-term viability rests on recurring service revenue capture rather than hardware shipment volumes. Monitor ECHA registration deadline extensions as inflection indicators for European chemical manufacturer upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Interoperability Certification | FDA process analytical technology guidelines demand open-architecture validation protocols. |
| Predictive Maintenance Platform Launch | Cloud-native diagnostics lock in long-term service contracts with pharmaceutical manufacturers. |
| Multi-Parameter Fusion Probe Development | REACH-compliant chemical producers require consolidated pH-conductivity-temperature measurement. |
| Direct Municipal Engagement Program | EPA combined sewer overflow mandates compress procurement cycles in United States districts. |
| Platinum Coating Backward Integration | Electrode cost volatility threatens margin stability for mid-tier instrument producers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at chemical processing facilities, procurement leads at municipal water utilities, aftermarket service heads at instrumentation distributors, and technical R&D directors at sensor manufacturers with secondary validation against EPA enforcement databases, ECHA registration filings, MIIT energy efficiency directives, and SEC 10-K disclosures from listed analytical equipment vendors. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates.
Segment-weighting approaches distributed value across product type, technology architecture, end-use vertical, and regional regulatory cluster dimensions. CAGRs were derived from installed base turnover rates and compliance-driven replacement schedules. Forecast inputs incorporated platinum price trajectory assumptions and federal infrastructure funding allocation patterns.
Inputs from regulatory filing databases and utility procurement records were available through the study window; gaps in real-time smart sensor deployment statistics introduce uncertainty bands around digital transition timing. Forecasts reflect documented assumptions about EPA enforcement continuity and REACH deadline adherence. Practitioners should monitor ECHA registration timeline adjustments and Jal Jeevan Mission funding release schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Circuit Breaker Test Devices Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Laser Interferometer Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
E-Axle and Inverter Efficiency and Reliability Test Platforms Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Sound Meter Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
Global 5G Test Equipment Market
Test and Measurement
Nanomechanical Testing Market