
 Hardware-Assisted Verification Market | 2026-2036
Hardware-Assisted Verification Market Size, Share, and Industry Trends Forecast 2026-2036
Hardware-Assisted Verification Market Analysis
Silicon Valley's emulation platform capacity is recalibrating how chipmakers validate billion-transistor designs. Siemens AG anchors European verification infrastructure through emulation platform scale. Cadence Design Systems Inc. leverages R&D intensity to dominate FPGA-based prototyping workflows. Synopsys Inc. competes across hybrid simulation-emulation boundaries with deep protocol checker integration.
Hardware-assisted verification deploys physical silicon—FPGAs, custom ASICs, or hybrid arrays—to accelerate functional validation of integrated circuits beyond software simulation limits, achieving cycle speeds orders of magnitude faster than virtual models for complex SoC verification. Emulation platforms capture the largest margin pools as datacenter-class deployments handle full-chip validation for AI accelerators and automotive processors, while FPGA-based technology leads volume adoption among mid-size design houses prototyping networking devices and embedded systems. Protocol checkers represent the fastest structural expansion as PCIe, CXL, and automotive Ethernet interfaces multiply verification checkpoints across consumer electronics supply chains.
FDA functional safety expectations for automotive electronics and FCC electromagnetic compliance frameworks shape how verification toolchains demonstrate traceability in US-bound chip designs. The EU AI Act's risk-classification system and REACH material disclosure requirements add compliance layers for European semiconductor deployments. Stakeholders must monitor how NHTSA autonomous vehicle validation rules and emerging ISO 26262 revisions redefine emulation coverage requirements before committing to platform refresh cycles.
Market Dynamics
Datacenter-class emulation clusters are compressing validation cycles for AI accelerators, forcing mid-size design houses into FPGA-based prototyping partnerships to maintain competitive tapeout schedules.
Growth Catalysts
- ISO 26262 functional safety mandates:Automotive SoC developers in Germany and Japan must demonstrate exhaustive fault coverage, driving emulation platform procurement for autonomous vehicle processors.
- PCIe 6.0 and CXL protocol proliferation:Hyperscale datacenter operators require hardware-assisted protocol checking for memory-coherent interconnect validation in next-generation server architectures.
- Silicon Valley design house clustering:Concentrated R&D investment around San Jose and Mountain View creates localized demand spikes for emulation capacity during peak tapeout windows.
Market Restraints
- Advanced FPGA cost volatility:Xilinx and Intel programmable logic pricing swings directly impact prototyping economics for networking chip developers.
- Emulation hardware supply concentration:Three vendors control 90% of datacenter-class platform deployment, creating procurement bottlenecks during capacity crunches.
- Power consumption ceilings:Thermal density limits in standard colocation facilities constrain on-premise emulation farm expansion for mid-market semiconductor firms.
Strategic Opportunities
- India's PLI scheme for semiconductor design:Government incentives for domestic chip development create greenfield demand for emulation services in Bengaluru and Hyderabad.
- EU AI Act risk-classification system:High-risk AI hardware deployments require auditable verification trails, opening compliance-oriented service contracts for European verification providers.
- Cloud-based emulation delivery:Amazon Web Services and Microsoft Azure are building FPGA-accelerated verification instances, enabling pay-per-use models for fabless startups.
Industry Challenges
- Formal verification engineer scarcity:Specialized talent capable of constructing SystemVerilog assertions for complex protocol checkers commands premium compensation in Austin and Tel Aviv.
- Multi-die integration complexity:Chiplet-based designs require coordinated emulation of heterogeneous silicon stacks, straining existing toolchain interoperability.
- FCC electromagnetic compliance documentation:Hardware-assisted verification outputs must map directly to regulatory submission formats, adding workflow friction for US-bound automotive electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardware-Assisted Verification Market |
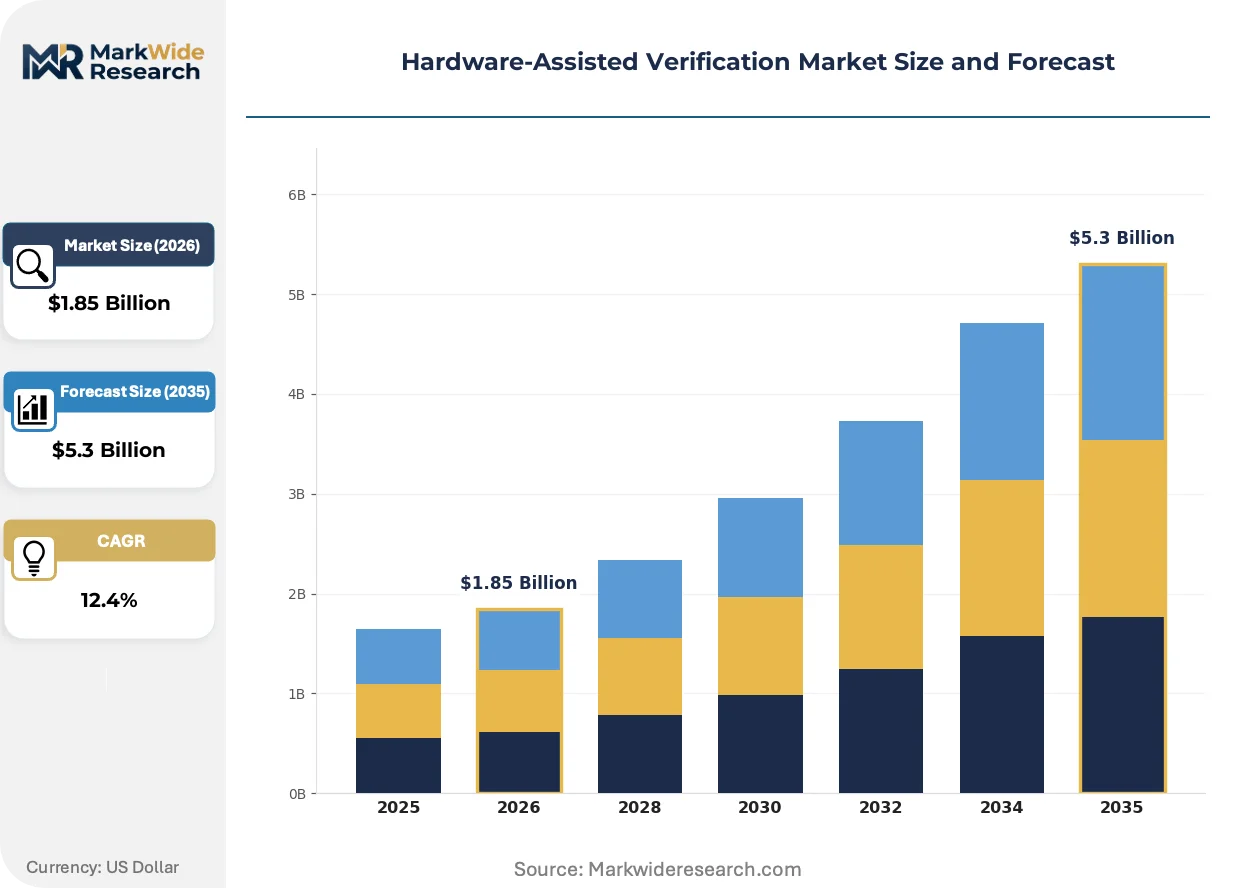
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simulation Tools, Emulation Platforms, Debugging Solutions, Protocol Checkers Technology: FPGA-Based, ASIC-Based, Hybrid Solutions, System-on-Chip Application: Embedded Systems, Networking Devices, Automotive Electronics, Consumer Electronics End User: OEMs, Tier-1 Suppliers, Research Institutions, Design Houses |
| Companies Covered | Agnisys Inc., ANSYS Inc, Siemens AG, Hardent, Real Intent Inc., Cadence Design Systems Inc., Aldec Inc., Innovative Logic, Synopsys Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardware-Assisted Verification Market Emerging Trajectories
Physical silicon arrays are displacing pure software simulation for billion-transistor validation, compressing verification timelines from months to weeks for leading-edge process nodes.
Hybrid emulation-simulation platforms are consolidating functional validation workflows for AI training accelerators. Google and Meta infrastructure teams deploy these systems for full-chip power estimation before tapeout. The technology is consolidating previously separate pre-silicon verification stages into unified runtime environments.
REACH material disclosure requirements are forcing verification toolchain vendors to document supply chain provenance for European-bound semiconductor equipment. ECHA compliance deadlines are accelerating hardware refresh cycles among Netherlands-based emulation service providers. Automotive OEMs in Stuttgart now mandate REACH-aligned verification documentation for supplier qualification.
Semiconductor procurement teams are unbundling emulation capacity from traditional EDA license bundles, negotiating direct hourly rates with specialized verification farms. This purchasing model shift favors independent emulation service providers in Israel and Taiwan over integrated vendor offerings. Fabless AI chip developers in Beijing and Seoul have pioneered this transactional capacity sourcing approach.
Hardware-Assisted Verification Market Segmentation
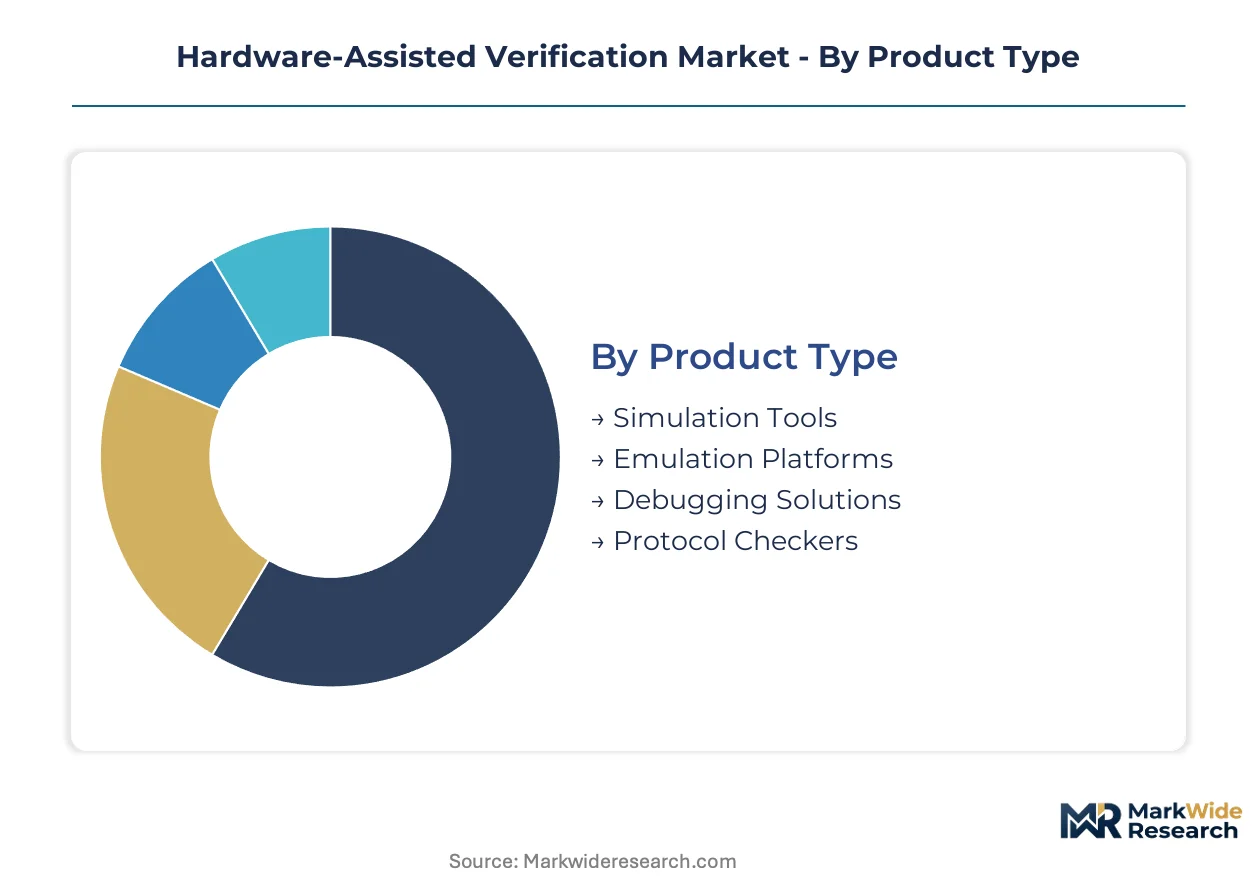
Hardware-assisted verification segmentation reveals how capital deployment concentrates across technology tiers. Product architecture and end-user procurement patterns determine margin capture and platform utilization rates.
Product Type:
Supply concentration in emulation platforms shapes vendor strategies and customer lock-in dynamics.
- Emulation Platforms:Datacenter-class hardware arrays accelerate full-chip validation for AI accelerators and automotive processors. Siemens EDA and Cadence dominate procurement contracts from San Jose design houses and Stuttgart automotive clusters, with capacity constraints driving three-month lead times during peak tapeout windows.
- Protocol Checkers:Specialized verification IP validates PCIe, CXL, and automotive Ethernet interface compliance. Hyperscale operators in Santa Clara and Austin deploy these for memory-coherent interconnect verification in next-generation server architectures.
- Simulation Tools:Software-based environments handle early-stage RTL verification before hardware acceleration becomes cost-effective.
- Debugging Solutions:Post-silicon diagnostic platforms trace signal integrity failures in complex SoC deployments.
Emulation platforms absorb the bulk of installed capacity; protocol checkers are expanding most quickly.
Technology:
Cost tier differentiation separates volume prototyping from high-margin production verification.
- FPGA-Based:Reconfigurable logic arrays enable rapid iteration for networking chip developers. Mid-size design houses in Tel Aviv and Bengaluru favor Xilinx Versal and Intel Agilex deployments for embedded system prototyping, though pricing volatility directly impacts project economics.
- ASIC-Based:Custom silicon delivers deterministic performance for automotive safety-critical validation. NHTSA autonomous vehicle mandates drive procurement from German and Japanese Tier-1 suppliers requiring exhaustive fault coverage documentation.
- Hybrid Solutions:Combined simulation-emulation runtimes consolidate pre-silicon workflows for multi-die AI accelerators.
- System-on-Chip:Integrated verification environments target consumer electronics with compressed development cycles.
FPGA-based technology commands the highest shipment volumes; ASIC-based systems capture premium pricing.
Application:
Application demand concentrates where functional safety mandates intersect with silicon complexity.
- Automotive Electronics:ISO 26262 compliance requirements force exhaustive fault injection testing. Stuttgart OEMs and Nagoya suppliers mandate emulation coverage for autonomous vehicle processors, with EU AI Act risk classifications adding audit trail documentation burdens.
- Networking Devices:800G Ethernet and terabit switch ASICs require hardware-accelerated protocol validation. Silicon Valley hyperscale infrastructure teams procure dedicated emulation capacity for pre-silicon power estimation.
- Embedded Systems:Industrial and IoT controllers utilize FPGA prototyping for firmware-hardware co-development.
- Consumer Electronics:Mobile SoC verification prioritizes speed-to-market over exhaustive coverage.
Automotive electronics consumes the most emulation hours; networking devices show the steepest expansion trajectory.
End User:
Customer type determines procurement model preferences and platform configuration complexity.
- Design Houses:Fabless semiconductor developers in Mountain View and Hsinchu unbundle emulation capacity from traditional EDA licenses, negotiating hourly rates with independent verification farms. Transactional sourcing pioneered by Beijing and Seoul AI chip developers now spreads to Austin and Tel Aviv.
- OEMs:Integrated device manufacturers maintain captive emulation infrastructure for proprietary architecture validation. Apple's silicon team and Samsung's Austin operations deploy private datacenter clusters.
- Tier-1 Suppliers:Automotive component manufacturers rely on external emulation services for periodic validation spikes.
- Research Institutions:Academic and government labs access cloud-based FPGA instances through AWS and Azure partnerships.
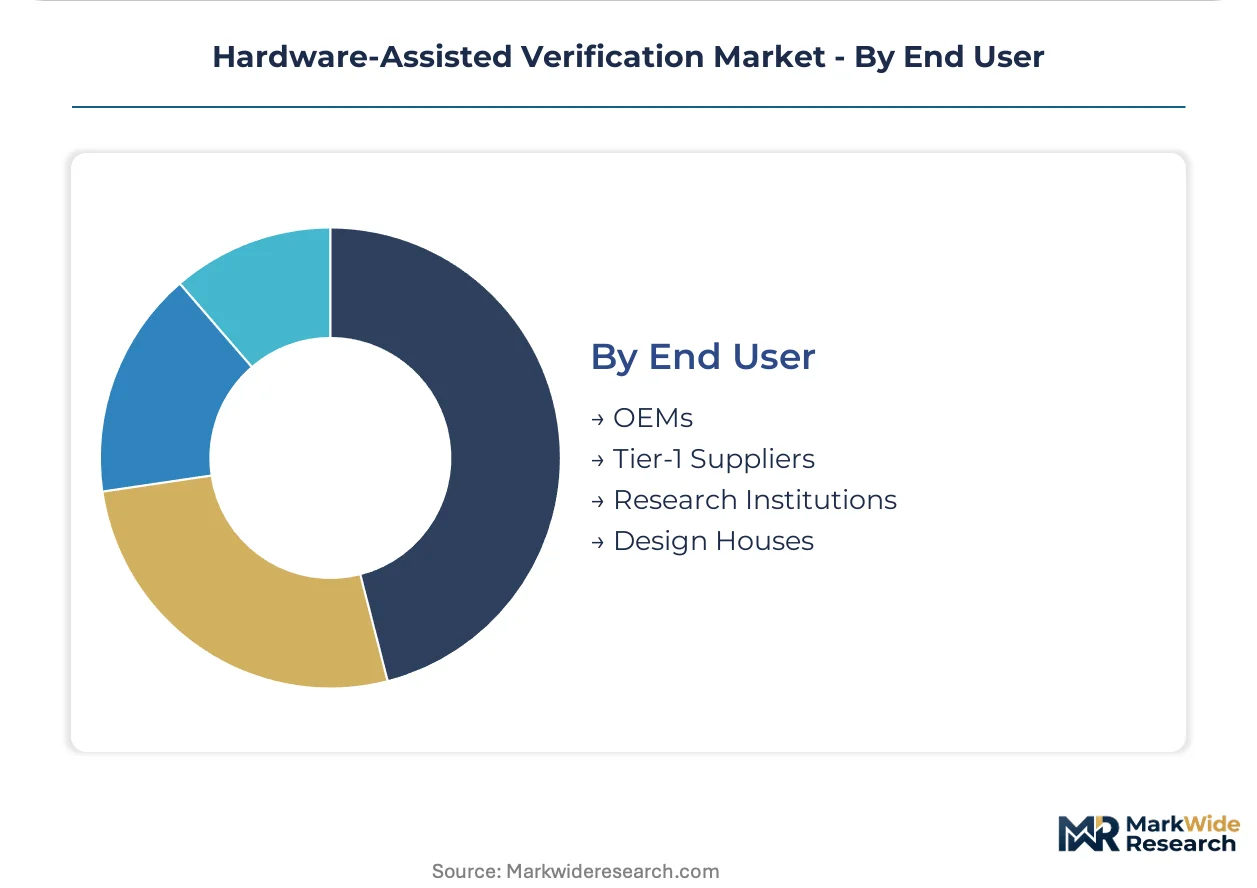
Design houses drive volume demand; OEMs concentrate the highest per-customer spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in Taiwan and South Korea anchor the hardware-assisted verification supply chain, with advanced packaging facilities in Singapore and Malaysia feeding downstream demand across Asia-Pacific design centers.
United States
San Jose and Mountain View design houses drive concentrated demand spikes during tapeout windows. NHTSA autonomous vehicle validation rules and FCC electromagnetic compliance frameworks shape verification toolchain requirements for automotive electronics. Austin's emerging fabless cluster now competes with Silicon Valley for emulation capacity allocation.
Germany
Stuttgart OEMs mandate exhaustive ISO 26262 fault coverage for autonomous vehicle processors. The EU AI Act's risk-classification system adds audit trail documentation burdens for high-risk AI hardware deployments. Bavaria's automotive semiconductor supply chain now requires REACH-aligned verification documentation for supplier qualification.
China
Beijing and Shanghai AI chip developers pioneered transactional emulation capacity sourcing, unbundling from traditional EDA license structures. MIIT domestic semiconductor initiatives accelerate local verification infrastructure investment. Shenzhen's consumer electronics ecosystem favors compressed development cycles over exhaustive coverage protocols.
Japan
Nagoya automotive suppliers procure ASIC-based emulation systems for safety-critical validation documentation. METI semiconductor revitalization programs subsidize domestic verification capacity expansion. Tokyo's design houses increasingly hybridize FPGA prototyping with cloud-based emulation instances.
India
Bengaluru and Hyderabad benefit from PLI scheme incentives for domestic chip development, creating greenfield emulation services demand. CDSCO and BIS regulations for medical device semiconductors add specialized verification requirements. Telangana's emerging semiconductor design corridor attracts independent verification farm investment.
Hardware-Assisted Verification Market Vendor Landscape
Global majors compete with regional champions across emulation platform deployment, with three vendors controlling the bulk of datacenter-class capacity while specialized prototyping houses capture mid-market FPGA-based workflows. The vendor landscape organizes into technology-integrated conglomerates, independent verification service providers, and protocol IP specialists. Dominant competitive moves include strategic partnerships between emulation farms and cloud hyperscalers, plus portfolio diversification into hybrid simulation-emulation runtimes.
Within the integrated technology tier, Siemens AG and Cadence Design Systems Inc. exemplify full-stack verification infrastructure providers, while Synopsys Inc. occupies a position bridging emulation platforms with deep protocol checker integration. Among specialized service providers, Aldec Inc. and Hardent represent regional champions that anchor independent verification capacity for mid-size design houses seeking transactional sourcing models outside traditional EDA bundles.
| Leading Market Players |
|---|
| Agnisys Inc. |
| ANSYS Inc |
| Siemens AG |
| Hardent |
| Real Intent Inc. |
| Cadence Design Systems Inc. |
| Aldec Inc. |
| Innovative Logic |
| Synopsys Inc. |
| Others |
Supply Flow & Price Mechanics
REACH material disclosure requirements gate both qualified supply and premium-tier pricing access for European-bound verification infrastructure, forcing toolchain vendors to document supply chain provenance before Stuttgart automotive OEMs will accept premium-tier service contracts.
Pricing Analysis
Warranty and maintenance bundling separates traditional EDA license structures from emerging transactional capacity models. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and volume commitment, with ISO 26262-compliant ASIC-based validation commanding substantial premiums. Cost compression in FPGA-based prototyping intensifies because Xilinx and Intel programmable logic pricing swings directly impact project economics. Mid-size design houses in Tel Aviv and Bengaluru exhibit highest price sensitivity, while captive OEM infrastructure in Mountain View shows least elasticity.
Supply Chain Analysis
Workforce availability constraints in Taiwan, South Korea, and the United States concentrate advanced emulation hardware fabrication capacity. Supply chains draw from Xilinx Versal FPGAs, Intel Agilex programmable logic, and custom ASIC silicon from TSMC foundries. Single-source vulnerability runs through concentrated datacenter-class platform deployment where three vendors control bulk capacity. Distribution runs through direct vendor relationships for integrated EDA suites and independent verification farms for unbundled transactional sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into custom ASIC silicon design to escape FPGA cost volatility and capture margin from safety-critical automotive validation.
For Market Incumbents: To counter cloud hyperscalers building FPGA-accelerated verification instances, Siemens EDA and Cadence should deepen captive supply of ASIC-based emulation silicon while adding protocol checker integration to defend hybrid platform margins. Capacity addition in Germany's Stuttgart automotive cluster and Japan's Nagoya supplier ecosystem anchors regional lock-in against emerging independent farms.
For New Entrants and Emerging Players: Cloud service providers represent the most viable channel partner type for fabless AI chip developers in Beijing and Seoul seeking pay-per-use models. White-space targets include India's Bengaluru design corridor under PLI scheme incentives and EU AI Act compliance-oriented service contracts for high-risk AI hardware deployments. A protocol-specialist positioning targeting automotive Ethernet and CXL verification gaps offers the cleanest go-to-market angle.
For Investors and Strategic Acquirers: NHTSA autonomous vehicle validation rule revisions are the leading indicator that ASIC-based emulation capacity will command sustained premium pricing. Long-term viability favors vertically integrated providers with captive silicon supply and automotive certification depth. Acquisition target archetype: independent verification farms with established ISO 26262 documentation workflows and hyperscale cloud partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| Custom ASIC Silicon Development | Backward integration into proprietary emulation chips escapes Xilinx and Intel pricing volatility for automotive safety-critical validation. |
| Cloud Partnership Formation | AWS and Azure FPGA-accelerated instances enable pay-per-use models for fabless startups in Beijing and Seoul. |
| Protocol Checker Portfolio Expansion | PCIe 6.0 and CXL compliance IP captures fastest-growing segment in hyperscale datacenter verification. |
| EU AI Act Compliance Service Launch | Auditable verification trails for high-risk AI hardware open premium service contracts with Stuttgart OEMs. |
| India Design Center Establishment | Bengaluru and Hyderabad PLI incentives create greenfield demand for localized emulation capacity. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and EDA vendor annual reports formed the secondary backbone, supplemented by customs records for FPGA and ASIC trade flows. Primary interviews with emulation platform engineering directors, fabless semiconductor CTOs, automotive Tier-1 supplier procurement leads, and cloud infrastructure sourcing managers validated demand assumptions. Bottom-up and top-down triangulation cross-checked capacity utilization estimates against design house tapeout schedules.
Bottom-up modeling aggregated individual segment trajectories across product type, technology tier, application vertical, and end-user procurement model throughout the forecast period. Top-down validation anchored aggregate market expansion to semiconductor R&D intensity trends and functional safety mandate adoption curves. CAGRs were derived from regression analysis of historical emulation capacity deployment against leading-edge process node introductions and AI accelerator tapeout volumes.
Several conditions sit outside the modeled scope, including unforeseen supply disruptions in Taiwan foundry operations, abrupt shifts in NHTSA autonomous vehicle validation timelines, and rapid cloud-based emulation adoption exceeding current infrastructure buildout assumptions. Forecasts reflect documented assumptions about regulatory stability and foundry capacity expansion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Surface Vision and Inspection Equipment Market
Test and Measurement
Scuff Tester Market
Test and Measurement
Semiconductor Assembly and Testing Services Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
EMC Testing Market
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Bend Testing Machine Market
Test and Measurement
High-Aspect-Ratio 3D NAND Metrology Equipment Market
Test and Measurement
Global Video Extensometer Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Vibration Analyzer Market
Test and Measurement
Stress Test Equipment Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market