
 Heavy Equipment Movers Market | 2026-2036
Heavy Equipment Movers Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Equipment Movers Market Analytics
Dealer networks for heavy equipment movers is fragmenting as OEMs bypass traditional distributors to serve rental services and large construction companies directly. Caterpillar Inc. controls extensive parts and service infrastructure across North American mining corridors. Komatsu Ltd. leverages its autonomous haulage expertise to differentiate its heavy mover offerings for integrated site operations. XCMG Group anchors volume production from its base in China, competing aggressively on cost for emerging market infrastructure projects.
Heavy equipment movers are self-propelled or towed machines engineered to transport loads exceeding five tons across uneven terrain, typically powered by diesel or electric drivetrains with hydraulic steering and braking subsystems. Their primary purpose centers on relocating excavators, cranes, and modular plant components within confined construction, mining, and port environments where standard trucking proves impractical. Hydraulic movers dominate current fleet composition due to proven torque density and field-repairability, though electric movers are gaining share where warehouse and manufacturing facility operators face indoor emissions constraints. Application demand from shipping yards generates premium pricing owing to salt-corrosion specifications and continuous-duty cycles, while construction sites remain the volume anchor.
FAA regulations govern airside heavy equipment movers at US airports, mandating towbar strength ratings and visibility standards that limit supplier qualification. EPA Tier 4 Final and emerging Stage V emissions frameworks in Europe and North America are elevating engine costs and accelerating electric platform R&D commitments. OSHA lift and rigging standards shape operator training requirements and equipment inspection intervals across US industrial facilities. Stakeholders must weigh electrification capital outlays against tightening emissions enforcement and evolving total-cost-of-ownership calculations for fleet procurement decisions.
Market Dynamics
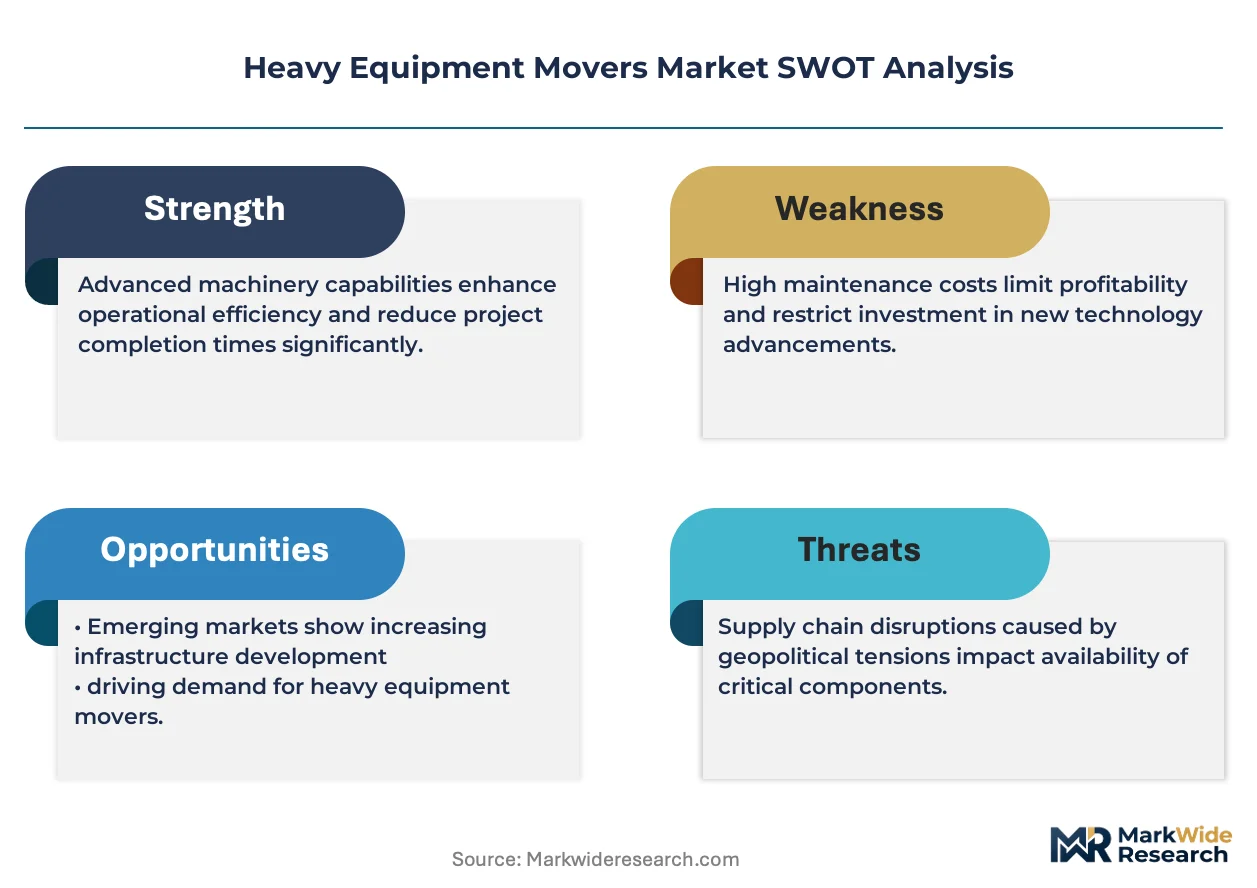
Electrification mandates and emissions enforcement are compressing diesel-equipment residual values while elevating electric platform R&D commitments across heavy equipment mover portfolios.
Growth Catalysts
- EU Green Deal implementation:European Stage V emissions frameworks are accelerating fleet replacement cycles and creating pull-through demand for electrified heavy mover platforms in Germany's industrial corridor.
- Remote mining logistics:Australian extraction operations are expanding specialized transport infrastructure to service inland resource deposits unreachable by conventional trucking networks.
- Port automation investments:Salt-corrosion specifications and continuous-duty requirements at shipping yards are generating premium equipment specifications that expand addressable market value.
Market Restraints
- Engine cost inflation:EPA Tier 4 Final compliance requirements have elevated diesel powertrain costs by 15-25% versus prior-generation equipment, compressing OEM margins on hydraulic platforms.
- Battery supply concentration:Lithium-ion cell production for electric heavy movers remains concentrated in Chinese manufacturing bases, exposing European and North American assemblers to input volatility and trade policy friction.
- Indoor emissions constraints:Warehouse and manufacturing facility operators face OSHA ventilation requirements that limit diesel equipment deployment, yet electric alternatives carry 40-60% capital cost premiums versus equivalent hydraulic units.
Strategic Opportunities
- India infrastructure buildout:National highway expansion and metro rail construction are creating demand for cost-optimized heavy movers capable of operating on unimproved road surfaces.
- Autonomous haulage integration:Convergence of telematics platforms with self-propelled mover controls enables coordinated fleet operations at integrated mining and construction sites.
- Rental channel bypass:OEM direct-to-fleet sales models are capturing margin previously allocated to dealer networks, particularly for large construction company procurement.
Industry Challenges
- Certification timeline compression:FAA airside equipment qualification and EPA emissions certification processes now run 18-24 months, delaying product launch windows and freezing engineering specifications early in development cycles.
- Electrification skill gaps:Field service technicians trained on hydraulic diagnostics require retraining on high-voltage systems, battery thermal management, and regenerative braking subsystems, constraining aftermarket service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Equipment Movers Market |
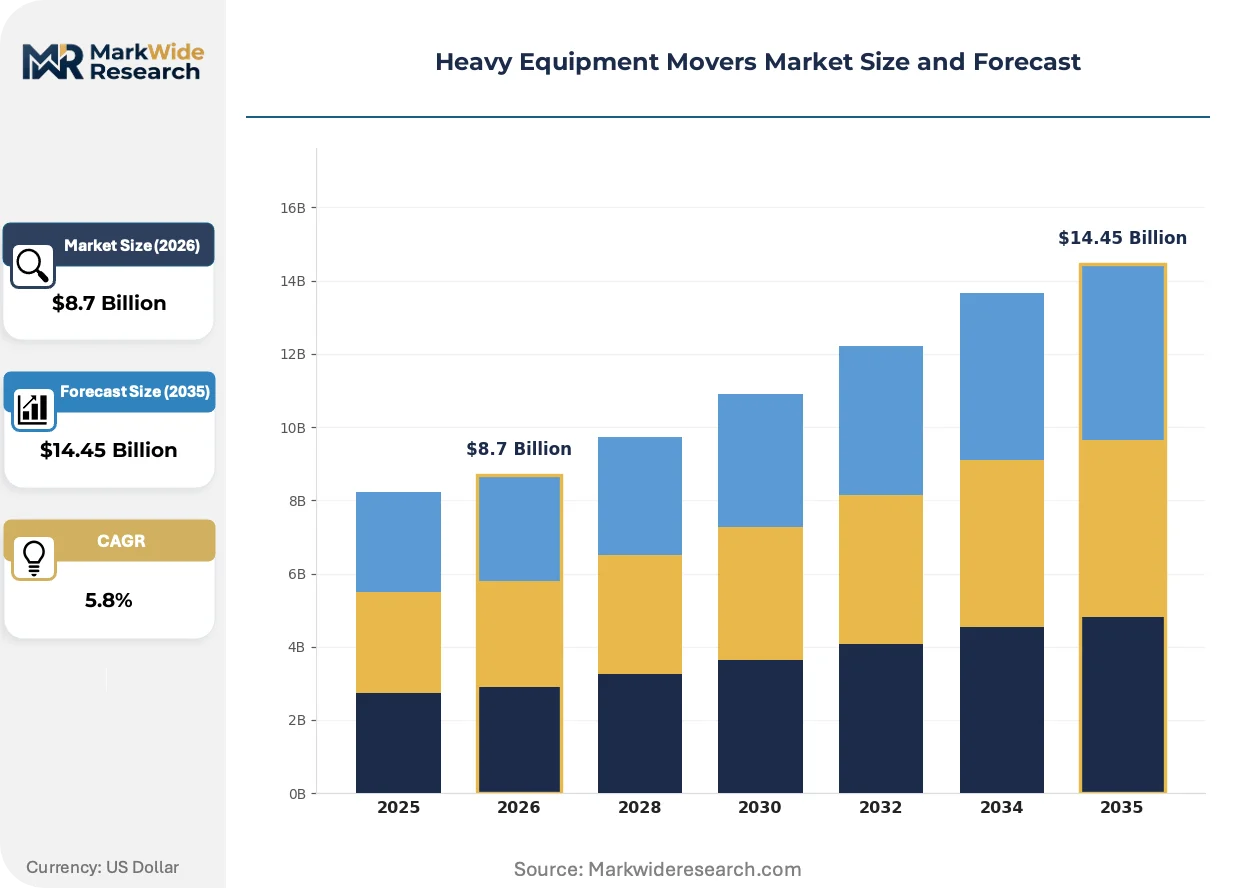
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Movers, Electric Movers, Manual Movers, Towing Equipment Application: Construction Sites, Warehouses, Shipping Yards, Manufacturing Facilities End User: Construction Companies, Logistics Firms, Industrial Manufacturers, Rental Services Capacity: 5 Tons, 10 Tons, 20 Tons, 50 Tons |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., XCMG Group, Sany Heavy Industry Co., Ltd., Volvo Construction Equipment, Hitachi Construction Machinery Co., Ltd., Liebherr Group, Doosan Bobcat Inc., Hyundai Construction Equipment Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Equipment Movers Market Evolving Landscape
Drivetrain architecture is fragmenting across parallel development tracks, with established hydraulic systems facing pressure from modular electric platforms and transitional hybrid configurations.
Modular battery-electric powertrains are hybridizing with existing hydraulic steering and braking subsystems to preserve field-repairability while eliminating tailpipe emissions. Warehouse operators in California and Germany's Rhine-Ruhr corridor are piloting these configurations for indoor material handling. This architecture is hybridizing procurement patterns by allowing staged capital deployment rather than full-platform replacement.
EPA Tier 4 Final and emerging Stage V frameworks are elevating engine costs and compressing diesel equipment production runs. European manufacturers face the steepest compliance gradients, accelerating electric platform commitments ahead of total-cost parity. Integrated site operations in Australian mining and German automotive clusters are most affected, with procurement specifications now mandating emissions disclosure and lifecycle carbon accounting.
Large construction companies and rental fleets are consolidating purchasing decisions into centralized procurement functions, disintermediating traditional dealer relationships. OEMs are responding with direct service contracts and captive parts distribution. This concentration is most visible in North American mining corridors and Germany's machinery clusters, where multi-site operators negotiate enterprise pricing and standardized fleet configurations.
Heavy Equipment Movers Market Segmentation
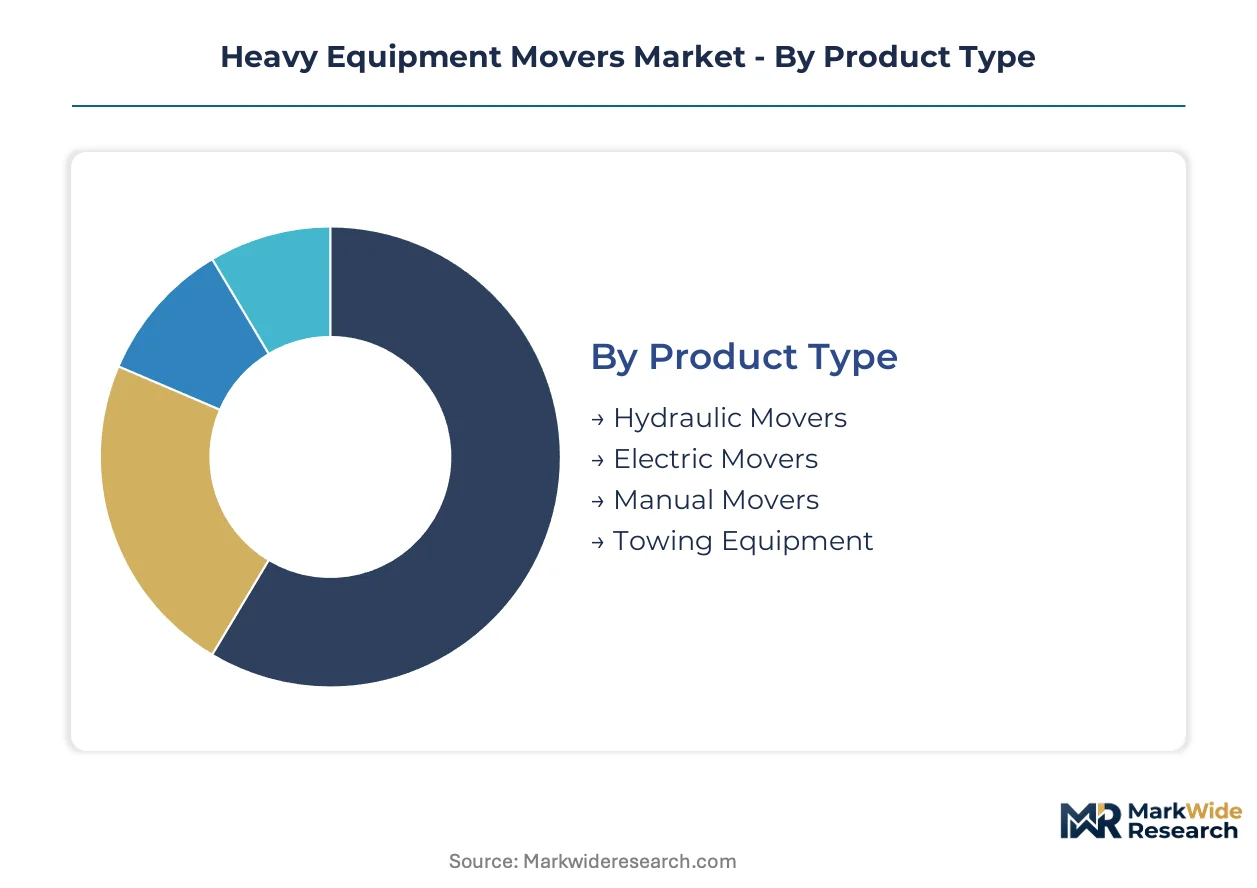
Heavy equipment movers serve distinct operational environments with sharply divergent replacement cycles and specification requirements. Procurement patterns vary dramatically across product architectures, with electrification mandates compressing diesel-equipment residual values while elevating capital commitments for emerging platforms.
Product Type:
Hydraulic movers turn over slowest due to field-repairability and proven torque density, while electric platforms cycle fastest as battery technology iterations accelerate replacement decisions.
- Hydraulic Movers:Diesel-powered systems with hydraulic steering and braking subsystems dominate current fleet composition across mining corridors and construction sites. Australian extraction operations and German automotive clusters specify these units for outdoor heavy-load logistics where emissions constraints remain secondary to field-serviceability. EPA Tier 4 Final compliance has elevated powertrain costs substantially, compressing OEM margins on legacy platforms.
- Electric Movers:Battery-electric powertrains with modular architecture are hybridizing with existing hydraulic subsystems to preserve repairability while eliminating tailpipe emissions. Warehouse operators in California and Germany's Rhine-Ruhr corridor pilot these configurations for indoor material handling where OSHA ventilation requirements constrain diesel deployment. Capital cost premiums of 40-60% versus hydraulic equivalents slow fleet conversion despite tightening emissions frameworks.
- Manual Movers:Human-powered or mechanically assisted systems for loads under five tons serve confined maintenance bays and small-scale fabrication shops.
- Towing Equipment:Towbar-connected systems for airside operations at US airports face FAA qualification requirements limiting supplier participation.
Hydraulic movers anchor the volume base while electric platforms gain share at the steepest rate.
Application:
Cost tier differentiation separates continuous-duty shipping yard specifications from intermittent construction site deployments with lower capital recovery requirements.
- Construction Sites:Intermittent-duty relocations of excavators, cranes, and modular plant components across unimproved terrain drive volume demand. India's national highway expansion and metro rail construction create pull-through for cost-optimized movers capable of operating on rough surfaces. Procurement concentrates among large construction companies negotiating enterprise pricing and standardized fleet configurations.
- Shipping Yards:Salt-corrosion specifications and continuous-duty cycles generate premium pricing and extended service intervals. Port automation investments across European and Asia-Pacific trade gateways are expanding addressable market value for specialized equipment meeting these rigorous environmental standards.
- Warehouses:Indoor emissions constraints under OSHA ventilation requirements limit diesel deployment, favoring electric alternatives despite capital cost premiums.
- Manufacturing Facilities:Production line integration and just-in-time component positioning require precise maneuverability in confined plant layouts.
Construction sites generate the highest unit volumes while shipping yards capture the steepest margin expansion trajectory.
End User:
Customer concentration patterns reveal direct OEM engagement displacing traditional dealer networks among the largest procurement accounts.
- Construction Companies:Multi-site operators in North American mining corridors and Germany's machinery clusters consolidate purchasing into centralized procurement functions. These enterprises negotiate standardized fleet configurations and captive parts distribution agreements that bypass traditional dealer markups.
- Rental Services:Fleet lessors prioritize residual value management and rapid turnaround specifications, driving demand for field-repairable hydraulic platforms over emerging electric alternatives with uncertain secondary markets.
- Logistics Firms:Third-party transport operators serving port and intermodal facilities specify corrosion-resistant equipment for coastal deployment environments.
- Industrial Manufacturers:Captive fleet operators in automotive and heavy machinery clusters favor integrated service contracts with direct OEM relationships.
Construction companies anchor procurement volume while rental services are expanding most quickly as fleet outsourcing accelerates.
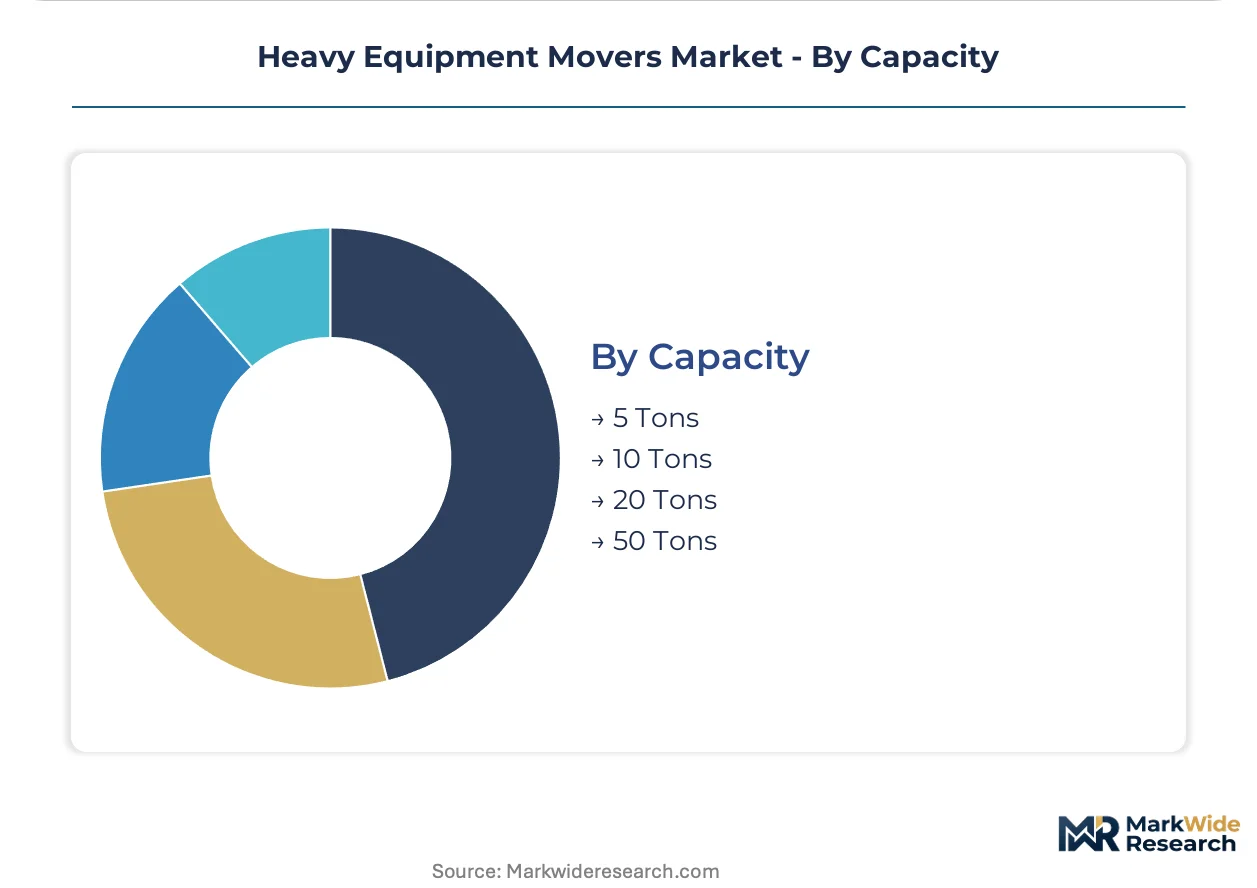
Capacity:
Application scale determines specification tier, with discrete payload thresholds triggering distinct regulatory and operational requirements.
- 50 Tons:Maximum-capacity systems for modular plant component relocation and heavy crane transport command specialized engineering and premium pricing. Australian mining operations expanding remote extraction infrastructure specify these units for inland resource deposits unreachable by conventional trucking.
- 20 Tons:Mid-range capacity serves excavator and medium crane repositioning across integrated construction and mining sites.
- 10 Tons:Compact systems for urban construction and facility maintenance balance maneuverability with load capability.
- 5 Tons:Entry-capacity units face substitution pressure from manual movers and standard industrial forklifts in light-duty applications.
20-ton and 50-ton segments dominate revenue concentration while 10-ton equipment is climbing the fastest as urban infrastructure constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums for salt-corrosion specifications at German ports exceed equivalent equipment in Indian construction corridors by substantial margins, reflecting divergent specification intensity and duty-cycle requirements across regional demand centers.
Germany
Automotive and machinery clusters in the Rhine-Ruhr corridor drive specialized heavy-load logistics procurement. EU Green Deal Stage V emissions frameworks accelerate fleet replacement cycles for electrified platforms. Stuttgart and Munich industrial zones mandate emissions disclosure and lifecycle carbon accounting in procurement specifications.
Australia
Remote mining operations expand specialized transport infrastructure to service inland resource deposits unreachable by conventional trucking networks. TGA equipment certification requirements govern site safety protocols for autonomous haulage integration. Western Australia extraction sites specify maximum-capacity 50-ton systems for modular plant component relocation.
United States
FAA regulations govern airside heavy equipment movers at airports, mandating towbar strength ratings and visibility standards that limit supplier qualification. EPA Tier 4 Final compliance elevates diesel powertrain costs substantially across North American mining corridors. Texas and Arizona extraction operations consolidate purchasing into centralized procurement functions bypassing traditional dealer networks.
China
National infrastructure buildout and dual carbon goals create demand for cost-optimized heavy movers on unimproved road surfaces. MIIT equipment standards and GB certification frameworks shape domestic manufacturing requirements. Xuzhou machinery clusters anchor volume production competing aggressively on cost for emerging market projects.
India
National highway expansion and metro rail construction generate demand for equipment capable of operating on rough surfaces. BIS certification and CEA electrical safety standards regulate equipment deployment. Maharashtra and Gujarat construction corridors concentrate procurement among large operators negotiating enterprise pricing.
Heavy Equipment Movers Market Competitive Landscape
Integrated mining-technology providers and construction-equipment conglomerates split the market between site-automation solutions and volume-production platforms. Consolidation concentrates among North American and East Asian players with captive parts distribution, while European specialists defend premium positioning through corrosion-resistant specifications. Three archetypes dominate: diversified industrial conglomerates with mining-technology integration, scale-driven volume manufacturers from Chinese production bases, and premium-tier European specialists. Competitive moves center on direct-to-fleet sales models disintermediating dealer networks, and modular electric platform development compressing diesel-equipment residual values.
Among diversified industrial conglomerates, Caterpillar Inc. and Komatsu Ltd. occupy positions exemplifying integrated site-automation capabilities, while XCMG Group anchors the scale-driven manufacturing archetype from its Chinese production base. These three represent the structural tension between technology-integrated premium positioning and cost-optimized volume competition reshaping procurement channel economics.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| XCMG Group |
| Sany Heavy Industry Co., Ltd. |
| Volvo Construction Equipment |
| Hitachi Construction Machinery Co., Ltd. |
| Liebherr Group |
| Doosan Bobcat Inc. |
| Hyundai Construction Equipment Co., Ltd. |
| Others |
Value Network & Pricing Analysis
The Rhine-Ruhr freight corridor channels German industrial logistics demand into pricing premiums for corrosion-resistant equipment, while Chinese battery cell concentration compresses margins on electric platforms and forces tiered pricing separation between standard hydraulic units and emissions-compliant configurations.
Pricing Analysis
Customization-premium spreads widen dramatically between FAA-certified airside towbar systems and standard construction-site hydraulic movers, with salt-corrosion specifications at European ports commanding substantial markups over Indian highway construction equipment. Three-tier pricing structure across premium corrosion-resistant, standard heavy-load, and economy compact segments reflects certification grade and duty-cycle intensity. Cost compression in mid-range hydraulic tiers intensifies because EPA Tier 4 Final compliance elevated diesel powertrain costs substantially. Rental services exhibit highest price sensitivity due to residual value uncertainty, while Australian mining operators show lowest sensitivity given remote-site operational imperatives.
Supply Chain Analysis
Contract manufacturing concentration for lithium-ion battery packs rests with Chinese cell producers in Xuzhou and Shenzhen industrial zones, while hydraulic subsystem fabrication concentrates in German and Japanese component clusters. Raw material dependencies include high-grade steel for frame structures, lithium carbonate for electric powertrains, and specialized hydraulic fluids for steering subsystems. Single-source vulnerability in battery cell supply exposes European and North American assemblers to trade policy friction and input volatility. Distribution runs through OEM direct-to-fleet channels displacing traditional dealer networks, particularly for large construction company procurement in North American mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks mining capital expenditure cycles, with Australian extraction expansion and Indian infrastructure buildout signaling recovery-phase demand acceleration across the analysis window.
For Market Incumbents: Harden aftermarket service moats by capturing high-voltage technician training capacity ahead of electrification skill gaps constraining field repair networks. Deepen backward integration into battery thermal management subsystems to defend margin position against Chinese cell supplier pricing power. Prioritize FAA qualification maintenance for airside equipment segments where regulatory barriers limit competitive entry.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat construction corridors offer white-space penetration for cost-optimized movers capable of rough-surface operation where incumbent premium positioning leaves volume gaps. Target warehouse operators in California's Central Valley facing OSHA ventilation constraints with modular electric-hybrid configurations enabling staged capital deployment. Pursue rental fleet partnerships as the fastest-converting channel given outsourcing acceleration among mid-tier construction operators.
For Investors and Strategic Acquirers: Regional specialists with captive corrosion-resistant engineering capabilities present acquisition targets given port automation investment trajectories across European and Asia-Pacific trade gateways. Long-term viability favors integrated site-automation providers over pure equipment manufacturers as autonomous haulage convergence reshapes procurement specifications. Watch Australian TGA certification timelines for autonomous equipment as inflection indicator for technology-integrated premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Electric Platform Development | Preserves field-repairability while eliminating tailpipe emissions for warehouse operators under OSHA constraints. |
| Direct-to-Fleet Sales Channel Establishment | Captures dealer margin previously allocated to distribution networks serving large construction company procurement. |
| Autonomous Haulage Integration Investment | Enables coordinated fleet operations at Australian mining sites requiring TGA-certified site safety protocols. |
| Corrosion-Resistant Specification Engineering | Commands premium pricing at European port facilities facing salt-environment continuous-duty requirements. |
| High-Voltage Technician Training Program | Addresses electrification skill gaps constraining aftermarket service capacity for battery-electric platforms. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at mining operations, plant engineers at German automotive clusters, OEM procurement teams, and aftermarket service heads, then refined through secondary validation against SEC 10-K filings, customs and trade data, equipment registration databases, and industry association reports. Bottom-up unit demand modeling triangulated against top-down market sizing across hydraulic, electric, and hybrid platform categories.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon, with segmentation dimensions spanning product architecture, application environment, end-user concentration patterns, and regional regulatory clusters. CAGRs were derived from installed base turnover analysis and replacement cycle compression under emissions mandates, incorporating mining capital expenditure trajectories and port automation investment pipelines as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese volume manufacturers or European electrification specialists would shift outcomes beyond modeled ranges. Quarterly review of EPA certification timelines, lithium carbonate pricing, and Australian mining fleet expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Electric Single Beam Crane Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
High-Precision Gear Reducer Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Industrial Lift Ladder Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Conveyor Sprocket Market