
 Building Integrated Photovoltaic (BIPV) Market | 2026-2036
Building Integrated Photovoltaic (BIPV) Market Size, Share, and Industry Trends Forecast 2026-2036
Building Integrated Photovoltaic (BIPV) Market Outlook
Certified BIPV installation labor is unwinding the bottleneck that has suppressed deployment velocity across Europe and North America. Tesla leverages its energy division to anchor residential solar roof penetration in California and Texas. LONGi Green Energy Technology dominates crystalline silicon module supply for commercial facade projects across East Asia. Onyx Solar specializes in transparent photovoltaic glass, sustaining premium positioning in heritage building retrofits where aesthetic constraints limit conventional panel use.
Building Integrated Photovoltaic refers to solar energy systems that replace conventional building envelope materials rather than attaching to surfaces, typically achieving 15-20% conversion efficiency in crystalline configurations while serving simultaneous structural and weatherproofing functions. The technology generates electricity at the point of consumption, eliminating transmission losses and reducing peak demand charges for commercial and institutional operators. Solar roofs command the largest installed base among product types, though transparent PV is capturing margin pools in high-rise commercial towers where glazing ratios exceed 60%. Crystalline silicon technology leads volume shipments, while thin-film alternatives are gaining traction in renovation projects where weight restrictions on existing structures prohibit heavier modules.
The EU Green Deal and F-Gas Regulation are tightening embodied carbon standards for construction materials, directly elevating BIPV eligibility in public procurement across Germany, France, and the Netherlands. The EPA's ENERGY STAR certification and state-level stretch codes in California and New York are mandating renewable-ready construction, expanding addressable market scope for new installation types. China's dual carbon goals and GB standards for near-zero energy buildings are accelerating domestic demand while reshaping export supply dynamics. Stakeholders must monitor how evolving grid interconnection tariffs affect project economics in jurisdictions where distributed generation compensation structures remain unsettled.
Market Dynamics
Net-zero building mandates across Germany, China, and the United States are compressing installation timelines and forcing developers to embed photovoltaic generation into structural envelopes rather than retrofitting later.
Growth Catalysts
- EU Green Deal:Near-zero energy building standards in Germany, France, and the Netherlands mandate on-site renewable generation, elevating BIPV eligibility in public procurement.
- Commercial real estate:Institutional developers facing tightening embodied carbon regulations are accelerating facade and roof-integrated solar to meet portfolio decarbonization targets.
- Thin-film advances:Cadmium telluride and copper indium gallium selenide chemistries are reducing module weight for renovation projects where structural load limits prohibit crystalline silicon.
Market Restraints
- Silicon price volatility:Polysilicon supply concentration in Xinjiang and Inner Mongolia creates input cost instability for crystalline module producers.
- Skilled labor scarcity:Certified BIPV installation capacity remains concentrated in Germany and California, constraining deployment velocity elsewhere.
- Grid interconnection uncertainty:Unsettled distributed generation compensation structures in multiple US states and Chinese provinces delay project financing.
Strategic Opportunities
- Heritage building retrofits:Transparent photovoltaic glass addresses aesthetic constraints in protected architectural districts where conventional panels face rejection.
- India's PLI scheme:Domestic manufacturing incentives for solar modules are creating localized supply capacity for commercial tower construction in Mumbai and Bangalore.
- California stretch codes:Renewable-ready construction mandates in Title 24 are expanding addressable scope for residential solar roof installations.
Industry Challenges
- Building-physics integration:Thermal bridging, moisture management, and fire safety certification for envelope-integrated systems extend engineering timelines.
- Architect-consultant coordination:Misaligned incentives between facade engineers, electrical contractors, and project architects generate change-order friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Integrated Photovoltaic (BIPV) Market |
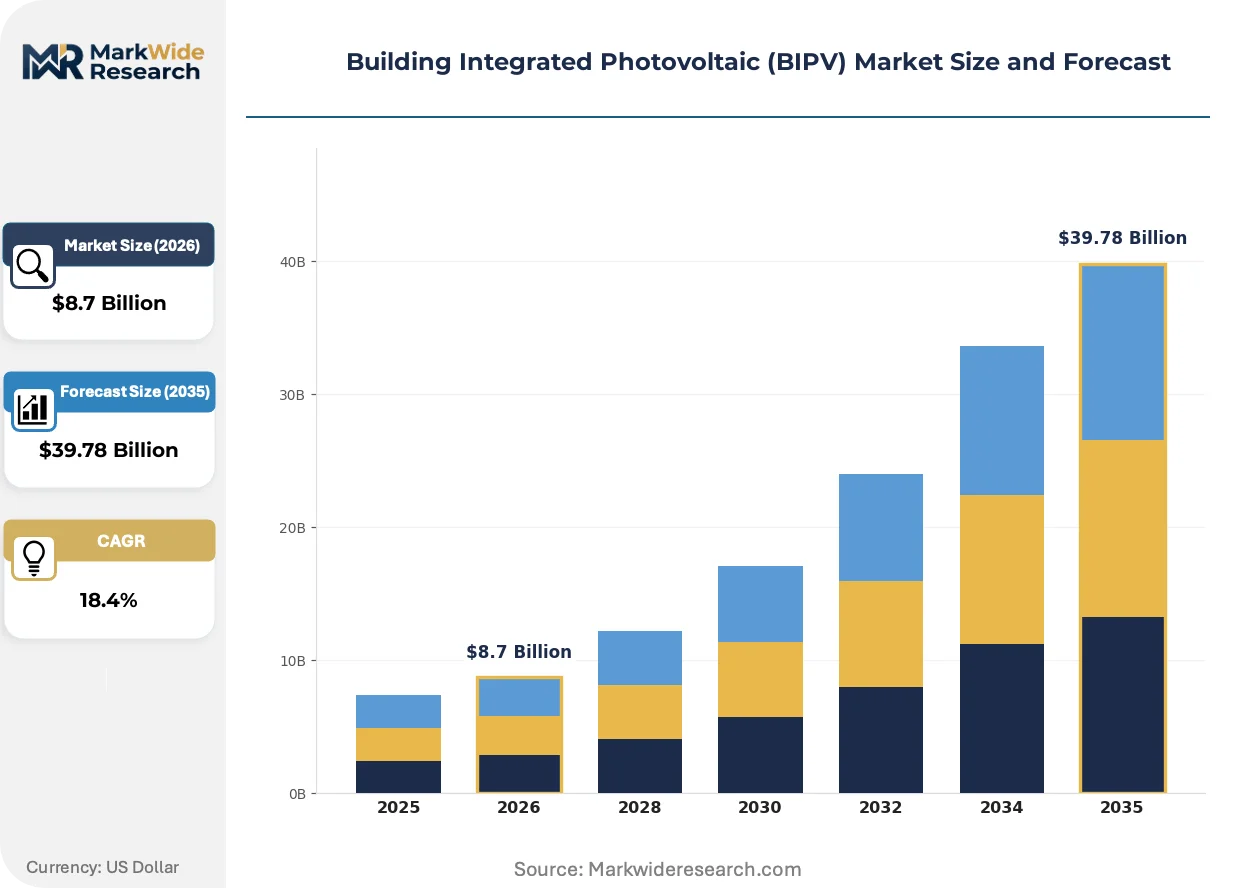
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Facades, Solar Roofs, Building-Integrated Modules, Transparent PV Installation Type: New Construction, Renovation, Retrofit, Upgrades End User: Residential, Commercial, Industrial, Institutional Technology: Thin-Film, Crystalline Silicon, BIPV Glass, Organic Photovoltaics |
| Companies Covered | First Solar, Canadian Solar, Tesla, LONGi Green Energy Technology, Trina Solar, AGC Inc., Onyx Solar, Solaria Corporation, Hanergy Holding Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Integrated Photovoltaic (BIPV) Market Strategic Shifts
Product architecture is shifting from bolt-on solar attachments to structural envelope materials that perform simultaneous generation and weatherproofing functions. This convergence is compressing traditional trade boundaries.
Perovskite tandem stacks layered atop crystalline silicon are supplanting single-junction architectures in premium facade applications. High-rise commercial developers in Shanghai and Singapore are piloting these configurations for glazing-dominant towers. The technology is supplanting conventional BIPV economics by pushing conversion efficiency toward 30% while maintaining translucency.
The F-Gas Regulation is tightening embodied carbon standards for fluorinated greenhouse gases used in module manufacturing and HVAC integration. European module suppliers are reformulating encapsulant chemistries to maintain CE marking compliance. Crystalline silicon producers with German and Dutch manufacturing footprints are most exposed to reformulation costs.
Design-build contracts are consolidating procurement authority for envelope and electrical scopes under single entities. General contractors in California and Texas are absorbing solar integration risk that architects previously managed separately. This concentration is most visible in commercial ground-up development where guaranteed maximum price structures dominate.
Building Integrated Photovoltaic (BIPV) Market Segmentation
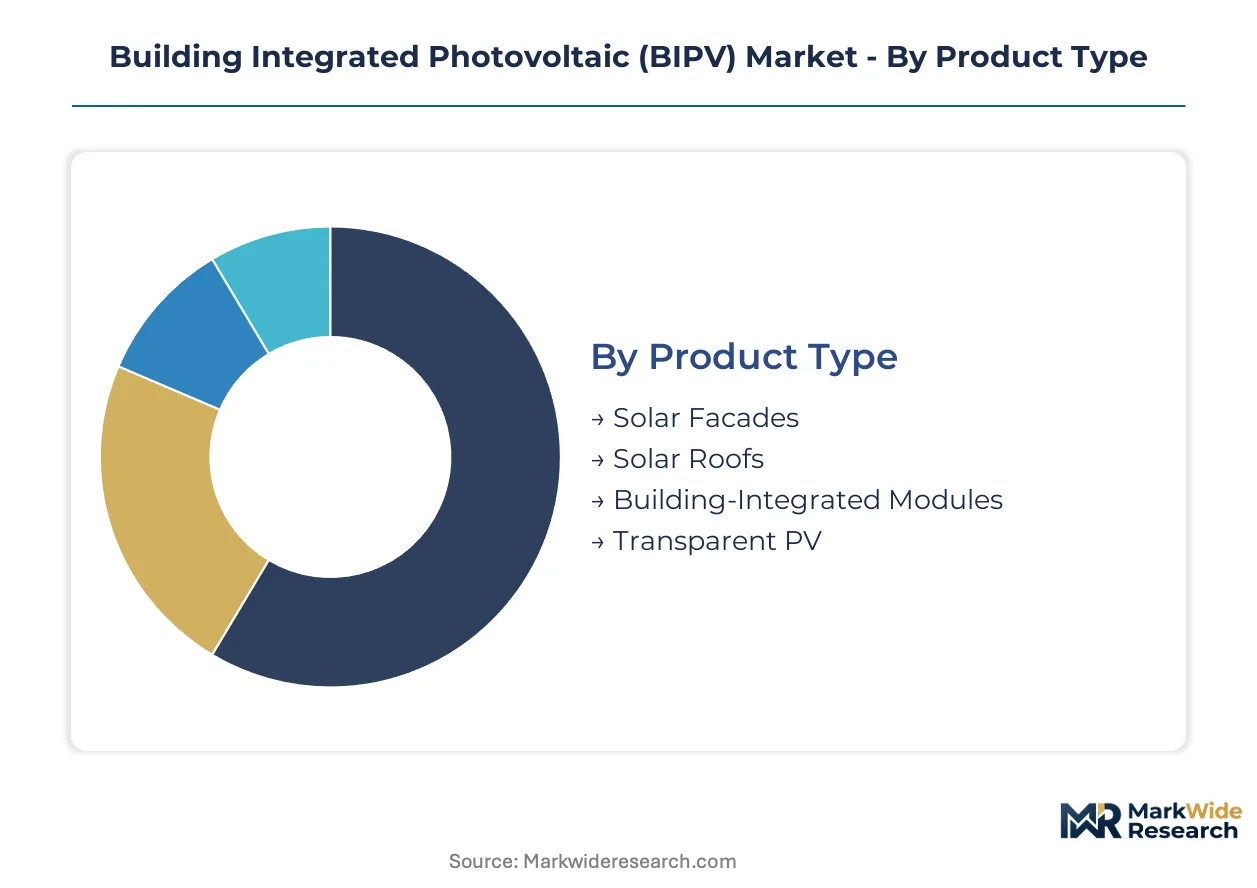
BIPV procurement channels diverge sharply by segment: solar roofs flow through residential roofing contractors, while transparent PV and facade systems route through architectural glazing specialists. Understanding these channel dynamics prevents misallocation of sales resources and partnership investments.
Product Type:
Channel architecture dictates margin capture: roofing distributors handle high-volume solar roof shipments, while facade integrators and glass fabricators control transparent PV and solar facade flows to commercial developers.
- Solar Roofs:These systems replace conventional roofing materials with photovoltaic tiles or shingles that serve simultaneous weatherproofing and generation functions. Residential developers in California and Texas are accelerating procurement through Tesla's certified installer network to meet Title 24 stretch code compliance. Solar roofs dominate installed base. Transparent PV is where expansion concentrates.
- Solar Facades:Vertical envelope-integrated systems mount photovoltaic elements directly onto building exteriors, typically achieving 15-20% conversion efficiency in crystalline configurations. Commercial real estate portfolios in Germany and the Netherlands are deploying these through specialized facade engineering firms to satisfy EU Green Deal embodied carbon mandates.
- Transparent PV:Photovoltaic glass maintains visible light transmission while generating electricity, enabling glazing-dominant towers to meet renewable generation requirements without sacrificing daylighting. Onyx Solar supplies heritage districts in Spain and Italy where aesthetic constraints prohibit conventional panels.
- Building-Integrated Modules:Custom-fabricated panels designed as structural envelope elements rather than surface attachments, requiring coordination between electrical contractors and facade engineers.
Solar roofs command volume leadership. Transparent PV and solar facades are climbing the fastest as commercial towers pursue net-zero certification.
Installation Type:
Cost tier separation is pronounced: new construction embeds BIPV into structural budgets at $15-25 per watt installed, while renovations and retrofits face 40-60% premiums due to structural engineering and grid interconnection complexities.
- New Construction:BIPV specified during design phase achieves lowest installed cost through integrated procurement of envelope and electrical scopes. Design-build contractors in Texas and Florida are absorbing integration risk under guaranteed maximum price structures.
- Renovation:Existing structures with adequate load-bearing capacity receive BIPV upgrades, typically triggered by roof replacement cycles or facade recladding mandates. Thin-film technology is displacing crystalline silicon here due to weight restrictions on aging structures.
- Retrofit:Deep energy retrofits combine BIPV with envelope insulation and HVAC replacement, common in Germany's building stock modernization programs. New construction dominates installed base. Renovation is where expansion concentrates.
- Upgrades:Incremental capacity additions to existing BIPV systems, typically triggered by inverter replacement or subsidy program changes.
New construction captures the majority of current deployment. Renovation and retrofit activity is accelerating as net-zero deadlines compress for existing building stock.
End User:
Customer type determines specification authority: institutional buyers prioritize 25-year performance warranties and fire safety certification, while residential purchasers respond to financing availability and installer brand recognition.
- Commercial:Office towers, retail centers, and hospitality assets deploy facade-integrated and rooftop systems to reduce peak demand charges and meet portfolio decarbonization targets. Institutional investors in Singapore and Shanghai are piloting perovskite tandem configurations for glazing-dominant properties.
- Residential:Single-family and multi-family housing specifies solar roofs through roofing contractors and energy division channels. Tesla's direct sales model in California and Texas is reshaping procurement patterns for premium segments.
- Industrial:Manufacturing facilities and warehouses with large roof areas favor building-integrated modules for structural simplicity. Commercial leads installed base. Residential is where expansion concentrates.
- Institutional:Schools, hospitals, and government buildings require extended warranty terms and public procurement compliance, elongating sales cycles but ensuring specification longevity.
Commercial real estate anchors current revenue. Residential penetration is expanding most quickly as net-zero mandates reach single-family construction codes.
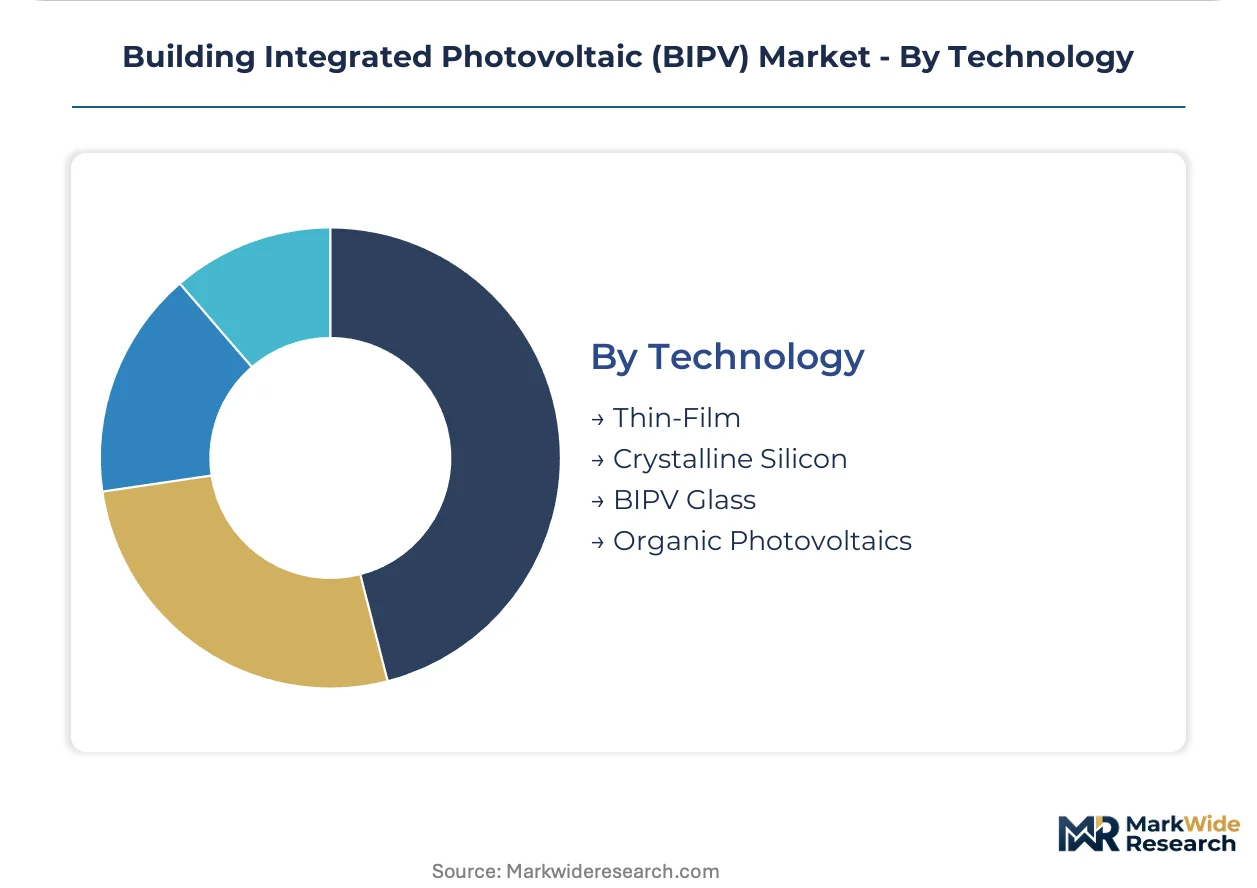
Technology:
Supply concentration shapes availability: crystalline silicon capacity clusters in China and Southeast Asia, while thin-film production concentrates in specific facilities with specialized equipment.
- Crystalline Silicon:Mature photovoltaic technology achieving 20-22% conversion efficiency in standard configurations, manufactured through established wafer-cell-module supply chains. LONGi Green Energy Technology dominates supply for East Asian commercial facade projects. Crystalline silicon dominates installed base. Thin-film is where expansion concentrates.
- Thin-Film:Cadmium telluride and copper indium gallium selenide chemistries reduce module weight by 40-60% compared to crystalline alternatives, enabling deployment on load-limited existing structures. First Solar's cadmium telluride technology is penetrating European renovation markets where structural constraints prohibit heavier modules.
- BIPV Glass:Photovoltaic elements laminated within architectural glazing, requiring specialized fabrication equipment and tempering capabilities. Supply concentrates in glass manufacturing regions with established architectural processing infrastructure.
- Organic Photovoltaics:Polymer-based thin-film technology offering flexibility and color customization, currently limited to niche applications in building-integrated design features and indoor energy harvesting.
Crystalline silicon leads volume shipments. Thin-film alternatives are gaining share fastest in renovation applications where weight restrictions apply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through GB standards for near-zero energy buildings, compressing project timelines across the Yangtze River Delta while reshaping export supply dynamics for crystalline silicon modules.
China
Dual carbon goals and GB standards mandate on-site renewable generation in new commercial construction. The Ministry of Ecology and Environment enforces embodied carbon thresholds that elevate BIPV eligibility in public tenders. Shanghai and Shenzhen clusters concentrate perovskite tandem pilot installations for glazing-dominant towers.
Germany
Commercial real estate portfolios deploy facade-integrated systems to satisfy EU Green Deal mandates and F-Gas Regulation compliance. The KBA and federal building codes enforce net-zero deadlines that compress renovation timelines. The Rhine-Ruhr and Bavarian industrial corridors anchor certified installer capacity that unwinds deployment bottlenecks.
United States
California and New York stretch codes mandate renewable-ready construction for institutional and residential assets. The EPA's ENERGY STAR certification and state-level regulators expand addressable scope for solar roof specifications. Texas and Florida design-build contractors absorb envelope-electrical integration risk under guaranteed maximum price structures.
India
Domestic manufacturing incentives under the PLI scheme localize crystalline silicon supply for commercial tower construction in Mumbai and Bangalore. The Central Electricity Authority and BIS standards reshape procurement patterns for net-zero office assets. Maharashtra and Karnataka sub-regions concentrate facade engineering capacity for high-rise development.
Netherlands
EU Green Deal near-zero energy building standards mandate BIPV in public procurement across Randstad commercial districts. The national building code regulator enforces embodied carbon limits that accelerate transparent PV adoption. The Eindhoven region clusters glass fabrication infrastructure for architectural photovoltaic lamination.
Building Integrated Photovoltaic (BIPV) Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the BIPV value chain. Crystalline silicon specialists dominate volume shipments through established wafer-cell-module supply chains, while thin-film and transparent glass fabricators occupy premium positioning in renovation and heritage applications. Three archetypes structure competition: integrated energy conglomerates with direct sales channels, specialized facade engineering firms with architect relationships, and glass manufacturers with architectural processing capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves, particularly around certified installer network development and perovskite tandem commercialization.
Among North American energy-division operators, Tesla exemplifies the integrated archetype through direct residential channel control in California and Texas. LONGi Green Energy Technology anchors crystalline silicon supply positioning for East Asian commercial facade projects. Onyx Solar occupies the transparent photovoltaic specialist tier, serving heritage building retrofits where aesthetic constraints limit conventional panel specification. These three represent distinct competitive vectors: channel integration, manufacturing scale, and architectural specialization.
| Leading Market Players |
|---|
| First Solar |
| Canadian Solar |
| Tesla |
| LONGi Green Energy Technology |
| Trina Solar |
| AGC Inc. |
| Onyx Solar |
| Solaria Corporation |
| Hanergy Holding Group |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between crystalline silicon producers and German commercial developers lock in polysilicon supply access while anchoring module price visibility across volatile input cycles. These arrangements insulate facade engineering firms from Xinjiang supply disruptions while compressing procurement timelines for net-zero compliance deadlines.
Pricing Analysis
Geographic price spreads between German certified installations and Chinese domestic projects reflect labor scarcity premiums and F-Gas Regulation compliance costs. Three-tier pricing structure across premium transparent PV, standard crystalline facades, and economy thin-film retrofits segments buyer archetypes. Cost compression in economy tiers is intensifying because Indian PLI scheme manufacturing scale is flooding Asian supply channels. Residential roofing contractors in California exhibit highest price sensitivity, while heritage building developers in Spain accept premium positioning for aesthetic compliance.
Supply Chain Analysis
Inventory lead times for architectural photovoltaic glass extend 14-20 weeks due to tempering equipment bottlenecks in Eindhoven and Shanghai fabrication clusters. Module assembly draws from polysilicon feedstock concentrated in Xinjiang and Inner Mongolia, with cadmium telluride thin-film sourcing anchored in Ohio and Malaysia. Single-source vulnerability in encapsulant chemistries exposes European suppliers to REACH reformulation delays. Distribution runs through roofing distributors for solar roofs and facade integrators for transparent PV, with design-build contractors consolidating procurement authority in Texas and Florida commercial development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
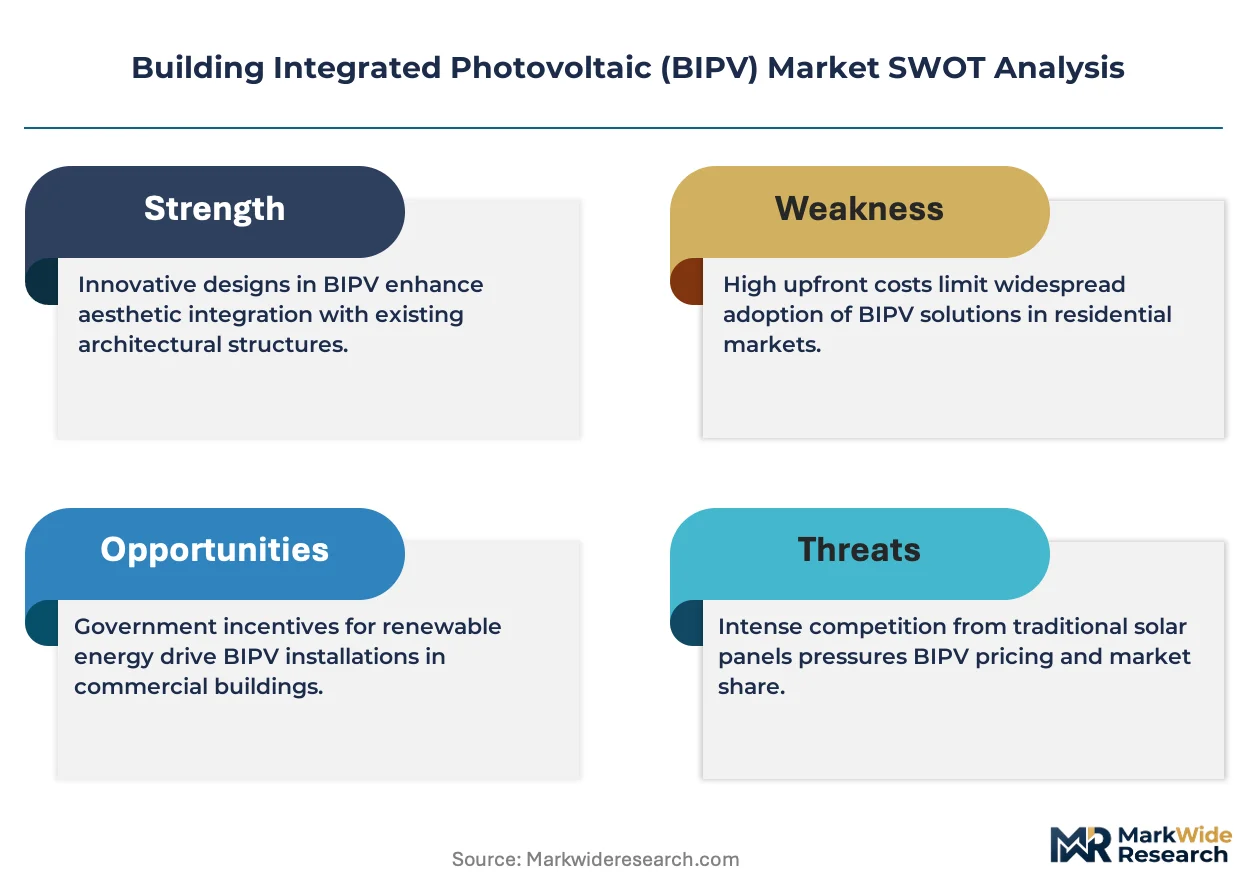
Building Integrated Photovoltaic incumbents face substitution pressure from standalone rooftop solar plus battery configurations that undercut envelope-integrated economics on retrofit projects. Defending position requires strategic moves that protect specification authority in new construction channels.
For Market Incumbents: Shield specification control by embedding crystalline silicon modules into design-build contracts before electrical contractors bid standalone alternatives. Deepen backward integration into polysilicon refining to offset Xinjiang supply volatility. Prioritize CE marking and UL fire-safety certification investments that disqualify thin-film substitutes in German and Dutch public procurement.
For New Entrants and Emerging Players: Differentiate on perovskite tandem efficiency for glazing-dominant towers in Singapore and Shanghai where 30% conversion thresholds command premium positioning. Target India's renovation segment where PLI scheme cost advantages and structural load limits on aging Mumbai commercial stock create penetrable white space. Pursue architect-direct sales models that bypass consolidated roofing distributor channels.
For Investors and Strategic Acquirers: Capital is best deployed toward transparent PV specialists with heritage district relationships and glass fabrication capabilities that resist commoditization. Long-term viability hinges on regulatory durability of net-zero mandates rather than technology cost curves alone. Monitor grid interconnection tariff settlements in California and Chinese provinces as inflection indicators for distributed generation project finance velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Tandem Commercialization | Shanghai and Singapore pilots validate 30% efficiency for glazing-dominant towers. |
| Certified Installer Network Expansion | Rhine-Ruhr and Bavarian labor pools unwind European deployment bottlenecks. |
| Encapsulant Chemistry Reformulation | F-Gas Regulation compliance maintains CE marking for Dutch and German supply. |
| Design-Build Contract Integration | Texas and Florida contractors absorb envelope-electrical risk under fixed-price structures. |
| Domestic Manufacturing Scale-Up | India PLI scheme localizes module supply for Mumbai and Bangalore tower construction. |
Study Parameters
The analysis maps crystalline silicon, thin-film, transparent PV, and organic photovoltaic sub-sectors, each validated through facade engineers, electrical contractors, architectural glazing specialists, and commercial real estate developers. Primary interviews with EPC contractors and project finance officers combined with secondary validation from EIA project databases, IEA renewable energy reports, FERC interconnection filings, and EU Green Deal implementation trackers. Bottom-up installation volume estimates triangulated against top-down construction spending forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology type, installation category, end-user segment, and regional regulatory cluster dimensions. CAGRs derived from segmented growth rate reconciliation with macroeconomic construction indicators. Industry-specific inputs included net-zero mandate implementation timelines and grid interconnection queue depths.
The analysis sits within stated boundaries; outcomes outside sustained policy support for distributed generation compensation would require recalibration. Forecasts reflect assumptions around polysilicon supply stability and certified labor availability. Silicon price volatility and grid tariff uncertainty constitute primary revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Thin-Film Photovoltaic Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market