
 Small Home Appliances Market | 2026-2036
Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Small Home Appliances Market Outlook
The gap between premium connected kitchen ecosystems and basic single-function appliances is expanding at the category level. Groupe SEB leverages its European manufacturing footprint to dominate the high-end coffee equipment segment. Midea Group Co., Ltd. anchors the mass-market tier through cost-engineered production at scale in Guangdong province. Dyson Ltd. differentiates on motor technology and air filtration integration across its small appliance portfolio.
Small home appliances comprise electrically powered countertop and portable devices designed for domestic food preparation, climate control, cleaning, and personal care, typically operating below 2,000 watts and manufactured through injection-molded thermoplastic housings with stamped-metal heating elements or brushless DC motors. Their primary commercial purpose is to automate repetitive household tasks within space-constrained residential environments. The coffee makers segment leads absolute revenue due to ritual-driven replacement cycles and pod-system lock-in effects, while smart appliances represent the fastest-expanding technology category as Wi-Fi modules and voice-protocol integration become standard bill-of-material items. Energy-efficient models command widening margin pools as utility rebate programs and EU Ecodesign Directive compliance costs filter through to retail pricing.
The EU Ecodesign Directive and REACH chemical restrictions shape material selection and recyclability requirements for products sold in Europe, while the US DOE appliance standards program mandates minimum energy consumption thresholds that R&D teams must engineer around. China's GB standards and SAMR certification requirements govern domestic market access and increasingly influence export specifications through manufacturing concentration. Stakeholders must monitor how fragmented national efficiency regimes evolve and whether harmonization pressure from the WTO TBT committee accelerates design standardization across major economies.
Market Dynamics
Countertop device electrification in compact urban dwellings is compressing replacement cycles and forcing manufacturers to consolidate multiple functions into single footprints. The EU Ecodesign Directive's escalating efficiency tiers are accelerating R&D spend toward brushless DC motor architectures and thermoplastic housing redesigns.
Growth Catalysts
- Appliance Electrification in Tier-Two Chinese Cities:Rising disposable incomes in cities like Chengdu and Xi'an are converting gas-dependent households to electric countertop devices, expanding addressable demand for multi-function food preparation units.
- EU Ecodesign Directive Compliance Mandates:Minimum energy consumption thresholds for heating elements and standby power are creating replacement pull for compliant models across Germany, France, and Italy.
- Wi-Fi Module Integration:Voice-protocol compatibility and app-based recipe programming are expanding into mid-market price bands, enabling data-driven consumables replenishment revenue streams.
Market Restraints
- Neodymium Magnet Supply Concentration:Brushless DC motor production depends on rare earth processing concentrated in China's Inner Mongolia region, exposing cost volatility and export quota risks.
- REACH Chemical Restrictions:ECHA's expanding list of restricted substances in thermoplastic housings and heating element coatings is extending material qualification timelines by 8-14 months for European market entry.
- Manual Food Preparation Substitution:Cultural persistence of traditional cooking methods in South Asian and Middle Eastern markets limits penetration of automated countertop devices despite electrification infrastructure.
Strategic Opportunities
- Underpenetrated Indian Urban Households:BIS certification alignment and cost-engineered production for sub-$50 price points can capture first-time appliance buyers in Mumbai and Bangalore's informal housing sectors.
- Air Filtration-Climate Control Convergence:Integration of HEPA filtration with portable heating-cooling units addresses post-pandemic indoor air quality concerns in Japanese and South Korean apartment markets.
- US DOE Appliance Standards Rebates:Utility-sponsored efficiency incentive programs in California and New York are creating margin pools for manufacturers who pre-certify products above minimum thresholds.
Industry Challenges
- Embedded Systems Firmware Talent Scarcity:Wi-Fi module integration and voice-protocol compliance require software engineering capabilities that appliance OEMs lack, forcing reliance on third-party module suppliers.
- Multi-Jurisdiction Certification Parallelism:Simultaneous pursuit of EU CE marking, US FCC Part 15, and China SAMR approvals fragments testing budgets and compresses product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Home Appliances Market |
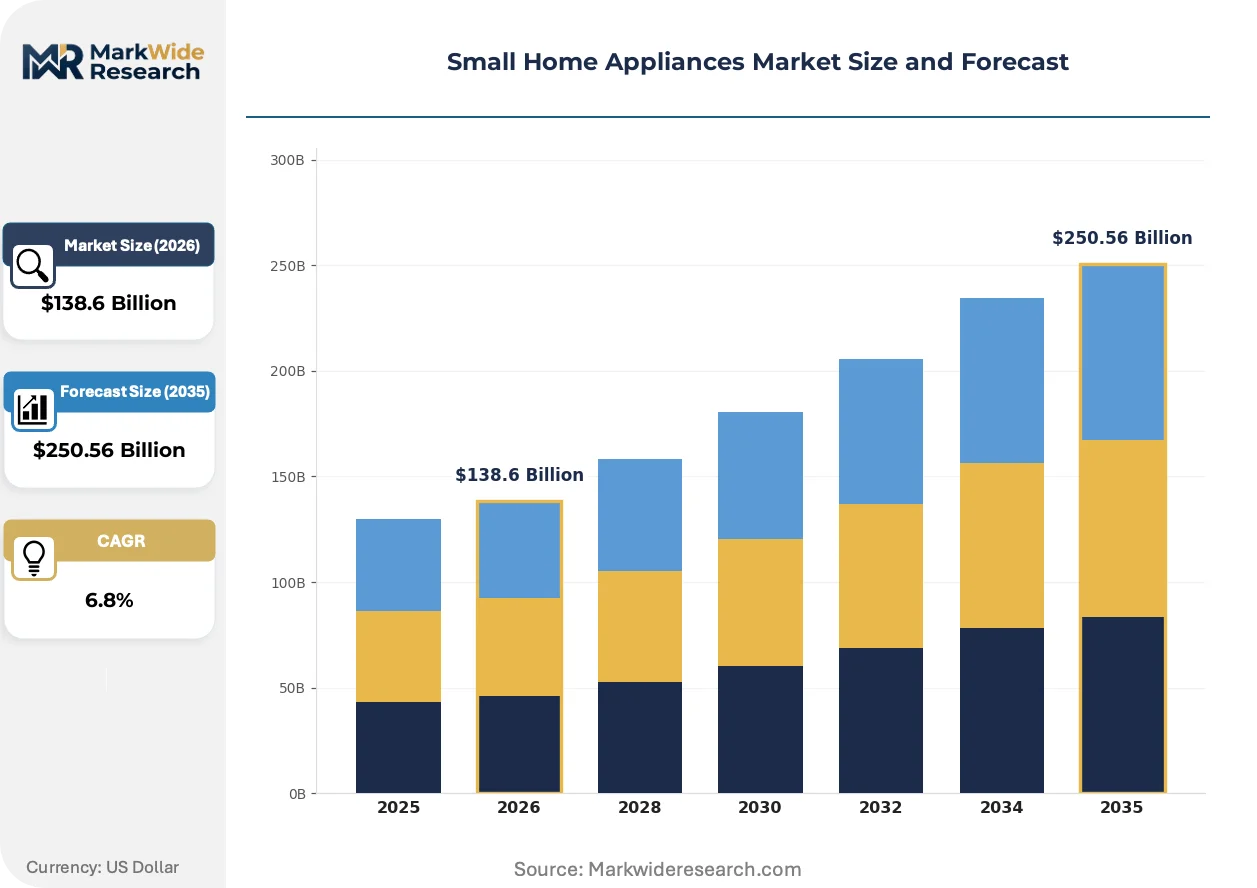
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coffee Makers, Toasters, Blenders, Microwave Ovens Technology: Smart Appliances, Traditional Appliances, Energy-Efficient Models, Manual Controls End User: Residential Users, Kitchen Use, Office Settings, Hospitality Sector Distribution Channel: Online Retailers, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Whirlpool Corporation, Groupe SEB, Koninklijke Philips N.V., SharkNinja Operating LLC, Dyson Ltd., Haier Smart Home Co., Ltd., LG Electronics Inc., Samsung Electronics Co., Ltd., Midea Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Home Appliances Market Strategic Shifts
Electrification of domestic tasks is converging with connected-device architectures, reshaping how manufacturers capture lifetime value beyond initial hardware sales. Material science advances and regulatory efficiency floors are accelerating motor and heating element redesign cycles.
Brushless DC motor technology is expanding into countertop appliance categories previously dominated by universal motors. Compact permanent-magnet designs enable variable speed control in food processors and coffee grinders, reducing noise profiles and energy draw. Premium kitchen ecosystem builders are adopting these motors to justify tiered pricing differentiation against basic single-function alternatives.
The EU Ecodesign Directive's 2027 efficiency tier escalation is forcing heating element redesigns across coffee maker and toaster oven portfolios. Manufacturers must engineer stamped-metal element geometries that meet standby power limits while maintaining thermal response times. German and Italian brands with captive metal-stamping capabilities are absorbing compliance costs faster than outsourced competitors.
Urban households in Japan and South Korea are unbundling after-sales service expectations from hardware purchases. Buyers now expect app-based troubleshooting and consumables subscription models rather than traditional warranty depot repair. This shift compresses distributor margins while expanding direct-to-manufacturer data relationships that inform next-generation feature prioritization.
Small Home Appliances Market Segmentation
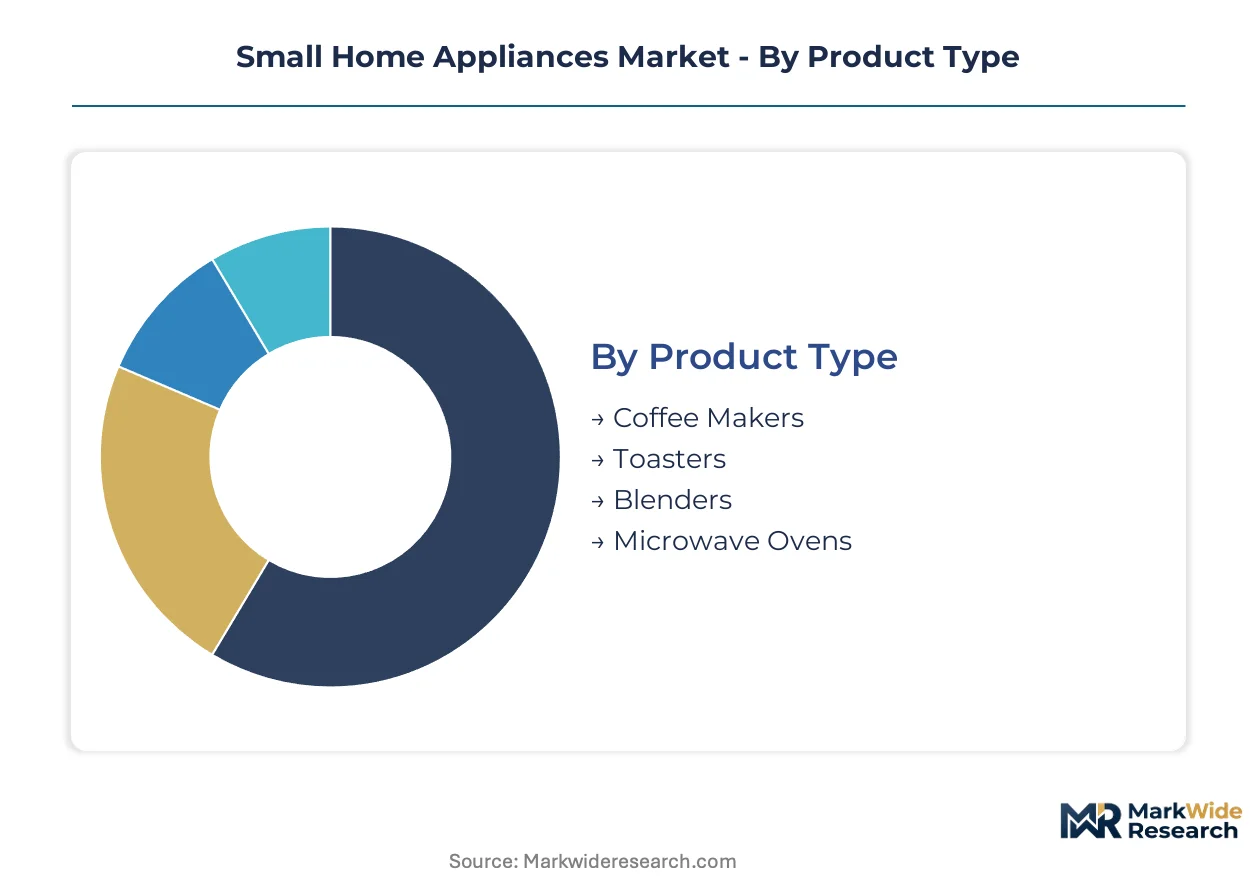
Segmentation in small home appliances reveals how electrification patterns, connectivity premiums, and channel economics split purchasing behavior across household types. Manufacturers align R&D budgets and certification strategies to the specific performance thresholds and price elasticity of each buyer cluster.
Product Type:
Purchase frequency and replacement cycles diverge sharply between ritual-driven beverage preparation and occasional-use cooking aids.
- Coffee Makers:Pod-system architectures and espresso pressure mechanics dominate countertop placement in compact urban dwellings. German and Italian households drive replacement demand as EU Ecodesign Directive standby power limits retire older heating element designs.
- Toasters:Stamped-metal element geometries and thermoplastic housing configurations serve rapid breakfast preparation cycles. Japanese apartment dwellers favor narrow-footprint two-slice units that minimize counter space in galley kitchens.
- Blenders:Variable-speed brushless DC motor integration enables nutrient extraction programming for health-conscious residential users.
- Microwave Ovens:Magnetron efficiency tiers and inverter control modules segment price bands across mass-market and premium kitchen renovations.
Volume sits with coffee makers; growth tilts toward blenders as motor technology costs decline.
Technology:
Margin capture potential separates connectivity-enabled ecosystems from compliance-driven efficiency upgrades.
- Smart Appliances:Wi-Fi module integration and voice-protocol compatibility transform hardware into data collection nodes. South Korean metropolitan households adopt app-based recipe programming and consumables replenishment subscriptions fastest.
- Traditional Appliances:Electromechanical controls and universal motor architectures serve price-sensitive first-time buyers in tier-two Chinese cities.
- Energy-Efficient Models:Brushless DC motors and optimized heating element geometries meet US DOE appliance standards and EU Ecodesign Directive tiers for utility rebate eligibility.
- Manual Controls:Rotary dial interfaces and basic safety thermostats dominate sub-$50 entry points in Indian informal housing sectors.
Revenue concentrates in smart appliances; expansion accelerates most quickly in energy-efficient models as regulatory floors rise.
End User:
Usage intensity and durability expectations reshape material specifications and warranty terms across deployment environments.
- Residential Users:Multi-function countertop devices in compact dwellings demand space-efficient footprints and modular attachment systems. French and Spanish apartment conversions from gas to electric cooking expand addressable demand for single-unit food preparation.
- Kitchen Use:Dedicated food preparation zones in open-plan layouts require aesthetic coordination with cabinetry and ventilation systems.
- Office Settings:High-cycle durability specifications and vandal-resistant interfaces serve break-room deployment with minimal maintenance intervals.
- Hospitality Sector:Commercial-grade safety certifications and rapid recovery heating elements support boutique hotel breakfast service operations.
Unit economics favor residential users; margin expansion targets hospitality sector procurement with outcome-based service contracts.
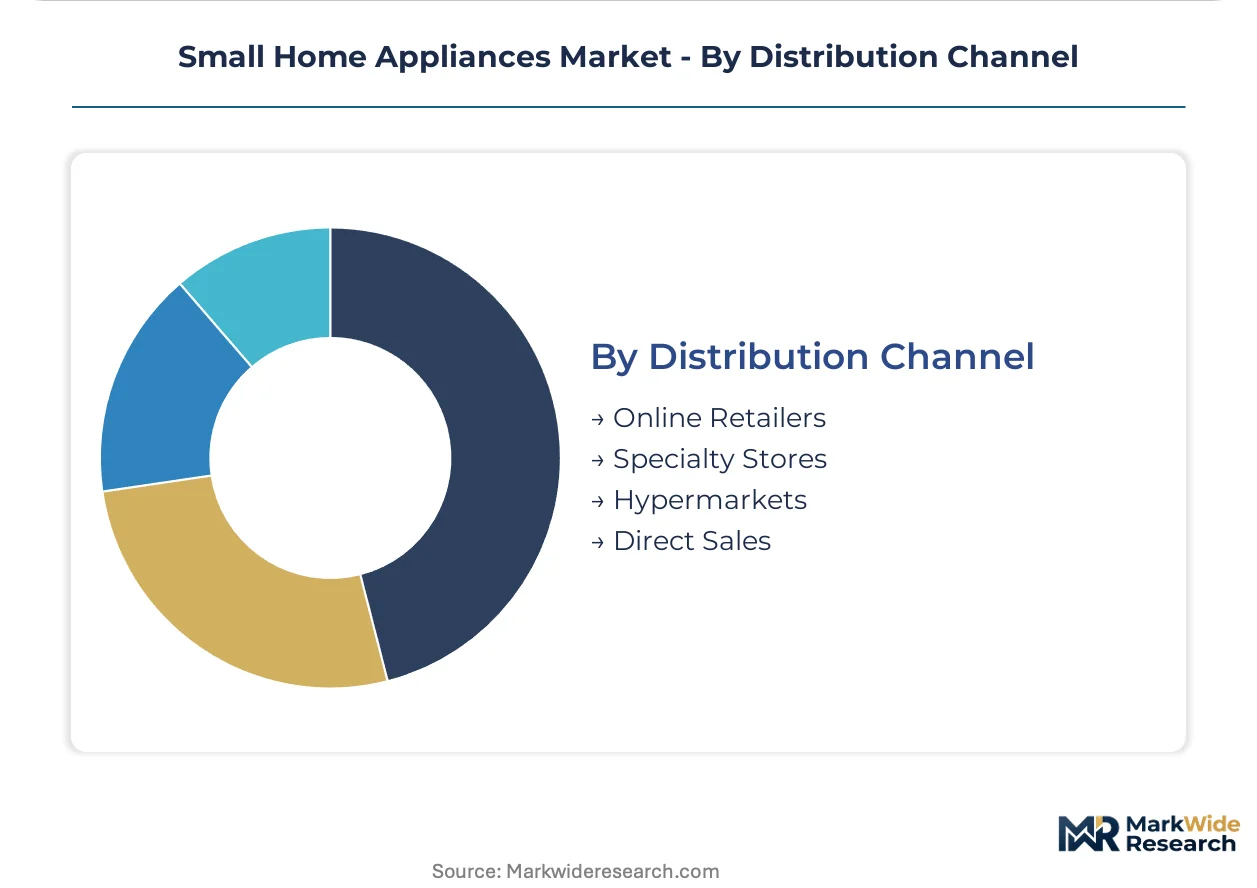
Distribution Channel:
Customer acquisition costs and post-sale data access determine channel prioritization for connected product portfolios.
- Online Retailers:Platform algorithms and review aggregation drive discovery for Wi-Fi-enabled appliances with app ecosystem dependencies. Amazon and JD.com capture disproportionate smart appliance volume through bundled installation services.
- Specialty Stores:Tactile demonstration and staff consultation justify premium pricing for espresso equipment and high-performance blending systems.
- Hypermarkets:Seasonal promotional calendars and impulse placement economics serve replacement purchases of toasters and basic microwave ovens.
- Direct Sales:Manufacturer-controlled data relationships and subscription attach rates attract Dyson and premium ecosystem builders bypassing retail margin stacking.
Transaction volume flows through online retailers; direct sales channels gain share fastest as firmware update dependencies deepen manufacturer-customer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors manufacturing concentration for small home appliances, with Shenzhen and Foshan hosting vertically integrated production clusters that supply both domestic electrification and export demand across multiple regulatory jurisdictions.
China
Tier-two cities including Chengdu and Xi'an are converting gas-dependent households to electric countertop devices as disposable incomes rise. SAMR certification requirements under GB standards govern domestic market access and increasingly shape export specifications. The Pearl River Delta manufacturing corridor in Guangdong province concentrates injection-molded thermoplastic housing production and brushless DC motor assembly for global supply.
United States
Utility-sponsored efficiency incentive programs in California and New York are creating margin pools for manufacturers certifying products above US DOE appliance standards minimum thresholds. The FCC Part 15 framework regulates Wi-Fi module integration for smart appliance connectivity. Chicago and Dallas metropolitan areas serve as distribution hubs for Midwest and Southwest residential replacement cycles.
Germany
EU Ecodesign Directive compliance mandates for standby power limits and heating element efficiency are accelerating replacement demand in German households. The country's national regulator enforces REACH chemical restrictions on thermoplastic housings through ECHA guidelines. The Rhine-Ruhr industrial region hosts metal-stamping capabilities for coffee maker and toaster oven heating element production.
Japan
Post-pandemic indoor air quality concerns in Tokyo and Osaka apartment markets are driving convergence of HEPA filtration with portable climate control units. METI efficiency labeling programs segment retail price bands for energy-conscious consumers. The Kansai manufacturing cluster around Osaka specializes in compact motor designs for space-constrained urban dwellings.
India
First-time appliance buyers in Mumbai and Bangalore's informal housing sectors present expansion opportunities for cost-engineered products below $50 price points. BIS certification alignment remains mandatory for domestic market entry. The Maharashtra industrial corridor near Pune is developing component sourcing capabilities for entry-level food preparation devices.
Small Home Appliances Market Competitive Environment
Premium-margin players sit above commodity-margin players across motor technology and connectivity integration tiers, with the market structure fragmenting between ecosystem builders and single-function specialists. Three strategic archetypes dominate: European heritage brands with captive manufacturing, Chinese scale producers with cost-engineered supply chains, and technology-led specialists with proprietary motor or filtration IP. Competitive moves concentrate on Wi-Fi module integration partnerships and brushless DC motor supply security through rare earth processing relationships.
Within the heritage-brand tier, Groupe SEB and Koninklijke Philips N.V. exemplify European manufacturing footprint strategies, while Midea Group Co., Ltd. anchors the scale-driven archetype through Guangdong province production concentration. Dyson Ltd. occupies a technology-specialist position built on motor and air filtration integration across product portfolios.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Groupe SEB |
| Koninklijke Philips N.V. |
| SharkNinja Operating LLC |
| Dyson Ltd. |
| Haier Smart Home Co., Ltd. |
| LG Electronics Inc. |
| Samsung Electronics Co., Ltd. |
| Midea Group Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive motor manufacturing in Guangdong province anchors both supply security and pricing power for tier-one producers, while outsourced competitors absorb margin compression from rare earth volatility and multi-jurisdiction certification costs.
Pricing Analysis
Value-based pricing anchored to energy-efficiency outcomes separates premium Wi-Fi-enabled ecosystems from basic single-function units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, brushless DC motor integration, and after-sales subscription bundling. Cost compression in the economy tier intensifies because Midea Group and Haier Smart Home leverage Guangdong production scale against European heritage brands. First-time buyers in Indian informal housing sectors exhibit highest price sensitivity; hospitality procurement teams show lowest sensitivity when outcome-based service contracts attach.
Supply Chain Analysis
Single-source vulnerability sits with rare earth processing concentrated in China's Inner Mongolia region, where export quota decisions ripple through brushless DC motor costs. Manufacturing draws from China, Vietnam, and Mexico for injection-molded thermoplastic housings, stamped-metal heating elements, and final assembly. Neodymium magnet supply concentration creates tariff exposure for US-bound shipments. Distribution runs through vertically integrated Pearl River Delta clusters feeding both JD.com fulfillment centers and European retail depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EU Ecodesign Directive compliance costs and firmware talent scarcity force weaker single-function specialists toward acquisition or exit.
For Market Incumbents: Deepen backward integration into rare earth magnet supply relationships to insulate brushless DC motor costs from export quota volatility. Consolidate R&D spend on voice-protocol firmware capabilities before third-party module suppliers capture connectivity margin pools. Threat substitution from Chinese scale producers with captive Guangdong manufacturing demands faster certification parallelism across EU CE marking and US FCC Part 15 frameworks. For New Entrants and Emerging Players: Begin with cost-engineered air filtration-climate control convergence units for Japanese and South Korean apartment markets where post-pandemic indoor air quality concerns outpace incumbent product pipelines. White-space penetration concentrates in Indian urban informal housing sectors below $50 price points with BIS-certified manual control interfaces. Direct-to-manufacturer channel control enables subscription attach for consumables replenishment revenue. For Investors and Strategic Acquirers: Exit pathways concentrate in technology-specialist acquisitions by ecosystem builders seeking proprietary motor IP or HEPA filtration integration capabilities. Five-to-ten year viability favors targets with captive metal-stamping for heating element compliance and established SAMR certification for China market access. Signal to monitor: utility rebate program expansion in California and New York that accelerates replacement pull for above-threshold efficiency models.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Supply Agreement | Brushless DC motor producers secure Inner Mongolia processing quotas ahead of export restrictions. |
| Wi-Fi Module Partnership | Appliance OEMs bridge firmware talent gaps through third-party voice-protocol integration specialists. |
| Multi-Jurisdiction Certification | Parallel CE marking and FCC Part 15 approvals compress launch windows for connected product portfolios. |
| Direct-to-Consumer Launch | Manufacturers bypass retail margin stacking to capture subscription revenue and usage data relationships. |
| Energy-Efficiency Repositioning | Pre-certification above US DOE and EU Ecodesign tiers unlocks utility rebate program margin pools. |
Study Parameters
Independent corroboration across appliance OEM product managers, rare earth procurement specialists, and retail category buyers underwrites the qualitative findings. Primary fieldwork engaged R&D directors at Guangdong manufacturing clusters, ECHA regulatory affairs consultants, and utility rebate program administrators in California and New York. Secondary validation drew from SAMR certification databases, US DOE appliance standards filings, and EU Ecodesign Directive implementation reports. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Comparable-period anchoring to historical electrification rates in tier-two Chinese cities and replacement cycle compression in compact European dwellings shaped the projection horizon. Segmentation modeling spanned product type, connectivity tier, end-use intensity, and regional regulatory cluster. CAGRs derived from fitted growth curves calibrated to observed adoption elasticities across income brackets. Forecast inputs incorporated neodymium price volatility indices and Wi-Fi module cost decline trajectories.
Underlying measurement precision varies by segment; smart appliance connectivity attach rates carry tighter precision than manual control penetration in informal housing sectors. Forecasts embed assumptions around EU Ecodesign tier escalation timing and rare earth export quota continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Residential Washing Machine Market
Home Appliances
Major Home Appliances Market
Home Appliances
Electric Fireplace Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
White Goods Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
India Home Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
United States Laundry Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Europe Personal Care Appliances Market