
 Built-In Appliance Market | 2026-2036
Built-In Appliance Market Size, Share, and Industry Trends Forecast 2026-2036
Built-In Appliance Market Insights
China is tilting toward integrated kitchen module production to serve Asia-Pacific renovation cycles. BSH Hausgeräte GmbH leverages its German engineering heritage to dominate European premium cabinetry partnerships. Haier Smart Home Co., Ltd. anchors its position through backward integration into compressor and control system manufacturing. Samsung Electronics Co., Ltd. differentiates via proprietary AI-driven cooking algorithms embedded across its built-in ranges.
Built-in appliances are factory-designed cooking, cooling, and cleaning units dimensioned to fit within fixed cabinetry enclosures, typically requiring 600 mm width standards and flush-mount installation protocols for seamless kitchen integration. Their primary commercial purpose is to maximize usable floor space while delivering performance parity with freestanding equivalents in residential and hospitality environments. Ovens and cooktops command the largest revenue share within product type segments due to replacement frequency and premium pricing on pyrolytic and steam-assist variants. Smart Appliances technology is expanding fastest as Wi-Fi-enabled diagnostics and recipe-guided automation reshape consumer expectations for kitchen connectivity.
The EU Ecodesign Regulation and REACH compliance frameworks mandate recyclable material content and restrict hazardous substances in heating elements and insulation, forcing redesigns of core components. The US Department of Energy appliance standards and California Title 24 building codes shape efficiency benchmarks and installation specifications that manufacturers must satisfy for market access. Stakeholders should monitor how tightening energy label thresholds in Europe and electrification mandates in North American building codes will redirect R&D budgets toward heat-pump dishwashing and induction-dominant cooktop portfolios.
Market Dynamics
The EU Ecodesign Regulation's tightening efficiency thresholds are forcing wholesale redesigns of heating elements and insulation systems, compressing product development cycles while elevating compliance costs across European manufacturing footprints.
Growth Catalysts
- Electrification Mandates:California Title 24 building codes and similar North American standards are mandating induction-dominant cooktop specifications, pulling replacement demand forward in premium residential construction.
- Smart Connectivity Integration:Wi-Fi-enabled diagnostics and recipe-guided automation are reshaping consumer expectations for kitchen connectivity, expanding attach rates for connected modules.
- Asia-Pacific Renovation Cycles:Integrated kitchen module production in China is accelerating to serve replacement demand in aging housing stock across Japan, South Korea, and Australia.
Market Restraints
- Copper and Rare Earth Volatility:Compressor manufacturing and control system production face input cost pressure from concentrated mining operations in Chile and the Democratic Republic of Congo.
- German Supply Concentration:Premium cabinetry partnerships and engineering expertise cluster disproportionately around Munich and Stuttgart, creating geographic dependency risk.
- REACH Compliance Friction:Hazardous substance restrictions in heating elements and insulation materials force costly reformulation of legacy product lines.
Strategic Opportunities
- Dubai Luxury Residential:Connected kitchen suite specifications from high-end developers present white-space demand for European and Asian OEMs with established smart appliance portfolios.
- Heat-Pump Dishwashing:Tightening energy label thresholds across Europe are creating regulatory tailwinds for next-generation dishwashing technology that exceeds current efficiency benchmarks.
- AI-Driven Cooking Convergence:Proprietary algorithms embedded in built-in ranges are converging with computer vision and sensor fusion to enable automated cooking assistance.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware development for Wi-Fi modules and cloud connectivity faces acute competition from automotive and consumer electronics sectors.
- Certification Timeline Compression:EU Ecodesign and US Department of Energy standard updates are accelerating test-and-validate cycles, straining R&D throughput capacity.
- Legacy Platform Integration:Flush-mount installation protocols and 600 mm width standards create friction when retrofitting smart modules into existing cabinetry footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Built-In Appliance Market |
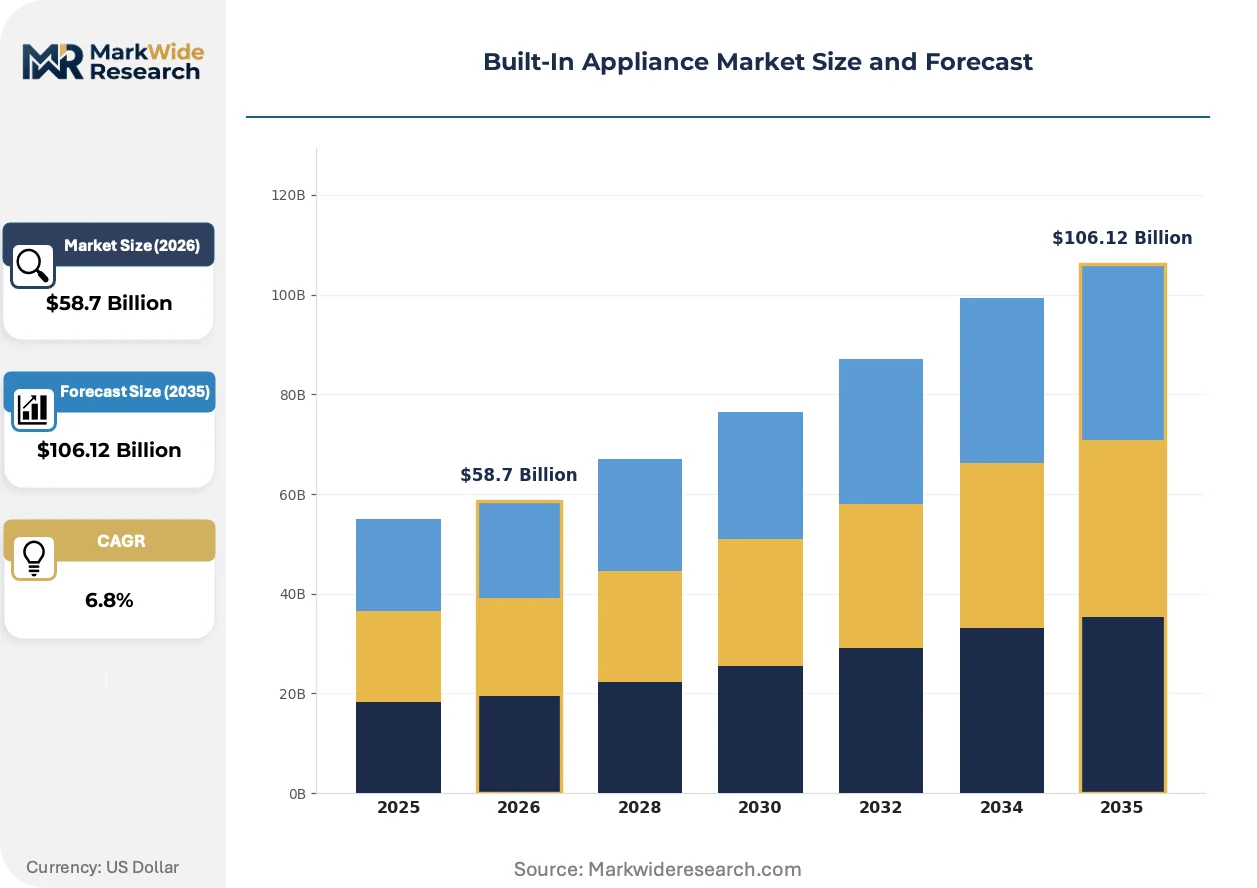
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ovens, Refrigerators, Dishwashers, Cooktops End User: Residential, Commercial, Hospitality, Construction Technology: Smart Appliances, Traditional Appliances, Energy-Efficient, Advanced Cooking Installation Type: Built-In, Integrated, Modular, Custom |
| Companies Covered | BSH Hausgeräte GmbH, AB Electrolux, Whirlpool Corporation, Haier Smart Home Co., Ltd., LG Electronics, Samsung Electronics Co., Ltd., Panasonic Holdings Corporation, Robert Bosch GmbH, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Built-In Appliance Market Trends and Innovations
Kitchen automation is digitizing every stage of meal preparation, from ingredient recognition to energy optimization, compressing the gap between professional culinary equipment and residential installations.
Steam-assist and pyrolytic oven technology is digitizing cleaning cycles and moisture control through sensor networks that adjust temperature profiles in real time. Luxury residential developers in Dubai are specifying these modules at accelerated rates for premium tower projects. The structural consequence is a compression of service intervals and a shift toward predictive maintenance contracts.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigeration circuits, forcing compressor redesigns and alternative refrigerant adoption across European manufacturing. This industrial consequence elevates R&D allocation toward propane and isobutane systems. Built-in refrigeration lines serving Germany, France, and Italy are responding with accelerated qualification timelines for flammable refrigerant architectures.
Buying patterns among German premium housing developers are consolidating procurement around full kitchen suite specifications rather than discrete appliance purchases. This channel consolidation is displacing traditional distributor relationships with direct OEM partnerships. The phenomenon is most visible in Stuttgart and Munich corridor developments where single-source kitchen contracts dominate new construction.
Built-In Appliance Market Segmentation
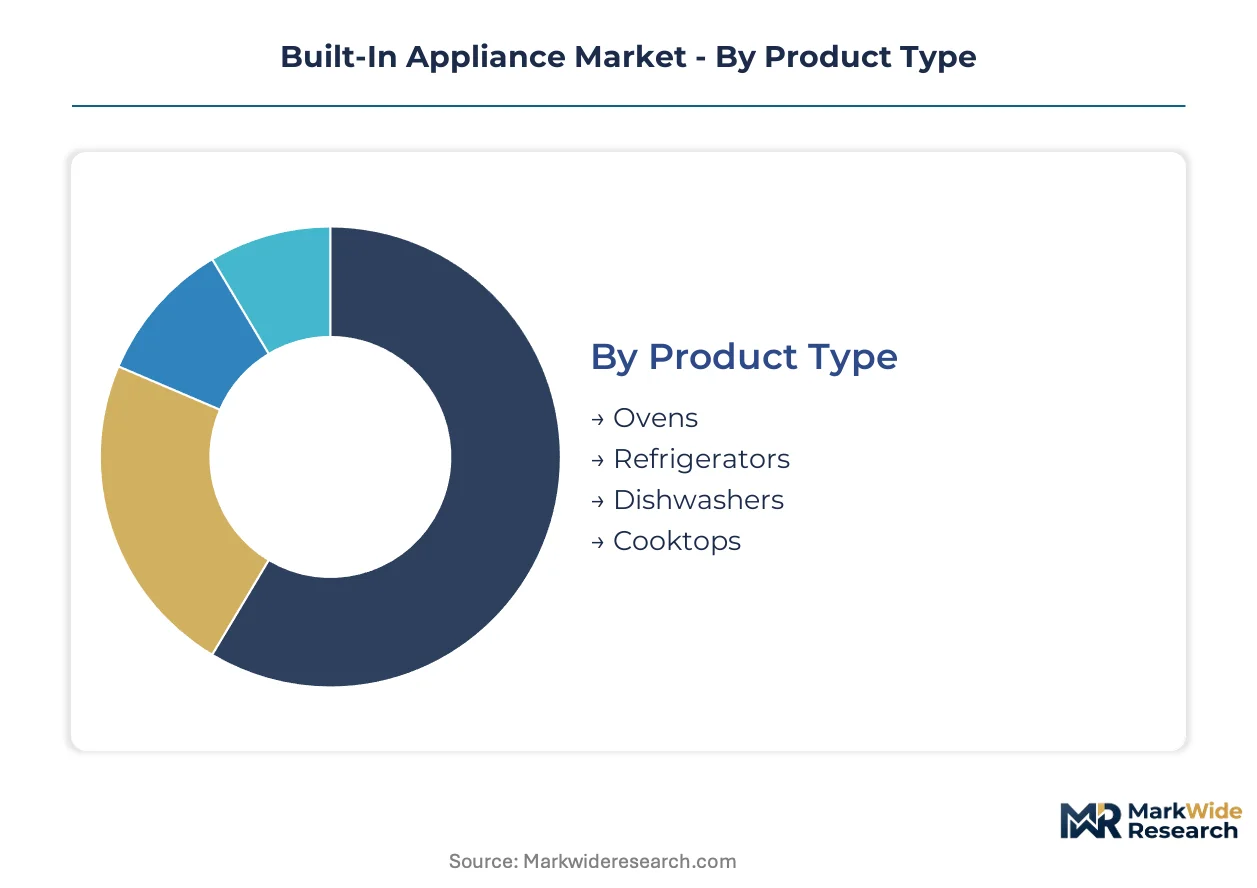
Built-in appliance manufacturers configure product portfolios around four distinct segmentation axes. Each dimension governs different margin structures, certification requirements, and channel access protocols that shape competitive positioning across residential and commercial deployments.
Product Type:
Cost tier stratification separates replacement-cycle frequency from premium pricing capture across cooking, cooling, and cleaning functions.
- Ovens:Pyrolytic self-cleaning and steam-assist variants command premium positioning through sensor-driven temperature profiling and automated maintenance cycles. Demand concentrates in German premium housing corridors around Munich and Stuttgart, pulled by full-kitchen-suite procurement contracts from luxury developers.
- Cooktops:Induction-dominant specifications are accelerating under California Title 24 electrification mandates, with flush-mount integration protocols requiring precise 600 mm width compliance. Dubai luxury residential towers are specifying connected variants at elevated rates.
- Refrigerators:Compressor redesigns for flammable refrigerant architectures are elevating qualification timelines under EU F-Gas Regulation phase-down schedules.
- Dishwashers:Heat-pump technology adoption is climbing fastest as tightening EU Ecodesign energy label thresholds redirect R&D budgets toward next-generation efficiency benchmarks.
Ovens hold installed capacity. Dishwashers are rotating up the share rankings.
End User:
Application context determines installation protocol complexity, service contract attachment rates, and specification authority concentration.
- Residential:Single-family and multi-family housing drives volume through replacement cycles in aging Asia-Pacific stock across Japan, South Korea, and Australia. Wi-Fi-enabled diagnostics are reshaping consumer expectations for predictive maintenance and recipe-guided automation.
- Hospitality:Premium hotels and restaurant chains demand performance parity with professional culinary equipment through sensor fusion and real-time moisture control. Procurement consolidates around direct OEM partnerships rather than traditional distributor relationships.
- Commercial:Corporate cafeterias and institutional kitchens prioritize durability specifications and standardized service intervals over connectivity features.
- Construction:New-build specifications are tilting toward integrated kitchen modules from Chinese production bases serving renovation cycles across the Asia-Pacific region.
Residential anchors volume throughput. Hospitality is climbing the fastest on margin contribution.
Technology:
Maturity gradients separate legacy platforms from connected architectures that require embedded systems talent scarce across appliance, automotive, and consumer electronics labor markets.
- Smart Appliances:Wi-Fi modules, cloud connectivity, and proprietary AI-driven cooking algorithms are expanding attach rates as firmware development faces acute competition from adjacent sectors. Samsung Electronics differentiates through computer vision and sensor fusion convergence in built-in ranges.
- Energy-Efficient:REACH compliance frameworks and US Department of Energy appliance standards mandate recyclable material content and restrict hazardous substances, forcing heating element and insulation redesigns.
- Traditional Appliances:Legacy platforms without connectivity modules serve price-sensitive replacement demand where flush-mount retrofit friction is lowest.
- Advanced Cooking:Steam-assist and pyrolytic variants digitize cleaning cycles through sensor networks that adjust temperature profiles in real time.
Traditional Appliances hold installed capacity. Smart Appliances is gaining share fastest on connectivity integration.
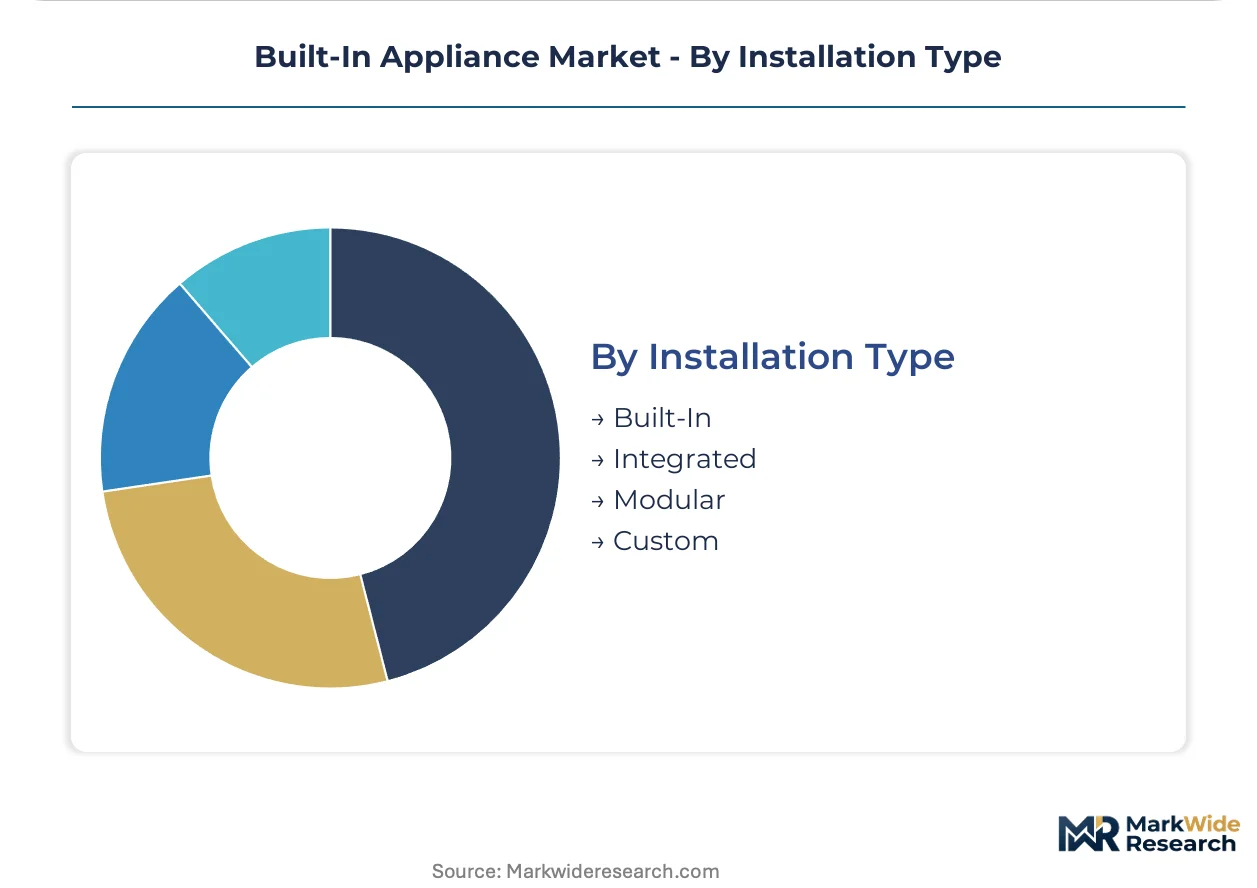
Installation Type:
Supply concentration around German engineering expertise and Chinese module production creates geographic dependency risk across specification protocols.
- Built-In:Factory-designed units dimensioned to 600 mm width standards require precise cabinetry enclosure tolerances for seamless kitchen integration. BSH Hausgeräte leverages German engineering heritage to dominate European premium cabinetry partnerships.
- Integrated:Panel-ready designs that accept custom cabinetry facings command premium positioning in luxury residential developments where aesthetic continuity overrides standardization.
- Modular:Flexible configuration systems accommodate non-standard kitchen footprints prevalent in renovation markets across aging Asia-Pacific housing stock.
- Custom:Bespoke specifications for ultra-premium installations in Dubai tower projects and Stuttgart corridor developments bypass standard distributor channels entirely.
Built-In holds installed capacity. Integrated is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters and Chinese module production bases anchor supply-side capacity for built-in appliances, with specification demand fragmenting across electrification mandates in North America, efficiency regulations in Europe, and luxury residential development in the Middle East.
United States
California Title 24 building codes mandate induction-dominant cooktop specifications in new residential construction, pulling replacement demand forward in premium housing markets. The US Department of Energy appliance standards shape national efficiency benchmarks for ovens and dishwashers. Los Angeles and San Francisco metropolitan corridors concentrate developer procurement for connected kitchen suites.
Germany
EU Ecodesign Regulation tightening drives wholesale redesigns of heating elements and insulation systems across oven and dishwasher portfolios. REACH compliance frameworks restrict hazardous substances in manufacturing processes. Munich and Stuttgart premium housing corridors dominate full-kitchen-suite procurement contracts from luxury developers.
China
Integrated kitchen module production accelerates to serve Asia-Pacific renovation cycles in aging Japanese, South Korean, and Australian housing stock. MIIT standards and dual carbon goals shape domestic manufacturing efficiency requirements. Yangtze River Delta production bases concentrate compressor and control system manufacturing capacity.
United Arab Emirates
Dubai luxury residential towers specify connected kitchen suites at accelerated rates for premium developments. MOHAP and local building codes establish installation and safety standards for imported appliances. Dubai Marina and Downtown Dubai districts concentrate high-end developer procurement around European and Asian OEM portfolios.
Japan
Aging housing stock across Tokyo, Osaka, and Nagoya metro areas drives replacement demand for compact built-in appliances. METI energy efficiency standards and JIS certification requirements shape product qualification timelines. Kanto region distributors consolidate procurement around smart connectivity modules for renovation markets.
Built-In Appliance Market Competitive Landscape
European heritage engineering specialists and Asian scale manufacturers split the market between premium cabinetry partnerships and integrated module production. Consolidation pressures concentrate around direct OEM relationships displacing traditional distributor channels, particularly in German and UAE luxury residential corridors. Three archetypes dominate: heritage engineering houses leveraging technical reputation, diversified electronics conglomerates embedding connectivity ecosystems, and integrated home appliance platforms controlling upstream component supply. Competitive moves center on backward integration into compressor manufacturing and AI-driven cooking algorithm development.
Among heritage engineering specialists, BSH Hausgeräte GmbH and Robert Bosch GmbH occupy positions anchored in German manufacturing tradition. Haier Smart Home Co., Ltd. exemplifies the integrated platform archetype through captive supply chain control. Samsung Electronics Co., Ltd. represents the connectivity-focused diversified player embedding proprietary ecosystems across product ranges.
| Leading Market Players |
|---|
| BSH Hausgeräte GmbH |
| AB Electrolux |
| Whirlpool Corporation |
| Haier Smart Home Co., Ltd. |
| LG Electronics |
| Samsung Electronics Co., Ltd. |
| Panasonic Holdings Corporation |
| Robert Bosch GmbH |
| GE Appliances |
| Others |
Pricing and Supply Chain Analysis
Compressor manufacturing concentration in China and the Yangtze River Delta feeds directly into margin capture by OEMs with backward integration into control system production, while copper and rare earth volatility from Chilean and Congolese mining operations compresses pricing power for non-integrated assemblers.
Pricing Analysis
EU Ecodesign Regulation dictates the pricing tier structure across European markets, with REACH compliance costs and F-Gas refrigerant phase-down requirements forcing premium positioning for certified heat-pump dishwashers and flammable-refrigerant architectures. Three-tier pricing structure across premium, standard, and economy levels separates pyrolytic steam-assist ovens from conventional electric units from basic replacement models. Pricing pressure stems from copper and rare earth input cost volatility concentrated in Chile and the Democratic Republic of Congo. Commercial and institutional buyers exhibit highest price sensitivity due to standardized service interval requirements, while Dubai luxury residential developers show lowest sensitivity given full-kitchen-suite procurement contracts.
Supply Chain Analysis
Contract manufacturing for Wi-Fi modules and embedded control systems concentrates with EMS providers serving automotive and consumer electronics clients, creating capacity competition for appliance firmware development. Supply draws from China for integrated kitchen modules, Germany for premium cabinetry partnerships, and South Korea for compressor technology. Critical dependencies include copper for heating elements, rare earth elements for control system magnets, and flammable refrigerants for EU-compliant refrigeration circuits. Single-source vulnerability runs through German engineering clusters around Munich and Stuttgart. Distribution runs through direct OEM partnerships displacing traditional distributor channels in premium residential corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The built-in appliance market is cycling through a replacement-driven recovery anchored by Asia-Pacific renovation demand in aging Japanese, South Korean, and Australian housing stock.
For Market Incumbents: Build switching-cost moats through predictive maintenance contracts and proprietary AI-driven cooking algorithm ecosystems that embed Samsung Electronics-style computer vision convergence. BSH Hausgeräte should deepen backward integration into compressor manufacturing to defend against Haier Smart Home's captive supply chain control. Induction-dominant cooktop mandates under California Title 24 and similar North American codes threaten legacy gas-cooktop inventories, requiring accelerated R&D reallocation. For New Entrants and Emerging Players: Build out white-space presence in Dubai luxury residential tower specifications where connected kitchen suite demand outpaces established European and Asian OEM supply. Heat-pump dishwashing technology presents the most penetrable segment given tightening EU Ecodesign energy label thresholds and limited incumbent qualification timelines. A direct developer partnership model bypassing traditional distribution offers the clearest go-to-market angle for premium positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European heritage engineering houses lacking connectivity ecosystem integration. Long-term viability over a five-to-ten year window hinges on embedded systems talent acquisition and cloud platform development. Monitor EU F-Gas Regulation phase-down enforcement velocity as the critical inflection signal for refrigerant technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Dishwasher Platform Launch | Exceeds tightening EU Ecodesign thresholds while capturing premium positioning in German housing corridors. |
| Backward Integration into Compressor Manufacturing | Mirrors Haier Smart Home's captive supply model to insulate margins from rare earth volatility. |
| AI-Driven Cooking Algorithm Development | Replicates Samsung Electronics' sensor fusion convergence for automated residential meal preparation. |
| Dubai Luxury Residential Direct Partnership | Bypasses distributor channels to capture white-space demand from premium tower developers. |
| Flammable Refrigerant Architecture Qualification | Secures EU market access under F-Gas Regulation phase-down schedules for built-in refrigeration lines. |
Research Methodology
Initial hypotheses were tested against primary input from appliance platform engineers, luxury residential procurement directors, hospitality F&B operations heads, and aftermarket service contract managers and refined through secondary validation against SEC 10-K filings, EU Ecodesign regulatory databases, MIIT standard disclosures, and customs trade data for compressor and control system imports. Bottom-up unit shipment estimates from country-level housing stock and renovation cycle analysis were triangulated against top-down manufacturer revenue disclosures.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by replacement frequency and premium capture potential, end user segmentation by installation protocol complexity, technology segmentation by connectivity maturity, and installation type segmentation by specification authority concentration. CAGRs were derived from regression analysis of historical shipment data against housing starts, electrification mandate adoption curves, and efficiency regulation implementation timelines. Forecast inputs included Asia-Pacific renovation cycle intensity and Dubai luxury residential tower pipeline specifications.
Practitioners should monitor copper and rare earth price volatility, EU Ecodesign threshold revision schedules, and embedded systems talent migration patterns for early signals of forecast revision. Quarterly review of F-Gas Regulation enforcement data, California Title 24 adoption rates in additional jurisdictions, and heat-pump dishwasher qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
Oman Home Appliances Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Oman Major Home Appliances Market
Home Appliances
Refrigerator Market
Home Appliances
China Small Home Appliances Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Egypt Home Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
United States Household Refrigerators Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
Residential Cooker Hoods Market