
 Brazil Home Appliances Market | 2026-2036
Brazil Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Home Appliances Market Analysis
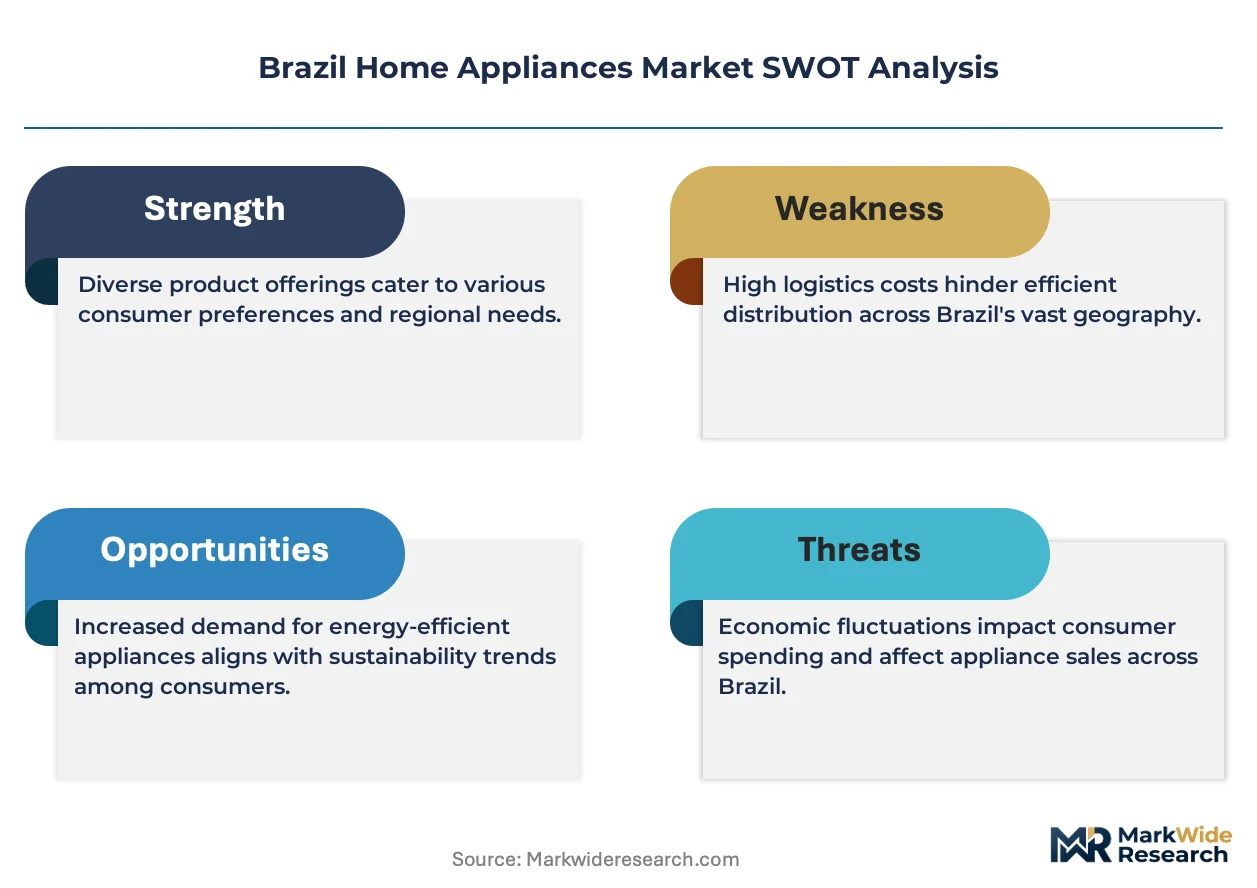
First-time homebuyers in gated communities is rotating demand toward compact, energy-efficient refrigerators and washer-dryer combos. Whirlpool Corporation leverages its Brazilian manufacturing footprint to sustain cost competitiveness in mid-range refrigeration. Electrolux do Brasil anchors premium positioning through Scandinavian design heritage and local assembly flexibility. Mondial Eletrodomesticos SA dominates price-sensitive segments with direct-to-retail distribution across the Northeast and Central-West.
Brazil home appliances comprise electromechanical devices designed for domestic tasks, typically operating on 127V or 220V Brazilian grid standards with INMETRO-certified energy efficiency ratings from A to G. Refrigerators, washers, microwaves, and ovens serve primary functions of food preservation, textile cleaning, and thermal food processing for residential and commercial kitchens. Smart appliances and IoT-enabled units capture margin pools through connected diagnostics and remote monitoring, while energy-efficient models lead replacement demand under stricter labeling protocols. Traditional technology still occupies rural and lower-income urban markets where upfront cost sensitivity overrides operating expense considerations.
ANVISA governs material safety in food-contact surfaces, while INMETRO enforces energy performance standards and conformity assessment procedures for electromagnetic compatibility. The National Institute of Metrology, Quality and Technology certification creates market access barriers that favor manufacturers with established Brazilian testing partnerships. Proposed updates to minimum energy performance standards for refrigeration equipment will force portfolio recalibration across all price tiers. Stakeholders must monitor central bank credit policy and payroll-deduction financing availability, as consumer durable purchases in Brazil remain tightly coupled to installment credit access and real interest rate trajectories.
Market Dynamics
INMETRO's tightening energy-labeling mandates are forcing manufacturers to redesign compressor architectures and sensor arrays across all price tiers, compressing development cycles while elevating certification costs.
Growth Catalysts
- INMETRO A-to-G labeling:Mandatory efficiency tiers accelerate replacement demand for inverter-compressor refrigerators and smart-sensor washing machines among credit-accessible households.
- Payroll-deduction financing:Central bank credit expansion through consigned credit lines unlocks installment purchasing power for durable goods in São Paulo's retail corridor.
- First-time homebuyers in gated communities:Compact appliance formats gain traction as developers specify space-efficient, energy-certified units for new residential stock.
Market Restraints
- Copper and steel input volatility:Compressor and cabinet manufacturing faces margin compression from commodity price swings in global metals markets.
- Southeast regional concentration:Demand clustering around São Paulo creates logistics inefficiencies and working capital strain for Northeast and Central-West distribution.
- Dual-voltage infrastructure heterogeneity:127V versus 220V grid standards force SKU proliferation and inventory duplication across state boundaries.
Strategic Opportunities
- Northeast urbanization corridors:Fortaleza and Recife exhibit appliance penetration gaps addressable through direct-to-retail distribution models bypassing traditional wholesale layers.
- IoT-enabled predictive maintenance:Connected diagnostics create recurring revenue streams through remote monitoring subscriptions attached to premium refrigeration units.
- ANVISA food-contact compliance:Stricter material safety protocols favor domestic assemblers with established testing partnerships over import-dependent competitors.
Industry Challenges
- INMETRO certification timelines:Laboratory testing queues and documentation requirements extend product launch windows by four to six months.
- Legacy 220V inventory obsolescence:Grid standard migration in select states forces write-downs of non-compliant stock in distributor channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Home Appliances Market |
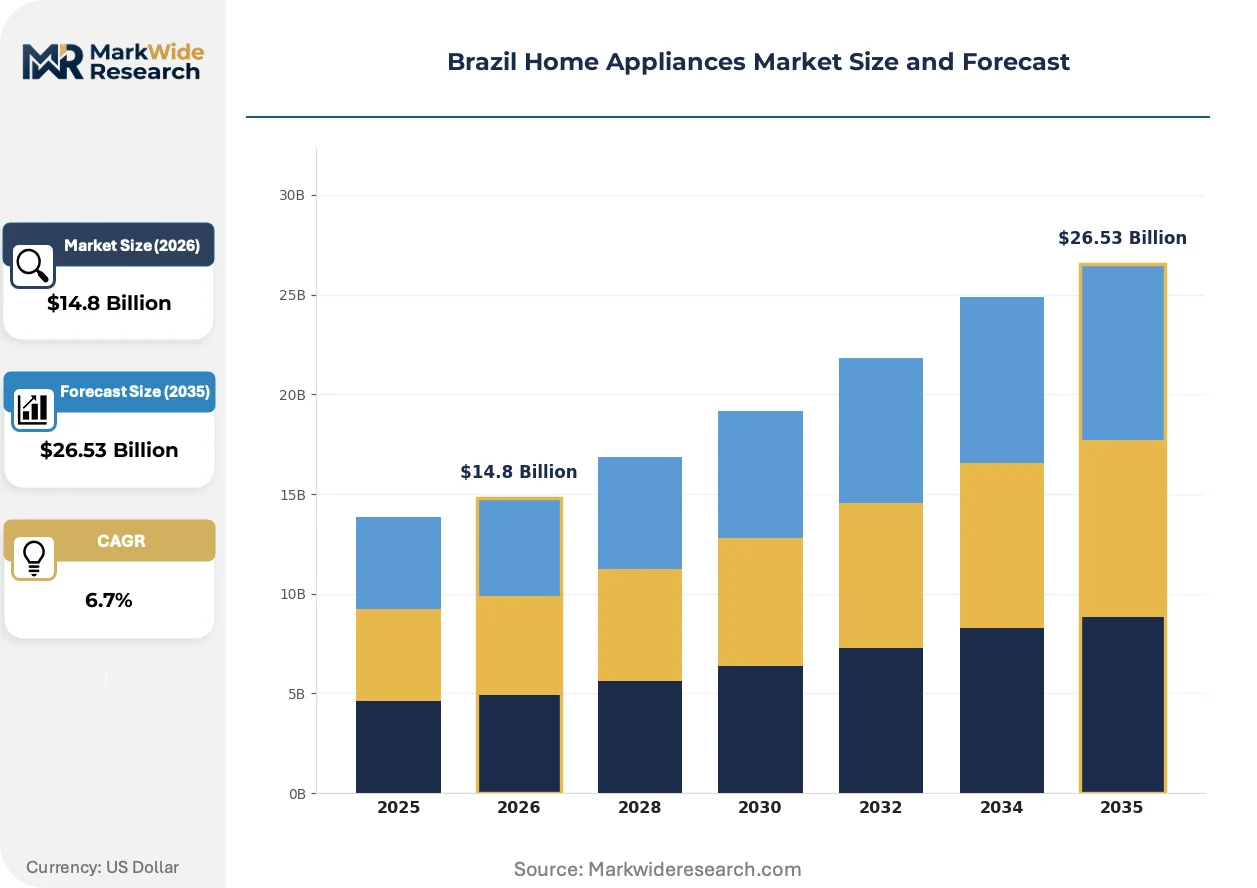
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washers, Microwaves, Ovens End User: Households, Retail Outlets, Hospitality, Commercial Technology: Smart Appliances, Energy-Efficient, Traditional, IoT-Enabled Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | LG Electronics, SEB Groupe, Whirlpool Corporation, Mondial Eletrodomesticos SA, Gree Electric Appliances Inc, Electrolux do Brasil, Midea Carrier, Panasonic Corporation, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Home Appliances Market Emerging Trajectories
Appliance architecture is fragmenting into modular, software-defined systems that separate thermal hardware from control intelligence. This decomposition enables faster feature updates and challenges traditional integrated design paradigms.
Inverter compressor technology is decomposing the conventional fixed-speed refrigeration market. Middle-class households in Minas Gerais and São Paulo are specifying variable-speed units in replacement cycles. The technology is compressing manufacturer margins on legacy fixed-speed portfolios while opening premium tier positioning.
ANVISA's updated food-contact surface protocols are reshaping interior liner material specifications. Manufacturers must reformulate coatings and plastics to meet migration limits for heavy metals and plasticizers. Premium refrigerator lines are responding fastest, using compliance as a differentiation marker against uncertified imports.
Retail financing unbundling is altering purchase behavior in Brazil's appliance channels. Traditional department store credit is losing share to fintech-enabled installment platforms and retailer-branded digital wallets. São Paulo's dense retail corridor exhibits the most pronounced channel fragmentation, with online-to-offline integration accelerating.
Brazil Home Appliances Market Segmentation
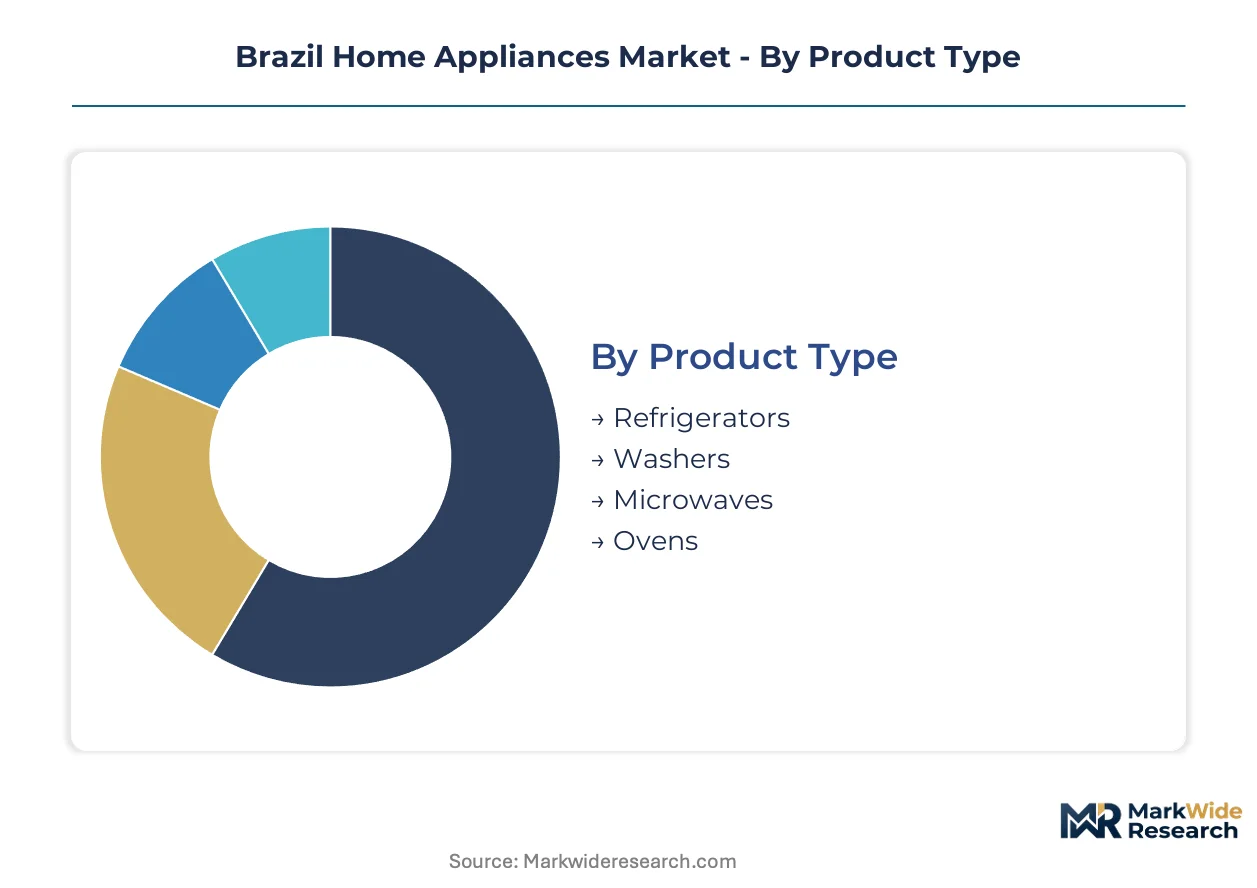
Segmentation in Brazil's home appliances market reveals how INMETRO energy-labeling mandates, voltage infrastructure heterogeneity, and credit-access patterns fragment demand across distinct technical and commercial profiles. Manufacturers must align portfolio depth with each segment's certification burden and financing sensitivity.
Product Type:
Margin pools concentrate in refrigeration and washing equipment where inverter-compressor upgrades command pricing premiums under stricter efficiency tiers.
- Refrigerators:Units span compact 260L formats for gated-community apartments to 500L+ multi-door systems. Demand clusters in São Paulo and Minas Gerais replacement cycles where INMETRO A-label inverter compressors displace fixed-speed legacy stock. Mondial Eletrodomesticos SA and Electrolux do Brasil anchor opposite ends of the price spectrum through direct retail and design-premium positioning respectively.
- Washers:Front-load and top-load configurations face diverging fates as water-efficiency mandates tighten. Washer-dryer combos gain traction among first-time homebuyers in space-constrained developments, though 220V compatibility requirements complicate Northeast distribution.
- Microwaves:Solo and grill variants serve quick-meal preparation in urban households. Price sensitivity dominates outside Southeast retail corridors.
- Ovens:Built-in and freestanding formats split between new construction specifications and replacement demand. Gas and electric variants must navigate state-level infrastructure heterogeneity.
The dominant share belongs to Refrigerators, while Washers is closing the gap fastest through replacement-driven inverter adoption.
End User:
Volume concentration follows credit accessibility and construction activity geography.
- Households:Middle-class units in São Paulo's retail corridor drive replacement cycles through payroll-deduction financing. Energy-label awareness elevates willingness-to-pay for A-grade certification among credit-accessible segments.
- Retail Outlets:Appliance specialty chains and department stores specify display and demonstration units with distinct warranty terms.
- Hospitality:Hotels and extended-stay operators prioritize durability and energy operating costs over upfront capital expenditure.
- Commercial:Restaurants and institutional kitchens demand heavy-duty cycles with ANVISA food-contact compliance.
Households captures the majority position, though Commercial is expanding most quickly through hospitality sector recovery.
Technology:
Certification cost structures and feature premiums stratify profitability across technical tiers.
- Smart Appliances:Connected units with remote diagnostics and predictive maintenance capabilities. São Paulo's dense retail corridor shows highest penetration where fintech-enabled installment platforms reduce upfront friction.
- Energy-Efficient:INMETRO A-to-G label compliance defines market access. Inverter compressors and smart sensors dominate new product development cycles.
- Traditional:Fixed-speed refrigeration and mechanical controls persist in rural markets and lower-income urban zones where upfront cost sensitivity overrides operating expense calculations.
- IoT-Enabled:Subscription-attached remote monitoring creates recurring revenue streams on premium refrigeration lines.
Energy-Efficient holds the largest installed base, while Smart Appliances is gaining share fastest through financing unbundling.
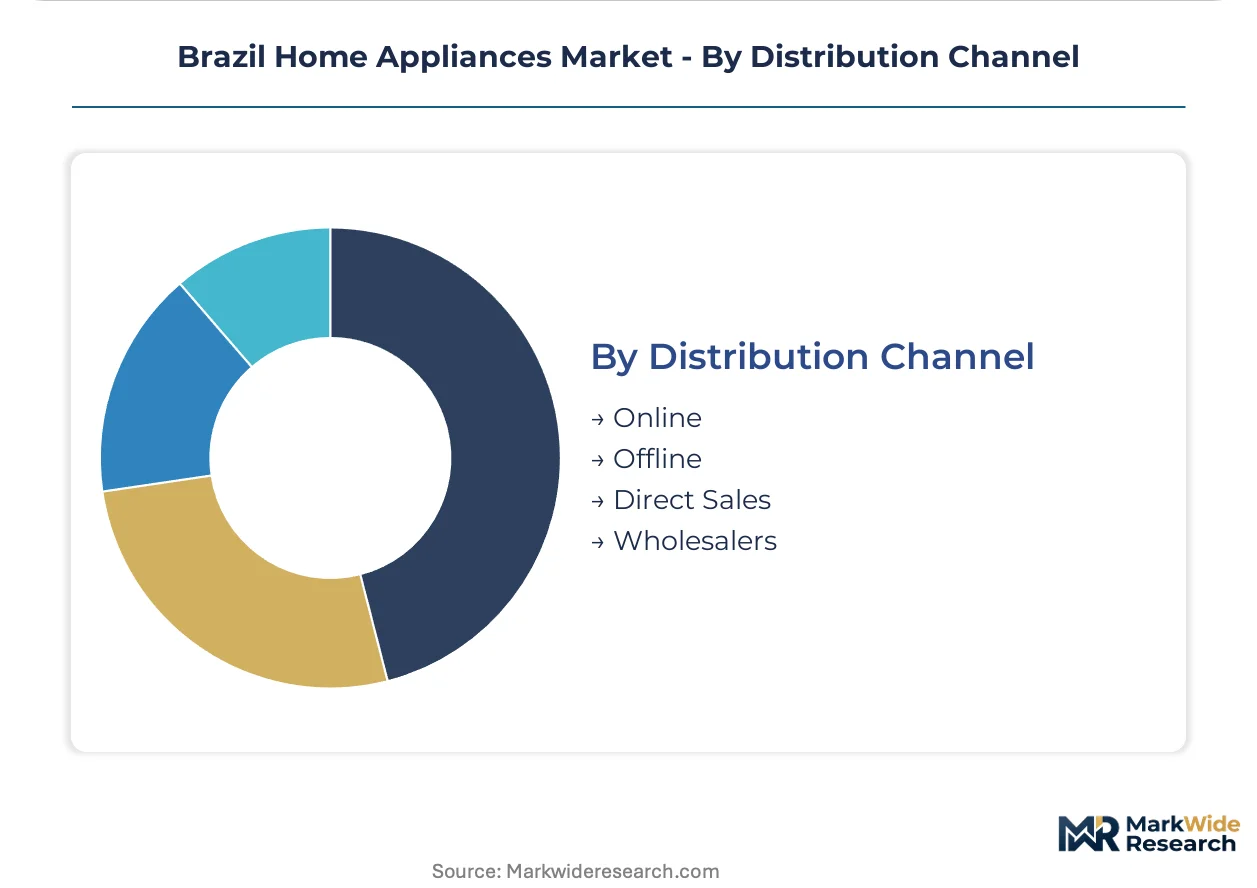
Distribution Channel:
Channel fragmentation accelerates as fintech platforms disintermediate traditional credit intermediaries.
- Online:Marketplace platforms and direct brand sites with digital-wallet integration. São Paulo exhibits highest online-to-offline conversion rates.
- Offline:Department stores and appliance specialty chains with in-house financing. Losing share to fintech alternatives.
- Direct Sales:Manufacturer-owned retail and factory outlet formats. Electrolux do Brasil leverages for premium positioning.
- Wholesalers:Traditional layer bypassed by Mondial Eletrodomesticos SA direct-to-retail model in Northeast and Central-West corridors.
Offline retains the dominant position, though Online is climbing the fastest through installment platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China-based manufacturers export compressors and electronic control modules to Brazilian assembly plants, while São Paulo's retail corridor redistributes finished appliances throughout the Southeast and into the Northeast urbanization corridors.
São Paulo
Middle-class replacement cycles concentrate in São Paulo's gated communities and dense retail corridors. INMETRO energy-labeling mandates accelerate demand for inverter-compressor refrigerators through payroll-deduction financing channels. The metropolitan area anchors national distribution networks with direct-to-retail penetration reaching price-sensitive segments.
Minas Gerais
Households in Belo Horizonte and surrounding municipalities specify energy-efficient washers and compact refrigeration formats. State-level grid standards at 127V drive SKU proliferation for manufacturers serving this corridor. Local assembly partnerships reduce logistics strain from Southeast concentration.
Rio Grande do Sul
Southern Brazil exhibits stronger 220V infrastructure penetration, creating inventory segmentation challenges for national distributors. Porto Alegre's retail channels favor European design heritage in premium positioning. ANVISA compliance requirements favor domestic assemblers with established testing partnerships over import-dependent competitors.
Bahia
Salvador and Northeast urbanization corridors show appliance penetration gaps addressable through direct distribution models. Mondial Eletrodomesticos SA bypasses traditional wholesale layers in this region. Federal credit expansion programs unlock installment purchasing power outside the Southeast core.
Paraná
Curitiba's manufacturing base supports component supply chains for refrigeration compressor assembly. The state bridges 127V and 220V grid standards, forcing voltage-specific inventory management. Logistics positioning enables redistribution into both Southeast and Central-West markets.
Brazil Home Appliances Market Vendor Landscape
Listed leaders compete with private specialists across financing access and distribution architecture. The market structure consolidates around three tiers: multinational manufacturers with Brazilian assembly footprints, domestic price-positioned assemblers, and import-dependent premium distributors. Strategic archetypes include scale-driven compressor integrators, design-premium positioning specialists, and direct-to-retail bypass operators. Competitive moves concentrate on portfolio recalibration under INMETRO efficiency mandates and geographic expansion through fintech-enabled installment platforms.
Within the multinational tier, Whirlpool Corporation and Electrolux do Brasil occupy positions anchored by local manufacturing flexibility and Scandinavian design heritage respectively. Mondial Eletrodomesticos SA exemplifies the domestic price-positioned archetype through direct-to-retail distribution across Northeast and Central-West corridors. These three entities represent distinct strategic responses to INMETRO certification burdens and voltage infrastructure heterogeneity.
| Leading Market Players |
|---|
| LG Electronics |
| SEB Groupe |
| Whirlpool Corporation |
| Mondial Eletrodomesticos SA |
| Gree Electric Appliances Inc |
| Electrolux do Brasil |
| Midea Carrier |
| Panasonic Corporation |
| Samsung Electronics |
| Others |
Supply Flow & Price Mechanics
Long-term compressor offtake agreements between São Paulo assembly plants and Chinese suppliers lock in both copper pricing visibility and inverter component access for Brazilian manufacturers navigating INMETRO recertification cycles. These contracts compress working capital volatility while embedding efficiency-grade premiums into tiered procurement structures.
Pricing Analysis
Inverter-compressor refrigerators command a 40-60% premium over fixed-speed legacy units, with price differentiation driven by INMETRO A-label certification grade and São Paulo retail corridor financing access. Cost compression in mid-range refrigeration intensifies as Mondial Eletrodomesticos SA and Electrolux do Brasil reposition portfolios toward energy-efficient tiers. Rural households in Northeast urbanization corridors exhibit highest price sensitivity, while gated-community first-time homebuyers absorb premium positioning for compact certified formats.
Supply Chain Analysis
Panama Canal transit congestion and Port of Santos container bottlenecks expose Brazilian assemblers to logistics chokepoint risk when sourcing inverter compressors and electronic control modules from China, South Korea, and Taiwan. Domestic manufacturing draws from Chilean copper cathode, Argentine steel sheet, and imported rare-earth magnet feedstock for motor assemblies. Distribution runs through São Paulo's wholesale consolidation layer before radiating to Northeast direct-to-retail bypass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's home appliances market represents a high-growth disruption as INMETRO's A-to-G labeling mandates force portfolio recalibration across all price tiers, compressing development cycles while elevating certification barriers.
For Market Incumbents: Fortify inverter-compressor supply partnerships through backward integration into motor winding and control module assembly, defending margin position against Chinese import cost volatility. Prioritize ANVISA pre-certified liner material inventories to compress INMETRO testing queue delays. Channel control through payroll-deduction financing exclusivity with retail chains anchors São Paulo corridor loyalty. For New Entrants and Emerging Players: Lead with direct-to-retail distribution in Fortaleza and Recife urbanization corridors, exploiting appliance penetration gaps bypassing traditional wholesale markups. Target 127V-compatible compact refrigeration for gated-community developers specifying space-efficient formats. Fintech-enabled installment platforms reduce upfront friction for credit-constrained households outside Southeast core markets. For Investors and Strategic Acquirers: Capital is best deployed toward domestic assemblers with established INMETRO testing partnerships and flexible voltage-SKU capabilities across 127V/220V infrastructure. Long-term viability hinges on regulatory compliance moats rather than scale economies alone. Monitor central bank consigned credit expansion rates as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| INMETRO A-Label Portfolio Migration | Repositions entire SKU base ahead of mandatory efficiency tier enforcement. |
| Direct-to-Retail Distribution Expansion | Bypasses wholesale layers in Northeast corridors where Mondial Eletrodomesticos SA established precedent. |
| IoT Predictive Maintenance Subscription Launch | Attaches recurring revenue to premium refrigeration lines in São Paulo's fintech-enabled channels. |
| Compressor Backward Integration | Captures motor winding and control module assembly from Chinese import dependency. |
| ANVISA Pre-Certified Material Partnerships | Compresses product launch windows by four to six months versus testing-queue competitors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of INMETRO certification databases, central bank credit policy circulars, and customs import records for compressor and electronic control module trade flows. Interviews with appliance manufacturing plant managers, retail chain category buyers, fintech platform credit officers, and ANVISA regulatory affairs specialists anchored demand-side and compliance-side validation. Bottom-up SKU-level volume builds triangulated against top-down macroeconomic consumption projections.
Segmentation dimensions modeled span product type, end-user category, technology tier, and distribution channel across the analysis window, with voltage infrastructure heterogeneity and regional credit accessibility patterns as cross-cutting variables. CAGRs derived from replacement cycle velocity, construction activity trajectories, and financing penetration elasticities. Forecast inputs incorporate INMETRO regulatory timeline assumptions and copper price volatility scenarios.
The analysis sits within stated boundaries; outcomes outside sustained central bank credit expansion and stable commodity input costs would require recalibration. Forecasts reflect documented assumptions on INMETRO enforcement timelines and payroll-deduction financing availability. Practitioners should keep alternative scenarios live as central bank monetary policy and copper futures curve dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Range Hood Market
Home Appliances
Europe Washing Machine Market
Home Appliances
India Refrigerator Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Germany Washing Machine Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
Canada Home Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Major Home Appliances Market
Home Appliances
White Goods Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Refrigerator Market