
 Electric Household Appliances Market | 2026-2036
Electric Household Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Household Appliances Market Analysis
EU Ecodesign Directive is rebalancing the cost-of-entry calculus for manufacturers targeting European households, forcing redesign of compressor architectures and insulation systems to meet stepped efficiency tiers. Whirlpool Corporation leverages its North American manufacturing footprint to sustain margin structures under evolving federal appliance standards. LG Electronics Inc. anchors its competitive posture through in-house production of linear compressor technology, reducing dependency on external component suppliers.
Electric household appliances encompass electromechanical devices designed for domestic tasks, typically operating on alternating current between 110 and 240 volts with rated power consumption from tens of watts for small appliances to several kilowatts for major cooling and heating units, manufactured through stamped metal forming, injection molding of polymer housings, and automated assembly of motor-drive subsystems. Refrigerators command the largest absolute revenue pool among product types due to universal household penetration and replacement-driven purchasing, while smart appliances and IoT-enabled devices represent the fastest-expanding technology segment as connectivity modules become standard in mid-tier washing machines and climate control equipment. Energy-efficient appliances dominate procurement specifications for commercial kitchens and rental property portfolios where operating cost visibility shapes landlord and facility manager decisions.
The US Department of Energy maintains federal minimum efficiency standards through its appliance program, while China's GB standards and India's Bureau of Energy Efficiency labeling scheme impose parallel compliance obligations on manufacturers serving those domestic markets. The EU F-Gas Regulation further constrains refrigerant selection for cooling appliances, directly impacting compressor system design and service infrastructure requirements. Stakeholders must monitor divergence between regional efficiency test procedures and refrigerant phase-down schedules when configuring product platforms for multi-jurisdiction deployment.
Market Dynamics
The EU Ecodesign Directive is forcing compressor redesigns across refrigeration portfolios, while China's GB standards and India's Bureau of Energy Efficiency labeling scheme impose parallel compliance burdens that fragment product platform strategies.
Growth Catalysts
- Urban kitchen upgrades in Brazil:Middle-class households in São Paulo and Rio de Janeiro are replacing legacy refrigeration units with frost-free models, compressing replacement cycles from fifteen years to eight.
- India's Bureau of Energy Efficiency star-rating mandates:The labeling scheme for air conditioners and refrigerators is pulling inefficient stock from circulation and redirecting procurement toward inverter-compressor platforms.
- Linear compressor technology maturation:The shift from reciprocating to linear drive architectures is reducing mechanical friction losses and enabling variable-speed operation across mid-tier washing machines.
Market Restraints
- Copper and rare-earth magnet cost volatility:Compressor motor assemblies depend on neodymium and copper winding stock, with price swings transmitted directly to bill-of-materials stability.
- EU F-Gas Regulation refrigerant constraints:The phasedown of hydrofluorocarbon refrigerants is forcing retooling of cooling circuit designs and service technician retraining across European distribution networks.
- Induction cooking substitution threat:Gas infrastructure expansion in Southeast Asian markets is slowing electric cooktop penetration where piped natural gas reaches residential developments first.
Strategic Opportunities
- Underpenetrated rural India:Village electrification under the Saubhagya scheme is creating first-time appliance demand for electric fans and entry-level refrigerators in states with sub-thirty percent household penetration.
- Appliance-as-a-service models:Rental and subscription platforms for washing machines are emerging in German and Dutch urban rental markets, decoupling capital expenditure from usage rights.
- IoT-enabled predictive maintenance:The convergence of vibration sensors and cloud analytics is enabling service revenue streams through failure prediction in commercial laundry installations.
Industry Challenges
- Embedded systems firmware talent scarcity:Connected appliance development requires expertise in real-time operating systems and over-the-air update architectures that outpaces supply from European and North American engineering programs.
- Multi-jurisdiction certification timelines:Refrigerators must clear separate test protocols for DOE compliance in the United States, GB standards in China, and BEE labeling in India, stretching product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Household Appliances Market |
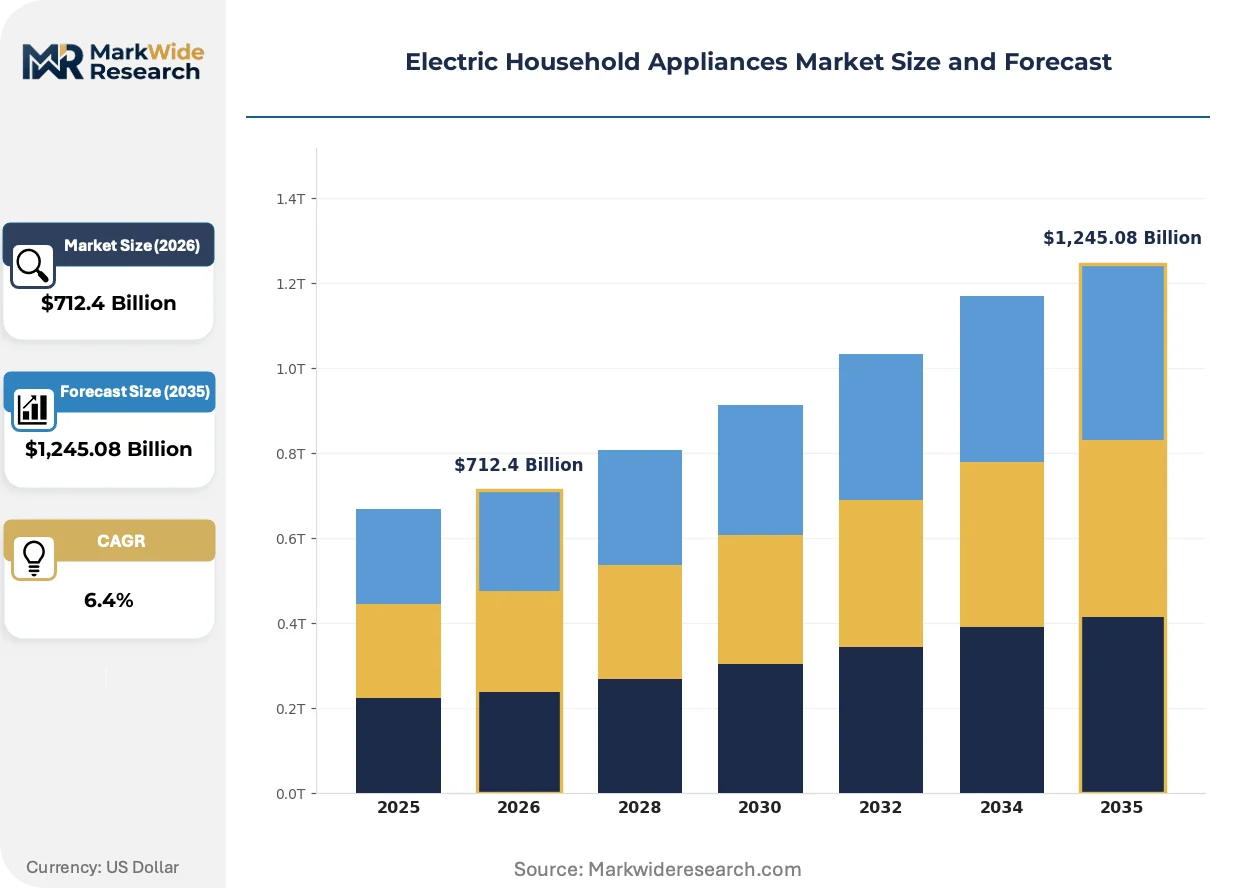
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $1,245.08 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Air Conditioners End User: Households, Commercial Kitchens, Hotels, Rental Properties Technology: Smart Appliances, Energy-Efficient Appliances, Conventional Appliances, IoT-Enabled Devices Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Haier Smart Home Co., Ltd., Whirlpool Corporation, LG Electronics Inc., Samsung Electronics Co., Ltd., Electrolux AB, Midea Group, BSH Hausgeräte GmbH, Panasonic Corporation, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Household Appliances Market Emerging Trajectories
Connectivity modules and variable-speed drive electronics are migrating from premium tiers to mass-market price bands, compressing the technology lag between flagship and entry-level product lines.
Heat pump dryer technology is converging with conventional vented architectures in European markets. German and Italian appliance buyers are accepting longer cycle times in exchange for ninety-percent energy reduction versus resistance-heated alternatives. The structural consequence is converging with vented dryer volume in Western European markets and forcing compressor suppliers to develop dedicated refrigerant circuits for laundry applications.
The EU F-Gas Regulation is accelerating hydrocarbon refrigerant adoption in domestic cooling appliances. Manufacturers serving European households must redesign sealed systems around isobutane and propane blends, with flammability protocols adding assembly line costs. The constraint is most acute in chest freezer categories where charge volumes exceed safety thresholds and demand redesign of compressor compartment ventilation.
Builder procurement is consolidating around energy-performance certificates in French and Spanish residential construction. Developers constructing multi-unit rental portfolios are specifying A+++ rated dishwashers and washing machines to meet regulatory minimums for building certification. The shift is visible in Mediterranean markets where rental stock modernization is outpacing owner-occupied replacement rates.
Electric Household Appliances Market Segmentation
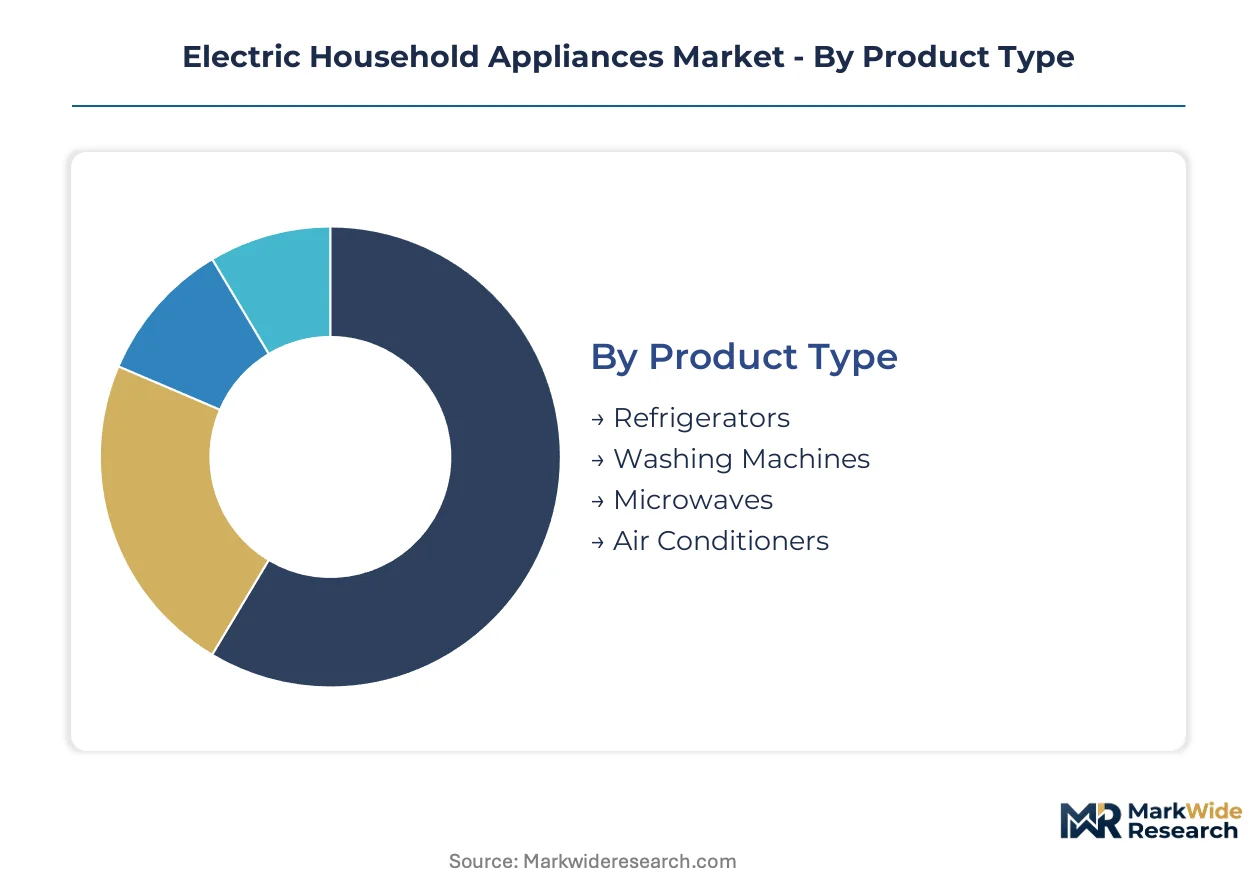
Segmentation in electric household appliances reveals how efficiency mandates and connectivity adoption reshape procurement patterns across price tiers. Manufacturers configure product platforms around refrigerant chemistry, motor drive architectures, and connectivity modules to match jurisdiction-specific compliance burdens and end-use operating profiles.
Product Type:
Compressor architecture and thermal management specifications differentiate performance tiers across cooling, cleaning, and cooking applications.
- Refrigerators:Sealed systems with variable-speed linear compressors dominate mid-tier and premium positioning, with hydrocarbon refrigerant migration accelerating under EU F-Gas Regulation constraints. Replacement cycles in Brazilian and Indian urban households are compressing from fifteen-year spans toward eight-year intervals as frost-free configurations displace direct-cool legacy stock.
- Washing Machines:Front-load drum assemblies with direct-drive motor elimination of belt-and-pulley systems reduce mechanical wear and enable vibration sensing for predictive maintenance. German and Dutch rental property portfolios are standardizing on A+++ rated units where operating cost visibility shapes landlord procurement decisions.
- Microwaves:Inverter power supply modules replace transformer-based architectures for defrosting precision and energy reduction in Japanese and South Korean product lines.
- Air Conditioners:Inverter-compressor platforms with R32 or R410A refrigerant circuits command procurement preference under India's Bureau of Energy Efficiency star-rating mandates.
Mature deployment sits with refrigerators. Newer deployment is concentrated in washing machines with heat pump dryer convergence.
End User:
Procurement authority and operating cost accountability determine specification intensity across residential and commercial installations.
- Households:Individual purchasers prioritize purchase price over ten-year operating cost in emerging markets, while European and North American buyers weight energy-label ratings more heavily. Connected appliance penetration is climbing fastest in middle-class Indian and Chinese urban households upgrading from first-generation electric equipment.
- Commercial Kitchens:High-cycle operation demands stainless steel construction, NSF certification, and service network proximity for refrigeration and cooking equipment. Energy-performance certificates in French and Spanish residential construction are pulling A+++ rated dishwashers into multi-unit rental portfolios.
- Hotels:Procurement consolidates through hospitality supply chains with standardized room configurations and centralized maintenance contracts.
- Rental Properties:Landlord capital expenditure constraints clash with tenant operating cost exposure, creating market space for appliance-as-a-service subscription models in German and Dutch urban markets.
Volume concentration rests with households. Margin expansion is steepest in rental properties through service revenue attachment.
Technology:
Control electronics and connectivity modules are migrating down price bands, collapsing the feature gap between flagship and mass-market tiers.
- Smart Appliances:Wi-Fi and Bluetooth connectivity with companion mobile applications enable remote cycle initiation and energy consumption monitoring. Firmware development talent scarcity in real-time operating systems and over-the-air update architectures constrains vendor roadmaps in European and North American engineering markets.
- Energy-Efficient Appliances:Inverter drives, vacuum insulation panels, and heat pump circuits deliver operating cost reductions that justify price premiums in markets with visible electricity tariffs. China's GB standards and India's Bureau of Energy Efficiency labeling impose parallel compliance test protocols that fragment product platform strategies.
- Conventional Appliances:Fixed-speed compressors and resistance heating elements maintain cost leadership in price-sensitive rural electrification contexts.
- IoT-Enabled Devices:Vibration sensors and cloud analytics integration enable failure prediction and service revenue streams in commercial laundry installations.
Installed base dominance belongs to conventional appliances. Connected functionality is gaining share fastest in smart appliances.
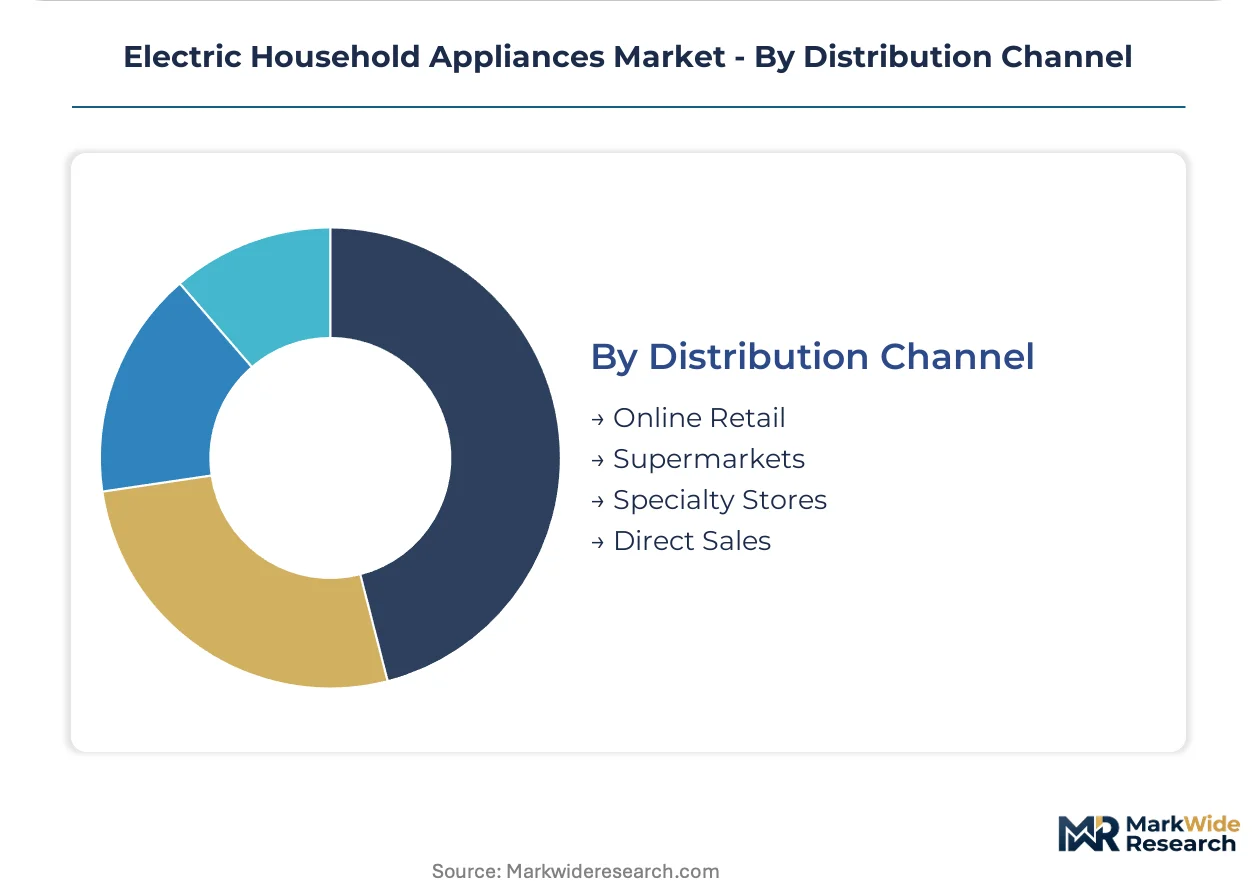
Distribution Channel:
Channel economics and installation service requirements shape category penetration and margin structures.
- Online Retail:Platform logistics networks handle compact appliances efficiently, while major cooling equipment requires last-mile installation partnerships. India's e-commerce penetration in tier-2 and tier-3 cities is accelerating first-time refrigerator and washing machine purchases beyond traditional dealer networks.
- Supermarkets:High-frequency traffic drives impulse replacement of small appliances and entry-level microwave ovens in Brazilian and Mexican retail formats.
- Specialty Stores:Trained sales staff and in-store demonstration capacity support premium-tier positioning for built-in refrigeration and induction cooking suites.
- Direct Sales:Manufacturer-controlled channels capture full margin in commercial kitchen and hospitality procurement with customized specification and service bundling.
Channel maturity centers on specialty stores. Digital migration is accelerating most quickly in online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban middle-class households in China, India, and Brazil are compressing replacement cycles and accelerating first-time purchases. Regulatory divergence across efficiency mandates and refrigerant protocols is fragmenting product platform strategies. Industrial clusters in Qingdao, Pune, and São Paulo are emerging as focal points for manufacturing investment and local supply chain development.
China
Tier-2 and tier-3 city electrification is pulling entry-level refrigerators and washing machines into first-time buyer households. The GB standards for energy efficiency impose compliance test protocols that manufacturers must satisfy for domestic market access. Qingdao's appliance manufacturing corridor hosts vertically integrated producers serving both domestic demand and export markets with hydrocarbon refrigerant platforms.
India
The Bureau of Energy Efficiency star-rating mandates for air conditioners and refrigerators are redirecting procurement toward inverter-compressor architectures. Village electrification under the Saubhagya scheme is creating demand for electric fans and entry-level cooling equipment in states with sub-thirty percent household penetration. Pune and Chennai industrial belts are scaling compressor motor assembly capacity to serve this expanding domestic market.
Brazil
Middle-class households in São Paulo and Rio de Janeiro are replacing legacy refrigeration units with frost-free models, compressing replacement cycles from fifteen years to eight. Federal energy efficiency labeling programs align with Mercosur technical regulations for cross-border trade. The Campinas manufacturing cluster is attracting component suppliers for linear compressor and variable-speed drive modules.
Germany
The EU Ecodesign Directive and F-Gas Regulation are forcing compressor redesigns and hydrocarbon refrigerant migration across cooling portfolios. Builder procurement for multi-unit rental portfolios is consolidating around A+++ rated dishwashers and washing machines to meet energy-performance certificate minimums. The BSH manufacturing footprint in Baden-Württemberg anchors European production of premium-tier built-in appliances.
United States
Federal appliance standards administered by the Department of Energy sustain margin pressure on manufacturers serving North American households. Connected appliance penetration is climbing fastest in metropolitan markets with visible electricity tariffs and smart grid infrastructure. The Midwest manufacturing corridor retains stamped metal forming and injection molding capacity for major cooling and cleaning equipment.
Electric Household Appliances Market Vendor Landscape
East Asian producers anchor one tier; European specialists hold premium positioning through built-in and integrated kitchen systems. The vendor base fragments across scale-driven conglomerates, component-integrated technology groups, and regional fabrication specialists. Three archetypes dominate: vertically integrated home appliance conglomerates with captive compressor production; electronics diversifiers leveraging semiconductor and display expertise; and European engineering-focused manufacturers emphasizing energy efficiency certification. Competitive moves center on backward integration into linear compressor technology and geographic expansion through localized assembly platforms.
Among East Asian conglomerates, Haier Smart Home Co., Ltd. and Midea Group exemplify scale-driven archetypes with integrated manufacturing footprints spanning multiple product categories. LG Electronics Inc. occupies a position within the technology-integrated tier, drawing on in-house capabilities in motor drive and control electronics. These three entities represent the dominant competitive postures in global household appliance supply, differentiated by degrees of vertical integration and regional market concentration.
| Leading Market Players |
|---|
| Haier Smart Home Co., Ltd. |
| Whirlpool Corporation |
| LG Electronics Inc. |
| Samsung Electronics Co., Ltd. |
| Electrolux AB |
| Midea Group |
| BSH Hausgeräte GmbH |
| Panasonic Corporation |
| GE Appliances |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign Directive mandates for stepped efficiency tiers are forcing compressor architecture redesigns that concentrate procurement power among suppliers with captive linear motor production, compressing margins for assembly-only manufacturers while rewarding backward-integrated producers. China's GB standards and India's Bureau of Energy Efficiency labeling impose parallel compliance test protocols that fragment platform economics and stretch certification timelines.
Pricing Analysis
Volume concentrates in entry-level conventional appliances while margin pools sit with premium inverter-compressor platforms and connected functionality tiers. Pricing stratifies across A+++ certified premium, mid-tier inverter-drive standard, and fixed-speed economy levels, with differentiation driven by energy-label grade and after-sales service bundling. Cost compression in mid-tier refrigeration is intensifying because hydrocarbon refrigerant migration demands sealed-system retooling. Emerging-market households exhibit highest price sensitivity, while European rental property portfolios weight ten-year operating cost over purchase price.
Supply Chain Analysis
Single-source vulnerability sits with neodymium rare-earth magnet suppliers concentrated in China's Inner Mongolia processing corridor, with secondary concentration in Vietnamese magnet assembly operations. Compressor motor production draws from copper winding stock, neodymium permanent magnets, and silicon steel laminations sourced from China, Japan, and South Korea. Tariff exposure runs through cross-border component flows between East Asian fabrication hubs and regional assembly plants. Distribution runs through manufacturer-direct channels for commercial kitchens, specialty retail for premium built-in suites, and platform logistics networks for compact appliance online retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Linear compressor manufacturing capacity constraints are propping pricing power for vertically integrated producers while constraining volume expansion for assembly-dependent competitors, creating a supply-constrained market structure through the projection horizon.
For Market Incumbents: Extend captive production of linear compressor technology to reduce dependency on external motor suppliers and defend margin structures against emerging Asian conglomerates with integrated manufacturing footprints. Prioritize certification investment for EU F-Gas Regulation hydrocarbon refrigerant compliance to maintain European market access. Channel control through direct sales relationships with hospitality procurement consolidates pricing power in commercial segments. For New Entrants and Emerging Players: Launch via appliance-as-a-service subscription platforms in German and Dutch urban rental markets where landlord capital constraints create white-space demand for usage-rights decoupled from purchase. Target underpenetrated rural India village electrification corridors for entry-level electric fans and direct-cool refrigerators, leveraging India's e-commerce platform logistics to bypass traditional dealer networks. Focus on firmware development partnerships to overcome embedded systems talent scarcity in European engineering markets. For Investors and Strategic Acquirers: The window for entry favors component-integrated technology groups with in-house motor drive and control electronics capabilities over pure-brand consumer goods plays. Long-term viability rests on five-to-ten year positioning around predictive maintenance service revenue attachment and IoT-enabled failure prediction analytics. The signal to watch is consolidation pace among compressor motor assembly specialists in Pune and Chennai industrial belts as domestic Indian demand scales.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Linear Compressor Manufacturing | Captive motor production reduces neodymium magnet cost volatility exposure for refrigeration portfolios. |
| Hydrocarbon Refrigerant Platform Migration | EU F-Gas Regulation compliance enables continued European market access for cooling appliance lines. |
| Appliance-as-a-Service Subscription Launch | German and Dutch rental property portfolios create recurring revenue pools decoupled from capital expenditure cycles. |
| Predictive Maintenance Capability Development | Vibration sensor and cloud analytics integration unlocks service revenue attachment in commercial laundry installations. |
| Rural India E-Commerce Channel Expansion | Tier-2 and tier-3 city platform penetration accelerates first-time buyer access beyond traditional dealer networks. |
Methodological Framework
Multi-period observation of Bureau of Energy Efficiency star-rating adoption curves, EU Ecodesign Directive compliance timelines, and inverter-compressor penetration rates anchored the trend analysis, supplemented by interviews with appliance manufacturing plant managers, procurement leads at hospitality supply chains, compressor motor R&D directors, and channel sales heads at specialty retailers. Secondary validation drew from customs and trade data, SEC 10-K filings of listed appliance conglomerates, national energy regulator efficiency program disclosures, and retail audit databases. Bottom-up product platform economics and top-down macro demand projections were triangulated to constrain forecast variance.
Segment-weighting across product type, technology tier, end-user procurement authority, and distribution channel shaped the analytical framework, with regional regulatory cluster effects modeled throughout the forecast period. CAGRs were derived from replacement cycle compression rates in Brazilian and Indian urban households, first-time purchase curves in village electrification corridors, and efficiency mandate-driven upgrade elasticities in European markets. Compressor architecture transition timelines and connectivity module cost decline curves served as industry-specific forecast inputs.
Copper and rare-earth magnet price volatility, refrigerant chemistry regulatory divergence, and induction cooking substitution in Southeast Asian gas infrastructure expansion corridors are the dominant revision risks that could shift volume and value trajectories. Forecasts reflect assumptions around electrification pace, middle-class expansion rates, and efficiency mandate enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Range Hood Market
Home Appliances
Europe White Goods Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Residential Dishwashers Market
Home Appliances
North America Home Appliances Market
Home Appliances
Germany Home Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Connected Home Appliances Market
Home Appliances
China Home Appliances Market
Home Appliances
North America Small Home Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
Saudi Arabia Small Home Appliances Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Built-In Hobs Market