
 Cooker Hoods Market | 2026-2036
Cooker Hoods Market Size, Share, and Industry Trends Forecast 2026-2036
Cooker Hoods Market Outlook
Multi-source component procurement is expanding across the cooker hoods supply base as manufacturers diversify motor and filtration sourcing beyond single-origin dependencies. Elica S.p.A. leverages its Italian design heritage to dominate European premium channels. BSH Home Appliances Group sustains R&D intensity across integrated kitchen ecosystems. Faber S.p.A. anchors its competitive position through specialized chimney and island hood architectures.
A cooker hood is a mechanical ventilation appliance installed above cooking surfaces, typically employing centrifugal or axial fans rated between 200 and 1,200 cubic meters per hour to extract grease, smoke, odors, and combustion byproducts from kitchen environments. Wall-mounted configurations occupy the largest installed base globally due to compatibility with standard residential layouts and straightforward duct routing. Smart technology segments are gaining traction fastest as IoT-enabled sensors automate fan speed adjustment based on particulate detection and ambient humidity levels.
EU Ecodesign regulations and CE marking requirements under EN 13141-1 mandate minimum energy-efficiency indexes and maximum sound power thresholds for residential ventilation units sold in Europe. The US Department of Energy and EPA ENERGY STAR program shape North American demand through certified efficiency benchmarks that influence consumer purchasing decisions and builder specification defaults. Stakeholders must monitor evolving particulate-matter filtration standards and interoperability protocols as kitchen ventilation converges with broader smart-home platforms.
Market Dynamics
EU Ecodesign regulations are compressing product lifecycles across the cooker hoods sector, forcing manufacturers to redesign motor architectures and filtration systems ahead of mandatory efficiency deadlines. This regulatory pressure is reshaping competitive positioning between integrated kitchen system suppliers and standalone ventilation specialists.
Growth Catalysts
- EN 13141-1 compliance mandates:European ventilation standards are accelerating replacement cycles as builders and renovators pre-emptively upgrade to certified systems before enforcement deadlines tighten.
- Smart sensor convergence:IoT-enabled particulate detection and humidity-responsive fan control are penetrating premium residential segments in Germany and the Netherlands.
- Urban middle-class kitchen upgrades:Households in Shanghai and Mumbai are shifting from recirculating to ducted extraction systems as apartment infrastructure modernizes.
Market Restraints
- Copper and rare-earth motor magnet volatility:Input cost swings for permanent-magnet synchronous motors compress margin visibility for mid-tier manufacturers.
- Single-source blower assembly concentration:Italian and Chinese motor suppliers control critical centrifugal fan capacity, creating supply vulnerability during demand spikes.
- Recirculating charcoal filter performance ceiling:Technical limitations in grease capture efficiency versus ducted systems restrict adoption in high-heat cooking environments.
Strategic Opportunities
- Underpenetrated Indian metropolitan markets:Bangalore and Hyderabad exhibit low ducted hood penetration relative to comparable-income Asian cities, creating first-mover whitespace.
- ENERGY STAR certification tailwinds:US federal efficiency benchmarks are shifting builder specification defaults toward certified models in multi-family residential construction.
- Voice-control and recipe-API convergence:Integration between hood automation and smart-home platforms is opening premium positioning in connected kitchen ecosystems.
Industry Challenges
- Acoustic engineering talent scarcity:Specialized noise-reduction expertise for high-CFM low-decibel designs concentrates in German and Italian engineering clusters.
- Multi-certification timeline compression:Simultaneous CE marking, ENERGY STAR, and country-specific electrical approvals extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooker Hoods Market |
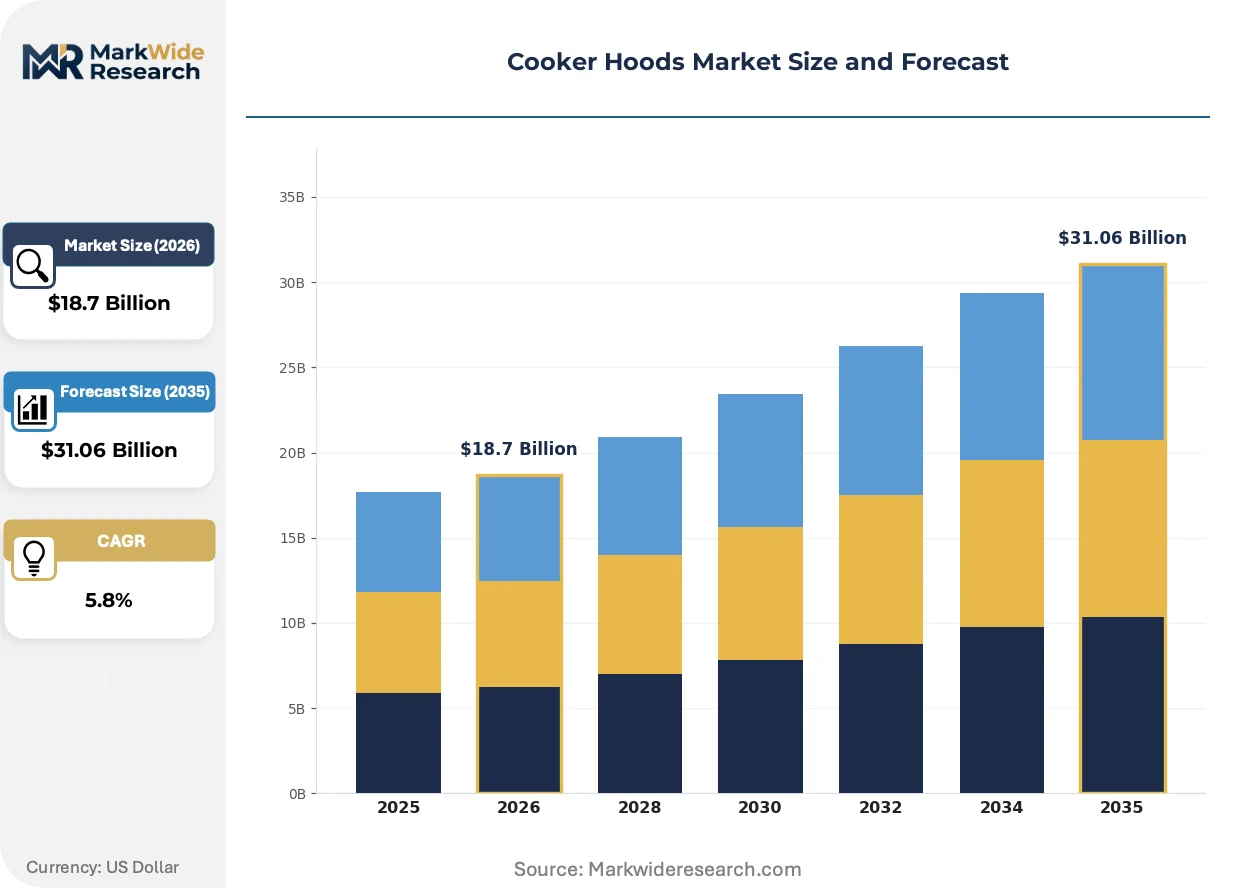
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Under-Cabinet, Downdraft, Island Technology: ductless, Ducted, Hybrid, Smart End User: Residential, Commercial, Industrial, Hospitality Operation Mode: Manual, Automatic, Sensor-Activated, Remote-Controlled |
| Companies Covered | BSH Home Appliances Group, Elica S.p.A., Broan-NuTone, LLC, AB Electrolux, Falmec Kitchen Appliance Limited, Faber S.p.A., Whirlpool Corporation, GE Appliances, Zephyr Ventilation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooker Hoods Market Strategic Shifts
Active noise cancellation and edge-computing sensors are redefining performance benchmarks across the cooker hoods sector. Manufacturers are racing to embed intelligence that anticipates cooking activity rather than merely reacting to it.
Perimeter suction technology is integrating continuous-slot extraction geometries that capture grease and smoke at lower airflow rates than traditional chimney designs. High-end kitchen studios in Milan and Copenhagen are specifying these systems for open-plan residential layouts. The technology is integrating reduced duct diameter requirements that ease retrofit installation in historic European building stock.
REACH chemical restrictions are phasing out certain flame-retardant coatings previously used in motor housings and control enclosures. Manufacturers are reformulating polymer compounds to maintain thermal stability without restricted substances. German and French certification bodies are accelerating testing protocols to validate substitute materials ahead of sunset dates.
Builder procurement consolidation is compressing vendor lists as multi-family developers standardize on single-source ventilation packages. National homebuilders in the US and volume developers in Spain are negotiating multi-year supply agreements that displace spot-market purchasing. This concentration is most visible in Madrid and Dallas-Fort Worth metropolitan construction pipelines.
Cooker Hoods Market Segmentation
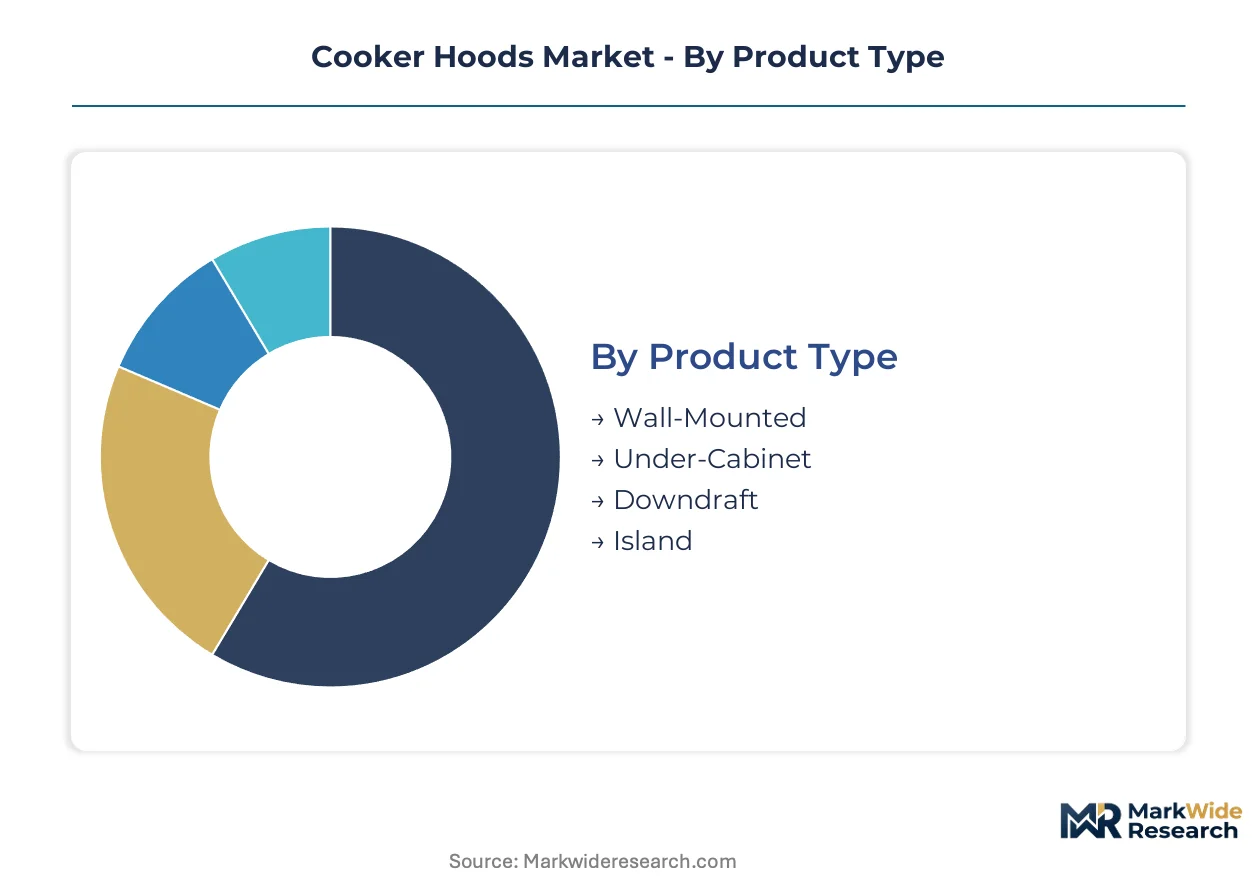
Segmentation in cooker hoods reflects divergent kitchen architectures, ventilation infrastructure maturity, and automation readiness across residential and commercial installations. Manufacturers configure motor assemblies, filtration media, and control interfaces differently for each slice, creating distinct margin profiles and certification pathways.
Product Type:
Standardization dominates at the entry level, while premium kitchens demand bespoke island and downdraft geometries that force custom duct engineering.
- Wall-Mounted:Vertical chimney configurations attach directly to rear walls above ranges, utilizing 150-200mm round ducting that routes through standard cavity construction. Builders in Madrid and Dallas-Fort Worth specify these for multi-family residential volume, driven by straightforward retrofit compatibility and ENERGY STAR certification eligibility.
- Island:Suspended ceiling-mounted units extract from cooktops positioned away from walls, requiring 250-400mm duct drops and reinforced structural support. Demand clusters in open-plan luxury renovations across Milan and Copenhagen, where perimeter suction technology enables lower airflow rates without compromising capture efficiency.
- Under-Cabinet:Compact horizontal units integrate into cabinetry above ranges, routing through concealed soffits.
- Downdraft:Retractable surface-integrated systems rise from countertops, eliminating overhead visual obstruction.
Most installed capacity flows through Wall-Mounted. Expansion is steepest in Island.
Technology:
Cost tiers separate recirculating entry systems from ducted mid-market workhorses and sensor-enabled premium platforms.
- Ducted:Direct exterior-venting systems achieve 90%+ grease and odor removal through metal baffle filters and continuous airflow paths. Urban middle-class households in Shanghai and Mumbai are upgrading to these as apartment infrastructure modernizes, displacing recirculating units that dominate legacy installations.
- Smart:IoT-enabled platforms embed particulate sensors, humidity detectors, and edge-computing controllers that anticipate cooking activity rather than react to it. German and Dutch premium segments are absorbing these fastest, where EN 13141-1 compliance mandates intersect with voice-control and recipe-API convergence.
- Ductless:Charcoal-filter recirculating systems suit buildings without exterior duct access, though grease capture ceilings constrain high-heat applications.
- Hybrid:Switchable platforms alternate between recirculating and ducted modes based on seasonal or installation constraints.
Ducted systems anchor current revenue. Smart configurations are gaining share fastest.
End User:
Application intensity varies sharply: residential cycles peak during renovation seasons, while commercial and hospitality demand tracks new construction permits and franchise rollout schedules.
- Residential:Single-family and multi-family households drive replacement cycles tied to kitchen renovation timelines. North American and European markets are accelerating upgrades as EU Ecodesign regulations compress product lifecycles ahead of mandatory efficiency deadlines.
- Hospitality:Hotels, restaurants, and catering facilities require high-CFM systems with fire suppression integration and continuous-duty motor ratings. Procurement concentrates through national foodservice equipment distributors in the US and specialized kitchen studio channels in France and Italy.
- Commercial:Corporate cafeterias, institutional kitchens, and retail food courts specify standardized ventilation packages.
- Industrial:Heavy-duty extraction for manufacturing canteens and processing facilities demands corrosion-resistant construction.
Residential channels handle the greatest unit volume. Hospitality exhibits the steepest specification upgrade trajectory.
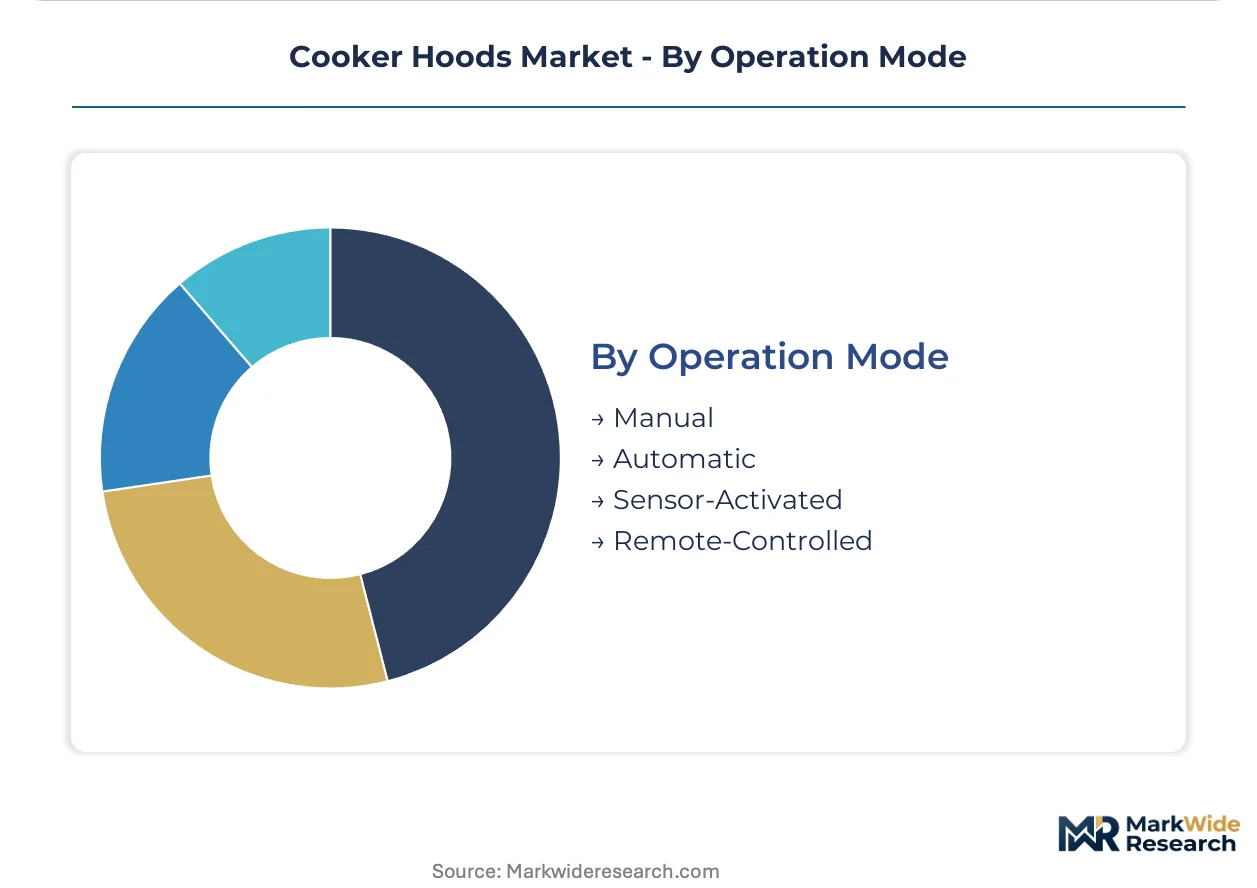
Operation Mode:
Customer type stratification separates price-sensitive manual buyers from automation-seeking premium purchasers and compliance-driven commercial specifiers.
- Automatic:Microprocessor-controlled systems adjust fan speed through preset algorithms responding to heat and humidity thresholds. These dominate mid-market builder specifications where ENERGY STAR defaults and multi-family developer procurement consolidation favor standardized, low-touch operation.
- Sensor-Activated:Real-time particulate and VOC detection triggers immediate fan response, minimizing energy waste and noise exposure. Adoption concentrates in German and Italian premium residential segments where acoustic engineering expertise enables high-CFM low-decibel designs.
- Manual:Push-button or slider controls persist in rental housing and budget replacement segments.
- Remote-Controlled:Handheld or wall-mounted wireless interfaces suit island installations and accessibility requirements.
Automatic platforms command the broadest installed base. Sensor-Activated is climbing the fastest among premium renovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing manufacturing footprints as producers seek jurisdictions with favorable cost-of-compliance profiles. The EU Ecodesign framework imposes stringent efficiency mandates that accelerate redesign cycles, while Asian production hubs capture volume through modular assembly ecosystems.
United States
Multi-family residential construction in Dallas-Fort Worth and Phoenix drives specification demand for ENERGY STAR-certified wall-mounted systems. The EPA ENERGY STAR program shapes builder procurement defaults through certified efficiency benchmarks. National homebuilders negotiate multi-year supply agreements that displace spot-market purchasing across Texas and Arizona metropolitan pipelines.
Germany
Premium kitchen renovations in Munich and Hamburg absorb sensor-activated platforms with voice-control integration. The country's national energy regulator enforces Bundes-Immissionsschutzgesetz ventilation standards that exceed baseline EU requirements. Engineering clusters in Stuttgart concentrate acoustic expertise for high-CFM low-decibel motor architectures.
China
Urban middle-class households in Shanghai and Hangzhou upgrade from recirculating to ducted extraction as apartment infrastructure modernizes. The Ministry of Ecology and Environment enforces GB standards for residential ventilation efficiency that align with dual carbon goals. Manufacturing concentration in Ningbo and Zhongshan supplies centrifugal fan assemblies for European OEM sourcing.
India
Metropolitan markets in Bangalore and Hyderabad exhibit low ducted hood penetration relative to comparable-income Asian cities, creating first-mover whitespace. The Bureau of Indian Standards mandates ISI certification for electrical safety in kitchen appliances. Real estate development in Gurugram and Pune integrates ventilation specifications into premium residential tower construction.
Italy
Milan and Bologna kitchen studios specify perimeter suction island configurations for open-plan luxury renovations. CE marking requirements under EN 13141-1 mandate minimum energy-efficiency indexes for residential ventilation units. Design heritage clusters in Marche and Veneto anchor European premium channel distribution through specialized retail networks.
Cooker Hoods Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue smart-home integration and voice-control convergence. The sector exhibits moderate consolidation with integrated kitchen system suppliers competing against standalone ventilation specialists. Three archetypes dominate: heritage design houses leveraging aesthetic differentiation, appliance conglomerates with captive distribution, and component specialists controlling critical motor capacity. Competitive moves concentrate on strategic partnerships with smart-home platforms and geographic expansion into underpenetrated Asian metropolitan markets.
Within the heritage design tier, Elica S.p.A. and Faber S.p.A. represent Italian engineering tradition through specialized chimney and island hood architectures. BSH Home Appliances Group exemplifies the integrated ecosystem approach across European and North American builder channels. These three anchors illustrate how competitive positioning splits between aesthetic authority, manufacturing scale, and platform integration capabilities.
| Leading Market Players |
|---|
| BSH Home Appliances Group |
| Elica S.p.A. |
| Broan-NuTone, LLC |
| AB Electrolux |
| Falmec Kitchen Appliance Limited |
| Faber S.p.A. |
| Whirlpool Corporation |
| GE Appliances |
| Zephyr Ventilation |
| Others |
Value Chain & Pricing Dynamics
EU Ecodesign regulation deadlines are compressing procurement timelines across European builder channels, forcing manufacturers to absorb motor redesign costs while holding contract pricing for multi-year supply agreements. This specification-driven cost pressure is reshaping how tier-one suppliers negotiate blower assembly sourcing from Italian and Chinese motor specialists.
Pricing Analysis
Copper and rare-earth magnet cost pass-through dominates pricing dynamics across permanent-magnet synchronous motor tiers. Three-tier pricing structure across premium sensor-activated, standard automatic, and economy manual levels separates certification grade from acoustic engineering investment. Pricing pressure stems from mid-tier margin compression as ENERGY STAR defaults shift builder specifications toward certified efficiency tiers. Residential renovators in North America exhibit highest price sensitivity, while hospitality specifiers in Milan and Copenhagen prioritize fire suppression integration over unit cost.
Supply Chain Analysis
Centrifugal fan assembly supply rests on manufacturing clusters in Ningbo and Zhongshan, China, alongside Italian motor engineering centers in Emilia-Romagna. Critical inputs include copper windings, neodymium permanent magnets, and galvanized steel ducting. Single-source blower assembly concentration creates vulnerability during demand spikes in Dallas-Fort Worth and Madrid construction cycles. Distribution runs through national homebuilder procurement consolidation and specialized kitchen studio channels across European premium markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Ecodesign efficiency mandates and EN 13141-1 compliance deadlines are accelerating replacement demand ahead of enforcement dates.
For Market Incumbents: Acquire acoustic engineering talent clusters in Stuttgart and Bologna to defend premium positioning against emerging smart-home platform entrants. Secure captive supply of rare-earth magnet motors through backward integration into Chinese component sourcing. Reinforce channel control through multi-year ENERGY STAR certification bundling with national homebuilder procurement consolidation. For New Entrants and Emerging Players: Capture underpenetrated ducted hood whitespace in Bangalore and Hyderabad metropolitan markets where ISI certification barriers remain surmountable. Target hospitality specification channels in French and Italian foodservice equipment distribution. Pursue voice-control integration partnerships with smart-home platform providers as primary go-to-market differentiation. For Investors and Strategic Acquirers: Asymmetric upside sits with component specialists controlling centrifugal fan capacity amid motor magnet volatility. Long-term viability favors acquisition targets with established CE marking pathways and ENERGY STAR certification infrastructure. Watch EN 13141-1 enforcement timeline compression as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Sensor Platform Integration | IoT-enabled particulate detection automates fan response in German premium renovations. |
| Perimeter Suction Technology Licensing | Continuous-slot extraction geometries enable lower airflow retrofit in historic European building stock. |
| Backward Integration into Motor Manufacturing | Captive rare-earth magnet sourcing insulates margins from copper price volatility. |
| ENERGY STAR Certification Investment | EPA benchmarks shift builder defaults toward certified models in Texas multi-family construction. |
| Voice-Control API Partnership | Recipe-integrated automation opens premium positioning in connected kitchen ecosystems. |
Study Parameters
Multiple input streams — primary interviews with appliance R&D directors, procurement leads at national homebuilders, and kitchen studio specification consultants — were reconciled against secondary validation from EPA ENERGY STAR certification databases, EU Ecodesign regulatory filings, and customs trade records. Bottom-up unit shipment modeling across wall-mounted, island, and downdraft configurations was triangulated with top-down value estimates from manufacturer revenue disclosures.
Historical volume trajectories were cross-referenced against panel input from engineering clusters in Stuttgart and Ningbo to derive expansion rates across the projection horizon. Segmentation dimensions modeled include product architecture, ventilation technology tier, end-use intensity, and automation mode. CAGRs reflect reconciliation between regulatory deadline impacts and infrastructure modernization timelines in Shanghai and Mumbai apartment markets.
Raw material cost spikes, enforcement timeline delays, and smart-home platform interoperability failures are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about builder procurement consolidation velocity and ducted infrastructure penetration rates. A small set of named triggers — copper volatility, CE marking backlog, and voice-control standard adoption — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Egypt Microwave Ovens Market
Appliances
Window Air Conditioners Market
Appliances
APAC White Goods Market
Appliances
Electric Ranges Market
Appliances
UAE Dishwasher Market
Appliances
Electric Dryers Market
Appliances
Asia Pacific Household Side by Side Refrigerator Market
Appliances
Electrical Appliances Plastics Market
Appliances
Water Dispenser Market
Appliances
China Washing Machine Market
Appliances
Glass Ceramic Cooktop Market
Appliances
United States Electric Kettle Market
Appliances
Microwave Oven Market
Appliances
Portable Dishwasher Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
Refrigerator Repair Service Market