
 Kitchen Chimney Market | 2026-2036
Kitchen Chimney Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Chimney Market Analytics
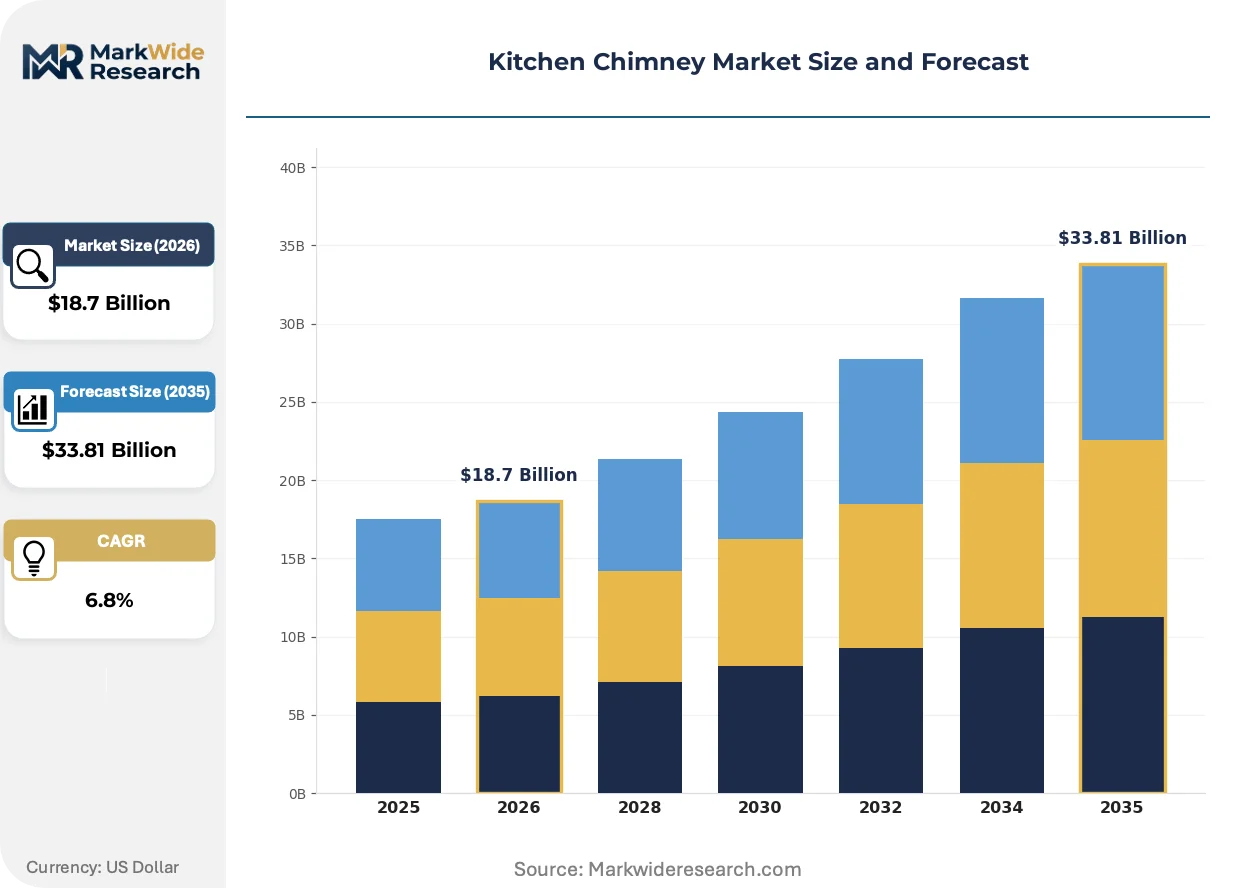
Smart sensor integration is fragmenting the kitchen chimney technology stack into modular, IoT-enabled ventilation ecosystems. Elica S.p.A. leverages Italian design heritage to dominate European premium channels. Hindware anchors mass-market penetration across Indian metro kitchens through localized distribution. Samsung Electronics competes on connected-home interoperability with its broader appliance portfolio.
A kitchen chimney is a mechanical ventilation device that extracts airborne grease, combustion products, smoke, odors, and steam from kitchen air through suction motors rated between 800 and 1500 cubic meters per hour, using baffle or filterless separation technology to maintain indoor air quality and surface cleanliness. Wall-mounted units lead volume globally due to universal compatibility with standard kitchen layouts, while filterless technology captures the fastest growth trajectory as maintenance-averse consumers reject periodic filter replacement costs. Island chimney configurations command premium positioning in open-plan residential architecture where ducted extraction paths must route through ceiling structures.
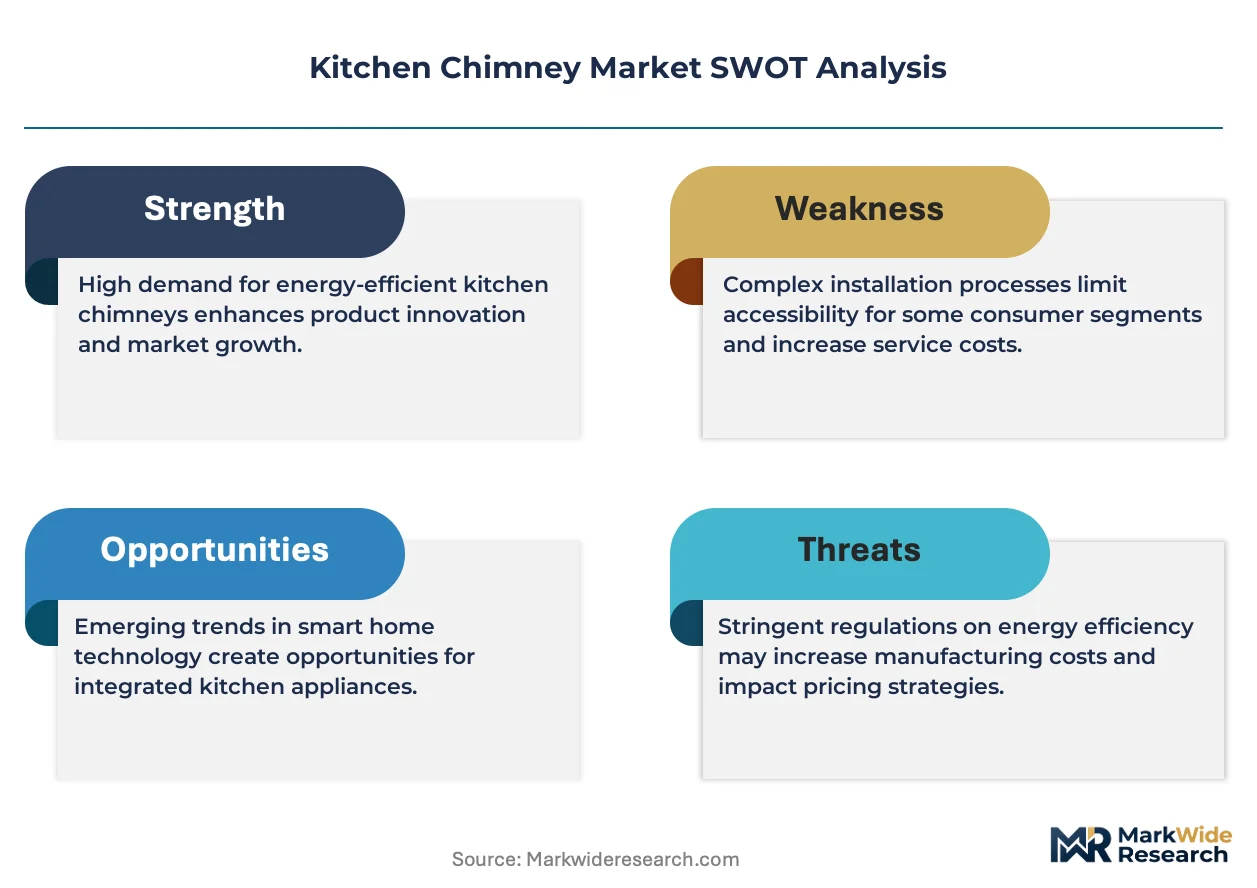
India's BIS mandates minimum suction efficiency thresholds and noise level caps, while EU Ecodesign regulations under the EU Green Deal enforce motor energy consumption limits that disqualify legacy models from CE-marked sale. The US EPA and OSHA indirectly shape commercial kitchen specifications through indoor air quality guidelines for food service worker safety. Stakeholders must monitor how tightening energy standards in Europe and Asia-Pacific will bifurcate product portfolios between compliance-driven redesigns and market withdrawal.
Market Dynamics
Filterless separation technology is compressing maintenance cycles and redirecting consumer preference toward premium-priced units, while BIS energy efficiency mandates in India force synchronous motor redesigns across manufacturing bases.
Growth Catalysts
- Urban kitchen renovation intensity:Tier-1 Indian cities and Southeast Asian metropolitan clusters are accelerating replacement demand as residential real estate turnover rises.
- BIS motor performance standards:India's mandatory energy efficiency labeling creates compliance-driven upgrade cycles that pull consumers toward certified higher-suction models.
- IoT-enabled ventilation ecosystems:Smart sensor integration is fragmenting the technology stack into modular, connected-home-compatible subsystems.
Market Restraints
- Copper and rare-earth magnet costs:Suction motor manufacturing faces input price volatility from concentrated Chinese rare-earth processing and Chilean copper supply.
- CE marking exclusion risk:EU Ecodesign regulations under the EU Green Deal threaten to disqualify legacy motor architectures from European sale.
- Ducted installation complexity:Island chimney configurations require ceiling-routed extraction paths that limit retrofit applicability in existing residential stock.
Strategic Opportunities
- Filterless technology convergence:Oil-capture centrifugal systems combined with self-cleaning automation create maintenance-free value propositions for time-constrained households.
- Indian tier-2 city expansion:Underpenetrated secondary urban centers offer distribution whitespace beyond saturated Delhi, Mumbai, and Bangalore markets.
- Connected-home interoperability:Integration with broader appliance portfolios enables ecosystem lock-in and recurring service revenue streams.
Industry Challenges
- Cross-border certification timelines:Simultaneous BIS, CE, and UL compliance creates product launch delays and portfolio fragmentation.
- Installation skill scarcity:Ducted and island configurations demand specialized HVAC technician labor that remains concentrated in major metropolitan labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Chimney Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Chimney Hood, Island Chimney, Under-Cabinet Technology: Filterless, Ductless, Ducted, Activated Carbon End User: Residential, Commercial, Industrial, Hospitality Feature: Smart Control, Touch Control, LED Lighting, Powerful Suction |
| Companies Covered | Whirlpool Corporation, LG Electronics, Elica S.p.A., Hindware, Panasonic Holdings Corporation, Faber S.p.A., Robert Bosch GmbH, KAFF, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Chimney Market Evolving Landscape
Active sensor networks and automated cleaning mechanisms are redefining the chimney from passive exhaust hardware to intelligent air quality infrastructure, with regulatory pressure and behavioral shifts reinforcing this trajectory.
Filterless centrifugal separation is digitizing maintenance scheduling through embedded pressure sensors that monitor oil accumulation and trigger automated cleaning cycles. Premium residential buyers in Indian metro markets are adopting these units at accelerating rates, compressing the traditional 6-month filter replacement interval to zero-touch operation. This digitization is enabling manufacturers to unbundle hardware from recurring service contracts.
EU Ecodesign regulations under the EU Green Deal enforce motor energy consumption limits that disqualify legacy induction motor architectures from CE-marked sale. Manufacturers serving European channels must redesign winding configurations and magnet materials to comply, raising unit costs but creating regulatory moats against non-compliant imports. Wall-mounted product lines face the steepest redesign burden given their volume concentration.
After-sales service unbundling is disrupting the traditional bundled installation-and-warranty model across Indian distribution channels. Third-party platform aggregators are capturing chimney installation and annual maintenance contracts, disintermediating brand-authorized service networks. This channel shift is most visible in Bangalore and Hyderabad, where digital-native consumers prefer app-scheduled technician dispatch over dealer-mediated service relationships.
Kitchen Chimney Market Segmentation
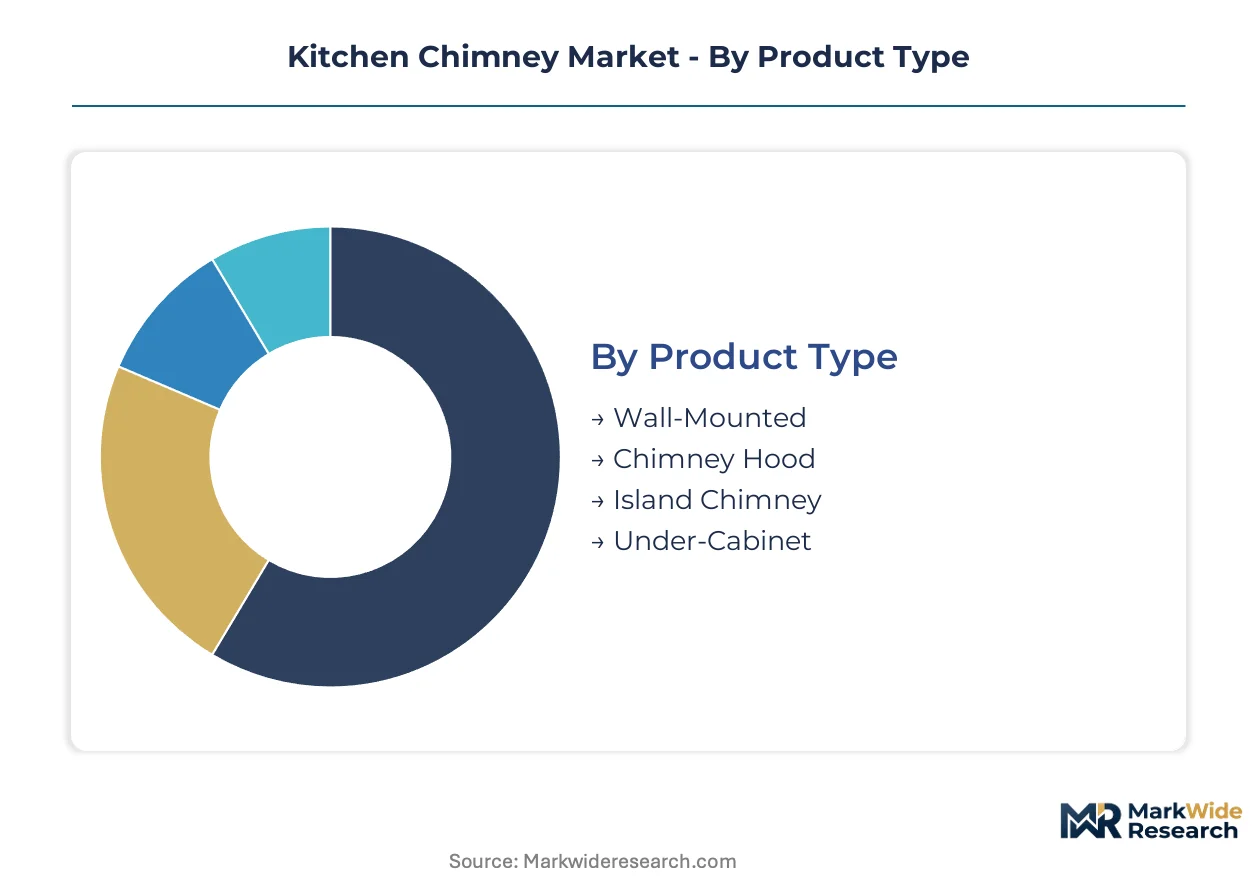
Kitchen chimney segmentation reveals how installation constraints, air handling physics, and user sophistication split demand into distinct value tiers. Product architecture and technology choices determine margin structures and replacement cycles across residential and commercial applications.
Product Type:
Installation geometry defines the use-case spectrum from compact urban apartments to expansive open-plan residences.
- Wall-Mounted:These units attach directly to vertical kitchen surfaces above cooktops, accommodating standard ceiling heights and existing ductwork paths. Demand concentrates in Indian metro renovations where space constraints favor vertical extraction without structural ceiling modifications. BIS energy efficiency mandates are accelerating replacement of legacy models in Delhi and Mumbai residential stock.
- Island Chimney:Ceiling-suspended configurations serve open-plan kitchens lacking perimeter walls, requiring routed ducting through overhead structures. Premium positioning in Southeast Asian metropolitan clusters reflects architect-specified installations in high-end residential developments where cooking islands anchor social spaces.
- Chimney Hood:Integrated canopy designs merge extraction hardware with overhead cabinetry, preserving visual continuity in compact kitchens. European channels favor these units for retrofit compatibility with existing cabinet systems.
- Under-Cabinet:Space-efficient units mount beneath overhead storage, sacrificing suction capacity for footprint reduction. Rental housing and budget renovations in tier-2 Indian cities drive volume here.
The dominant share belongs to Wall-Mounted, while Island Chimney is closing the gap fastest.
Technology:
Cost tier separates maintenance-heavy legacy systems from capital-intensive automation.
- Filterless:Centrifugal oil-separation eliminates consumable filters through spinning turbine mechanics that deposit grease in collection chambers. Indian metro buyers facing technician scarcity are adopting these units to eliminate 6-month replacement cycles. Self-cleaning automation enabled by pressure sensors is digitizing service revenue for manufacturers.
- Ducted:Direct exterior venting through rigid ductwork delivers maximum extraction efficiency for heavy-use cooking environments. Commercial kitchens in US food service operations specify these units to meet OSHA indoor air quality guidelines for worker safety.
- Ductless:Recirculating configurations pass air through activated carbon and grease filters before returning it to the kitchen, avoiding structural ducting. Apartment retrofits in dense European urban centers rely on these where exterior wall penetration is prohibited.
- Activated Carbon:Adsorption-based odor neutralization layers supplement primary grease capture in hybrid extraction systems. Hospitality applications in Southeast Asian hotel kitchens combine carbon stages with primary baffle separation.
Filterless technology commands expanding margin premiums, whereas Ducted maintains volume leadership in commercial specification.
End User:
Application maturity determines specification stringency and procurement channel.
- Residential:Individual household installations dominate unit volume, with renovation cycles driving replacement timing. Tier-1 Indian cities and Southeast Asian metropolitan clusters concentrate demand as real estate turnover accelerates kitchen upgrades.
- Commercial:Food service operations require continuous-duty motors and fire suppression integration, with procurement running through HVAC contractors rather than retail channels. US EPA guidelines indirectly shape specifications through indoor air quality enforcement.
- Hospitality:Hotel and restaurant chains standardize across properties, creating volume procurement leverage and long-term service contracts. Brand-authorized networks compete with third-party platform aggregators for maintenance revenue in Bangalore and Hyderabad.
- Industrial:Centralized kitchen facilities and institutional food production specify heavy-gauge construction and extended motor warranties. Compliance with national occupational safety regulators drives specification in each operating geography.
Residential claims the dominant installed base, while Hospitality is expanding most quickly through chain standardization.
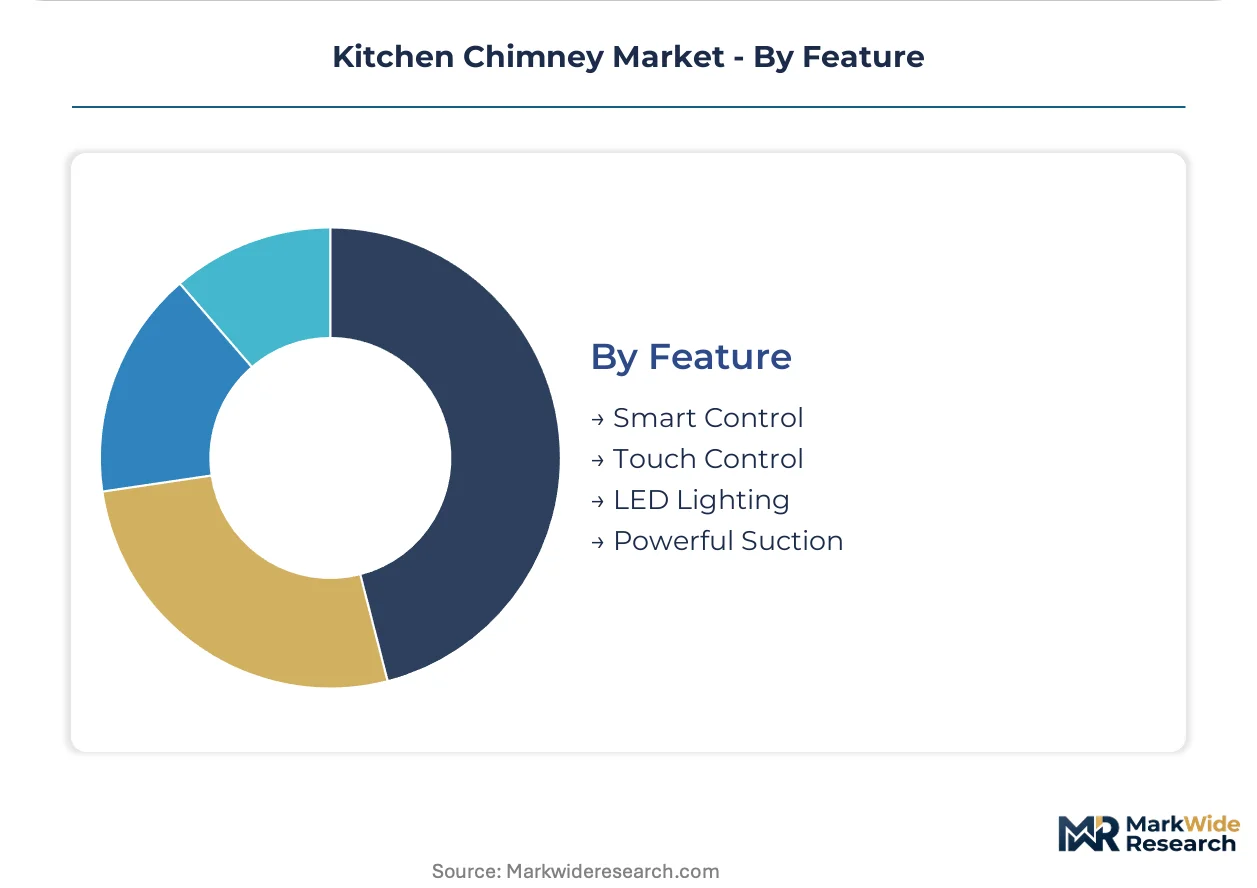
Feature:
Customer sophistication stratifies between basic functionality and ecosystem integration.
- Powerful Suction:High-capacity motors rated 1200-1500 cubic meters per hour address heavy frying and spice-intensive cooking. Indian BIS minimum efficiency thresholds are disqualifying low-suction legacy models from certified sale.
- Smart Control:IoT-enabled units integrate with connected-home platforms, enabling remote activation and air quality monitoring. Samsung Electronics leverages appliance portfolio interoperability to differentiate against standalone competitors.
- Touch Control:Capacitive interfaces replace mechanical switches, improving cleanability and aesthetic integration. Mass-market penetration across Indian metro kitchens favors these interfaces for durability in humid environments.
- LED Lighting:Integrated task illumination reduces countertop shadowing while consuming less energy than halogen predecessors. EU Ecodesign regulations under the EU Green Deal accelerate LED adoption through efficiency mandates.
Powerful Suction retains specification priority, though Smart Control is gaining share fastest through ecosystem lock-in strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for rare-earth magnets and copper windings shapes regional manufacturing competitiveness, with assembly concentration tilting toward markets with stringent energy efficiency enforcement.
India
Urban kitchen renovation intensity in Delhi, Mumbai, and Bangalore accelerates replacement cycles for legacy suction units. BIS energy efficiency labeling mandates stricter motor performance standards that disqualify uncertified models from retail channels. Manufacturing clusters in Gujarat and Tamil Nadu are retooling for synchronous motor production to meet compliance deadlines.
China
Domestic demand for filterless centrifugal systems expands as maintenance-averse households in Shanghai and Shenzhen upgrade from baffle-filter designs. MIIT efficiency standards for household appliances tighten motor energy consumption thresholds. Zhejiang and Guangdong provinces concentrate export-oriented production serving Southeast Asian distribution networks.
Germany
CE marking requirements under EU Ecodesign regulations enforce motor energy limits that reshape product portfolios for European distribution. REACH compliance obligations constrain material selection for grease-separation components. Industrial clusters in North Rhine-Westphalia and Bavaria engineer high-efficiency winding configurations for premium channel supply.
United States
Commercial kitchen specifications respond to OSHA indoor air quality guidelines for food service worker safety, driving ducted system demand. EPA indirect enforcement through ventilation standards influences HVAC contractor procurement. Metropolitan construction in Texas and Florida absorbs island chimney configurations for open-plan residential architecture.
Italy
Design-driven premium positioning leverages CE marking as a regulatory moat against non-compliant imports. EU Green Deal implementation accelerates phase-out of legacy induction motor architectures. Manufacturing concentration in Emilia-Romagna supplies wall-mounted and island configurations to architect-specified residential developments across Southern Europe.
Kitchen Chimney Market Competitive Landscape
On the supply side, the industry is bifurcated between appliance conglomerates with connected-home portfolios and specialized ventilation manufacturers with regional distribution depth. Tiered competitive positioning separates premium design houses from mass-market fabricators. Strategic archetypes include Italian design-origin specialists, Korean-Japanese electronics integrators, and Indian market-focused distributors. Dominant competitive moves center on filterless technology licensing and backward integration into motor manufacturing.
Among European-origin specialists, Elica S.p.A. and Faber S.p.A. exemplify design-driven premium positioning anchored in Italian manufacturing heritage. Korean-Japanese electronics conglomerates occupy the connected-home interoperability tier, with LG Electronics and Samsung Electronics representing ecosystem-integrated appliance portfolios. Indian market penetration concentrates through Hindware, which exemplifies mass-market distribution depth across metropolitan retail networks.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| LG Electronics |
| Elica S.p.A. |
| Hindware |
| Panasonic Holdings Corporation |
| Faber S.p.A. |
| Robert Bosch GmbH |
| KAFF |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
The Shanghai-Ningbo port corridor governs landed cost dynamics for rare-earth magnet imports, concentrating pricing power among Guangdong-based motor assemblers while forcing Indian and European OEMs into three-tier pricing structures across premium, standard, and economy levels based on certification tier and after-sales bundling.
Pricing Analysis
The filterless-to-baffle technology-generation pricing gap spans roughly 40-60 percent at wholesale, with current-gen centrifugal units commanding premium positioning against prior-gen mesh-filter designs and next-gen IoT-integrated systems layering subscription revenue atop hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked synchronous motor models from BIS-certified regional variants and uncertified legacy induction architectures. Cost compression in the standard tier is intensifying because Gujarat and Tamil Nadu manufacturing clusters are absorbing copper price volatility through captive winding operations. Mass-market residential buyers in Indian tier-2 cities exhibit highest price sensitivity, while architect-specified island configurations in Southeast Asian luxury developments show lowest elasticity.
Supply Chain Analysis
Upstream feedstock concentration for rare-earth neodymium-iron-boron magnets centers on Chinese processing facilities in Inner Mongolia and Jiangxi, with secondary magnet sourcing from Japanese sintering operations in Nagasaki and Malaysian downstream separation plants. Copper winding supply draws from Chilean concentrate and Zambian cathode refined through Chinese smelters. Single-source vulnerability in dysprosium terbium heavy rare-earth elements creates exposure to export quota fluctuations. Distribution runs through brand-authorized dealer networks in Indian metros, third-party platform aggregators in Bangalore and Hyderabad, and HVAC contractor channels for US commercial specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through third-party installation platform aggregation in Indian metros, fragmenting brand-authorized service relationships and compressing aftermarket revenue pools for incumbent manufacturers.
For Market Incumbents: Insulate margin pools by securing backward integration into synchronous motor manufacturing before BIS efficiency mandates fully phase out induction architectures. Lock in tier-2 Indian city distribution through exclusive dealer arrangements to preempt platform-aggregator disintermediation. The threat of filterless technology commoditization demands certification moats via CE marking and UL listing investments. For New Entrants and Emerging Players: Pursue white-space penetration in Indian tier-2 cities where ducted installation skill scarcity has suppressed brand presence below metro saturation levels. Target hospitality chain standardization contracts in Southeast Asian markets where property developers specify island configurations without established service relationships. A go-to-market angle through app-scheduled technician dispatch platforms bypasses legacy dealer infrastructure. For Investors and Strategic Acquirers: Filterless technology licensors with embedded sensor IP and recurring service contract revenue represent the most defensible acquisition archetype against hardware commoditization. Long-term viability hinges on regulatory compliance breadth across BIS, CE, and UL certification portfolios rather than single-market dominance. The signal to watch is MIIT efficiency standard tightening in China, which would accelerate global motor architecture convergence and validate premium positioning for synchronous designs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Gujarat and Tamil Nadu clusters gain cost control over synchronous winding configurations. |
| Filterless Technology Licensing | Centrifugal separation IP creates recurring royalty streams from OEM adopters. |
| Connected-Home Platform Integration | Samsung and LG ecosystem interoperability locks in residential replacement cycles. |
| Tier-2 Distribution Expansion | Hyderabad and Pune whitespace captures renovation demand ahead of platform aggregation. |
| CE Marking Compliance Investment | EU Ecodesign motor limits create regulatory moats against non-compliant imports. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with HVAC contractor procurement heads, kitchen appliance brand managers, BIS certification consultants, and rare-earth magnet trading desk analysts. Secondary validation drew from BIS energy efficiency notification archives, EU Ecodesign implementing measure texts, US OSHA ventilation guidance documents, and Indian customs import duty schedules for copper winding and magnet components. Bottom-up unit shipment estimates from manufacturing clusters in Gujarat, Tamil Nadu, Zhejiang, and Guangdong were triangulated against top-down real estate renovation spend projections.
Calibration against historical BIS mandate implementation timelines and EU Green Deal phase-out schedules anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, separation technology, end-use application, and motor efficiency tier. CAGRs were derived from elasticity-adjusted replacement cycle compression in Indian metros and filterless technology penetration curves. Industry-specific forecast inputs incorporated copper LME price volatility bands and rare-earth export quota sensitivity scenarios.
Sensitivities concentrate around BIS enforcement intensity in tier-2 Indian cities, EU Ecodesign revision timelines, and Chinese rare-earth processing capacity expansion. Forecasts reflect documented assumptions on renovation spend correlation and technology substitution elasticities. Cross-checking against Indian real estate transaction databases and Southeast Asian property development pipeline data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Small Kitchen Appliances Market
Kitchen Appliances
Self-Stirring Mug Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
Outdoor Kitchen Appliances Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Smart Kitchen Appliances Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Europe Smart Cooker Market
Kitchen Appliances
Popcorn Makers Market
Kitchen Appliances
Electric Corkscrew Market