
 Battery Voltage Supervisor Market | 2026-2036
Battery Voltage Supervisor Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Voltage Supervisor Market Outlook
China's semiconductor foundry expansion is reshaping competitive dynamics for battery voltage supervisors. Texas Instruments leverages its analog portfolio depth to sustain design-win rates across automotive battery management systems. Infineon Technologies AG anchors its position through in-house production of supervisor die and power-stage integration. Analog Devices differentiates via high-precision delta-sigma architectures that dominate industrial equipment deployments.
A battery voltage supervisor is an integrated circuit or discrete system that monitors cell-stack potential against programmable thresholds, typically resolving differential voltages below one millivolt to prevent overcharge, deep-discharge, or thermal runaway conditions. The device generates fault flags or control signals that disconnect loads, balance cells, or alert host processors, serving as the electrochemical safety layer in lithium-ion and solid-state architectures. Integrated supervisors now capture the dominant margin pool as OEMs eliminate discrete component counts in space-constrained packs, while IoT Connectivity represents the fastest-expanding technology segment as cloud-linked predictive maintenance displaces passive threshold alerting. Portable supervisors remain a mature category with limited pricing power despite volume scale in consumer electronics.
The US FAA and NHTSA enforce functional safety standards that mandate redundant voltage monitoring in aviation and automotive traction batteries, directly expanding supervisor content per pack. China's MIIT and GB standards bodies impose cell-level monitoring granularity on domestic energy storage installations, creating compliance-driven demand for digital monitoring architectures with serial bus reporting. Stakeholders must weigh analog versus digital topology bets against evolving certification requirements in their target geographies.
Market Dynamics
EU Green Deal battery passport mandates are forcing cell manufacturers to embed traceable voltage monitoring at every production stage, compressing supplier qualification timelines and favoring vendors with automotive-grade certification histories.
Growth Catalysts
- EU Green Deal battery passport requirements:German electric vehicle manufacturers are expanding procurement of precision voltage monitoring systems to meet cell-level traceability mandates.
- China's Jiangsu and Guangdong cell production clusters:Localized supervisor supply chains are concentrating demand in these provinces as domestic battery gigafactories scale output.
- Aviation traction battery safety:The US FAA enforces redundant voltage monitoring standards that expand supervisor content per pack in commercial aircraft energy storage systems.
Market Restraints
- Silicon wafer input cost volatility:Analog supervisor die fabrication depends on 300mm silicon substrate pricing that fluctuates with semiconductor foundry loading rates.
- Automotive-grade qualification timelines:AEC-Q100 certification cycles extend 18-24 months, freezing out new entrants from design-win opportunities in vehicle platforms.
- Discrete component substitution in cost-sensitive consumer electronics:Basic protection ICs from Chinese suppliers undercut integrated supervisors in portable power banks and entry-level smartphones.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic battery production incentives are creating first-mover advantages for supervisor vendors establishing local technical support.
- Solid-state battery architectures:Next-generation cell chemistries require redesigned monitoring thresholds and fault-response algorithms that reset competitive positioning.
- Cloud-linked predictive maintenance:IoT connectivity integration enables recurring revenue service models that displace one-time component sales in industrial battery deployments.
Industry Challenges
- Mixed-signal IC design talent scarcity:Battery voltage supervisor development requires rare expertise in precision analog front-ends combined with digital serial interface protocols.
- Legacy 12V automotive electrical system integration:48V mild-hybrid architectures demand supervisor solutions that bridge heterogeneous voltage domains without full platform redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Voltage Supervisor Market |
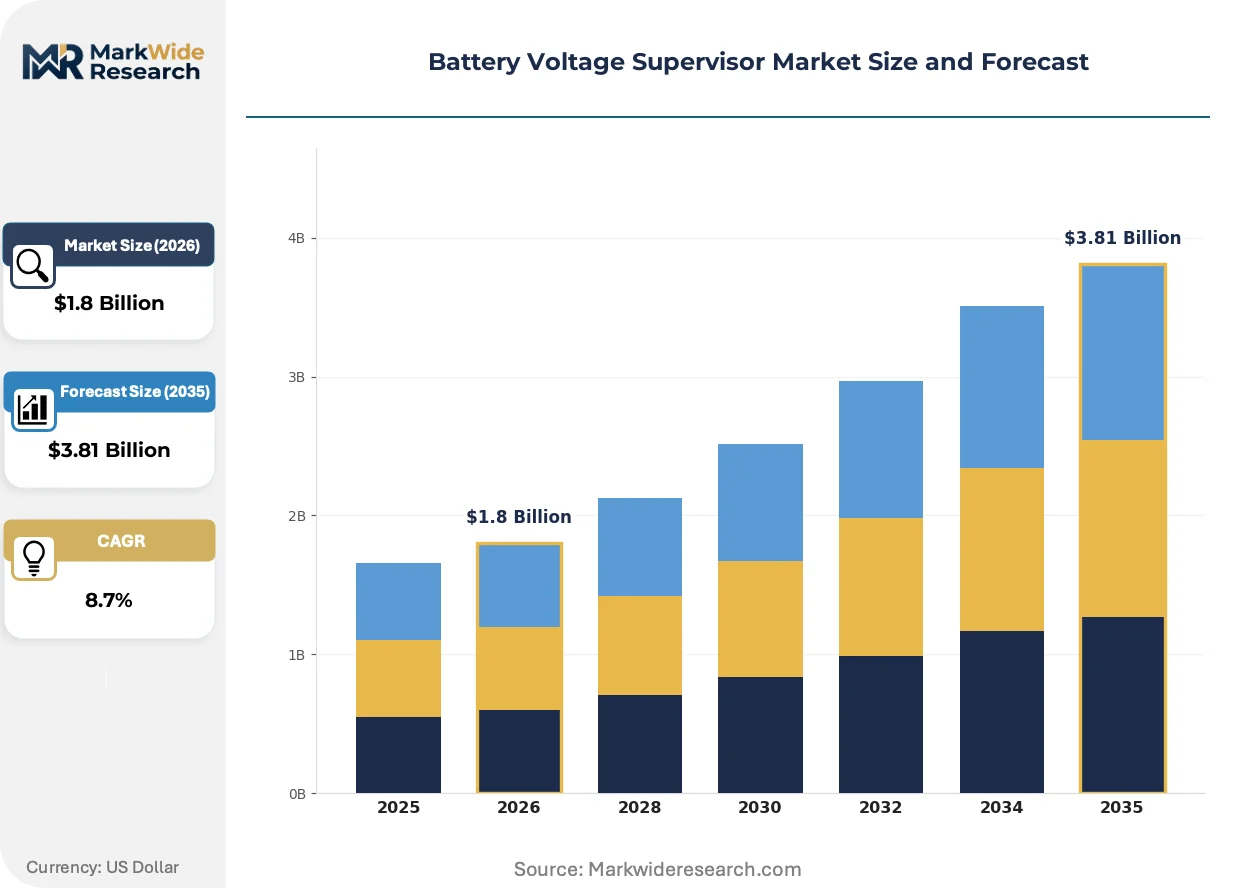
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted Supervisors, Portable Supervisors, Integrated Supervisors, Modular Supervisors Technology: Analog Monitoring, Digital Monitoring, IoT Connectivity, Wireless Communication End User: Consumer Electronics, Automotive, Industrial Equipment, Renewable Energy Installation: Fixed Installation, Temporary Installation, Rack-Mounted Installation, Remote Installation |
| Companies Covered | Texas Instruments Incorporated, Analog Devices, Infineon Technologies AG, STMicroelectronics, Renesas Electronics Corporation, Maxim Integrated, Rohm Co. Ltd., Semiconductor Components Industries LLC, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Voltage Supervisor Market Strategic Shifts
Architectural consolidation is compressing the traditional separation between measurement, protection, and communication functions. Voltage supervisors are absorbing capabilities that previously required multi-chip solutions.
Delta-sigma analog-to-digital conversion is migrating from industrial equipment into automotive battery management systems. Cell manufacturers in Germany and South Korea are specifying sub-millivolt resolution for state-of-charge estimation accuracy. This migration from discrete comparator-based designs to precision conversion architectures is enabling single-IC solutions that reduce pack-level component counts by 40%.
China's MIIT and GB standards bodies are mandating cell-level monitoring granularity on domestic energy storage installations. These regulations require serial bus reporting architectures that displace passive threshold alerting in utility-scale battery farms. Domestic Chinese supervisor vendors are capturing design wins in state-backed grid storage projects that prioritize local certification compliance.
Direct purchasing relationships between cell manufacturers and supervisor semiconductor vendors are displacing traditional tiered distribution. CATL and BYD are negotiating volume commitments that bypass regional component distributors. This pattern is most visible in China's Jiangsu province, where production clusters co-locate cell fabrication and supervisor die testing facilities.
Battery Voltage Supervisor Market Segmentation
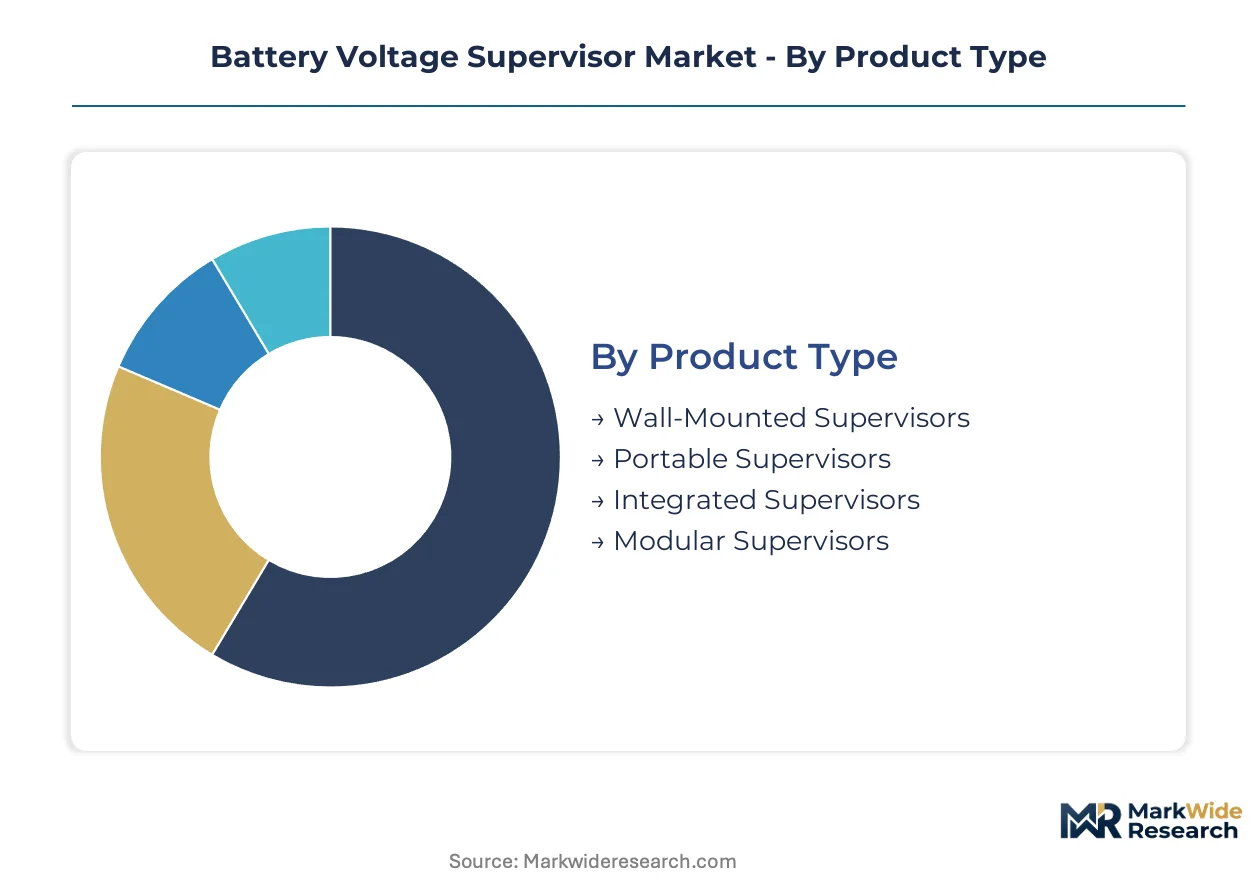
Voltage supervisor architectures fragment across installation constraints, power-domain complexity, and connectivity requirements. Each segment carries distinct margin profiles and qualification barriers that reshape vendor positioning.
Product Type:
Fixed and mobile power systems impose radically different form-factor, thermal, and reliability specifications on supervisor designs.
- Integrated Supervisors:Monolithic ICs combine voltage sensing, threshold comparison, and fault signaling in single-die solutions. Automotive battery management systems in Germany specify these for cell-level monitoring under EU Green Deal traceability mandates.
- Portable Supervisors:Compact protection circuits target consumer power banks and handheld electronics. Jiangsu province contract manufacturers absorb volume here, though pricing pressure from basic discrete alternatives constrains margins.
- Wall-Mounted Supervisors:Enclosed units serve stationary energy storage installations with extended temperature ratings.
- Modular Supervisors:Hot-swappable cards enable maintenance in utility-scale battery farms without system shutdown.
The dominant share belongs to Integrated Supervisors, while Portable Supervisors is closing the gap fastest on volume scale in consumer electronics.
Technology:
Signal processing topology determines resolution, power consumption, and system integration depth across end-use categories.
- IoT Connectivity:Cloud-linked supervisors stream cell telemetry for predictive maintenance algorithms. Industrial equipment deployments in Guangdong province are specifying these for remote battery health monitoring.
- Digital Monitoring:Serial bus architectures report granular voltage data to host processors. China's MIIT mandates this granularity for domestic grid-storage compliance.
- Analog Monitoring:Comparator-based designs persist in cost-constrained applications with loose threshold requirements.
- Wireless Communication:RF-linked supervisors eliminate wiring harnesses in rotating machinery and sealed enclosures.
Digital Monitoring holds the largest installed base, yet IoT Connectivity is climbing the fastest as recurring-revenue service models displace component sales.
End User:
Functional safety requirements and operating environment severity create tiered qualification barriers across customer categories.
- Automotive:AEC-Q100 certified supervisors resolve sub-millivolt differentials across 400V+ traction packs. NHTSA redundant-monitoring mandates expand content per vehicle platform.
- Industrial Equipment:Delta-sigma architectures dominate here for state-of-charge estimation accuracy in motive power and backup systems.
- Consumer Electronics:Basic protection ICs serve smartphones and laptops with minimal resolution requirements.
- Renewable Energy:Utility-scale solar and wind storage installations demand serial-reporting supervisors for remote asset management.
Automotive commands the highest revenue per unit, while Renewable Energy is gaining share fastest on gigafactory deployment timelines.
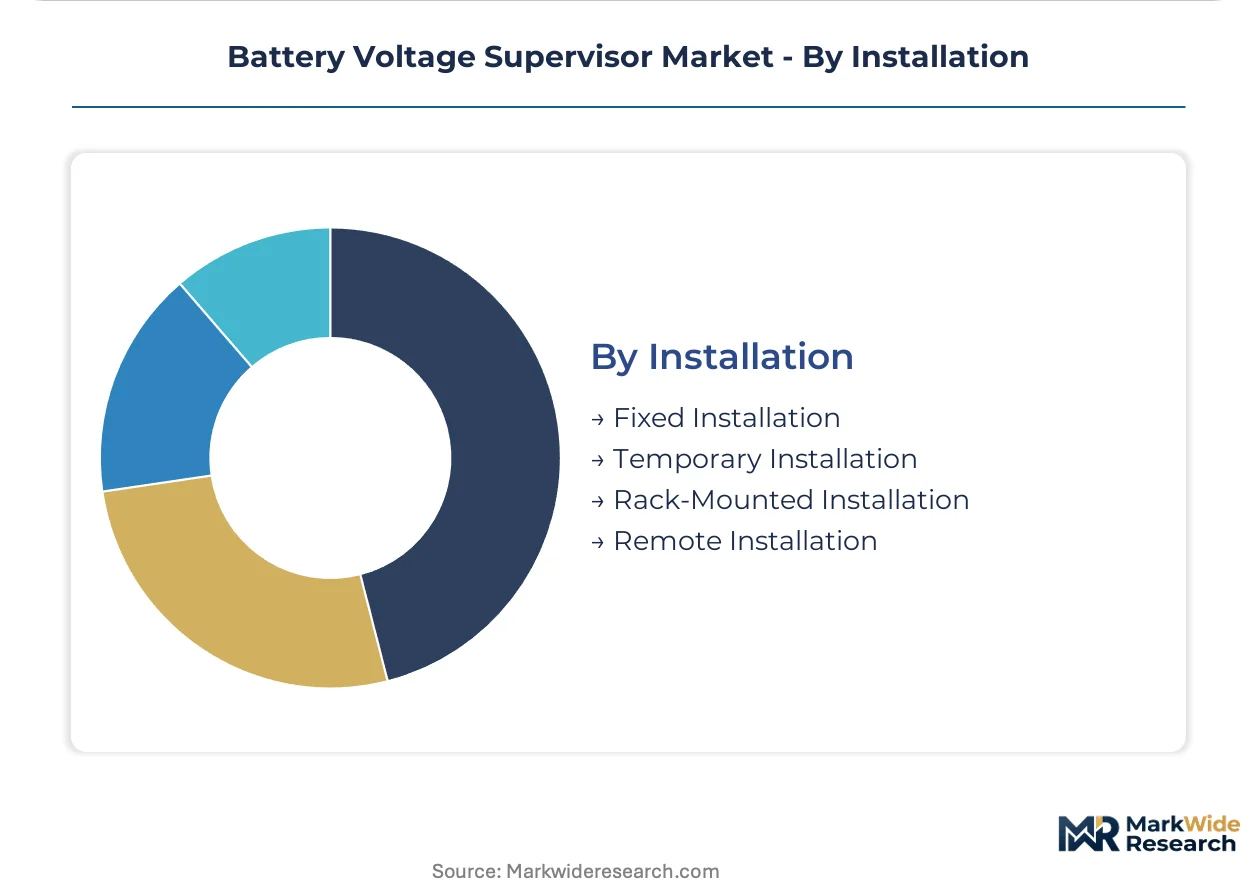
Installation:
Physical mounting topology constrains thermal management, accessibility, and electromagnetic compatibility design choices.
- Fixed Installation:Permanently mounted supervisors in electric vehicle battery packs must survive vibration and thermal cycling. FAA standards for aviation traction systems specify redundant fixed installations.
- Rack-Mounted Installation:Standardized 19-inch enclosures serve data center and telecom backup power with hot-swap serviceability.
- Temporary Installation:Portable supervisors support field testing and maintenance operations.
- Remote Installation:Distributed supervisors in offshore wind and remote grid storage require extended temperature ranges and sealed housings.
Fixed Installation accounts for the greatest unit volume, with Rack-Mounted Installation expanding most quickly on data center power infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT and GB standards bodies in China impose cell-level monitoring granularity that anchors global supervisor demand. Regulatory mandates across Germany, the United States, South Korea, and India create distinct qualification barriers and procurement patterns.
China
Jiangsu and Guangdong province cell production clusters concentrate domestic supervisor procurement as CATL and BYD scale gigafactory output. MIIT mandates serial bus reporting architectures for utility-scale grid storage compliance. Domestic vendors capture design wins in state-backed projects that prioritize local certification over foreign alternatives.
Germany
Electric vehicle manufacturers expand precision voltage monitoring procurement under EU Green Deal battery passport traceability requirements. KBA enforces automotive-grade functional safety standards that extend supplier qualification timelines. Bavaria-based battery pack assembly plants co-locate with supervisor testing facilities to compress logistics cycles.
United States
NHTSA redundant voltage monitoring mandates expand supervisor content per automotive traction battery pack. FAA standards enforce dual-channel architectures in commercial aviation energy storage systems. Michigan and Ohio automotive battery corridors drive procurement of AEC-Q100 certified monitoring ICs.
South Korea
Cell manufacturers specify sub-millivolt resolution supervisors for state-of-charge estimation accuracy in premium electric vehicle platforms. MFDS-aligned industrial safety protocols apply to stationary energy storage installations. Gyeonggi-do province production clusters integrate supervisor die testing with cell fabrication lines.
India
PLI scheme incentives for advanced chemistry cell manufacturing create first-mover advantages for supervisor vendors establishing local technical support. CEA grid codes mandate remote monitoring capabilities for utility-scale battery installations. Gujarat and Tamil Nadu emerging production zones concentrate procurement negotiations with semiconductor distributors.
Battery Voltage Supervisor Market Competitive Environment
Capability concentration sits with analog-mixed signal specialists; scale advantage sits with diversified semiconductor conglomerates. The market structures around three tiers: integrated device manufacturers with captive fabrication, fabless designers leveraging foundry partnerships, and regional component suppliers serving cost-constrained segments. Dominant competitive moves include backward integration into supervisor die production and strategic partnerships with cell manufacturers for co-development of next-generation monitoring architectures.
Within the diversified analog portfolio tier, Texas Instruments Incorporated and Analog Devices occupy positions that leverage decades of precision signal processing expertise. Infineon Technologies AG exemplifies the integrated manufacturing archetype through in-house production of supervisor die combined with power-stage integration capabilities. These three entities anchor the premium qualification segment where AEC-Q100 certification histories determine design-win access in automotive platforms.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Analog Devices |
| Infineon Technologies AG |
| STMicroelectronics |
| Renesas Electronics Corporation |
| Maxim Integrated |
| Rohm Co. Ltd. |
| Semiconductor Components Industries LLC |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
300mm silicon wafer fabrication capacity in Taiwan and South Korea anchors cost structures for precision analog die, concentrating margin capture with integrated device manufacturers while fabless competitors absorb foundry pricing volatility through contract terms. Automotive-grade qualification premiums widen spreads between AEC-Q100 certified supervisors and consumer-tier alternatives.
Pricing Analysis
Price spreads between German automotive platforms and Jiangsu province consumer electronics contract manufacturers exceed three-to-one on equivalent die functionality. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive-grade supervisors from industrial equipment variants and basic portable protection ICs. Cost compression in consumer-tier portable supervisors intensifies as discrete component substitutes from domestic Chinese suppliers erode integrated IC positioning. Cell manufacturers and automotive OEMs exhibit lowest price sensitivity due to certification lock-in effects, while power bank assemblers in Guangdong province negotiate aggressively on volume.
Supply Chain Analysis
Extended payment terms from CATL and BYD compress working capital cycles for supervisor semiconductor vendors, forcing supply-chain finance facilities or foundry pre-payment structures. Manufacturing concentrates in Taiwan, South Korea, and China for 300mm analog wafer processing, with back-end testing and tape-out services clustering in Malaysia and Vietnam. Raw material dependencies span silicon substrate, gold wire bonding, and epoxy molding compounds. Single-source vulnerability runs through TSMC's specialty analog node capacity. Distribution runs through direct purchasing relationships that displace regional component distributors as cell manufacturers negotiate volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Discrete protection ICs from cost-optimized Chinese suppliers threaten substitution at the economy tier, forcing integrated supervisor vendors to defend positioning through certification depth and automotive-grade qualification barriers.
For Market Incumbents: Harden AEC-Q100 certification moats by accelerating investment in next-generation delta-sigma architectures before solid-state battery thresholds reset competitive positioning. Deepen backward integration into supervisor die production to capture margin pools currently flowing to foundry partners. Lock in multi-year supply agreements with CATL and BYD that embed technical support obligations and displace emerging domestic Chinese competitors. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme production zones before qualification timelines freeze out late movers from Gujarat and Tamil Nadu battery corridors. Target rack-mounted installation supervisors for data center backup power where AEC-Q100 certification requirements are less stringent than automotive traction applications. Lead with IoT connectivity integration and predictive maintenance software bundles that generate recurring revenue streams distinct from commoditized hardware sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed analog-mixed signal specialists holding automotive certification histories but lacking power-stage integration capabilities. Five-to-ten year viability hinges on positioning for solid-state battery monitoring architectures and cloud-linked service model transitions. Watch for inflection signals in FAA and NHTSA rulemaking that mandate redundant voltage monitoring granularity beyond current specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade Certification Investment | AEC-Q100 qualification histories determine design-win access in German EV platforms under EU Green Deal mandates. |
| Backward Integration into Die Production | In-house 300mm wafer fabrication captures margin pools and insulates against foundry pricing volatility from TSMC loading rates. |
| IoT Connectivity Platform Development | Cloud-linked predictive maintenance displaces passive threshold alerting in Guangdong industrial equipment deployments. |
| India Technical Support Localization | PLI scheme incentives create first-mover advantages for vendors establishing Gujarat and Tamil Nadu engineering presence. |
| Solid-State Battery Architecture Co-Development | Next-generation cell chemistries require redesigned monitoring thresholds that reset competitive positioning against incumbents. |
Study Parameters
The analysis maps integrated supervisor architectures, portable protection circuits, and IoT-connected monitoring platforms, each validated through battery pack design engineers, automotive platform procurement leads, semiconductor distribution channel managers, and grid storage project developers. Primary interviews triangulate against MIIT regulatory filings, FAA airworthiness directives, NHTSA safety standards, customs trade data for analog IC imports, and SEC 10-K disclosures from diversified semiconductor manufacturers. Bottom-up cell production forecasts from Jiangsu and Guangdong provinces reconcile with top-down battery gigafactory capacity announcements.
Assumptions hold EU Green Deal battery passport implementation timelines and China's MIIT grid storage monitoring mandates as fixed regulatory drivers, while varying solid-state battery commercialization pace and silicon wafer pricing trajectories across modeling scenarios. Segmentation dimensions span product type, technology topology, end-use vertical, and installation configuration alongside regional production cluster qualification requirements. CAGRs derive from unit volume build-ups by automotive platform and utility-scale storage deployment, cross-checked against semiconductor content-per-pack estimates from tiered supplier interviews.
Sensitivities concentrate around AEC-Q100 certification timeline extensions, foundry capacity allocation shifts toward AI accelerators, and domestic Chinese vendor capture rates in state-backed grid storage procurement. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Thermoelectric Assemblies Market
Power Systems
Battery Electronic Control Unit Market
Power Systems
Transformer Tap Changers and Voltage Control Relay Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
AC DC Power Adapter Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
South America DC Distribution Network Market
Power Systems
Micro-Inverter Market
Power Systems
Module-Level Power Electronics (MLPE) Market
Power Systems
Global Automatic Voltage Stabilizer Market
Power Systems
Battery Balancer Market
Power Systems
North America Telecom Power Systems Market
Power Systems
South Korea Battery Management Systems Market