
 Open System MRI Market | 2026-2036
Open System MRI Market Size, Share, and Industry Trends Forecast 2026-2036
Open System MRI Market Analytics
Permanent magnet and hybrid field architectures is reconfiguring how open-configuration scanners achieve diagnostic-grade image quality without superconducting helium dependence. Siemens Healthineers leverages its superconducting R&D pipeline to sustain premium positioning across academic medical centers. GE Healthcare anchors North American installed-base service revenue through predictive maintenance platforms. Esaote specializes in extremity-dedicated open systems that occupy a defensible niche in orthopedic and sports-medicine workflows.
Open System MRI denotes diagnostic imaging equipment employing non-cylindrical or partially open magnet geometries, typically operating at field strengths below 1.0 Tesla for permanent-magnet configurations or up to 1.5 Tesla in hybrid superconducting designs, engineered to accommodate claustrophobic, pediatric, or bariatric patients while maintaining sufficient signal-to-noise ratios for musculoskeletal and neurological assessment. Among product-type categories, open MRI and extremity MRI configurations capture expanding share as outpatient imaging centers prioritize throughput and patient satisfaction metrics over peak field strength. Superconducting technology segments retain margin concentration in hospital settings, while permanent-magnet and resistive systems compete on capital efficiency and siting flexibility for private practices and mobile imaging fleets.
FDA device classification standards govern 510(k) clearance pathways and clinical indication labeling for open-configuration systems in the United States, directly shaping manufacturer R&D allocation and reimbursement eligibility. ISO 13485 quality management frameworks and IEC 60601-1-2 electromagnetic compatibility standards constrain design choices and market access timelines across all major jurisdictions. Stakeholders must weigh helium supply-chain volatility against hybrid-technology capital costs when configuring procurement strategies for the next replacement cycle.
Market Dynamics
Permanent-magnet field architectures are displacing superconducting helium dependence in open-configuration scanners, reconfiguring capital deployment patterns across outpatient imaging networks and mobile diagnostic fleets.
Growth Catalysts
- Claustrophobia accommodation protocols:Pediatric radiology departments at academic medical centers prioritize open geometries to reduce sedation rates and improve throughput metrics.
- Helium supply-chain volatility:Permanent-magnet systems eliminate cryogenic cooling requirements, insulating procurement budgets from geopolitical helium sourcing disruptions.
- Outpatient imaging center expansion:United States-based ambulatory networks favor siting-flexible systems that bypass quench-vent infrastructure and reduce facility preparation costs.
Market Restraints
- Signal-to-noise ratio limitations:Sub-1.0 Tesla permanent-magnet configurations constrain soft-tissue contrast resolution for certain neurological assessments.
- Superconducting R&D concentration:Premium-field-strength innovation pipelines remain concentrated among established superconducting equipment manufacturers.
- FDA 510(k) pathway duration:Novel hybrid-field architectures face extended clearance timelines for clinical indication labeling.
Strategic Opportunities
- Extremity-dedicated workflows:Orthopedic and sports-medicine practices present white-space demand for limb-specific open configurations with dedicated coil arrays.
- Mobile imaging fleet penetration:Rural and semi-urban United States markets remain underpenetrated by fixed-site superconducting infrastructure.
- ISO 13485 certification arbitrage:Quality management framework harmonization enables faster multi-jurisdiction market access for compliant manufacturers.
Industry Challenges
- MR physicist staffing scarcity:Specialized clinical application training for open-system protocols lags scanner installation rates.
- Legacy PACS integration complexity:Hybrid-field systems require middleware adaptation for seamless connectivity with hospital enterprise imaging archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Open System MRI Market |
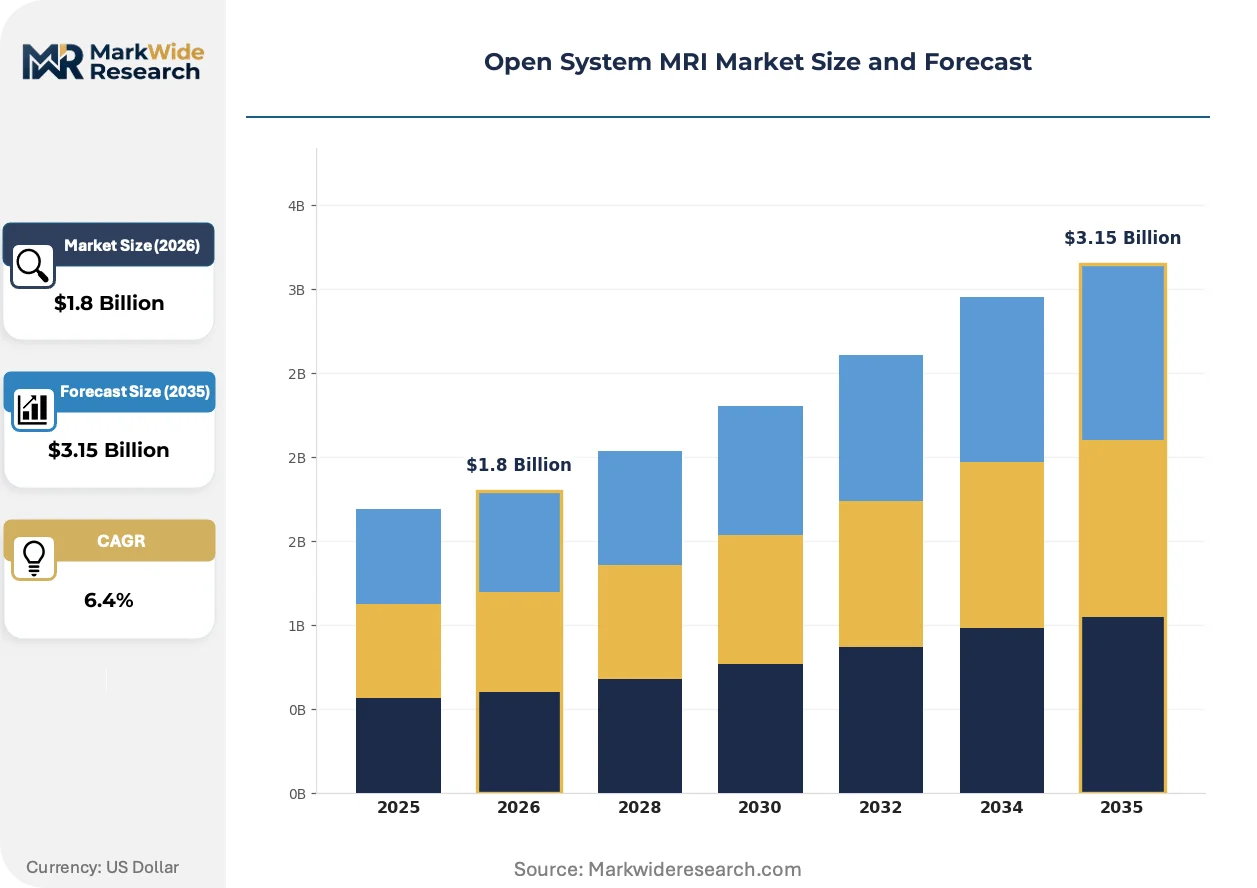
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Hybrid MRI End User: Hospitals, Imaging Centers, Research Institutions, Private Practices Technology: Superconducting, Resistive, Permanent Magnet, Hybrid Technology Application: Orthopedics, Neurology, Oncology, Cardiology |
| Companies Covered | Canon Medical Systems, Hitachi Healthcare, Siemens Healthineers, United Imaging Healthcare, Esaote, GE Healthcare, Fujifilm Holdings, Aspect Imaging, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Open System MRI Market Evolving Landscape
Magnet engineering and clinical workflow design are converging to expand diagnostic utility beyond traditional superconducting constraints. Three developments are actively restructuring competitive positioning.
Permanent-magnet field stabilization is migrating from fixed-site hospital installations toward mobile diagnostic platforms. Fleet operators in the United States are adopting trailer-mounted open configurations for community screening programs. This shift is compressing the addressable market for conventional superconducting systems in rural catchment areas.
FDA magnetic resonance device classification standards are tightening clinical indication requirements for pediatric populations. Manufacturers must demonstrate enhanced motion-correction algorithms and faster acquisition sequences. Academic medical centers in the United States are prioritizing compliant systems for institutional review board approval of research protocols.
After-sales service unbundling is fragmenting traditional equipment procurement contracts. Outpatient imaging centers are separating hardware acquisition from maintenance and software upgrade obligations. This pattern is most visible in United States private practice networks seeking operational expense predictability over capital-intensive bundled arrangements.
Open System MRI Market Segmentation
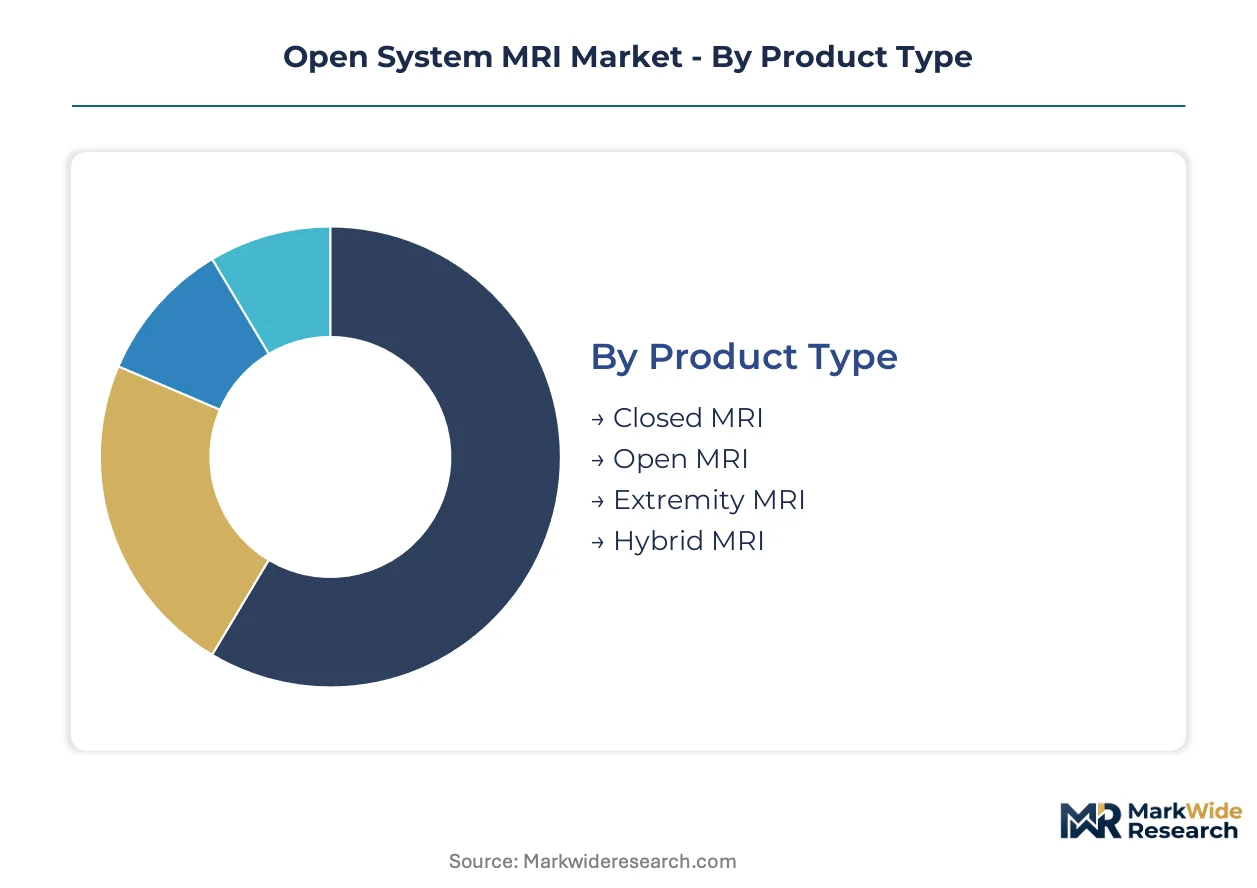
Open System MRI segmentation reveals divergent service intensity and capital deployment patterns across product architectures and clinical settings. Understanding these divides enables targeted positioning for equipment manufacturers and procurement strategists navigating replacement cycles.
Product Type:
After-sales-service intensity varies sharply across magnet geometries, with superconducting hybrids demanding specialized cryogenic maintenance while permanent-magnet configurations shift revenue toward software subscriptions.
- Open MRI:Non-cylindrical magnet geometries operating below 1.0 Tesla eliminate claustrophobia triggers for pediatric and bariatric populations. Academic medical centers in the United States prioritize these systems to reduce anesthesia dependency and accelerate throughput metrics.
- Extremity MRI:Limb-dedicated configurations with specialized coil arrays target orthopedic workflows. Sports medicine practices and ambulatory surgery centers favor these systems for dedicated extremity imaging without full-body scanner capital burden.
- Closed MRI:Cylindrical superconducting systems retain diagnostic-grade field strength for neurological soft-tissue contrast. Hospital radiology departments maintain these for complex cases where signal-to-noise ratio cannot be compromised.
- Hybrid MRI:Combines superconducting performance with open-architecture accessibility. Premium positioning attracts academic institutions seeking research flexibility alongside clinical volume.
Open MRI holds the largest share; momentum sits with Extremity MRI.
End User:
Procurement authority concentrates differently across customer types, with imaging centers optimizing for patient satisfaction scores while research institutions prioritize protocol flexibility.
- Imaging Centers:Outpatient networks in the United States favor siting-flexible permanent-magnet systems that bypass quench-vent infrastructure and reduce facility preparation costs. These operators unbundle service contracts to achieve operational expense predictability.
- Hospitals:Integrated health systems balance throughput demands against capital constraints. Superconducting installations dominate where neurological case volume justifies helium supply-chain management.
- Private Practices:Small orthopedic and sports medicine groups seek extremity-dedicated configurations with minimal physicist staffing requirements.
- Research Institutions:Academic medical centers require FDA-compliant systems with enhanced motion-correction algorithms for pediatric protocol approval.
Hospitals anchor installed-base revenue; imaging centers are expanding most quickly.
Technology:
Magnet engineering choices determine total cost of ownership, with helium independence becoming decisive for mobile fleet operators and budget-constrained networks.
- Permanent Magnet:Eliminates cryogenic cooling requirements entirely. Mobile diagnostic fleets in rural United States markets adopt trailer-mounted configurations for community screening programs.
- Superconducting:Retains margin concentration through premium field strength above 1.5 Tesla. Hospital settings maintain preference where soft-tissue contrast resolution cannot be sacrificed.
- Resistive:Lower capital entry point suits private practices with limited case volume. Electromagnet designs trade field stability for siting flexibility.
- Hybrid Technology:Merges superconducting performance with open geometries. Extended FDA 510(k) pathways constrain clearance timelines for novel architectures.
Superconducting systems dominate hospital procurement; permanent-magnet configurations gain share fastest.
Application:
Clinical indication requirements shape coil array design and software algorithm development, with orthopedic workflows demanding dedicated extremity configurations.
- Orthopedics:Limb-specific imaging drives demand for open and extremity-dedicated systems. Sports medicine practices require rapid turnaround for injury assessment.
- Neurology:Soft-tissue contrast requirements sustain superconducting system preference. Motion-correction algorithms become critical for uncooperative or pediatric patients.
- Oncology:Staging and treatment monitoring applications span field strength requirements. Academic centers prioritize multi-parametric imaging capability.
- Cardiology:Cardiac MRI remains concentrated in hospital settings with specialized physiologist support. Gating and synchronization technology differentiates competitive offerings.
Orthopedics commands the broadest installed base; neurology maintains steepest expansion trajectory for open-configuration adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and outpatient imaging networks concentrate procurement authority across distinct national healthcare systems. Each market exhibits unique regulatory pathways and infrastructure replacement cycles that shape open-configuration adoption.
United States
Pediatric radiology departments at academic medical centers drive claustrophobia-reduction protocols. FDA 510(k) clearance pathways govern clinical indication labeling for hybrid-field architectures. The Southeast corridor from Florida to Georgia hosts expanding ambulatory imaging networks replacing aging superconducting infrastructure.
Germany
University hospitals prioritize research-flexible systems for motion-correction algorithm development. EU Medical Device Regulation (MDR) compliance requirements extend clearance timelines for novel magnet geometries. The Baden-Württemberg cluster around Stuttgart anchors orthopedic-focused extremity system manufacturing.
China
Provincial hospital networks accelerate permanent-magnet procurement to bypass helium supply-chain vulnerabilities. National Medical Products Administration (NMPA) standards increasingly align with ISO 13485 quality frameworks. The Yangtze River Delta medical device corridor concentrates domestic open-system assembly capacity.
Japan
Aging demographics sustain demand for bariatric-accommodating scanner geometries. Pharmaceutical and Medical Devices Agency (PMDA) reviews emphasize pediatric safety documentation. The Kansai region surrounding Osaka maintains specialized coil array manufacturing for extremity-dedicated configurations.
India
Private diagnostic chains favor capital-efficient permanent-magnet systems for tier-2 city expansion. Central Drugs Standard Control Organization (CDSCO) device registration harmonizes with IEC 60601-1-2 electromagnetic compatibility standards. Maharashtra's Mumbai-Pune corridor hosts the fastest-growing installed base of mobile imaging fleets.
Open System MRI Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority. Superconducting equipment manufacturers retain margin concentration in hospital settings. Permanent-magnet specialists capture outpatient imaging center expansion. Three archetypes dominate: diversified health technology conglomerates, dedicated diagnostic imaging manufacturers, and regional medical device specialists. Strategic moves center on predictive maintenance platform deployment and extremity-dedicated workflow specialization.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify channel-controlling positions through installed-base service revenue. Esaote occupies a specialist archetype focused on limb-dedicated configurations. United Imaging Healthcare represents scale-driven geographic expansion from manufacturing concentration into international procurement networks.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Hitachi Healthcare |
| Siemens Healthineers |
| United Imaging Healthcare |
| Esaote |
| GE Healthcare |
| Fujifilm Holdings |
| Aspect Imaging |
| Koninklijke Philips |
| Others |
Value Network & Pricing Analysis
Helium refining capacity concentrates in the United States and Qatar, creating asymmetric margin capture for superconducting system manufacturers dependent on cryogenic cooling while permanent-magnet alternatives redirect procurement budgets toward software subscriptions and coil array specialization.
Pricing Analysis
Cost-plus service contracts with helium price indexation dominate superconducting system maintenance agreements, while permanent-magnet configurations shift toward flat-rate software subscriptions. Price differentiation separates FDA-cleared pediatric systems from standard orthopedic configurations, with academic medical centers absorbing brand premiums for research-flexible hybrid architectures. Pricing pressure stems from outpatient imaging center unbundling of hardware and service obligations. Private practice networks exhibit highest price sensitivity; research institutions prioritize protocol flexibility over capital efficiency.
Supply Chain Analysis
Export control regimes under the U.S. Department of Commerce restrict superconducting wire and cryogenic component flows to certain end-users, fragmenting procurement pathways for non-Western hospital networks. Magnet core fabrication concentrates in Germany, China, and Japan; gradient amplifier assembly localizes in South Korea and Taiwan. Rare-earth permanent magnet sourcing draws from Chinese processing facilities and Australian extraction operations. Single-source vulnerability sits with helium liquefaction infrastructure. Distribution runs through manufacturer-direct sales for hospital systems and specialized imaging distributors for ambulatory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open System MRI demand tracks healthcare capital expenditure cycles, with aging superconducting infrastructure replacement and outpatient imaging center expansion forming the current upswing phase.
For Market Incumbents: Harden installed-base service revenue through predictive maintenance platform deployment across North American hospital networks. Deepen backward integration into permanent-magnet core fabrication to offset helium supply-chain volatility. Prioritize FDA 510(k) clearance investment for pediatric motion-correction algorithms to defend academic medical center positioning against hybrid-technology challengers. For New Entrants and Emerging Players: Establish a beachhead in extremity-dedicated configurations for orthopedic and sports-medicine private practices, where physicist staffing requirements are minimal and capital barriers favor nimble competitors. Target mobile imaging fleet operators in rural United States markets underserved by fixed-site superconducting infrastructure. Pursue ISO 13485 certification early to accelerate multi-jurisdiction market access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed outpatient imaging center rollups seeking operational expense predictability through permanent-magnet fleet standardization. Long-term viability favors manufacturers with software subscription revenue streams and extremity-dedicated workflow specialization. Watch FDA pediatric indication labeling velocity as inflection signal for research-protocol adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Pediatric Indications | Unlocks academic medical center procurement and IRB-approved research protocol eligibility. |
| Helium-Independent Magnet Architecture Development | Insulates procurement budgets from geopolitical supply disruptions and quench-vent infrastructure costs. |
| Extremity-Dedicated Coil Array Specialization | Captures orthopedic and sports-medicine workflows with lower capital barriers than full-body systems. |
| Predictive Maintenance Platform Deployment | Converts installed-base service relationships into recurring revenue streams with higher margin stability. |
| ISO 13485 Quality Framework Harmonization | Accelerates multi-jurisdiction clearance timelines for manufacturers targeting international expansion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, hospital procurement databases, and GPO contract disclosures. Interviews with biomedical engineers, radiology department heads, imaging center operations directors, and GPO contracts managers informed demand-side validation. Manufacturer-side perspectives came from product managers and regulatory affairs leads at equipment suppliers. Secondary sources include CMS Medicare reimbursement data, ISO certification registries, and helium market trade publications. Bottom-up scanner installation tracking triangulates against top-down healthcare capital expenditure estimates.
Forecast inputs span product type segmentation across open, extremity, closed, and hybrid configurations; technology segmentation across permanent-magnet, superconducting, resistive, and hybrid architectures; and end-user segmentation across imaging centers, hospitals, private practices, and research institutions. CAGRs derive from replacement cycle modeling and outpatient network expansion trajectories. Industry-specific inputs include helium price volatility scenarios and FDA pediatric indication approval velocity assumptions.
Stress conditions across helium supply disruption severity, FDA clearance timeline extension, and outpatient imaging center bankruptcy rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about capital expenditure cycle phasing and reimbursement stability. Material shifts in Medicare imaging reimbursement policy or superconducting wire export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
Medical Imaging Outsourcing Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
Echocardiography Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Asia-Pacific Digital Pathology Market