
 Europe Nuclear Medicine Market | 2026-2036
Europe Nuclear Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nuclear Medicine Market Foresight
The split between premium therapeutic radiopharmaceuticals and commodity diagnostic isotopes is hardening as reimbursement frameworks diverge across European health systems. Curium Pharma anchors its position through vertical integration into isotope production networks spanning multiple EU member states. Siemens Healthineers differentiates via hybrid imaging systems that merge PET and CT modalities for real-time therapeutic monitoring.
Nuclear medicine encompasses the clinical use of radioactive substances for both diagnostic imaging and targeted therapy, requiring half-life precision within specific radionuclide decay parameters measured in hours to days. Its primary purpose is to enable molecular-level visualization of physiological function and deliver localized radiation doses to malignant tissue while sparing healthy structures. Diagnostic imaging and therapeutic agents represent the dominant product categories, with therapeutic agents capturing expanding margin pools as lutetium-177 and actinium-225 therapies gain clinical traction. Positron emission tomography leads technology deployment for neurology and cardiology applications, though hybrid imaging systems are displacing standalone modalities in major European referral centers.
The European Medicines Agency oversees centralized marketing authorization for radiopharmaceuticals, while national regulators such as France's ANSM and Germany's BfArM enforce Good Manufacturing Practice compliance at production sites. REACH and the EU's F-Gas Regulation constrain supply chain chemistry for certain isotope production processes, elevating compliance costs for market entrants. Stakeholders must monitor EMA guidance on radiopharmaceutical quality standards and cyclotron network capacity as therapeutic demand outpaces current production infrastructure.
Market Dynamics
The therapeutic radiopharmaceutical pipeline is compressing development timelines as lutetium-177 and actinium-225 therapies demonstrate durable efficacy in solid tumors, forcing reimbursement bodies to recalibrate cost-effectiveness frameworks for precision oncology.
Growth Catalysts
- EMA Centralized Authorization Pathway:The streamlined marketing authorization process for novel radiopharmaceuticals accelerates cross-border patient access and reduces regulatory duplication across EU member states.
- Cyclotron Network Expansion:Germany's university hospital clusters are building dedicated isotope production facilities, creating regional supply hubs that shorten radiopharmaceutical half-life logistics.
- Hybrid Imaging Adoption:PET-CT convergence in major European referral centers enables real-time therapeutic monitoring, expanding the addressable patient population for molecular radiotherapy.
Market Restraints
- Molybdenum-99 Supply Concentration:Ageing research reactors in the Netherlands and Belgium create single-point-of-failure risk for technetium-99m, the workhorse diagnostic isotope.
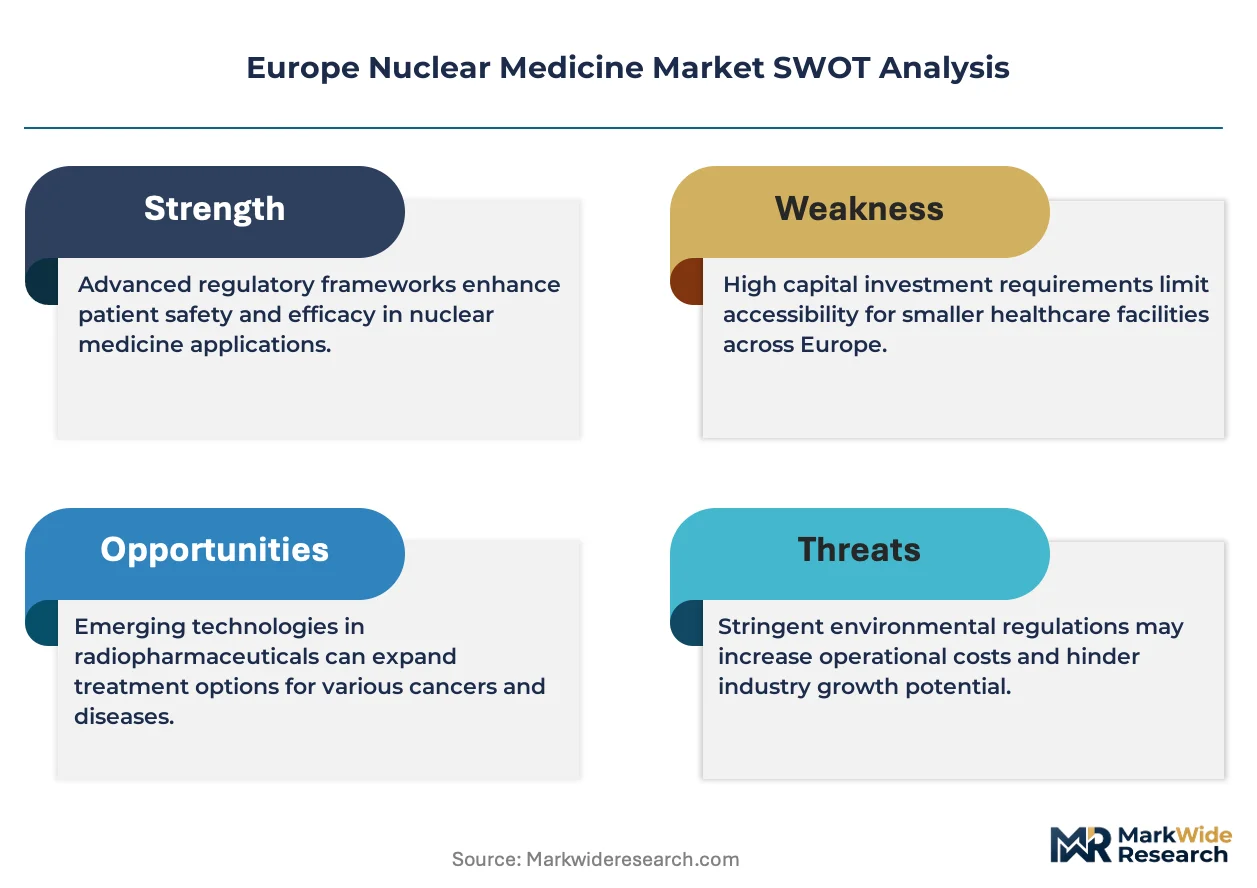
- REACH Compliance Burden:The EU's chemicals framework imposes costly registration requirements on precursor compounds used in radiopharmaceutical synthesis, elevating barriers for new market entrants.
- F-Gas Regulation Constraints:Fluorinated gas phase-out mandates limit certain isotope production chemistries, forcing capital-intensive process reengineering at established manufacturing sites.
Strategic Opportunities
- Poland and Czech Republic:Central European oncology networks remain underpenetrated by therapeutic radiopharmaceuticals, offering first-mover advantages for cyclotron-equipped distributors.
- MDR Transition Window:The EU Medical Device Regulation's 2027 enforcement deadline creates temporary regulatory clarity that favors early certifiers of combined drug-device radiopharmaceutical systems.
- Alpha-Emitter Theranostics:The pairing of actinium-225 therapy with companion diagnostics represents an emerging application category with limited established competition.
Industry Challenges
- Qualified Personnel Scarcity:Radiopharmacy specialists and nuclear medicine physicians require decade-long training pipelines that lag current therapeutic demand expansion.
- GMP Facility Certification:National regulators such as France's ANSM and Germany's BfArM enforce divergent inspection protocols, complicating multi-site manufacturing strategies.
- Legacy Cyclotron Integration:Existing particle accelerator infrastructure requires costly retrofitting to produce emerging therapeutic isotopes with non-standard energy requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nuclear Medicine Market |
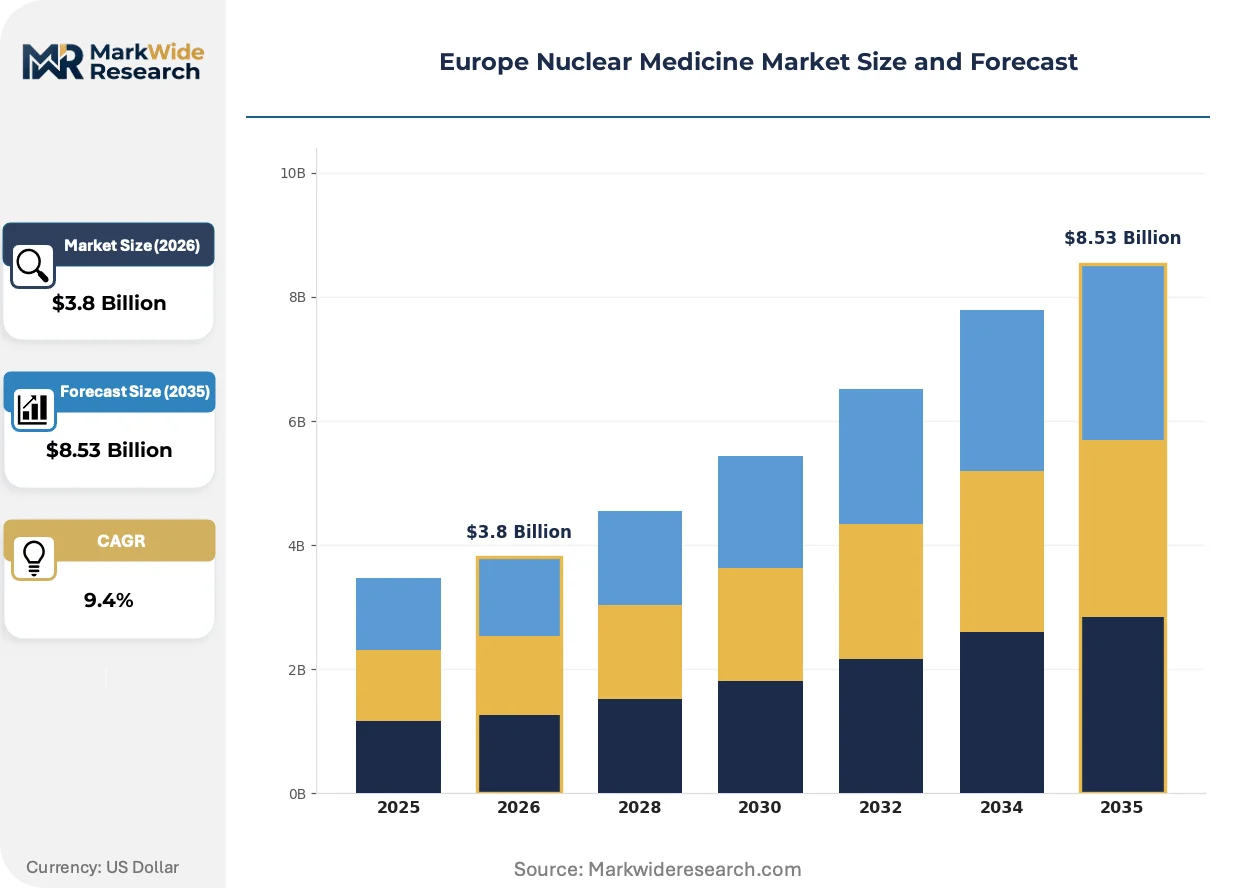
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Imaging, Therapeutic Agents, Radiopharmaceuticals, Radioisotopes End User: Hospitals, Clinics, Research Institutions, Diagnostic Centers Technology: Single Photon Emission Computed Tomography, Positron Emission Tomography, Hybrid Imaging, Radiochemistry Application: Oncology, Cardiology, Neurology, Infectious Diseases |
| Companies Covered | Cardinal Health, Curium Pharma, GE Healthcare, Novartis AG, Siemens Healthineers AG, Bayer AG, Bracco Imaging, Lantheus Holdings, Merck KGaA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nuclear Medicine Market Shifts & Advancements
Digital theranostics platforms are fusing molecular imaging data with AI-assisted dosing algorithms, compressing the gap between diagnostic visualization and therapeutic intervention. This convergence is redrawing competitive boundaries between device manufacturers and radiopharmaceutical developers.
Alpha-emitter radiochemistry is modularizing production workflows for actinium-225 and lead-212, enabling hospital-based radiopharmacies to generate patient-specific doses without centralized manufacturing dependencies. Major German cancer centers are piloting these systems to reduce cold-chain logistics constraints. The technology is modularizing supply chain architecture away from bulk isotope shipments toward distributed, just-in-time synthesis.
REACH and the EU F-Gas Regulation are tightening precursor chemical access for fluorine-18 production, forcing manufacturers to redesign synthesis routes or relocate certain process steps outside the EU regulatory perimeter. The industrial consequence is elevated capital intensity for new production capacity. France and Belgium, with established nuclear research infrastructure, are absorbing disproportionate investment as producers seek regulatory arbitrage within the single market.
Hospital procurement committees are consolidating vendor relationships for combined imaging-radiopharmaceutical contracts, displacing standalone isotope purchasing. Academic medical centers in the Netherlands and Switzerland are piloting long-term partnership models that bundle cyclotron maintenance, isotope supply, and therapeutic agent access. This concentration is most visible in university hospital systems with integrated oncology and nuclear medicine departments.
Europe Nuclear Medicine Market Segmentation
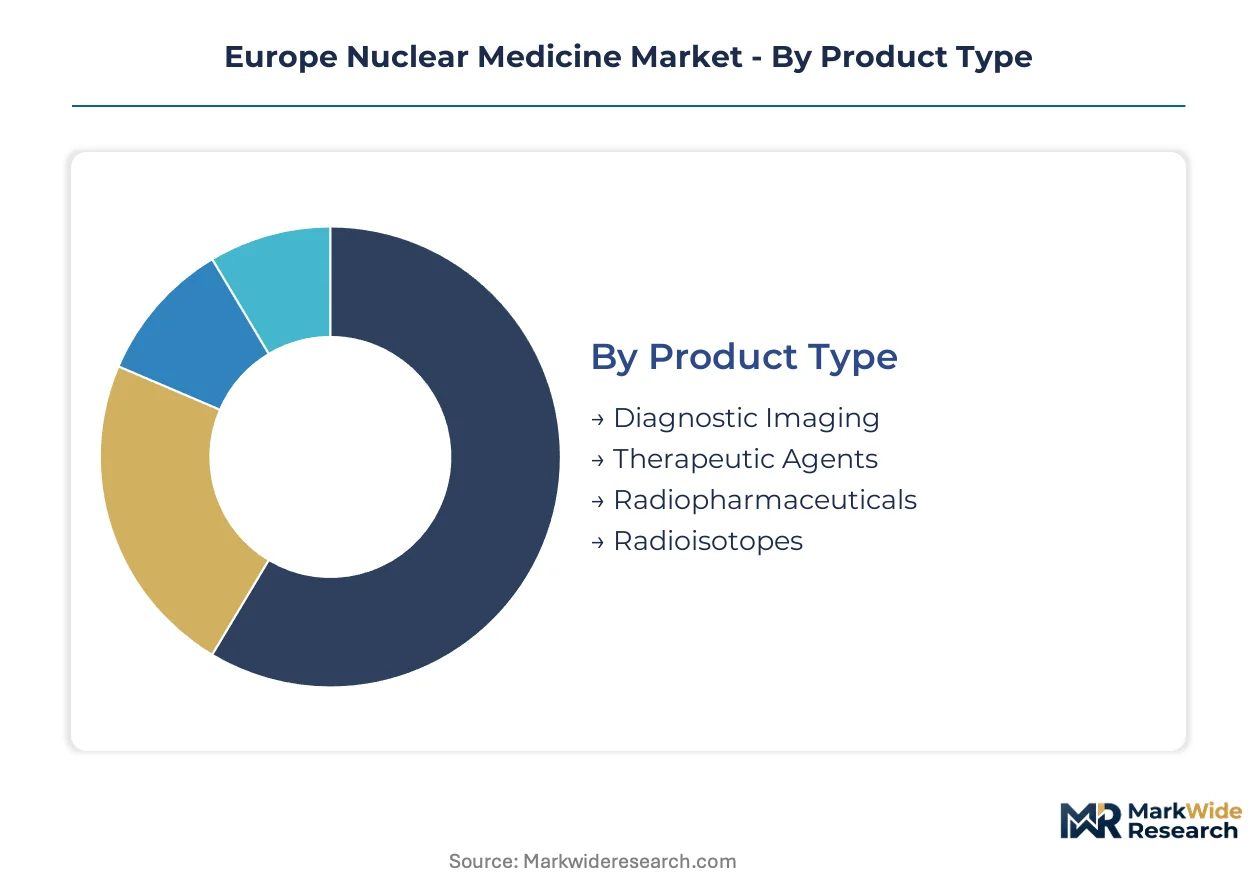
Segmentation in European nuclear medicine reveals how diagnostic and therapeutic modalities diverge in procurement patterns, reimbursement pathways, and facility infrastructure requirements. Understanding these divisions clarifies where capital investment concentrates and which patient populations drive volume economics.
Product Type:
Integration depth varies sharply: standalone radioisotopes feed external supply chains, while finished radiopharmaceuticals embed directly into hospital workflows.
- Therapeutic Agents:Lutetium-177 and actinium-225 formulations deliver targeted beta and alpha radiation to malignant cells with half-life precision measured in days. German university hospitals and French cancer centers anchor demand as reimbursement frameworks for precision oncology mature under EMA guidance.
- Diagnostic Imaging:Technetium-99m and fluorine-18 compounds enable functional visualization of perfusion, metabolism, and receptor density. Reliance on ageing research reactors in the Netherlands and Belgium concentrates supply risk for this workhorse category.
- Radiopharmaceuticals:Finished dosage forms combining isotope and carrier molecule for specific clinical indications.
- Radioisotopes:Bulk unprocessed radionuclides requiring further synthesis or compounding.
Volume placements concentrate in Diagnostic Imaging; the faster expansion belongs to Therapeutic Agents.
End User:
Customer scale dictates procurement sophistication, with large integrated systems commanding bundled contracts unavailable to smaller operators.
- Hospitals:Academic medical centers with in-house cyclotrons and nuclear medicine departments control the majority of therapeutic radiopharmaceutical consumption. Germany's university hospital clusters and the Netherlands' comprehensive cancer centers lead capital deployment for alpha-emitter infrastructure.
- Research Institutions:National nuclear research centers in France and Belgium generate isotopes for downstream distribution while advancing radiochemistry for emerging therapeutic applications.
- Clinics:Outpatient facilities without on-site production capabilities dependent on external radiopharmacy networks.
- Diagnostic Centers:Imaging-focused operators purchasing finished diagnostic agents rather than processing raw isotopes.
Procurement leverage clusters in Hospitals; Research Institutions capture the steepest funding trajectory for novel isotope development.
Technology:
Equipment lifecycle and replacement cycles separate mature modalities from convergent systems displacing standalone installations.
- Hybrid Imaging:PET-CT and PET-MR systems merge functional and anatomical data streams for real-time therapeutic monitoring. Major European referral centers in Switzerland and Austria are retiring standalone PET scanners in favor of these integrated platforms.
- Positron Emission Tomography:Detects positron-emitting isotope distribution with resolution measured in millimeters, remaining essential for neurology and cardiology despite hybrid displacement in oncology.
- Single Photon Emission Computed Tomography:Gamma camera-based tomography using technetium-99m tracers for cardiac stress testing and bone imaging.
- Radiochemistry:Synthesis and quality control infrastructure for on-site or centralized radiopharmaceutical production.
Installed base concentrates in Single Photon Emission Computed Tomography; Hybrid Imaging claims the fastest replacement cycle momentum.
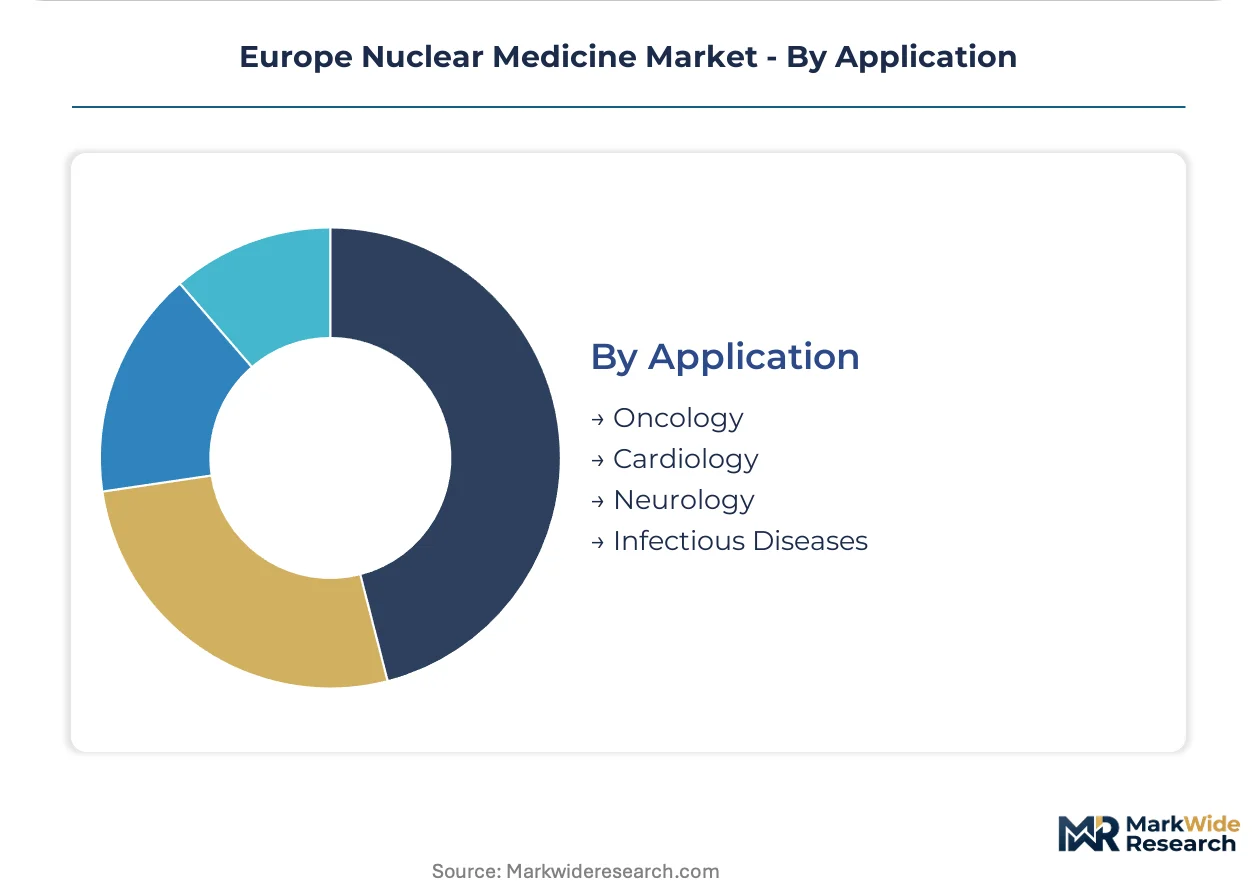
Application:
Clinical area determines isotope selection, dosing regimen complexity, and regulatory pathway for novel agent approval.
- Oncology:Theranostic pairing of diagnostic and therapeutic agents targeting identical tumor markers, with prostate-specific membrane antigen applications leading European adoption. France's ANSM has processed the majority of EMA-authorized radiopharmaceutical indications in this category.
- Neurology:Amyloid and tau PET imaging for neurodegenerative disease diagnosis, concentrated in specialized memory clinics and academic neurology departments.
- Cardiology:Myocardial perfusion imaging using technetium-99m sestamibi or tetrofosmin remains the dominant non-invasive stress test modality.
- Infectious Diseases:White blood cell labeling and specific pathogen imaging for occult infection localization.
Procedure volume concentrates in Cardiology; Oncology commands the fastest indication expansion and pricing premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's university hospital corridor anchors European therapeutic radiopharmaceutical deployment, with cyclotron clusters radiating across southern Germany into Austria and Switzerland.
Germany
Bavarian and North Rhine-Westphalian university hospitals drive lutetium-177 therapy volume through dedicated cyclotron networks. The BfArM enforces GMP compliance for multi-site manufacturing strategies. Heidelberg and Tübingen cancer centers pilot actinium-225 production workflows, reducing cold-chain dependencies for alpha-emitter therapies.
France
Paris-Saclay's nuclear research infrastructure feeds isotope supply chains across the Île-de-France region. ANSM processes the majority of EMA-authorized oncology indications for radiopharmaceuticals. Lyon and Grenoble radiochemistry facilities concentrate investment as producers seek regulatory arbitrage within REACH and F-Gas constraints.
Netherlands
Rotterdam and Amsterdam comprehensive cancer centers command bundled imaging-radiopharmaceutical procurement contracts. The Dutch national health system's reimbursement recalibration favors precision oncology agents. Petten's ageing research reactor creates technetium-99m supply vulnerability for diagnostic workflows.
Switzerland
Zurich and Basel academic medical centers deploy hybrid PET-CT systems for real-time therapeutic monitoring. Swissmedic maintains autonomous authorization pathways parallel to EMA centralized procedures. The country's radiopharmaceutical procurement committees consolidate vendor relationships across imaging and isotope supply.
Belgium
Mol's nuclear research center generates isotopes for downstream European distribution. The country's regulatory alignment with EMA frameworks streamlines cross-border patient access. Brussels-based hospital networks concentrate demand for neurology and cardiology diagnostic applications.
Europe Nuclear Medicine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the therapeutic-diagnostic divide, with lutetium-177 and actinium-225 formulations commanding pricing power against technetium-99m diagnostics. The market structure consolidates around vertically integrated isotope producers, hybrid imaging system manufacturers, and pharmaceutical developers with radiopharmaceutical pipelines. Three archetypes dominate: cyclotron network operators securing captive isotope supply, theranostic platform developers pairing diagnostics with therapy, and imaging equipment vendors bundling hardware with radiopharmaceutical contracts. Competitive moves concentrate on cyclotron capacity expansion and strategic partnerships between device manufacturers and radiopharmaceutical developers.
Among diversified healthcare conglomerates, GE Healthcare and Siemens Healthineers AG exemplify the imaging-systems archetype, while Novartis AG occupies a position within the theranostic pharmaceutical tier. Curium Pharma anchors the isotope production specialist category. These three represent distinct strategic postures: hardware-anchored platform control, pharmaceutical pipeline depth, and vertical integration into radionuclide supply chains.
| Leading Market Players |
|---|
| Cardinal Health |
| Curium Pharma |
| GE Healthcare |
| Novartis AG |
| Siemens Healthineers AG |
| Bayer AG |
| Bracco Imaging |
| Lantheus Holdings |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Radiopharmacy specialists concentrated in Bavaria and North Rhine-Westphalia command wage premiums that compress margins at hospital-based production sites, widening spreads between premium therapeutic formulations and commodity diagnostic isotopes across European procurement tiers.
Pricing Analysis
Value-based pricing anchored to progression-free survival outcomes for lutetium-177 therapies commands premium positioning against technetium-99m diagnostics sold on per-dose transactional terms. Price differentiation separates EMA-authorized therapeutics with centralized manufacturing from compounded hospital doses lacking cross-border portability. Cost compression in technetium-99m reflects concentrated reactor supply and generic substitution, while alpha-emitter therapies resist downward pressure due to qualified personnel scarcity. Academic medical centers with captive cyclotron capacity exhibit lowest price sensitivity; outpatient diagnostic centers dependent on external radiopharmacy networks face highest procurement cost exposure.
Supply Chain Analysis
Logistics costs for short-half-life isotopes consume disproportionate procurement budgets, with cold-chain requirements for actinium-225 doses exceeding conventional pharmaceutical freight multiples. Isotope supply concentrates in Belgium, France, and the Netherlands, where ageing research reactors and cyclotron clusters feed downstream European distribution. Raw material dependencies span enriched uranium targets for molybdenum-99, specialized precursor chemicals constrained by REACH registration, and fluorinated gases facing F-Gas Regulation phase-out. Single-source vulnerability at Petten's research reactor creates technetium-99m supply risk for diagnostic workflows. Distribution runs through hospital procurement committees consolidating vendor relationships for bundled imaging-radiopharmaceutical contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH and F-Gas Regulation create regulatory moats favoring incumbents with established GMP infrastructure and national regulator relationships.
For Market Incumbents: Extend cyclotron network coverage into Central European corridors before reimbursement frameworks mature in Poland and the Czech Republic. Secure backward integration into precursor chemical supply to offset REACH registration cost inflation. Curium Pharma's multi-state isotope production footprint demonstrates the defensive value of geographic redundancy against single-point reactor failures. For New Entrants and Emerging Players: The mid-tier pricing gap between premium therapeutics and economy diagnostics offers white-space positioning for regional radiopharmacy operators serving clinics without on-site production. Target hospital systems in Switzerland and Austria where bundled procurement committees seek alternatives to incumbent vendor concentration. Pursue GMP certification under France's ANSM pathway to exploit regulatory arbitrage within EU single-market access. For Investors and Strategic Acquirers: Re-rating potential sits with theranostic platform developers pairing companion diagnostics with alpha-emitter therapies given EMA's expanding oncology indication approvals. Long-term viability over a decade horizon favors entities with cyclotron assets and radiochemistry IP rather than pure-play pharmaceutical licensing. Monitor BfArM inspection queue depth as an inflection signal for manufacturing capacity constraints tightening supply-side discipline.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Centralized Authorization Pathway | Accelerates cross-border patient access for novel radiopharmaceuticals under single regulatory review. |
| Cyclotron Network Expansion | German university hospital clusters reduce cold-chain dependencies for short-half-life therapeutic isotopes. |
| Hybrid Imaging System Deployment | PET-CT convergence enables real-time therapeutic monitoring in major European referral centers. |
| GMP Facility Certification Investment | ANSM and BfArM compliance creates barrier-to-entry moat for multi-site manufacturing strategies. |
| Alpha-Emitter Theranostic Development | Actinium-225 pairing with companion diagnostics opens limited-competition application category. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with nuclear medicine physicians, radiopharmacy directors, hospital procurement managers, and EMA regulatory affairs specialists. Secondary sources encompassed EMA centralized authorization databases, ANSM and BfArM GMP inspection records, EU customs isotope trade flows, and national health system reimbursement decisions. Bottom-up modeling of cyclotron capacity and radiopharmaceutical dose volumes triangulated against top-down market sizing from healthcare expenditure tracking.
Segment-level granularity modeled product type splits between therapeutic agents and diagnostic imaging, technology adoption across hybrid and standalone modalities, and end-user concentration in academic medical centers versus outpatient clinics. Application dimensions tracked oncology, neurology, and cardiology procedure volumes. CAGRs derived from regression analysis of historical reimbursement trajectory and cyclotron installation pipeline data across the projection horizon. Forecast inputs incorporated EMA guidance timeline assumptions and national regulator inspection capacity constraints.
Underlying measurement precision varies by segment; therapeutic radiopharmaceutical volumes carry tighter precision given centralized manufacturing reporting than diagnostic isotope flows through fragmented hospital compounding. Forecasts reflect assumptions about reimbursement framework evolution and cyclotron construction timelines that stakeholder operating contexts may revise. Stakeholders should weight assumptions against their own regulatory engagement experience and capital deployment capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Medical Holography Market
Medical Imaging
Medical Videoscope Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Germany Mammography Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Global Automated Breast Ultrasound System (ABUS) Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
Medical Image Exchange System Market
Medical Imaging
Portable Ultrasound Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market