
 Global Technetium-99M Market | 2026-2036
Global Technetium-99M Market Size, Share, and Industry Trends Forecast 2026-2036
Global Technetium-99M Market Foresight
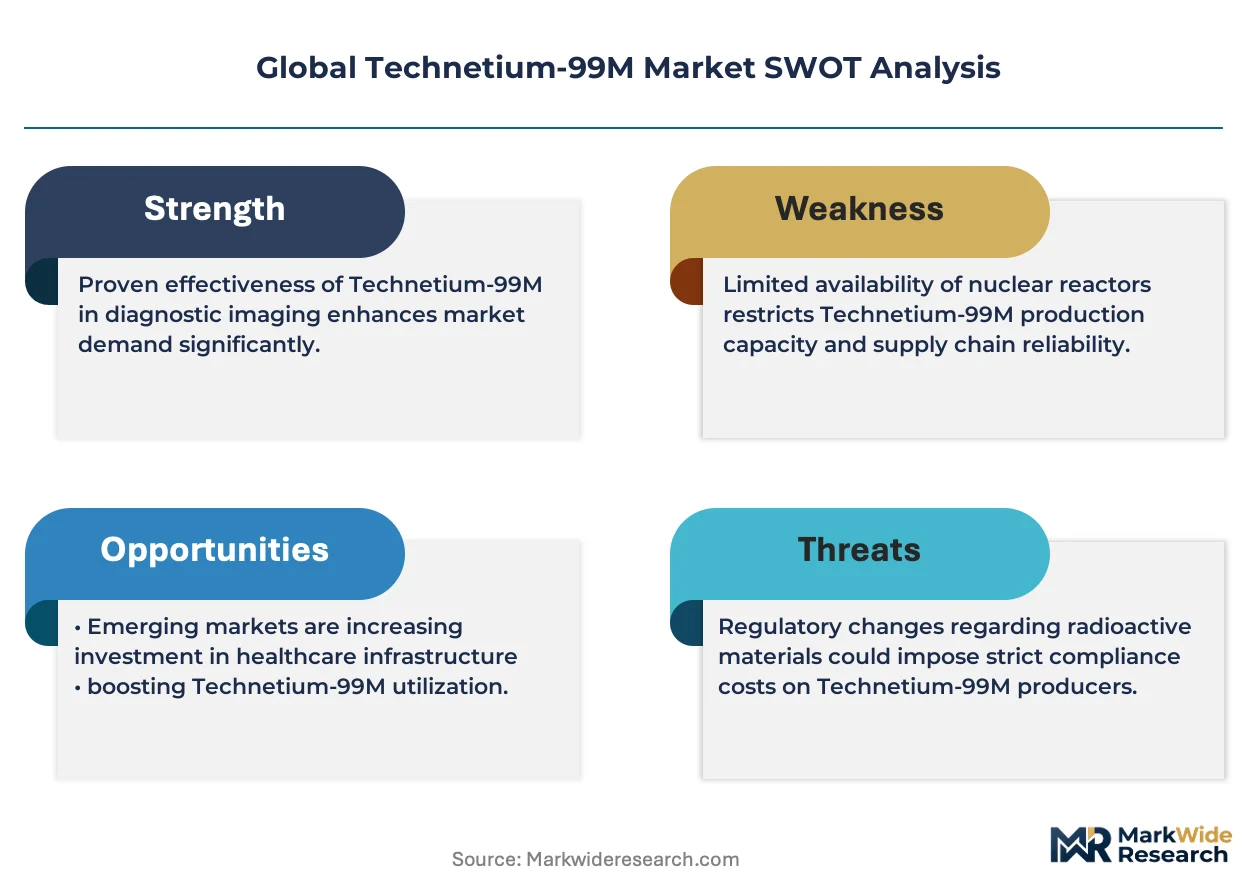
Hospital-based imaging centers are gaining procurement share as demand is bifurcating away from centralized nuclear pharmacy chains. GE Healthcare sustains generator manufacturing scale across North American and European distribution hubs. Siemens Healthineers leverages its integrated PET-SPECT platform footprint to lock in long-term technetium supply contracts. Lantheus Holdings anchors the radiopharmaceutical formulation segment through cold kit specialization.
Technetium-99M is a metastable nuclear isomer of technetium-99 with a half-life of six hours, produced primarily through molybdenum-99 decay in generator systems for diagnostic gamma camera imaging. Its primary commercial purpose is single-photon emission computed tomography (SPECT) procedures in functional organ assessment. Generator systems dominate installed base economics due to their on-site elution convenience and shielded transport logistics. Cyclotron production is expanding fastest as regional governments fund non-HEU supply diversification. Cold kits concentrate margin pools through proprietary ligand chemistry and regulatory exclusivity.
FDA and EMA oversight of molybdenum-99 supply chain security is tightening batch release documentation and HEU-to-LEU conversion timelines. The EU F-Gas Regulation and NRC agreement state requirements in the United States are reshaping generator transport container standards and cold chain compliance costs. Stakeholders must monitor which production technology secures national strategic stockpile designation.
Market Dynamics
The transition from highly enriched uranium to low-enriched uranium production pathways is restructuring molybdenum-99 supply economics and forcing capital redeployment across generator manufacturing networks.
Growth Catalysts
- EMA HEU-to-LEU conversion mandates:European regulatory deadlines are accelerating infrastructure investment in non-uranium production capacity.
- Cyclotron-produced technetium-99M:Regional governments in Canada and Australia are funding domestic cyclotron networks to reduce import dependency.
- Hospital-based imaging centers:These facilities are expanding direct generator procurement to secure supply continuity outside centralized pharmacy chains.
Market Restraints
- Molybdenum-99 supply concentration:Five aging research reactors in the Netherlands, Belgium, South Africa, Australia, and Canada still account for the majority of global production.
- Generator transport container costs:EU F-Gas Regulation compliance is raising cold chain logistics expenditure for cross-border shipments.
- Positron emission tomography substitution:PET imaging with fluorodeoxyglucose is capturing cardiac and oncology indications previously served by SPECT.
Strategic Opportunities
- India's diagnostic imaging expansion:CDSCO streamlined radiopharmaceutical approval pathways are opening generator markets in tier-two cities.
- Integrated PET-SPECT platform convergence:Hybrid imaging systems are creating bundled supply contracts that lock in long-term technetium offtake.
- United States strategic stockpile designation:National isotope program funding is creating procurement guarantees for domestic non-HEU producers.
Industry Challenges
- Qualified radiopharmacist scarcity:Generator elution and cold kit compounding require specialized personnel that academic programs are not producing at replacement rates.
- Batch release documentation complexity:FDA and EMA are tightening certificate of analysis requirements for each generator elution cycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Technetium-99M Market |
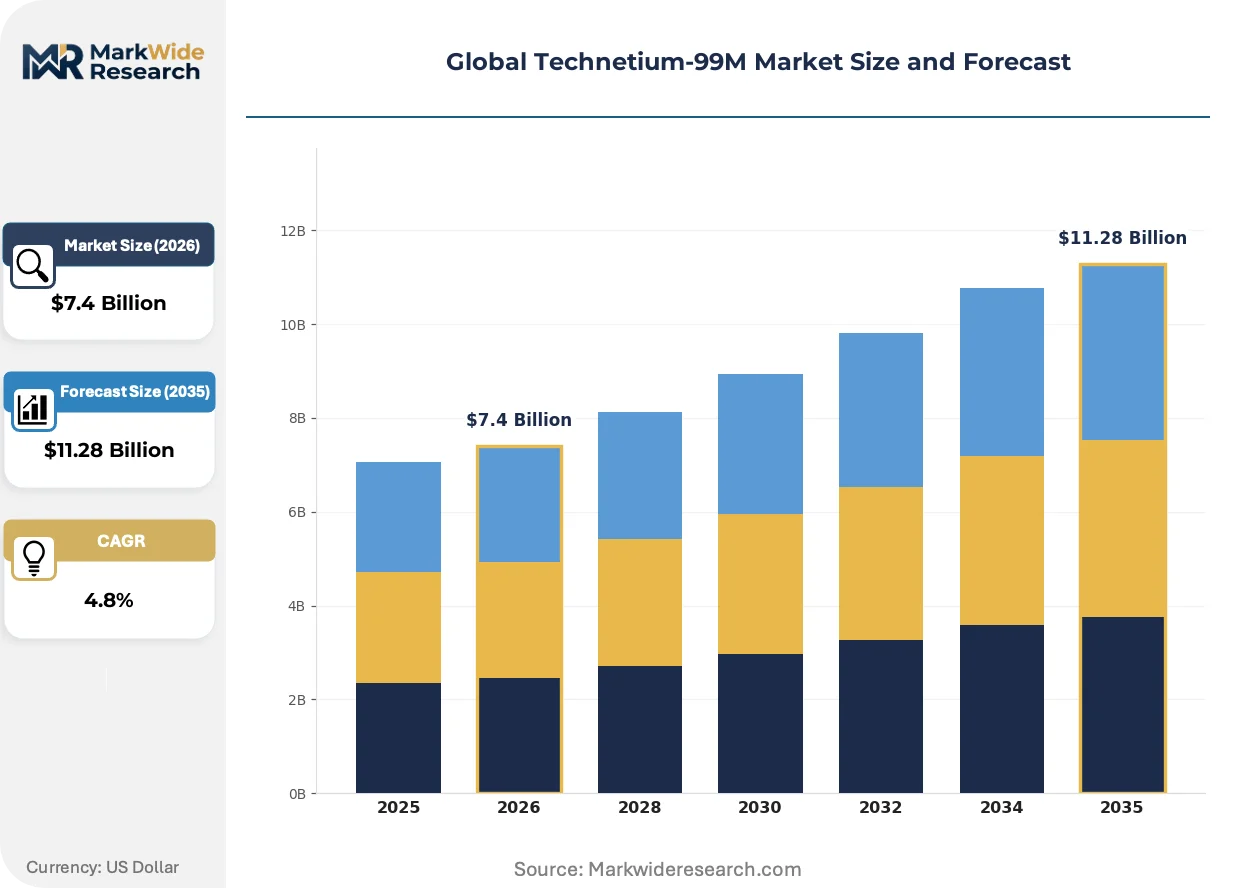
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Kits, Generators, Radiopharmaceuticals, Transport Containers Application: Cardiology, Neurology, Oncology, Skeletal Imaging End User: Diagnostic Labs, Pharmacies, Research Institutes, Imaging Centers Technology: Generator Systems, Cyclotron Production, Radiochemistry, Quality Control Instruments |
| Companies Covered | Siemens Healthineers, GE Healthcare, Lantheus Holdings, Curium, NorthStar Medical Radioisotopes, IBA, Jubilant Life Sciences, BWX Technologies, Advanced Cyclotron Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Technetium-99M Market Shifts & Advancements
Production technology diversification is disrupting the historical reactor-centric supply model while regulatory pressure on uranium enrichment is compressing legacy infrastructure economics.
Electron accelerator-based molybdenum-99 production is fragmenting the supply base away from nuclear reactor dependency. Medical isotope startups in Canada and the United States are deploying photonuclear systems to generate Mo-99 without uranium targets. This technology is enabling regional production hubs that bypass transcontinental transport logistics.
EU F-Gas Regulation phase-down schedules are forcing generator manufacturers to redesign transport containers with lower-global-warming-potential refrigerants. Container recertification timelines are extending from six months to eighteen months as new insulation materials undergo thermal validation. European distribution networks are absorbing these compliance costs through consolidated shipment scheduling.
Hospital procurement departments are consolidating radiopharmaceutical purchasing through group purchasing organizations to secure volume-based generator pricing. This behavior is compressing margins for independent nuclear pharmacies that lack scale to match hospital system negotiating leverage. The United States exhibits this pattern most acutely as health system consolidation accelerates in metropolitan markets.
Global Technetium-99M Market Segmentation
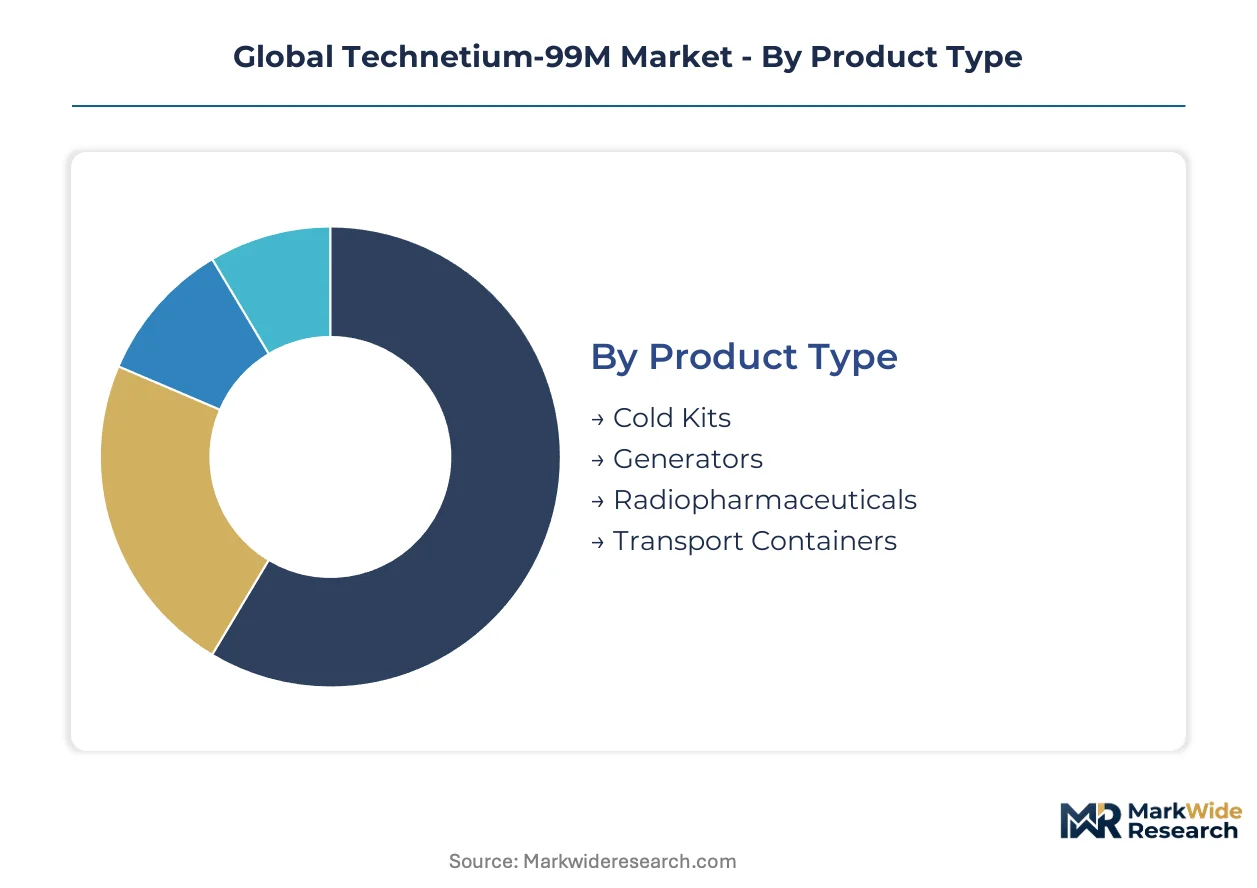
Technetium-99M market segmentation reveals distinct procurement patterns across product categories, with hospital systems and centralized pharmacies channeling demand through different supply configurations. Each segment category carries specific regulatory, logistical, and clinical constraints that shape vendor positioning and margin structures.
Product Type:
Generator systems flow through nuclear pharmacy distributors while cold kits concentrate margin in direct hospital contracting; transport containers and finished radiopharmaceuticals occupy intermediary channel positions with varying cold chain requirements.
- Generators:Shielded molybdenum-99 elution systems enable on-site technetium-99M production with six-hour half-life management. Demand concentrates in United States hospital imaging centers seeking supply security outside centralized pharmacy chains, driven by NRC generator possession licensing requirements.
- Cold Kits:Lyophilized ligand formulations requiring technetium-99M radiolabeling prior to patient administration. United States health system GPOs are consolidating procurement of proprietary cardiac and bone imaging kits, compressing independent pharmacy margins through volume-based contracting leverage.
- Radiopharmaceuticals:Pre-compounded technetium-99M labeled agents for immediate clinical use.
- Transport Containers:Lead-shielded vessels with F-Gas compliant refrigeration for generator cross-border shipment.
Generators dominate installed base. Cold kits are where expansion concentrates.
Application:
Clinical application segments stratify by reimbursement intensity, procedure volume, and PET substitution vulnerability across cardiac, oncologic, neurologic, and skeletal diagnostic categories.
- Cardiology:Myocardial perfusion imaging constitutes the highest-volume technetium-99M application globally. United States Medicare reimbursement patterns sustain SPECT procedure volumes despite fluorodeoxyglucose PET encroachment in tertiary centers.
- Oncology:Sentinel lymph node mapping and tumor perfusion studies utilizing technetium-99M sulfur colloid and sestamibi analogs. Australian and Canadian cyclotron networks are expanding regional production capacity to reduce import dependency for oncologic radiopharmaceuticals.
- Skeletal Imaging:Bone scintigraphy for metastasis detection and fracture assessment.
- Neurology:Cerebral perfusion studies for stroke and dementia evaluation.
Cardiology commands procedure volume. Oncology is climbing the fastest as sentinel node protocols expand.
End User:
End user segments diverge by regulatory sophistication, compounding capability, and procurement scale across institutional categories.
- Imaging Centers:Hospital-based and independent diagnostic facilities performing SPECT procedures with direct generator elution or kit radiolabeling. United States metropolitan health system consolidation is accelerating direct generator procurement by imaging centers seeking supply continuity guarantees.
- Diagnostic Labs:Clinical laboratories with radiopharmaceutical preparation capabilities.
- Pharmacies:Centralized nuclear pharmacy chains and hospital radiopharmacies.
- Research Institutes:Academic medical centers and government laboratories.
Imaging centers anchor demand volume. Diagnostic labs represent the steepest expansion trajectory as hospital outsourcing contracts proliferate.
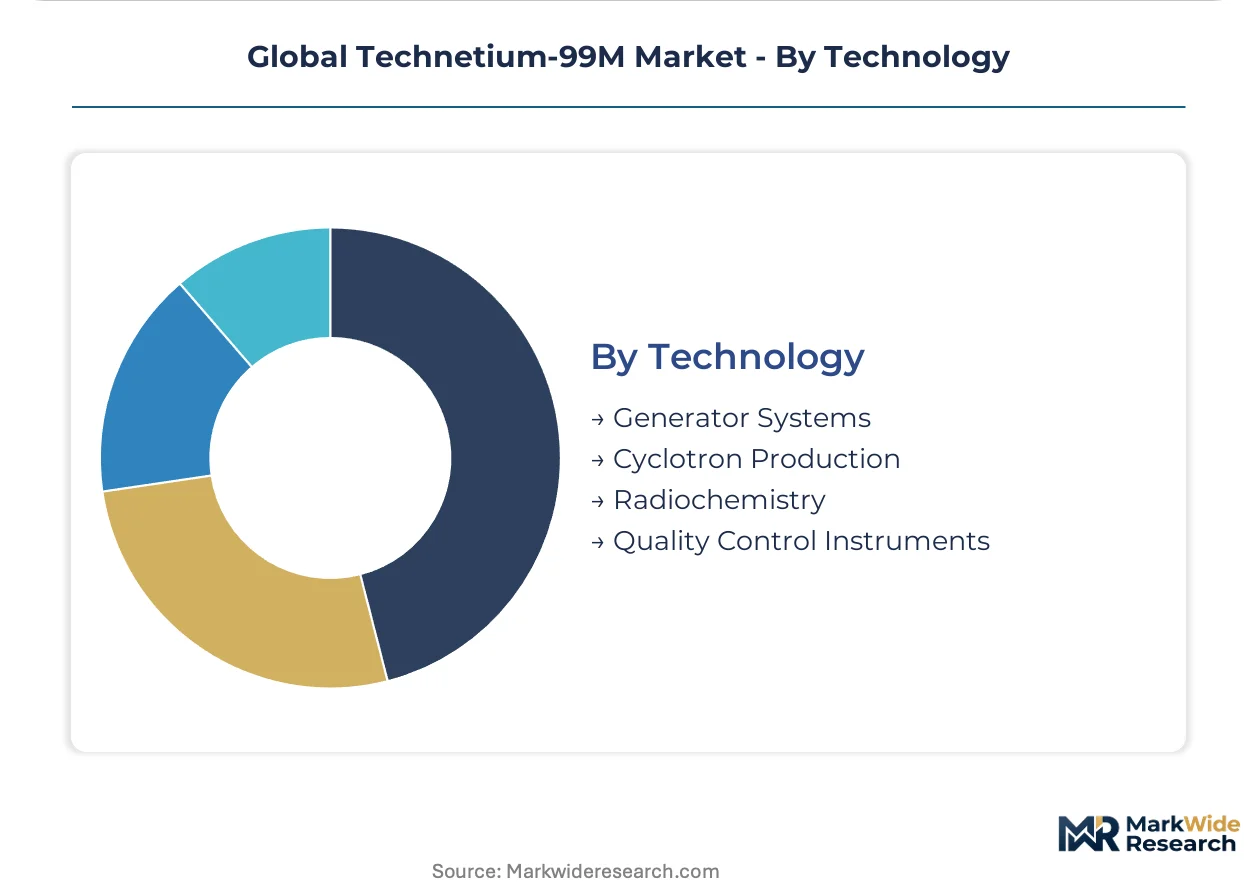
Technology:
Technology segments reflect the transition from reactor-dependent molybdenum-99 supply to diversified production architectures with distinct capital intensity and regulatory pathways.
- Generator Systems:Molybdenum-99/technetium-99M column elution technology with lead shielding and sterile saline eluent systems. Netherlands and Belgium reactor-produced molybdenum-99 still supplies the majority of global generator feedstock despite aging infrastructure.
- Cyclotron Production:Direct technetium-99M generation through proton bombardment of molybdenum-100 targets without uranium intermediate. Canada's national isotope program is funding regional cyclotron networks to establish non-HEU supply independence.
- Radiochemistry:Ligand synthesis and radiolabeling protocols for cold kit preparation.
- Quality Control Instruments:Chromatography and dose calibrator systems for elution validation.
Generator systems retain installed base dominance. Cyclotron production is gaining share fastest as EMA HEU-to-LEU mandates accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital imaging centers in the United States concentrate procurement volume, while cyclotron networks in Canada and Australia secure supply independence. European conversion mandates accelerate non-HEU infrastructure investment. India's diagnostic expansion and South Africa's aging reactor base complete the geographic demand map.
United States
Metropolitan health systems consolidate direct generator procurement to bypass centralized pharmacy chains. The FDA and NRC enforce HEU-to-LEU conversion timelines and generator possession licensing standards. NorthStar Medical Radioisotopes anchors domestic production in the Midwest, supplying non-uranium-derived molybdenum-99 to regional hospital networks.
Canada
Federal isotope program funding expands regional cyclotron networks for technetium-99M self-sufficiency. Health Canada coordinates with the national nuclear regulator to streamline non-reactor production approvals. Ontario and Quebec host the densest cyclotron concentration, with Toronto-area medical centers pioneering direct hospital-based elution systems.
Germany
EMA HEU-to-LEU mandates force generator manufacturers to redesign transport containers for F-Gas Regulation compliance. The EU F-Gas phase-down extends container recertification timelines from six to eighteen months. Bavaria's nuclear medicine clusters absorb compliance costs through consolidated shipment scheduling across Central European distribution hubs.
India
Tier-two city diagnostic imaging expansion drives generator demand outside traditional metro concentrations. CDSCO streamlined radiopharmaceutical approval pathways accelerate cold kit market entry. Maharashtra and Gujarat host the most active nuclear pharmacy licensing activity, with Mumbai-based imaging centers negotiating volume-based generator contracts.
Australia
Domestic cyclotron production targets reduction of import dependency for oncologic radiopharmaceuticals. The TGA aligns batch release documentation with tightened FDA and EMA certificate of analysis requirements. Lucas Heights and Sydney metropolitan medical centers lead sentinel lymph node protocol expansion, consuming rising technetium-99M sulfur colloid volumes.
Global Technetium-99M Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with integrated imaging platform footprints. Siemens Healthineers and GE Healthcare anchor the consolidated tier through generator manufacturing scale and distribution hub control. Three archetypes dominate: integrated imaging platform vendors, specialized radiopharmaceutical formulators, and regional cyclotron operators. Competitive moves center on long-term supply contract lock-ins and non-HEU production capacity expansion.
Within the integrated platform tier, Siemens Healthineers and GE Healthcare exemplify scale-driven positioning through combined generator manufacturing and imaging system bundling. Lantheus Holdings occupies the specialist archetype, anchoring radiopharmaceutical formulation through cold kit chemistry expertise. These three companies represent the structural concentration where procurement leverage, regulatory compliance depth, and clinical workflow integration converge.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Lantheus Holdings |
| Curium |
| NorthStar Medical Radioisotopes |
| IBA |
| Jubilant Life Sciences |
| BWX Technologies |
| Advanced Cyclotron Systems |
| Others |
Supply & Pricing Matrix
Generator manufacturing scale economies in the Netherlands and Belgium reactor complexes anchor global molybdenum-99 feedstock pricing, concentrating supply-side leverage among legacy producers while cyclotron entrants struggle to match unit economics. This concentration compresses price floors for hospital-based buyers in the United States and Germany, who absorb transport container recertification costs through consolidated shipment scheduling.
Pricing Analysis
Cost-plus contracts with molybdenum-99 feedstock indexation dominate generator procurement between nuclear pharmacy distributors and hospital imaging centers. Three-tier pricing structure across premium shielded generators, standard elution systems, and economy cold kit bundles reflects certification grade differentiation and volume scale. Pricing pressure stems from health system GPO consolidation in United States metropolitan markets, where independent nuclear pharmacies lack negotiating leverage against bundled radiopharmaceutical contracts. Independent imaging centers exhibit highest price sensitivity due to single-source generator dependency, while consolidated health systems leverage multi-year offtake guarantees for lowest tier access.
Supply Chain Analysis
Sixty-six hour molybdenum-99 half-life constraints compress inventory buffers and force just-in-time elution scheduling across generator distribution networks. Supply concentrates in the Netherlands, Belgium, and South Africa research reactor complexes, with raw material dependencies on highly enriched uranium targets, lead shielding components, and F-Gas compliant refrigerants. Single-source vulnerability from aging reactor infrastructure in the Netherlands and Belgium threatens batch release continuity. Distribution runs through nuclear pharmacy chains in North America and direct hospital procurement in European metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technetium-99M supply fragmentation creates arbitrage opportunities as production technology diversification disrupts historical reactor-centric procurement patterns. Hospital imaging center expansion outside centralized pharmacy chains generates niche contracting windows for non-HEU producers.
For Market Incumbents: Consolidate generator manufacturing scale through long-term molybdenum-99 supply agreements with emerging electron accelerator producers, defending against cyclotron substitution in Canadian and Australian markets. Lock in health system GPO contracts with bundled cold kit chemistry exclusivity to neutralize independent pharmacy price competition. Vertical integration into transport container recertification services captures F-Gas compliance margin pools. For New Entrants and Emerging Players: Regional cyclotron service gaps in India's tier-two cities offer penetrable white-space where CDSCO streamlined approvals reduce regulatory friction. Target diagnostic lab outsourcing contracts in United States metropolitan markets with direct elution system leasing models, bypassing nuclear pharmacy intermediaries. Position on non-HEU production credentials to secure national strategic stockpile designation procurement guarantees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cold kit formulators with proprietary ligand chemistry and regulatory exclusivity, offering subscription-like compounding service contracts. Long-term viability centers on production technology diversification away from reactor dependency, with electron accelerator and photonuclear systems capturing EMA HEU-to-LEU mandate tailwinds. Acquisition target archetype: regional cyclotron operators with Health Canada or TGA production approvals and hospital direct contracting relationships. Signal to watch: national isotope program funding announcements indicating strategic stockpile procurement guarantee allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Non-HEU Production Capacity Expansion | EMA conversion deadlines and FDA timelines accelerate capital deployment into electron accelerator and cyclotron infrastructure. |
| Hospital Direct Procurement Contracts | United States health system consolidation bypasses nuclear pharmacy chains, locking in generator offtake through GPO leverage. |
| Cold Kit Chemistry Patent Extension | Proprietary ligand formulations for cardiac and bone imaging sustain margin pools through regulatory exclusivity barriers. |
| Transport Container Recertification Services | EU F-Gas Regulation compliance extends container validation timelines, creating captive service revenue from generator manufacturers. |
| Regional Cyclotron Network Partnerships | Canada's national isotope program and Australia's TGA alignment fund domestic production hubs reducing import dependency. |
Research Methodology
A spread of perspectives from generator manufacturing executives, nuclear pharmacy procurement directors, hospital radiology administrators, and cyclotron operations specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA generator possession licensing records, EMA HEU-to-LEU conversion documentation, Health Canada isotope program disclosures, and CDSCO radiopharmaceutical approval databases. Bottom-up demand modeling from hospital imaging center installation counts and top-down supply assessment from reactor and cyclotron capacity announcements were triangulated for convergence.
Segmentation dimensions modeled include production technology type, product category configuration, clinical application area, and end-user procurement channel across the projection horizon. CAGRs were derived from installed base replacement cycles, procedure volume growth assumptions, and reimbursement pattern stability. Industry-specific forecast inputs incorporated molybdenum-99 half-life decay logistics, F-Gas Regulation compliance cost trajectories, and qualified radiopharmacist workforce expansion constraints.
Underlying assumptions cover EMA and FDA regulatory timeline adherence, reactor infrastructure retirement schedules, and cyclotron network funding continuity, with deviation risk concentrated in geopolitical export restriction scenarios and raw material uranium target supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
Argentina Nuclear Imaging Market
Medical Imaging
US Interventional Radiology Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Australia Digital X-Ray Market
Medical Imaging
Contrast Media Market
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
Image Guided Therapy Market