
 Plunger Pumps Market | 2026-2036
Plunger Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Plunger Pumps Market Analysis
Ceramic-coated plungers is rebalancing cost-performance trade-offs across high-pressure product lines. LEWA GmbH leverages its diaphragm-plunger hybrid expertise to anchor premium positioning in chemical processing. Flowserve Corporation sustains manufacturing scale across triplex and quintuplex configurations for oilfield services. Cat Pumps Inc. specializes in compact electric-drive units for pressure washing and industrial cleaning segments.
Plunger pumps are positive-displacement reciprocating devices that generate pulsating flow through the linear motion of a precision-machined plunger within a cylindrical barrel, typically achieving discharge pressures exceeding 1,000 bar depending on configuration and material selection. These pumps serve critical functions in chemical injection, high-pressure cleaning, and hydrocarbon transfer where precise volumetric delivery and resistance to abrasive media prove essential. Triplex configurations dominate oilfield chemical injection due to smoother flow characteristics and reduced pulsation dampening requirements. Quintuplex units command premium positioning in offshore and sour-service applications where redundancy and continuous duty cycles justify higher capital outlay. Electric drive types lead the water treatment and food processing sectors, while hydraulic drives retain dominance in mobile pressure-washing equipment.
API 674 and ISO 13709 standards govern materials, testing, and performance documentation for upstream oil and gas plunger pump deployments, directly influencing supplier qualification timelines and aftermarket parts compatibility. EPA effluent guidelines and OSHA process safety management requirements shape chemical processing procurement specifications, particularly for leak-free packing systems and emission controls. REACH compliance in Europe restricts certain chromium and nickel alloy formulations, pushing OEMs toward certified alternative metallurgies. Stakeholders must monitor evolving methane emissions regulations and carbon-intensity disclosure frameworks that are beginning to penetrate capital equipment procurement criteria across energy-intensive end-use sectors.
Market Dynamics
API 674 compliance timelines and ISO 13709 certification requirements are compressing supplier qualification windows while simultaneously elevating material specifications for sour-service deployments. This regulatory tightening is forcing foundry capacity reallocation toward certified alloy formulations.
Growth Catalysts
- Permian Basin shale activity:Sustained hydraulic fracturing intensity drives quintuplex pump deployments for high-pressure chemical injection at extended duty cycles.
- REACH metallurgy restrictions:ECHA limitations on chromium-nickel alloys are accelerating certified alternative material qualification programs across European process industries.
- Ceramic coating adoption:Advanced surface engineering extends plunger service intervals in abrasive media handling, reducing total cost of ownership for downstream operators.
Market Restraints
- Specialized foundry concentration:Certified alloy casting capacity clusters in Germany, Japan, and the United States, creating geographic supply vulnerability.
- Diaphragm pump substitution:Zero-leakage requirements in chemical processing favor hermetic diaphragm designs for hazardous fluid transfer.
- Extended API 674 testing protocols:Documentation and witness-test requirements add 4-6 months to supplier onboarding for upstream oilfield procurement.
Strategic Opportunities
- Saudi Aramco upstream expansion:Megaproject timelines create demand for redundant quintuplex configurations in sour-gas gathering and injection systems.
- Carbon-intensity disclosure frameworks:Emerging Scope 3 reporting mandates favor electric-drive plunger pumps over hydraulic units in water treatment applications.
- Predictive maintenance convergence:Vibration monitoring and IoT sensor integration enable condition-based service models for offshore platform deployments.
Industry Challenges
- Precision machining talent scarcity:Cylindrical grinding and ceramic coating application skills concentrate in aging workforce cohorts across Midwestern US and German manufacturing clusters.
- Legacy packing system integration:Emission-control retrofits on installed triplex pumps require mechanical redesign to accommodate leak-free sealing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plunger Pumps Market |
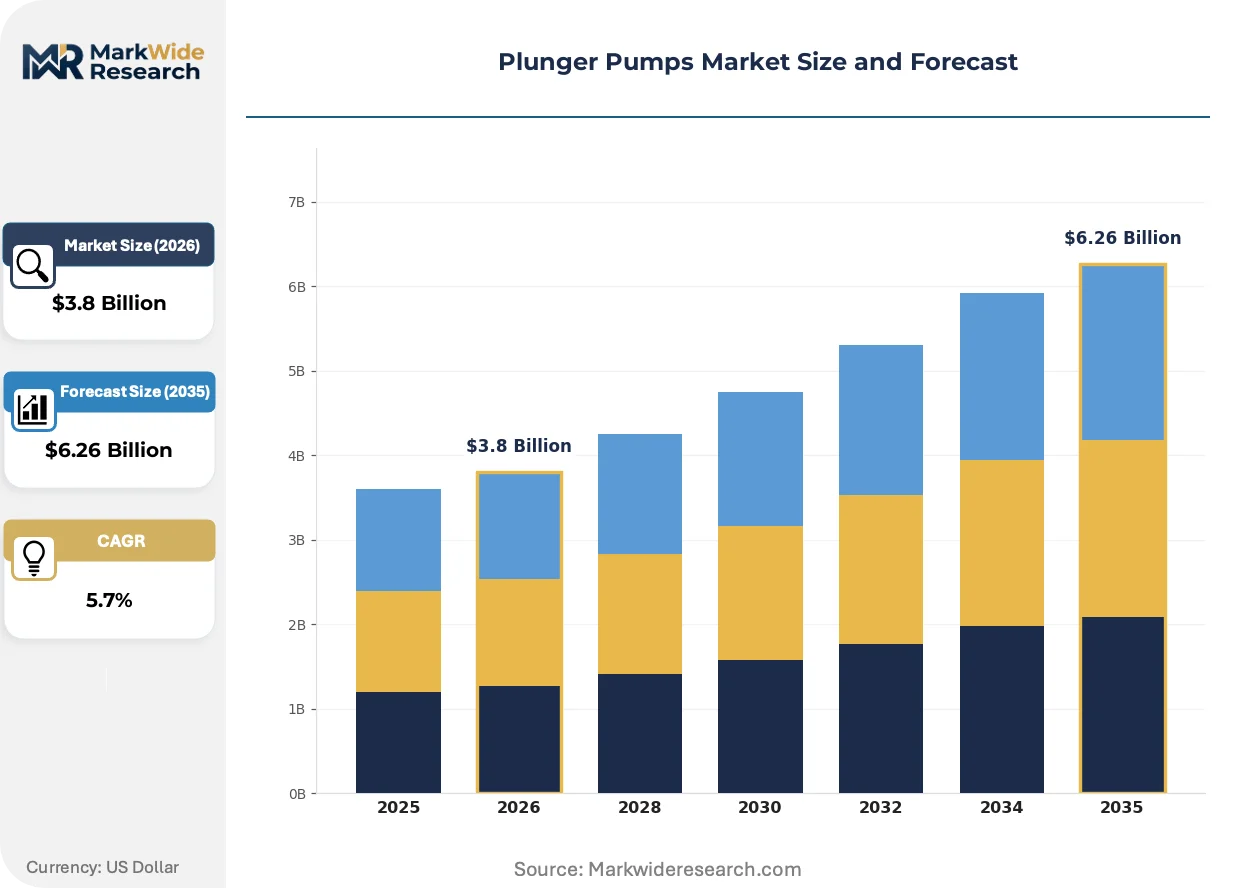
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Acting, Double Acting, Triplex, Quintuplex End User: Oil & Gas, Chemical Processing, Water Treatment, Food & Beverage Drive Type: Electric, Hydraulic, Pneumatic, Manual Application: Chemical Injection, Pressure Washing, High-Pressure Cleaning, Liquid Transfer |
| Companies Covered | Ruhrpumpen, Cat Pumps Inc., Muth Pump, LEWA GmbH, Flowserve Corporation, Standard Industrial Corp., GD Energy Products, Peroni Pompe S.r.l., Elteex Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plunger Pumps Market Emerging Trajectories
Ceramic surface engineering and electrification architectures are displacing conventional metallurgy and hydraulic drive systems across pressure-intensive applications. These shifts are compressing maintenance intervals while opening new verticals previously dominated by alternative pump technologies.
Ceramic-coated plungers are converging with tungsten carbide base substrates to achieve 4,000+ hour service life in proppant-laden fracturing fluids. Permian Basin operators are specifying these configurations for continuous-duty chemical injection skids. The technology is converging with real-time wear monitoring to enable predictive replacement scheduling rather than calendar-based maintenance.
EPA effluent guidelines and OSHA process safety management requirements are tightening emission thresholds for packing seal arrangements in chemical transfer service. Leak-free containment systems now dominate procurement specifications for hazardous fluid handling. North American refineries and European petrochemical complexes are retrofitting existing triplex installations with advanced sealing architectures to preempt regulatory enforcement.
Service unbundling is fragmenting traditional OEM aftermarket relationships as independent rebuild shops capture plunger reconditioning and packing replacement work. Oilfield service companies are insourcing routine maintenance to reduce downtime during fracturing campaigns. This pattern is most visible in Texas and North Dakota, where operator fleets exceed 500 units per pressure pumping provider.
Plunger Pumps Market Segmentation
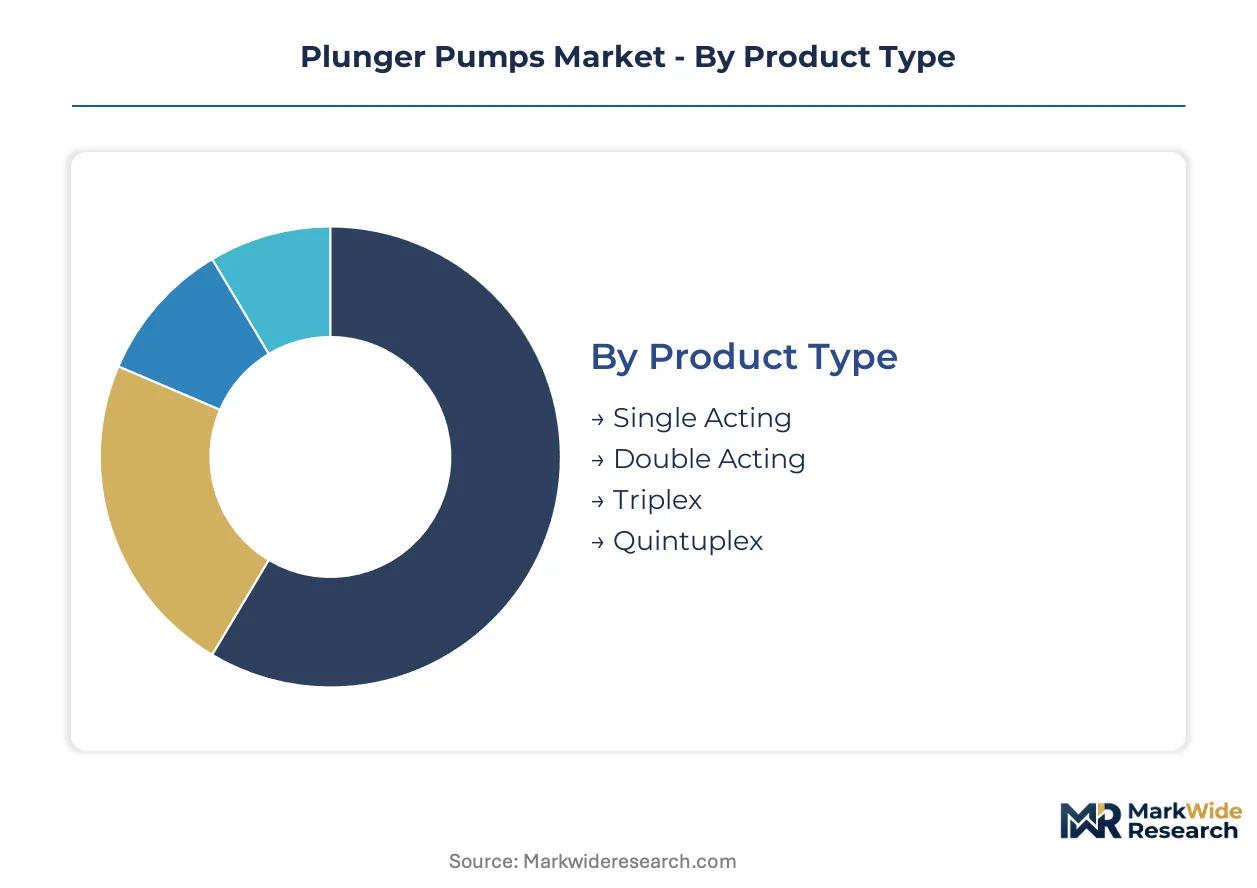
Configuration choices in plunger pumps determine pulsation characteristics, duty-cycle tolerance, and compliance pathways across pressure-intensive applications. Segmentation reveals where capital deployment concentrates versus where technology substitution is accelerating.
Product Type:
Standalone skid-mounted configurations dominate upstream oilfield deployments, while embedded multi-pump arrays serve integrated processing facilities.
- Single Acting:One discharge stroke per crankshaft revolution generates pronounced pulsation requiring substantial dampening infrastructure. Food & Beverage processors specify these for intermittent CIP cycles where pulsation tolerance exceeds capital constraints.
- Double Acting:Alternating suction and discharge on both plunger faces delivers smoother flow with reduced footprint. Water Treatment facilities in Germany and Japan embed these in membrane filtration skids where space optimization outweighs pulsation sensitivity.
- Triplex:Three plungers phased at 120 degrees achieve flow uniformity without external dampeners. Permian Basin operators deploy triplex arrays for continuous chemical injection at hydraulic fracturing sites.
- Quintuplex:Five-plunger architectures minimize residual pulsation amplitude for sour-service and subsea duties. Saudi Aramco upstream specifications mandate quintuplex redundancy for high-pressure gas injection systems.
Volume placements concentrate in Triplex; the faster expansion belongs to Quintuplex.
End User:
Customer archetypes diverge sharply between asset-intensive hydrocarbon operators and specification-driven hygienic processors.
- Oil & Gas:Upstream exploration companies and pressure pumping service providers drive demand for API 674-certified units rated beyond 1,000 bar. North Sea decommissioning activities and Permian Basin drilling intensity sustain replacement cycles.
- Chemical Processing:Petrochemical complexes and specialty chemical manufacturers prioritize zero-emission packing architectures. EPA process safety management and OSHA enforcement timelines accelerate upgrade schedules.
- Water Treatment:Municipal desalination plants and industrial wastewater facilities specify corrosion-resistant metallurgy for reverse osmosis feed applications. Carbon-intensity disclosure frameworks favor electric-drive configurations.
- Food & Beverage:Dairy processors and beverage bottlers require FDA-compliant wetted materials with clean-in-place compatibility. 3-A sanitary standards govern plunger surface finishes and seal elastomer selection.
Revenue concentration sits with Oil & Gas; Food & Beverage is climbing the fastest.
Drive Type:
Power transmission architecture determines maintenance cadence, energy efficiency, and mobility characteristics across stationary versus field-deployed assets.
- Electric:AC induction and permanent magnet synchronous motors deliver precise speed control with minimal environmental emissions. Water treatment facilities in the Netherlands and Singapore specify electric drives for carbon accounting compliance.
- Hydraulic:Diesel-hydraulic power packs dominate mobile pressure washing and offshore platform maintenance where grid connectivity is absent. Service companies in Texas maintain captive hydraulic fleets for fracturing campaign flexibility.
- Pneumatic:Compressed air actuation suits explosion-rated environments and food-grade washdown protocols. Chemical processing plants in Belgium deploy pneumatic units for solvent transfer in ATEX-classified zones.
- Manual:Hand-crank or lever-actuated mechanisms persist in laboratory calibration and emergency backup roles. Research institutions and military field kits specify manual redundancy for grid-independent operation.
Installed base tilts toward Electric; Hydraulic retains share in mobile segments.
Application:
Use-case specificity dictates plunger material, sealing architecture, and pulsation management requirements.
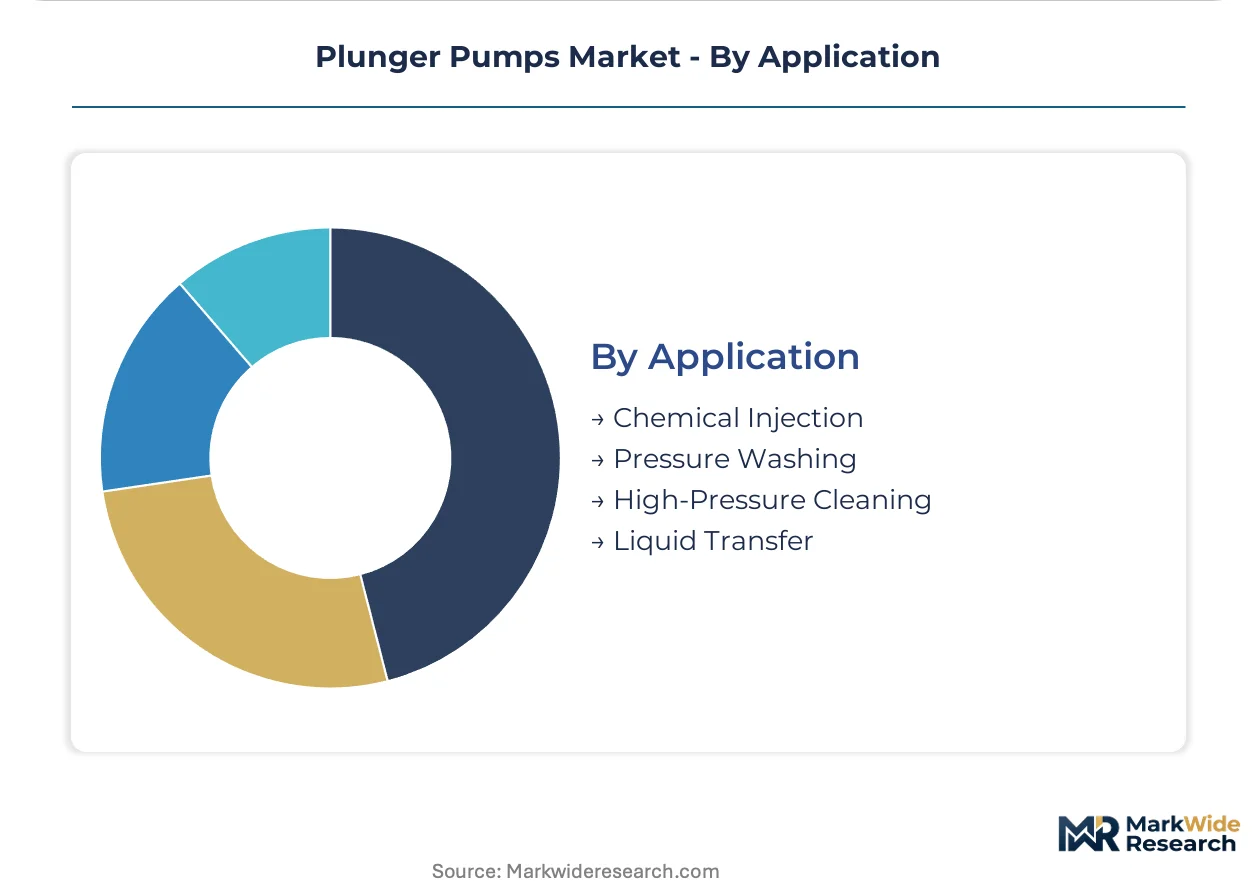
- Chemical Injection:Precise volumetric dosing of corrosion inhibitors and methanol into wellbore annuli demands pulsation-tolerant flow. Ceramic-coated plungers extend service intervals in proppant-laden fracturing fluids.
- Pressure Washing:Surface preparation and industrial cleaning operations require portable high-pressure output with rapid mobilization. Cat Pumps and similar specialists optimize compact electric-drive units for this segment.
- High-Pressure Cleaning:Fixed-installation CIP systems and heat exchanger maintenance demand continuous-duty ratings with automated control integration. Food processors specify 3-A compliant configurations with electropolished surfaces.
- Liquid Transfer:Viscous hydrocarbon and abrasive slurry handling requires hardened plunger materials and specialized packing geometries. Refinery turnaround operations drive seasonal demand spikes for rental transfer pumps.
Deployment scale favors Chemical Injection; High-Pressure Cleaning is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream oilfield activity clusters in the Permian Basin, Saudi Arabia's Eastern Province, and the North Sea, with each region imposing distinct certification regimes on pump procurement.
United States
Permian Basin pressure pumping fleets drive quintuplex pump demand for proppant-laden fracturing fluids. EPA effluent guidelines and OSHA process safety management requirements tighten packing seal specifications for chemical injection service. Houston and Midland-Odessa host the densest concentrations of pump rebuild shops and OEM service centers.
Germany
REACH restrictions on chromium-nickel alloys accelerate certified alternative material programs across Ruhr industrial corridors. ECHA enforcement timelines compress supplier qualification windows for European process industries. Düsseldorf and Essen anchor foundry capacity for API 674-certified alloy castings serving Middle East export markets.
Saudi Arabia
Saudi Aramco megaproject timelines create demand for redundant quintuplex configurations in sour-gas gathering systems. SFDA-equivalent national standards for pressure equipment align with ISO 13709 certification pathways. The Eastern Province concentrates fabrication yards and pump assembly facilities for upstream expansion programs.
Japan
Precise volumetric dosing requirements in semiconductor chemical processing sustain demand for ceramic-coated plunger architectures. METI industrial standards govern material traceability for high-purity fluid handling applications. Osaka and Nagoya manufacturing clusters specialize in cylindrical grinding and surface engineering for Asian export markets.
United Kingdom
North Sea decommissioning activities and remaining production operations sustain replacement cycles for triplex chemical injection pumps. Health and Safety Executive pressure systems regulations mandate documented compliance for offshore platform equipment. Aberdeen maintains service infrastructure for subsea pump maintenance and packing system retrofits.
Plunger Pumps Market Vendor Landscape
Capacity expansion dominates the current landscape as foundries allocate certified alloy production toward API 674-qualified castings. The vendor base stratifies across three tiers: integrated multinationals with full-spectrum oilfield service portfolios, mid-scale specialists concentrating on configuration-specific architectures, and regional rebuild shops capturing aftermarket maintenance. Strategic archetypes include OEMs leveraging diaphragm-plunger hybrid expertise for chemical processing premiums, and scale-driven fabricators optimizing triplex and quintuplex production lines for oilfield volume. Geographic expansion and technology licensing represent the dominant competitive vectors.
Within the integrated multinational tier, Flowserve Corporation and LEWA GmbH exemplify scale-driven positioning across upstream and process industry segments. Among configuration specialists, Cat Pumps Inc. occupies a position in compact electric-drive architectures for industrial cleaning applications. Ruhrpumpen and Peroni Pompe S.r.l. represent regional fabricators with concentration in European and Middle Eastern procurement channels respectively. GD Energy Products anchors North American oilfield service positioning, while Muth Pump and Standard Industrial Corp. sit within the mid-scale specialist tier serving regional pressure pumping markets.
| Leading Market Players |
|---|
| Ruhrpumpen |
| Cat Pumps Inc. |
| Muth Pump |
| LEWA GmbH |
| Flowserve Corporation |
| Standard Industrial Corp. |
| GD Energy Products |
| Peroni Pompe S.r.l. |
| Elteex Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive foundry integration into certified alloy casting anchors both supply security and pricing power for API 674-qualified pump OEMs. This backward control over metallurgy insulates premium-tier producers from raw material volatility while forcing mid-market competitors toward outsourced procurement with compressed margins.
Pricing Analysis
Volume placements concentrate in standard-grade triplex configurations with thin margins, while quintuplex sour-service units command premium positioning. Pricing stratifies across API 674-certified, ISO 13709-compliant, and uncertified economy tiers based on material traceability and witness-test documentation. Cost compression in standard-grade products is intensifying because foundry capacity reallocation toward certified alloys constrains supply. Water treatment and food processing buyers exhibit highest price sensitivity; offshore oilfield operators show least sensitivity due to redundancy requirements and total cost-of-ownership framing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Saudi Aramco and Permian Basin pressure pumping fleets, while distributor networks serve mid-scale process industry procurement. Certified alloy casting concentrates in Germany, Japan, and the United States. Production draws from nickel-chromium feedstock, tungsten carbide substrates, and ceramic coating precursors. Single-source vulnerability runs through German foundry clusters serving Middle East export markets. Distribution runs through OEM-direct contracts for upstream oilfield, authorized distributors for process industries, and independent rebuild shops for aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive control over certified alloy foundry capacity to secure API 674 qualification timelines and defend margin structure against material cost volatility.
For Market Incumbents: Hedge against diaphragm pump substitution in chemical processing by accelerating ceramic-plunger hybrid development and locking in long-term foundry offtake agreements. Diaphragm hermetic designs threaten zero-emission chemical transfer segments. Backward integration into certified alloy casting insulates supply security and compresses competitor qualification windows. For New Entrants and Emerging Players: Launch via independent rebuild shop partnerships to capture aftermarket fragmentation in Texas and North Dakota pressure pumping markets. Food and beverage sanitary applications offer the most penetrable white-space given 3-A certification barriers that favor specialized engineering over capital scale. Target electric-drive compact architectures for industrial cleaning where brand concentration remains dispersed. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated oilfield service conglomerates seeking pump manufacturing capability. Long-term viability hinges on certification moats and foundry access rather than volume scale alone. Watch for EPA methane emissions enforcement timelines as inflection indicator for electric-drive configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Foundry Capacity Expansion | API 674 qualification timelines anchor competitive positioning in upstream oilfield procurement. |
| Ceramic Coating Technology Licensing | Surface engineering partnerships extend service intervals for Permian Basin proppant-laden applications. |
| Predictive Maintenance Platform Integration | IoT sensor deployment enables condition-based service models for offshore platform operators. |
| REACH-Compliant Metallurgy Transition | ECHA restrictions on chromium-nickel alloys force material qualification programs across European process industries. |
| Electric-Drive Configuration Development | Carbon-intensity disclosure frameworks favor electric units over hydraulic drives in water treatment sectors. |
Methodological Framework
Independent corroboration across OEM product managers, foundry operations directors, and oilfield service procurement leads underwrites the qualitative findings. Primary fieldwork included maintenance directors at Permian Basin pressure pumping fleets, chemical processing plant engineers in Germany and Belgium, and aftermarket service heads at independent rebuild shops. Secondary validation drew from API 674 documentation databases, EPA effluent guideline enforcement records, ECHA REACH restriction announcements, and customs trade data for certified alloy castings. Bottom-up unit placement estimates and top-down industry spend analysis were triangulated to anchor volume and value outputs.
Comparable-period anchoring to historical replacement cycles and upstream capital expenditure patterns structured the projection framework. The analytical model segmented by configuration type, end-use industry, drive architecture, and regional regulatory cluster across the modeling period. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers. Forecast inputs included Saudi Aramco megaproject timelines, North Sea decommissioning schedules, and EPA/OSHA enforcement trajectory assumptions.
Upstream capital expenditure volatility, REACH metallurgy restriction expansion, and diaphragm pump technology advancement are the dominant revision risks. Forecasts reflect assumptions regarding certification timeline stability and foundry capacity allocation continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Submersible Pumps Market
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Canned Motor Pumps Market
Pumps and Control Devices
Electrohydraulic Pumps Market
Pumps and Control Devices
Global Reciprocating Pumps Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Food and Beverages Industry Pumps Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
Membrane Pump Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
Industrial Pumps Market