
 Electric Submersible Pump (ESP) in Oil and Gas Market | 2026-2036
Electric Submersible Pump (ESP) in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Submersible Pump (ESP) in Oil and Gas Market Insights
Condition-based monitoring subscriptions is pivoting how vendors monetize ESP fleets beyond hardware sales. Baker Hughes leverages digital twin diagnostics to lock in recurring revenue from offshore operators. Schlumberger anchors its position through integrated artificial lift service contracts spanning installation through abandonment. Weatherford competes on modular retrofit kits that extend run life in mature wells without full workovers.
An Electric Submersible Pump (ESP) in Oil and Gas is a centrifugal pump-motor assembly hermetically sealed and deployed downhole to lift hydrocarbons from reservoir to surface, typically operating at motor speeds of 3,600 rpm and handling fluid volumes from 150 to 150,000 barrels per day across multistage configurations. Its primary purpose is artificial lift in wells where natural reservoir pressure proves insufficient for commercial flow rates. Multistage ESP systems dominate capital allocation due to their indispensability in high-volume offshore developments where failure costs escalate into millions per day. Onshore facilities represent the fastest-growing end-user category as shale producers redeploy ESPs for secondary recovery in stripper wells. Control systems technology commands disproportionate margin attention because real-time variable speed drives and downhole sensor integration determine run-life economics.
API specification 11S and ISO 15551 govern ESP design verification and material traceability, while BSEE well control regulations in the US Gulf and PSA Norway standards enforce subsea equipment redundancy that elevates procurement qualification barriers. The EU F-Gas Regulation restricts fluorinated greenhouse gas use in ESP cooling systems, pushing manufacturers toward dry motor architectures and synthetic dielectric fluids. Stakeholders must monitor how methane emission intensity benchmarks from the EPA and evolving EU taxonomy criteria reshape operator preferences between ESP and gas lift alternatives.
Market Dynamics
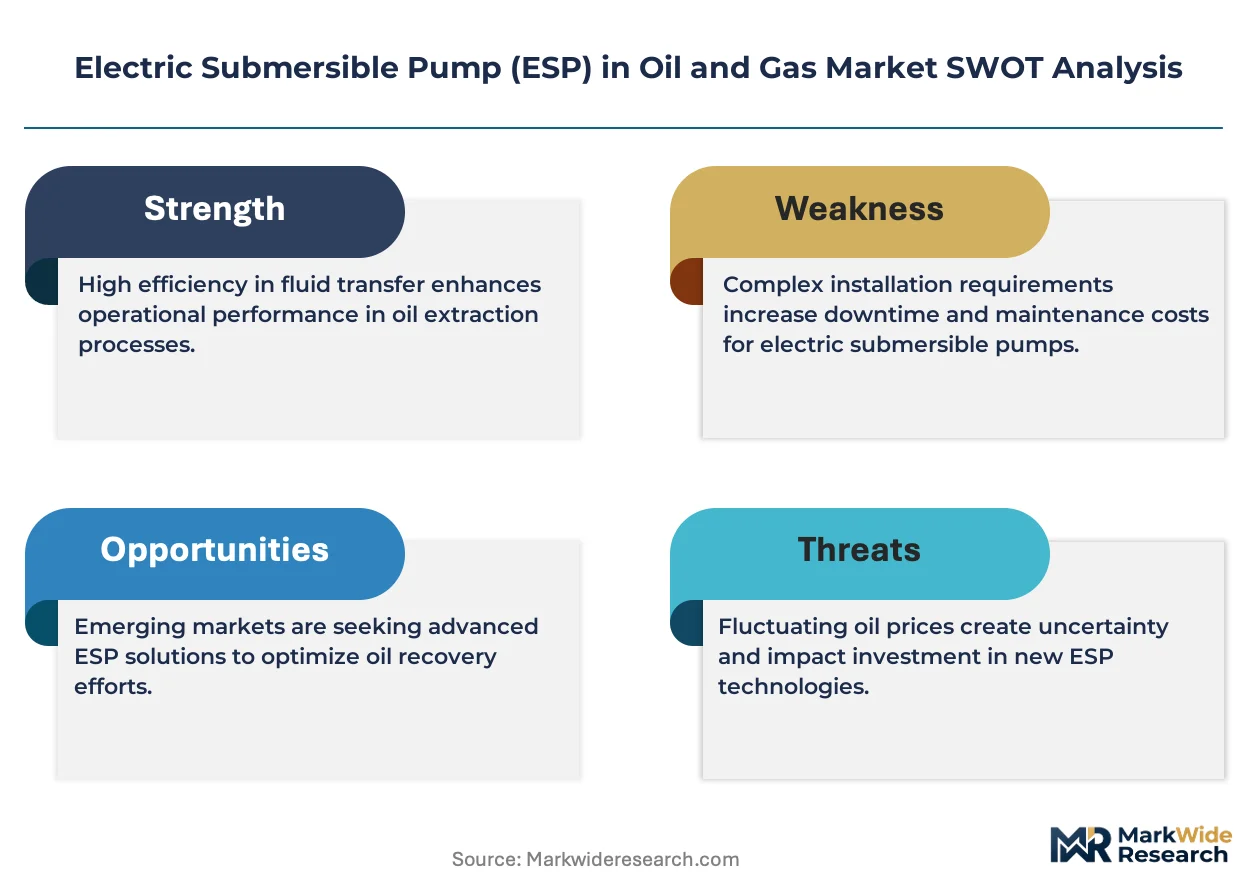
Deepwater operators are forcing ESP manufacturers toward permanent magnet motor architectures and real-time downhole telemetry to cut intervention frequency in subsea tiebacks where rig rates exceed half a million dollars daily.
Growth Catalysts
- BSEE Well Control Regulations:Mandated subsea equipment redundancy in the US Gulf elevates qualification barriers, locking in premium-tier suppliers and extending contract tenures for qualified vendors.
- Pre-salt carbonate reservoirs:Brazil's Santos Basin developments require high-temperature ESP systems rated above 200°C, pulling multistage pump-motor assemblies into ultra-deepwater service envelopes.
- Digital twin integration:Condition-based monitoring platforms enable predictive failure modeling that stretches run life and converts hardware sales into recurring software subscriptions.
Market Restraints
- Permanent magnet supply concentration:Rare earth processing dominance in China creates procurement vulnerability for high-efficiency motor programs targeting offshore specifications.
- Fluorinated gas restrictions:EU F-Gas Regulation phases out SF6 and PFAS-based dielectric coolants, forcing costly dry motor redesigns and synthetic fluid qualification cycles.
- Gas lift economics:Associated gas availability in Middle East fields and US Permian flaring constraints make gas lift competitive for marginal wells, capping ESP penetration in stripper well segments.
Strategic Opportunities
- Plug-and-abandonment retrofit kits:Modular ESP systems that deploy through existing wellheads without workover rigs unlock marginal barrel recovery in maturing North Sea assets.
- EPA methane intensity benchmarks:Emissions accounting rules favor ESPs over gas lift in carbon-conscious operator procurement scorecards, creating regulatory tailwind in US onshore markets.
- Variable speed drive convergence with edge computing:Real-time optimization algorithms embedded at the wellsite reduce power consumption and extend motor insulation life in high-GOR applications.
Industry Challenges
- Subsea electrical technician scarcity:Downhole cable splicing and wet-mate connector certification require specialized training pipelines that lag fleet expansion timelines in Brazil and Norway.
- API 11S qualification bottlenecks:Third-party verification queues for high-temperature metallurgy and elastomer compatibility testing extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Submersible Pump (ESP) in Oil and Gas Market |
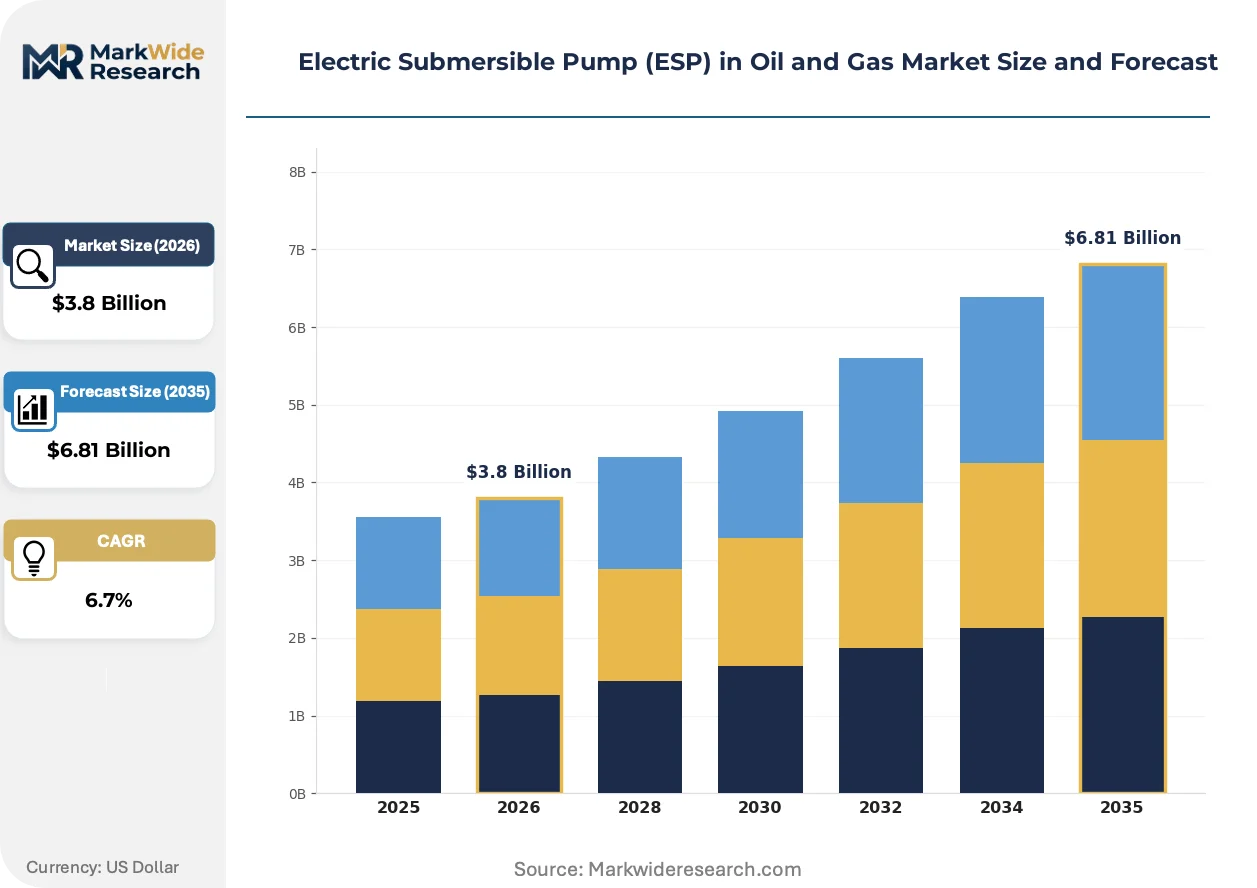
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical ESP, Horizontal ESP, Multistage ESP, Electrical Submersible Pump Systems End User: Oil Fields, Gas Fields, Offshore Platforms, Onshore Facilities Application: Well Pumping, Water Injection, Enhanced Oil Recovery, Production Boosting Technology: Motor Types, Pump Designs, Control Systems, Cable Configurations |
| Companies Covered | Borets International, Weatherford, Schlumberger, Atlas Copco, Flowserve Corporation, Baker Hughes, Novomet, EBARA Corporation, Halliburton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Submersible Pump (ESP) in Oil and Gas Market Trends and Innovations
Permanent magnet motor technology is compressing power consumption curves while downhole sensor density is rewriting maintenance economics across offshore and shale plays.
Axial-flux permanent magnet motors are absorbing the high-torque requirements of slimhole ESP deployments in extended-reach laterals. US shale operators in the Permian and Eagle Ford are retrofitting legacy induction motor fleets with permanent magnet systems to cut surface power demand by one-third. The technology is absorbing capital allocation from variable frequency drive upgrades as the primary lever for operating expenditure reduction.
EU F-Gas Regulation mandates phase-down of fluorinated greenhouse gases in ESP cooling systems by 2030. Manufacturers are accelerating dry motor architectures and synthetic ester dielectric fluid qualification to maintain CE marking access. Offshore platform operators in the Norwegian North Sea face the steepest compliance timeline, with PSA Norway auditing cooling system inventories ahead of statutory deadlines.
Subscription-based performance contracts are displacing traditional unit-sales relationships in offshore procurement. Gulf of Mexico operators now contract guaranteed run-life outcomes rather than equipment purchases, transferring downhole failure risk to vendors. This model concentrates in deepwater Brazil and US federal waters where daily production loss costs dwarf hardware replacement values.
Electric Submersible Pump (ESP) in Oil and Gas Market Segmentation
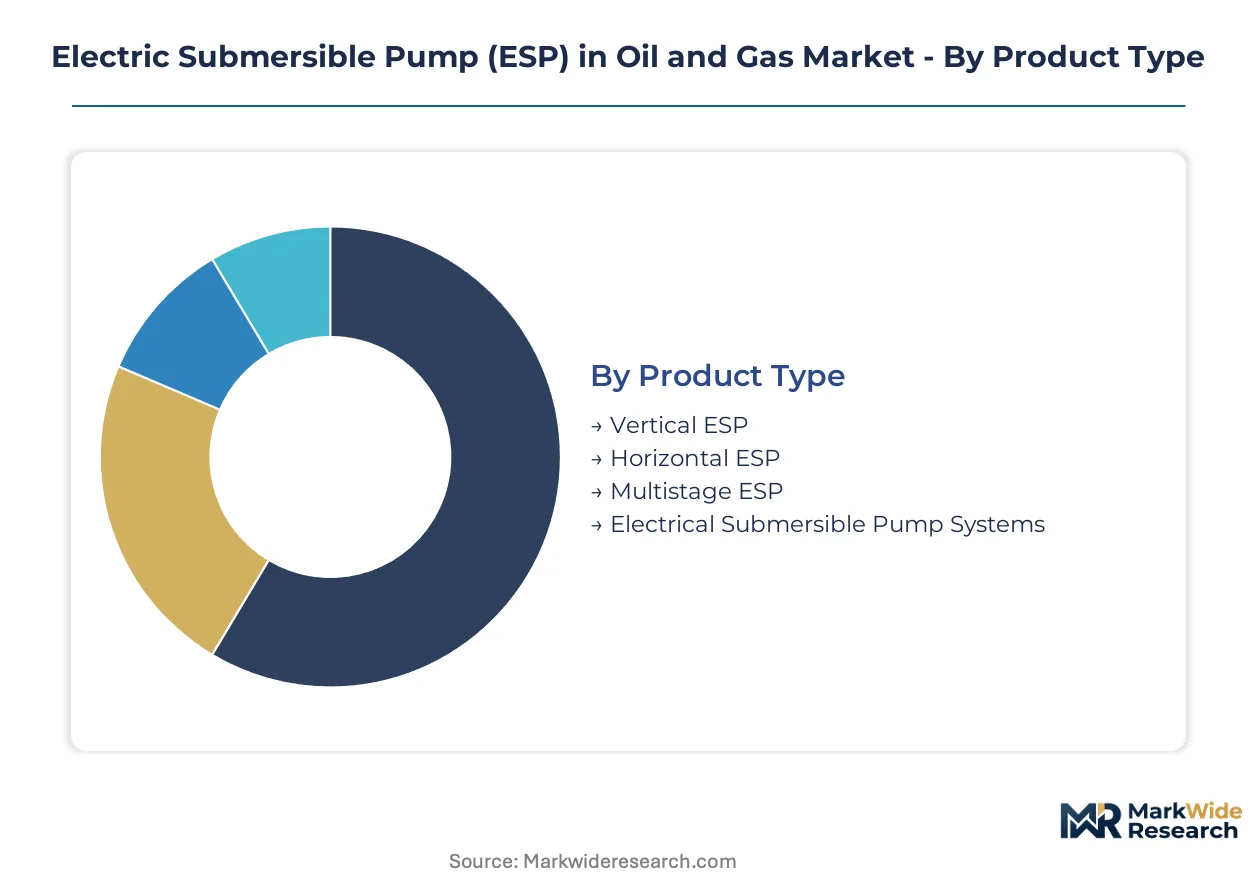
ESP procurement patterns diverge sharply between high-volume offshore developments and marginal onshore stripper wells. Understanding these segment boundaries reveals where vendors can extract premium pricing versus where commoditization pressures dominate.
Product Type:
Supply concentration tilts toward multistage architectures as deepwater operators standardize on high-horsepower configurations that amortize qualification costs across multi-well developments.
- Multistage ESP:Centrifugal pump stages stacked in series to generate high discharge pressures against deep reservoir hydrostatic heads. Brazil's Santos Basin pre-salt fields and US Gulf deepwater tiebacks concentrate demand here, driven by bottom-hole pressures exceeding 10,000 psi that rule out simpler lift methods.
- Vertical ESP:Conventional shaft-aligned pump-motor assemblies deployed in vertical or low-deviation wellbores. Onshore US Permian operators favor these for secondary recovery in mature waterflood patterns where workover economics favor standardization over optimization.
- Horizontal ESP:Slimhole configurations engineered for extended-reach laterals with high dogleg severity tolerances.
- Electrical Submersible Pump Systems:Integrated packages bundling pump, motor, seal, and cable with surface variable speed drives.
Today's leader: Multistage ESP. Tomorrow's challenger: Horizontal ESP.
End User:
Cost tier stratification separates capital-intensive offshore platform installations from onshore facilities where operating expenditure discipline governs equipment selection.
- Offshore Platforms:Fixed and floating production facilities in water depths exceeding 1,000 feet where ESP redundancy requirements multiply hardware costs. Norway's Johan Sverdrup and Brazil's Buzios developments anchor procurement volume, with PSA Norway and BSEE regulations mandating dual-train configurations that lock in premium-tier vendors.
- Onshore Facilities:Well pads and centralized processing sites where modular retrofit kits extend run life without workover rigs. US shale producers in the Permian and Eagle Ford represent the steepest expansion trajectory as secondary recovery programs redeploy ESPs for stripper well artificial lift.
- Oil Fields:Conventional and unconventional crude production assets spanning primary through tertiary recovery phases.
- Gas Fields:Associated and non-associated gas developments where liquid loading management determines ESP applicability.
Offshore Platforms command the margin pool. Onshore Facilities are climbing the fastest.
Application:
Volume concentration centers on well pumping as the baseline artificial lift function, with adjacent applications gaining traction where integrated field development strategies bundle lift with reservoir management.
- Well Pumping:Primary hydrocarbon lifting from reservoir to surface across natural flow decline curves. Gulf of Mexico operators and Brazil's Petrobras anchor equipment throughput, with run-life guarantees now standard in deepwater procurement contracts that transfer failure risk to vendors.
- Enhanced Oil Recovery:ESP deployment in polymer flood and chemical EOR patterns where high-viscosity fluid handling demands specialized metallurgy. The Permian Delaware and Midland sub-basins concentrate North American demand as operators push recovery factors past primary depletion limits.
- Water Injection:Disposal and pressure maintenance pumping where corrosion-resistant materials address sour service conditions.
- Production Boosting:ESP installation in gas-lifted or naturally flowing wells to accelerate decline curve management.
Well Pumping dominates the installed base. Enhanced Oil Recovery offers the steepest expansion trajectory.
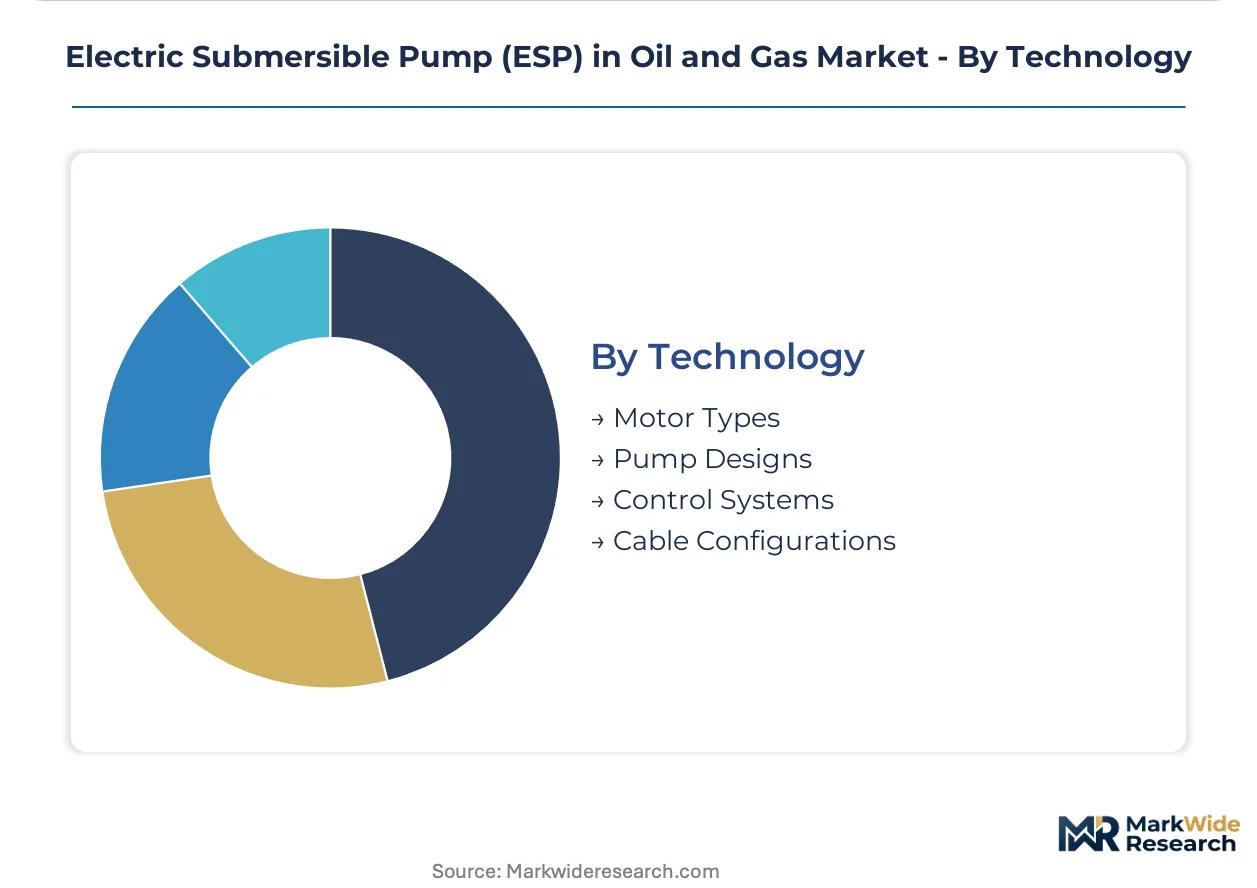
Technology:
Margin extraction concentrates in control systems and motor architectures where real-time optimization capabilities differentiate vendor offerings from commodity hardware.
- Motor Types:Induction, permanent magnet, and switched reluctance architectures spanning 100 to 1,500 horsepower ratings. Permanent magnet systems from US shale operators in the Permian and Eagle Ford absorb capital allocation as surface power demand reductions justify retrofit premiums against legacy induction fleets.
- Control Systems:Variable speed drives and downhole sensor integration enabling real-time frequency modulation and predictive diagnostics. Norway's North Sea operators and US Gulf independents concentrate subscription-based procurement here, converting hardware sales into recurring software revenue through guaranteed run-life contracts.
- Pump Designs:Radial and mixed-flow stage geometries optimized for gas handling and solids tolerance.
- Cable Configurations:Subsea power and signal transmission systems with wet-mate connector architectures.
Control Systems capture the margin premium. Motor Types are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting ESP procurement toward jurisdictions where subsea qualification costs and environmental compliance burdens diverge most sharply. Operators in Brazil and Norway absorb premium-tier pricing for BSEE-equivalent redundancy standards, while US shale producers exploit modular retrofit pathways that bypass full workover economics. This compliance-cost gradient concentrates multistage system deployment in deepwater basins while accelerating horizontal ESP adoption in marginal onshore strips.
United States
Permian Basin stripper well operators are redeploying ESPs for secondary recovery as primary decline curves exhaust natural flow capacity. EPA methane intensity benchmarks under the Inflation Reduction Act favor ESPs over gas lift in carbon-conscious procurement scorecards, tightening equipment selection criteria for federal leaseholders. Houston anchors vendor engineering centers where Baker Hughes and Schlumberger coordinate Gulf of Mexico deepwater service contracts.
Brazil
Petrobras pre-salt developments in the Santos Basin pull high-temperature ESP systems rated above 200°C into ultra-deepwater service envelopes where intervention costs exceed rig day rates. ANVISA equipment traceability requirements intersect with BSEE-aligned PSA Norway standards for subsea redundancy, elevating qualification barriers for foreign suppliers. Rio de Janeiro concentrates fabrication and wet-mate connector certification facilities serving Buzios and Mero field tiebacks.
Norway
Johan Sverdrup and upcoming North Sea brownfield redevelopments mandate dual-train ESP configurations under PSA Norway regulations that lock in premium-tier vendors for multi-decade contract tenures. EU F-Gas Regulation phase-down deadlines force dry motor architecture transitions ahead of 2030 statutory limits, compressing synthetic dielectric fluid qualification timelines. Stavanger hosts subsea electrical technician training pipelines that lag fleet expansion timelines across the Norwegian Continental Shelf.
China
Domestic shale operators in Sichuan-Chongqing basin pilot slimhole ESP deployments for extended-reach laterals where dogleg severity tolerances strain conventional vertical configurations. MIIT energy efficiency standards and GB equipment certification frameworks tighten motor efficiency thresholds, accelerating permanent magnet system adoption against legacy induction fleets. Shanghai and Tianjin concentrate manufacturing capacity for export-oriented multistage pump-motor assemblies serving Middle East and Central Asian markets.
Saudi Arabia
Gas lift economics dominate marginal well artificial lift decisions in Ghawar and Khurais fields where associated gas availability undercuts ESP penetration in stripper well segments. Saudi Aramco supplier qualification protocols for high-GOR applications emphasize real-time variable speed drive integration with downhole sensor telemetry. Dhahran anchors engineering centers coordinating ESP deployment in carbonate reservoir developments where scale and corrosion-resistant metallurgy determines run-life economics.
Electric Submersible Pump (ESP) in Oil and Gas Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service conglomerates controlling offshore platform procurement through bundled installation-to-abandonment contracts while regional fabricators compete on modular retrofit pricing for onshore stripper wells. The vendor base organizes into three strategic archetypes: full-service artificial lift integrators, component-focused pump-motor specialists, and digital platform vendors monetizing condition-based monitoring subscriptions. Consolidation pressure concentrates in control systems technology where real-time optimization capabilities determine margin extraction, while capacity expansion dominates permanent magnet motor manufacturing to address rare earth supply vulnerability.
Among US-based oilfield service conglomerates, Baker Hughes, Schlumberger, and Halliburton occupy positions as full-service integrators anchoring deepwater procurement through guaranteed run-life contracts. Weatherford exemplifies the modular retrofit specialist archetype with deployment systems that extend mature well economics without workover rig mobilization. Borets International and Novomet represent geographically concentrated fabrication specialists serving regional basin operators with customized high-temperature configurations.
| Leading Market Players |
|---|
| Borets International |
| Weatherford |
| Schlumberger |
| Atlas Copco |
| Flowserve Corporation |
| Baker Hughes |
| Novomet |
| EBARA Corporation |
| Halliburton |
| Others |
Pricing and Supply Chain Analysis
Captive motor manufacturing in China and the United States anchors supply positions for permanent magnet systems while simultaneously determining pricing power across premium and standard tiers. API 11S qualification costs create natural segmentation between certified vendors commanding service-contract premiums and modular retrofit competitors competing on unit economics.
Pricing Analysis
Distributor margins for multistage ESP systems compress in Brazil and Norway where direct-to-operator contracting dominates deepwater procurement. Three-tier pricing structure across premium, standard, and economy levels separates API-certified subsea configurations from onshore stripper well retrofits and non-certified replacement components. Price differentiation rests on BSEE and PSA Norway qualification status alongside guaranteed run-life contracting terms. Pricing pressure stems from rare earth magnet cost volatility feeding through permanent motor architectures. Onshore shale operators in the Permian exhibit highest price sensitivity while Gulf of Mexico platform contractors absorb premium tiering without volume negotiation.
Supply Chain Analysis
API 11S and ISO 15551 certification gating concentrates qualified manufacturing in China, the United States, and Norway for high-temperature subsea assemblies. Rare earth magnet processing draws from Chinese separation facilities while synthetic dielectric fluids source from German and Belgian chemical producers. Supply chain risk centers on single-source vulnerability for neodymium-dysprosium alloys in permanent magnet motors. Distribution runs through Houston and Rio de Janeiro service hubs coordinating installation-to-abandonment contracts for offshore platform operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet motor cost curves and subscription-based performance contracting are expanding service-margin pools beyond hardware sales. Digital twin diagnostics and edge-computing variable speed drives represent the primary premium-tier shift.
For Market Incumbents: To counter rare earth supply concentration in Chinese processing facilities, secure backward integration into magnet alloy sourcing or establish dual-source qualification with Japanese and Australian rare earth projects. Anchor position through captive control system development integrating real-time downhole telemetry with surface optimization algorithms. Defend against modular retrofit specialists by embedding sensor density that locks operators into proprietary diagnostic platforms. For New Entrants and Emerging Players: Regional fabrication partnerships with Brazilian ANVISA-authorized facilities offer the most penetrable entry path into pre-salt carbonate developments where foreign qualification barriers exclude unproven suppliers. Target slimhole horizontal ESP configurations for US shale extended-reach laterals where dogleg severity tolerances strain incumbent vertical architectures. Pursue white-label motor manufacturing for established service companies seeking to bypass in-house production investments. For Investors and Strategic Acquirers: Roll-up economics work for control systems specialists because real-time optimization capabilities determine margin extraction while hardware commoditization pressures concentrate in pump-motor assembly manufacturing. Long-term viability favors vendors with recurring software revenue streams anchored to guaranteed run-life contracts. Monitor EPA methane intensity benchmark enforcement as the signal indicating accelerated ESP displacement of gas lift in carbon-conscious operator procurement scorecards.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Capacity Buildout | Reduces surface power demand for Permian and Eagle Ford shale operators by one-third. |
| API 11S Certification Investment | Unlocks BSEE-mandated subsea redundancy contracts in US Gulf deepwater tiebacks. |
| Digital Twin Platform Integration | Converts Baker Hughes and Schlumberger hardware sales into recurring software subscriptions. |
| Synthetic Dielectric Fluid Qualification | Maintains CE marking access ahead of EU F-Gas Regulation phase-down deadlines. |
| Modular Retrofit Kit Distribution Partnership | Extends Weatherford run-life economics in mature North Sea assets without workover rigs. |
Research Methodology
Coverage spans Brazil, the United States, Norway, and China, with primary inputs from each anchoring regional demand calibration. The research combines structured interviews with artificial lift service directors, subsea electrical technicians, platform maintenance managers, and EPC procurement leads with secondary validation from BSEE enforcement records, PSA Norway audit reports, ANVISA equipment traceability filings, and API certification databases. Bottom-up well-count modeling and top-down operator capital expenditure triangulation produce volume and value estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product architecture, end-user facility type, application function, and motor-control technology tier. CAGRs derive from production decline curve analysis, rig day-rate sensitivity, and regulatory compliance cost trajectories. Forecast inputs incorporate rare earth magnet price volatility and subsea intervention frequency assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to permanent magnet supply disruption and EU F-Gas Regulation enforcement timing. Model outputs reflect assumptions around Petrobras pre-salt development pacing and US shale secondary recovery program adoption. A model refresh is warranted upon material change in EPA methane intensity benchmark implementation or BSEE well control regulation amendment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Multistage Pump Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Membrane Pump Market
Pumps and Control Devices
Spiral Classifier Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Europe Asia Submerged Pump Market