
 Subsea Pump System Market | 2026-2036
Subsea Pump System Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Pump System Market Analytics
Performance-based maintenance contracts is expanding as a discrete revenue layer, shifting supplier economics from hardware shipment to uptime guarantees. Baker Hughes Company leverages its turbomachinery service infrastructure to anchor long-term service agreements across the Gulf of Mexico. Schlumberger Limited competes through integrated subsea production systems that bundle pump deployment with digital monitoring architectures. Aker Solutions ASA specializes in subsea processing packages where pump modules integrate with separation and compression units.
A subsea pump system comprises an electric motor-driven centrifugal or positive-displacement pump housed in a pressure-balanced vessel rated for depths exceeding 3,000 meters, designed to boost hydrocarbon flow from subsea wells to surface facilities or inject fluids for reservoir pressure maintenance. Centrifugal pumps dominate high-volume oil extraction applications due to scalable hydraulic performance across varying gas-liquid ratios, while electric pumps displace hydraulic alternatives as subsea power distribution matures. Fixed installation systems anchor margin pools in brownfield tiebacks where platform infrastructure exists, whereas floating systems represent the fastest-growing configuration as deepwater developments shift to FPSO-hosted production.
API RP 11S4 and ISO 13628-7 govern subsea pump design verification and materials qualification, while the Norwegian Petroleum Safety Authority enforces functional safety requirements that shape control system architectures for North Sea deployments. The US Bureau of Safety and Environmental Enforcement mandates blowout preventer integration protocols that influence subsea pump system emergency isolation logic. Stakeholders must monitor subsea electrification roadmaps and evolving carbon intensity disclosure rules as these forces determine which pump technologies qualify for future field development tenders.
Market Dynamics
Subsea electrification roadmaps are compressing deployment timelines for electric submersible pump configurations while simultaneously raising qualification barriers for hydraulic alternatives, forcing suppliers to reconfigure product portfolios around permanent magnet motor architectures and subsea power distribution networks.
Growth Catalysts
- Pre-salt basin development:Brazil's ultra-deep reservoirs require high-reliability boosting systems that electric submersible pumps uniquely deliver, anchoring demand concentration in South Atlantic offshore fields.
- API RP 11S4 certification pathways:Standardized design verification protocols reduce qualification uncertainty for new entrants, accelerating technology transfer from surface turbomachinery expertise into subsea environments.
- FPSO-hosted production migration:Floating systems now dominate greenfield deepwater developments, creating modular pump installation demand that fixed platform tiebacks cannot satisfy.
Market Restraints
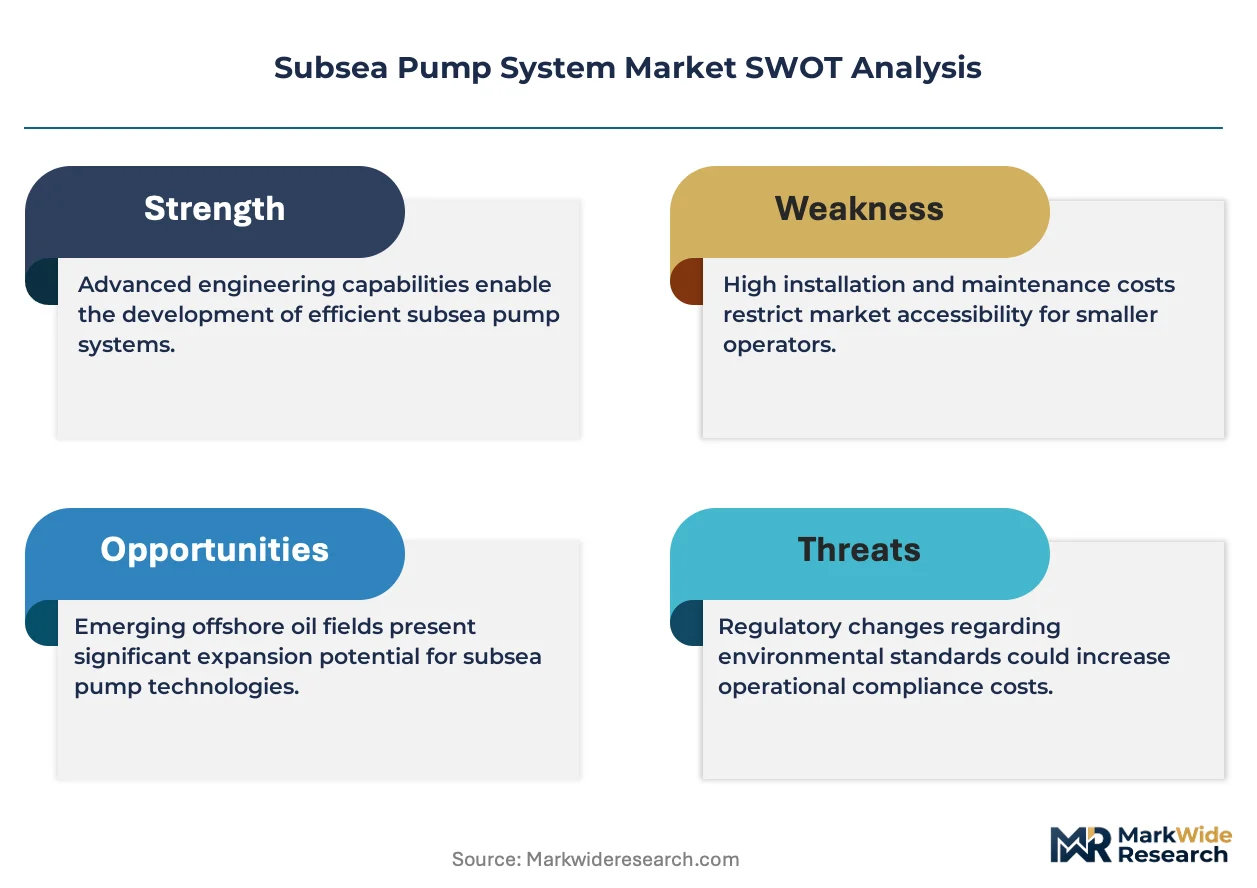
- High-grade alloy supply concentration:Super-duplex stainless steel and Inconel sourcing concentrates among specialty metallurgical suppliers in Norway and Germany, exposing lead times to geopolitical friction.
- Subsea power cable technical limitations:Current wet-mate connector technology caps power transmission distances, constraining field architecture flexibility for remote well clusters.
- ISO 13628-7 compliance costs:Materials qualification and factory acceptance testing requirements extend development cycles, elevating break-even thresholds for marginal field developments.
Strategic Opportunities
- West African frontier basins:Underexplored deepwater blocks off Angola and Ghana present greenfield pump system demand as international operators advance final investment decisions.
- Subsea processing integration:Pump modules converging with separation and compression units enable all-electric subsea factories, reducing topside footprint requirements.
- EU Green Deal carbon intensity disclosure:Emerging tender qualification criteria favor electrified subsea infrastructure over hydraulic alternatives, creating regulatory tailwind for technology transition.
Industry Challenges
- Subsea systems engineering talent scarcity:Cross-disciplinary expertise spanning high-pressure vessel design, marine electrical systems, and reservoir engineering concentrates among aging specialist workforces in Stavanger and Houston.
- Legacy hydraulic infrastructure integration:Brownfield tiebacks require hybrid architectures that bridge existing hydraulic control systems with new electric pump deployments, complicating commissioning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Pump System Market |
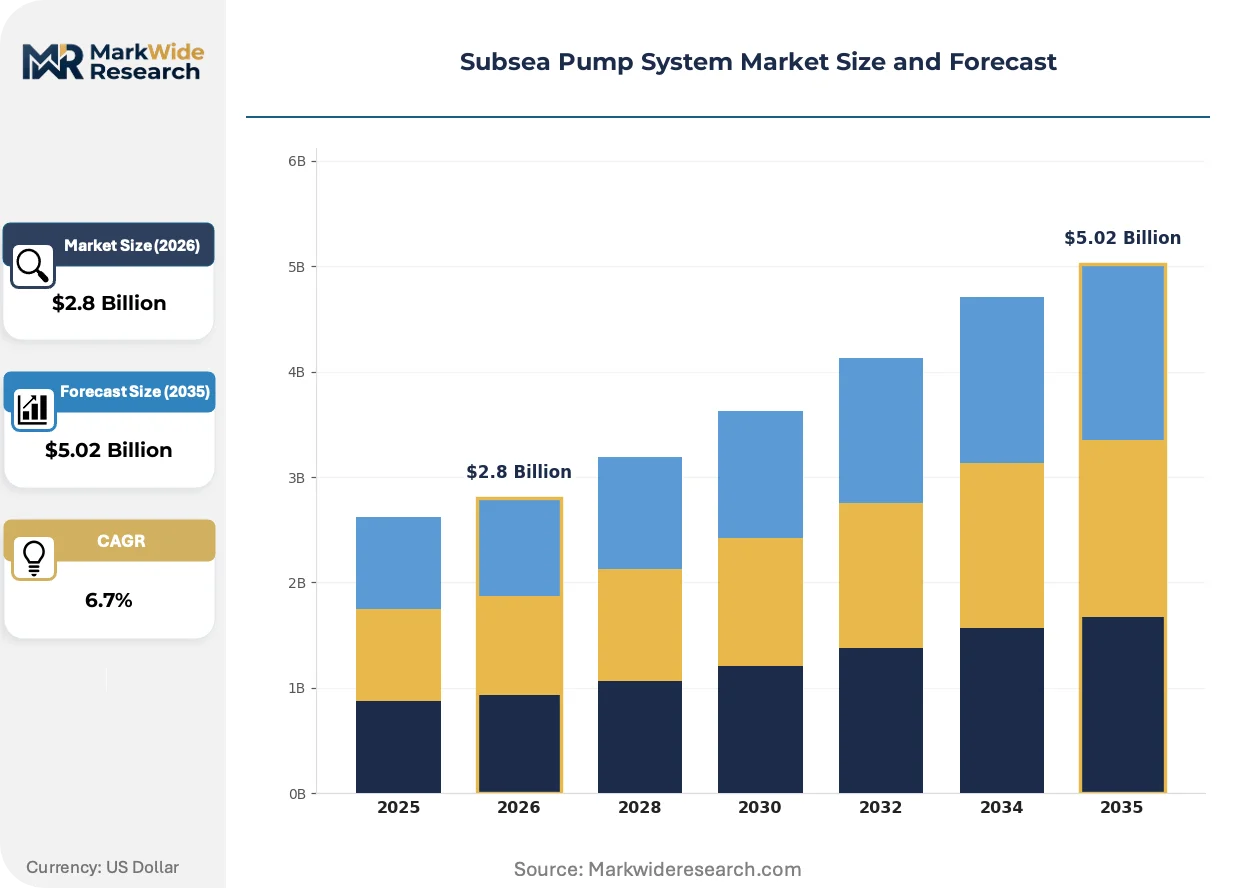
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Centrifugal Pumps, Diaphragm Pumps, Electric Pumps End User: Oil & Gas, Marine, Offshore Wind, Mining Application: Oil Extraction, Water Injection, Well Testing, Chemical Injection Installation Type: Fixed Systems, Floating Systems, Remotely Operated Systems, Portable Systems |
| Companies Covered | Aker Solutions ASA, Schlumberger Limited, Baker Hughes Company, Oceaneering International Inc., TechnipFMC PLC, Halliburton Company, General Electric Co., Flowserve Corporation, Sulzer Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Pump System Market Evolving Landscape
Digital twin architectures and predictive maintenance platforms are rewiring supplier-customer relationships around uptime guarantees rather than equipment ownership, compressing traditional service margins while opening recurring revenue streams.
Permanent magnet motor technology is expanding into high-temperature, high-pressure subsea environments previously dominated by induction motor designs. Petrobras and major independents operating Brazil's pre-salt fields now specify permanent magnet configurations for new boosting installations. This shift is expanding into deeper reservoir applications while compressing the addressable market for conventional hydraulic pump alternatives.
Norwegian Petroleum Safety Authority functional safety requirements are mandating redundant control system architectures for North Sea pump deployments. These regulations force suppliers to duplicate critical instrumentation and emergency shutdown logic, elevating system complexity and qualification costs. Subsea control module manufacturers serving the Norwegian continental shelf have responded by pre-integrating safety instrumented systems into standardized pump control packages.
Performance-based service contracts are displacing traditional break-fix maintenance arrangements across Gulf of Mexico and West African installations. Operators now contract for guaranteed availability percentages rather than discrete spare parts procurement, transferring operational risk to pump system suppliers. This behavioral pivot is most visible among supermajor operators with mature subsea portfolios seeking to reduce internal technical staffing requirements.
Subsea Pump System Market Segmentation
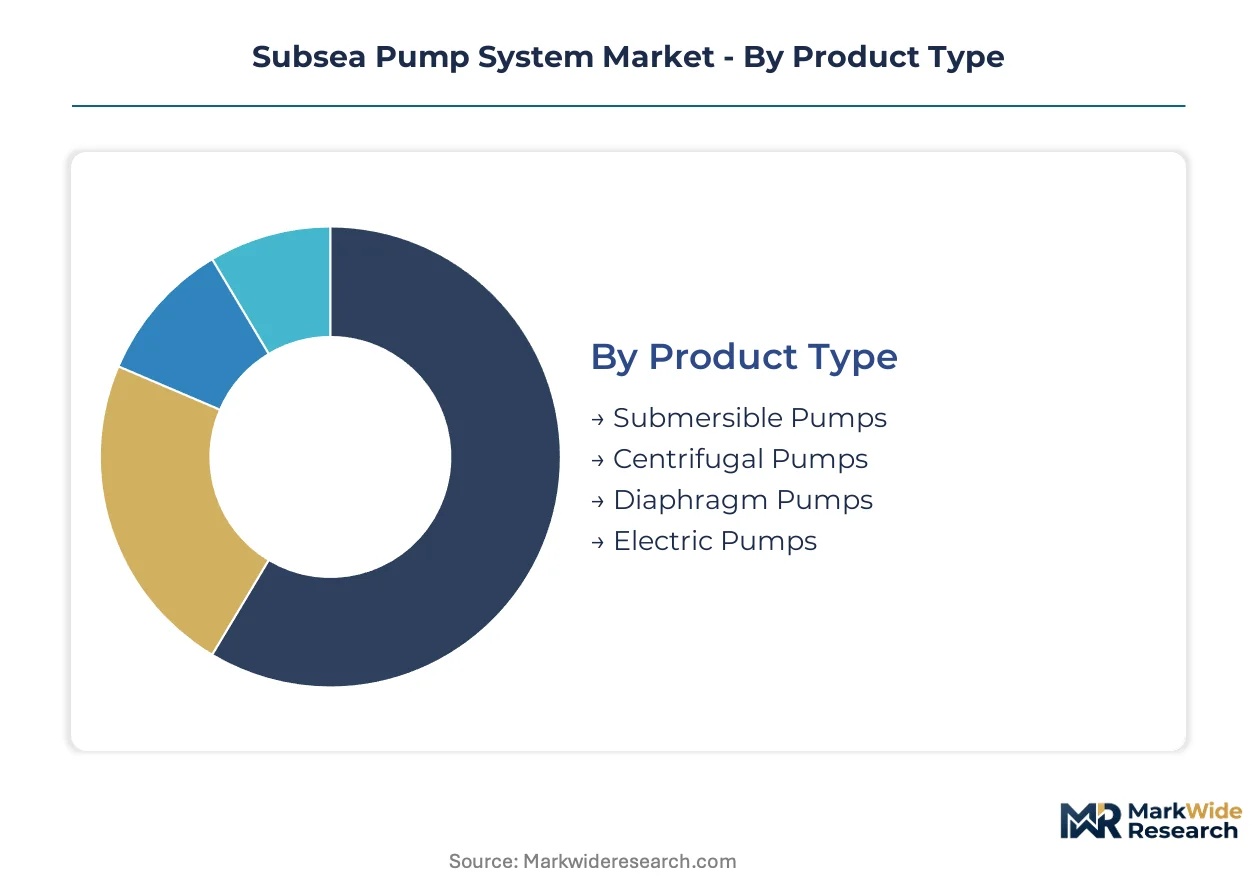
Segmentation reveals how capital deployment varies sharply across pump technologies and installation contexts. Equipment specifications diverge based on reservoir depth, fluid chemistry, and tieback architecture, creating distinct margin pools for suppliers.
Product Type:
Capital intensity escalates with motor complexity and pressure rating requirements, separating commodity hardware from engineered subsea systems.
- Submersible Pumps:Electric motor-driven units housed in pressure-balanced vessels rated for depths exceeding 3,000 meters. Petrobras-led pre-salt developments in Brazil anchor demand for high-reliability configurations that withstand ultra-deep reservoir pressures.
- Centrifugal Pumps:Multi-stage impeller designs scalable across varying gas-liquid ratios dominate high-volume oil extraction. API RP 11S4 certification pathways reduce qualification uncertainty for these configurations, accelerating adoption in Gulf of Mexico brownfield tiebacks.
- Diaphragm Pumps:Positive-displacement mechanisms handle high-viscosity fluids and abrasive produced water. Chemical injection applications in North Sea mature fields specify these for precise flow control.
- Electric Pumps:Permanent magnet motor architectures displace hydraulic alternatives as subsea power distribution networks mature. Norway's electrification mandates favor these for new greenfield developments.
Submersible pumps absorb the bulk of installed capacity; electric pumps are expanding most quickly.
End User:
Customer sophistication and procurement scale determine qualification barriers and contract structures across verticals.
- Oil & Gas:Supermajor operators and national oil companies dominate procurement volumes. FPSO-hosted production migration creates modular installation demand that fixed platform tiebacks cannot satisfy.
- Marine:Subsea mining and dredging operations require corrosion-resistant pumping systems for seawater handling. Port infrastructure projects in Singapore and Rotterdam specify these for ballast and cargo transfer.
- Offshore Wind:Jacket foundation grouting and cable burial operations drive demand for portable subsea pumping units. North Sea wind farm construction schedules concentrate procurement timing.
- Mining:Deep-sea mineral extraction pilots off Papua New Guinea and the Cook Islands test prototype pumping systems for polymetallic nodule recovery.
Oil and gas commands the dominant share of capital deployment; offshore wind is climbing the fastest as renewable infrastructure scales.
Application:
Functional requirements shape hydraulic design, materials selection, and control system architecture.
- Oil Extraction:Artificial lift and boosting systems maintain flow rates from declining reservoirs. West African frontier basins off Angola present greenfield demand as operators advance final investment decisions.
- Water Injection:Pressure maintenance systems inject treated seawater or produced water into reservoir formations. Saudi Aramco's Marjan and Berri field expansions specify high-rate injection pumps.
- Well Testing:Temporary boosting configurations evaluate reservoir productivity during exploration and appraisal drilling. Modular skid-mounted systems reduce mobilization costs for marginal well tests.
- Chemical Injection:Precise dosing pumps deliver corrosion inhibitors, scale suppressants, and hydrate preventers subsea. Brazilian pre-salt fields require specialized metallurgy for acidic fluid compatibility.
Oil extraction retains the largest installed base; water injection is gaining share fastest as secondary recovery programs expand.
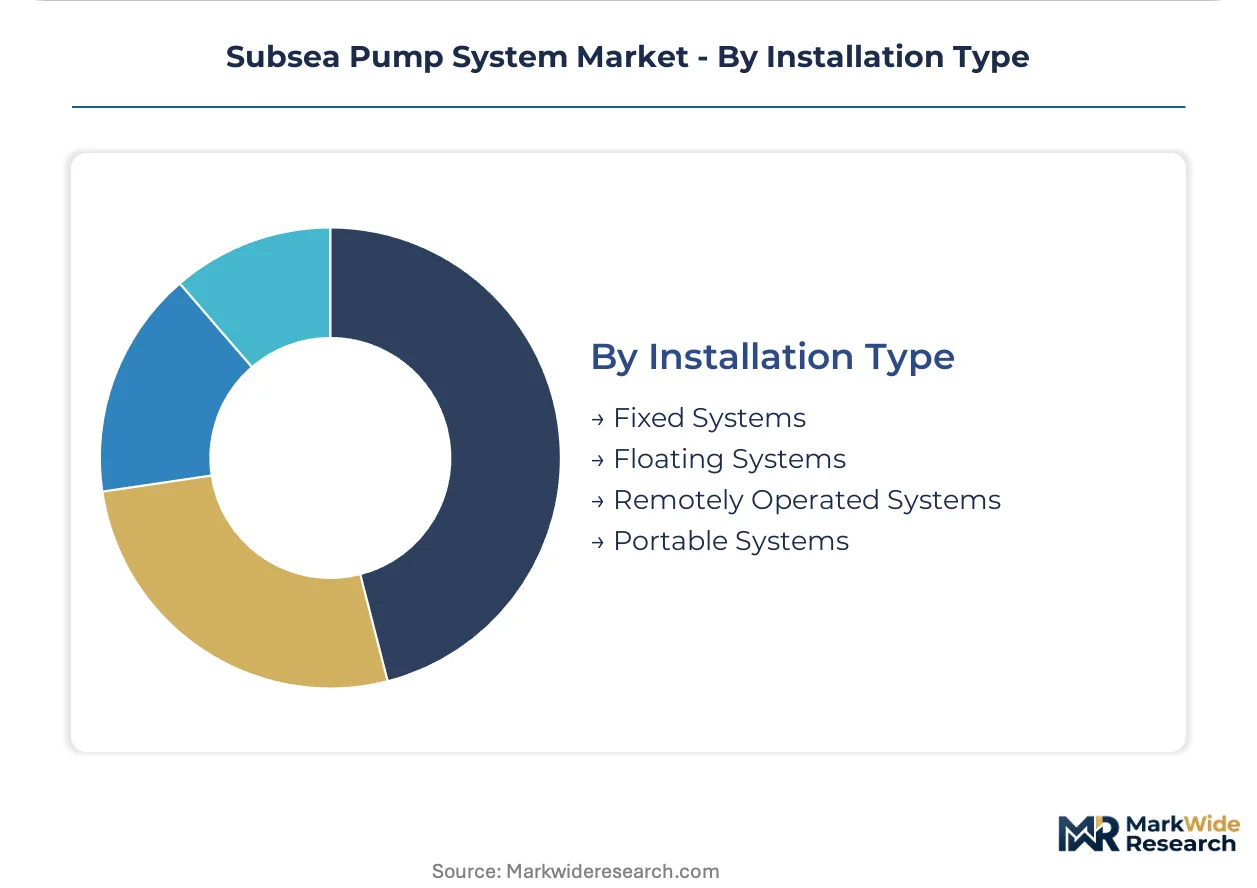
Installation Type:
Field architecture determines system modularity, maintenance access, and integration complexity.
- Fixed Systems:Platform-tied installations anchor margin pools in brownfield developments where surface infrastructure exists. UK North Sea late-life assets favor these for minimal capital exposure.
- Floating Systems:FPSO and semi-submersible-hosted pumps enable deepwater greenfield developments beyond fixed platform reach. Guyana's Stabroek Block developments exemplify this configuration's scalability.
- Remotely Operated Systems:Tethered deployment and retrieval capabilities reduce intervention vessel requirements. Remote well clusters off Western Australia employ these for distance-constrained fields.
- Portable Systems:Skid-mounted or modular packages serve temporary applications and emergency replacement scenarios. Gulf of Mexico hurricane recovery operations deploy these for rapid production restoration.
Fixed systems hold the majority of legacy installations; floating systems are scaling fastest as deepwater exploration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors subsea pump engineering concentration, hosting specialist workforces that span high-pressure vessel design and marine electrical systems. Field development clusters in Norway, Brazil, and West Africa concentrate procurement volumes for ultra-deep boosting configurations.
Brazil
Pre-salt basin developments off the Santos and Campos coasts drive electric submersible pump demand for reservoirs exceeding 2,000 meters depth. ANP regulatory frameworks mandate blowout preventer integration protocols that shape subsea pump emergency isolation logic. Petrobras-led projects in the Búzios and Mero fields specify permanent magnet motor architectures for new boosting installations.
Norway
North Sea late-life asset extensions and Johan Sverdrup phase expansions sustain brownfield pump system procurement. The Norwegian Petroleum Safety Authority enforces functional safety requirements that mandate redundant control system architectures for subsea deployments. Stavanger-based engineering clusters concentrate cross-disciplinary expertise in subsea systems integration and high-pressure vessel qualification.
United States
Gulf of Mexico deepwater tiebacks and post-hurricane restoration operations generate modular pump installation demand. The US Bureau of Safety and Environmental Enforcement mandates blowout preventer integration protocols that influence subsea pump emergency isolation logic. Houston's turbomachinery service infrastructure anchors performance-based maintenance contracts for FPSO-hosted production systems.
Angola
West African frontier basin developments off the Kwanza and Benguela basins present greenfield pump system demand as operators advance final investment decisions. The country's national petroleum regulator oversees subsea equipment certification requirements that align with classification society standards. Luanda serves as the logistics hub for pump module mobilization to ultra-deep blocks operated by international consortia.
United Kingdom
UK North Sea decommissioning deferrals and electrification retrofits sustain demand for fixed installation pump systems. The North Sea Transition Authority oversees asset integrity requirements that extend qualification timelines for replacement boosting equipment. Aberdeen's subsea technology corridor hosts specialist firms focused on hybrid hydraulic-electric integration for brownfield tiebacks.
Subsea Pump System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the subsea pump system value chain, with integrated oilfield service conglomerates controlling turbomachinery qualification pathways while specialist subsea fabricators capture modular installation niches. Market structure tilts toward consolidation among full-system integrators capable of bundling pump deployment with digital monitoring architectures. Three archetypes dominate: integrated production system providers, standalone pump module specialists, and turbomachinery service incumbents. Competitive dynamics center on strategic partnerships for subsea power distribution networks and portfolio diversification into subsea processing packages.
Among integrated oilfield service providers, Schlumberger Limited, Baker Hughes Company, and TechnipFMC PLC occupy positions that exemplify the full-system archetype, bundling pump deployment with broader subsea production architectures. These entities represent the capital-intensive tier where turbomachinery service infrastructure anchors long-term performance contracts. Specialist subsea fabricators including Aker Solutions ASA sit within the module-integration tier, focusing on processing packages where pump units converge with separation and compression equipment.
| Leading Market Players |
|---|
| Aker Solutions ASA |
| Schlumberger Limited |
| Baker Hughes Company |
| Oceaneering International Inc. |
| TechnipFMC PLC |
| Halliburton Company |
| General Electric Co. |
| Flowserve Corporation |
| Sulzer Ltd |
| Others |
Value Network & Pricing Analysis
Petrobras-led procurement consolidation around permanent magnet motor specifications is forcing suppliers to absorb alloy certification costs, compressing margins on standard configurations while elevating pricing power for qualified vendors.
Pricing Analysis
Margin tightening in standard electric pump configurations reflects ISO 13628-7 compliance cost absorption by tier-two suppliers. Project-based long-term offtake contracts dominate, with price differentiation anchored in API RP 11S4 certification tier and permanent magnet motor integration depth. National oil companies exhibit lowest price sensitivity; independent operators in West African frontier basins face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian and German specialty metallurgical suppliers for super-duplex stainless steel and Inconel feedstock. Manufacturing draws from Norway, Germany, and the United States for pressure vessel fabrication. Tariff exposure on high-grade alloys constrains field architecture flexibility. Distribution runs through Stavanger and Houston engineering clusters to Brazil, Angola, and Gulf of Mexico deployment sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialist workforce scarcity in subsea systems engineering props pricing for qualified vendors, creating durable margin pools for incumbents with captive expertise.
For Market Incumbents: To counter permanent magnet motor commoditization, anchor turbomachinery service infrastructure in Brazil and West Africa for performance-based contract capture. Deepen backward integration into high-pressure vessel qualification capabilities to defend certification-tier pricing. For New Entrants and Emerging Players: Launch via modular skid-mounted configurations targeting well testing and portable replacement demand in Gulf of Mexico hurricane recovery operations. West African frontier basins off Ghana present the most penetrable greenfield entry point. For Investors and Strategic Acquirers: The window for entry favors subsea control module specialists with pre-integrated safety instrumented systems. Watch Norwegian Petroleum Safety Authority electrification mandates as the signal for technology transition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Certification | API RP 11S4 qualification opens Petrobras pre-salt procurement access. |
| Subsea Processing Integration | Pump-separation-compression bundling reduces topside footprint for FPSO operators. |
| Performance-Based Service Contracts | Uptime guarantees transfer operational risk from supermajors to suppliers. |
| West African Engineering Presence | Luanda logistics hubs capture Angola greenfield final investment decision timing. |
| Digital Twin Architecture Deployment | Predictive maintenance platforms rewire supplier-customer relationships around availability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving subsea systems engineers, turbomachinery service directors, national oil company procurement leads, and classification society surveyors. Bottom-up equipment shipment tallies combined with top-down field development capex analysis across the analysis window.
Segment-level modeling addressed pump technology type, installation architecture, reservoir depth tier, and regional regulatory cluster throughout the forecast period. CAGRs derived from project sanctioning timelines and electrification roadmap adoption curves. Permanent magnet motor specification rates and FPSO orderbook conversion served as industry-specific demand inputs.
The model assumes a particular technology adoption path; alternative pathways for hydraulic-to-electric transition timing would alter the outlook. Forecasts reflect assumptions on subsea power cable technical maturation and alloy supply chain stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
APAC Positive Displacement Pumps Market
Pumps and Control Devices
Split Casing Pump Market
Pumps and Control Devices
Pump Over Tanks Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Dry Vacuum Pumps Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Global Hydraulic Metering Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Hydrogen Circulation Pump Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Heating Tape Market