
 Energy-Saving Canned Motor Pump Market | 2026-2036
Energy-Saving Canned Motor Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Energy-Saving Canned Motor Pump Market Insights
Project finance for energy-efficiency retrofits is narrowing the competitive field to vendors with leasing-capable balance sheets. HERMETIC-Pumpen GmbH leverages its German engineering heritage to dominate specialty chemical applications. Nikkiso Co., Ltd. anchors its position through backward integration into precision motor manufacturing. KSB SE & Co. KGaA competes across multiple end-user channels with a broad centrifugal portfolio.
Energy-saving canned motor pumps seal the motor and rotor within a containment shell, eliminating mechanical seals and enabling leak-free operation for volatile or toxic fluids at pressures up to 400 bar and temperatures exceeding 400°C. Centrifugal pumps occupy the largest share of installed base due to their versatility in chemical and power generation loops. Variable frequency drive technology represents the fastest-expanding segment as facilities pursue demand-responsive flow control without throttling losses. Water treatment applications sustain above-average growth from tightening effluent standards and expanding desalination capacity.
EMA efficiency designations, EU F-Gas Regulation phase-down schedules, and REACH chemical compliance requirements collectively elevate product certification barriers and reshape procurement specifications across European process industries. In the United States, DOE pump efficiency standards and EPA leak detection mandates for hazardous fluids drive parallel specification upgrades. Stakeholders must monitor how regional efficiency benchmarks diverge and whether harmonization efforts emerge through ISO pump performance standards.
Market Dynamics
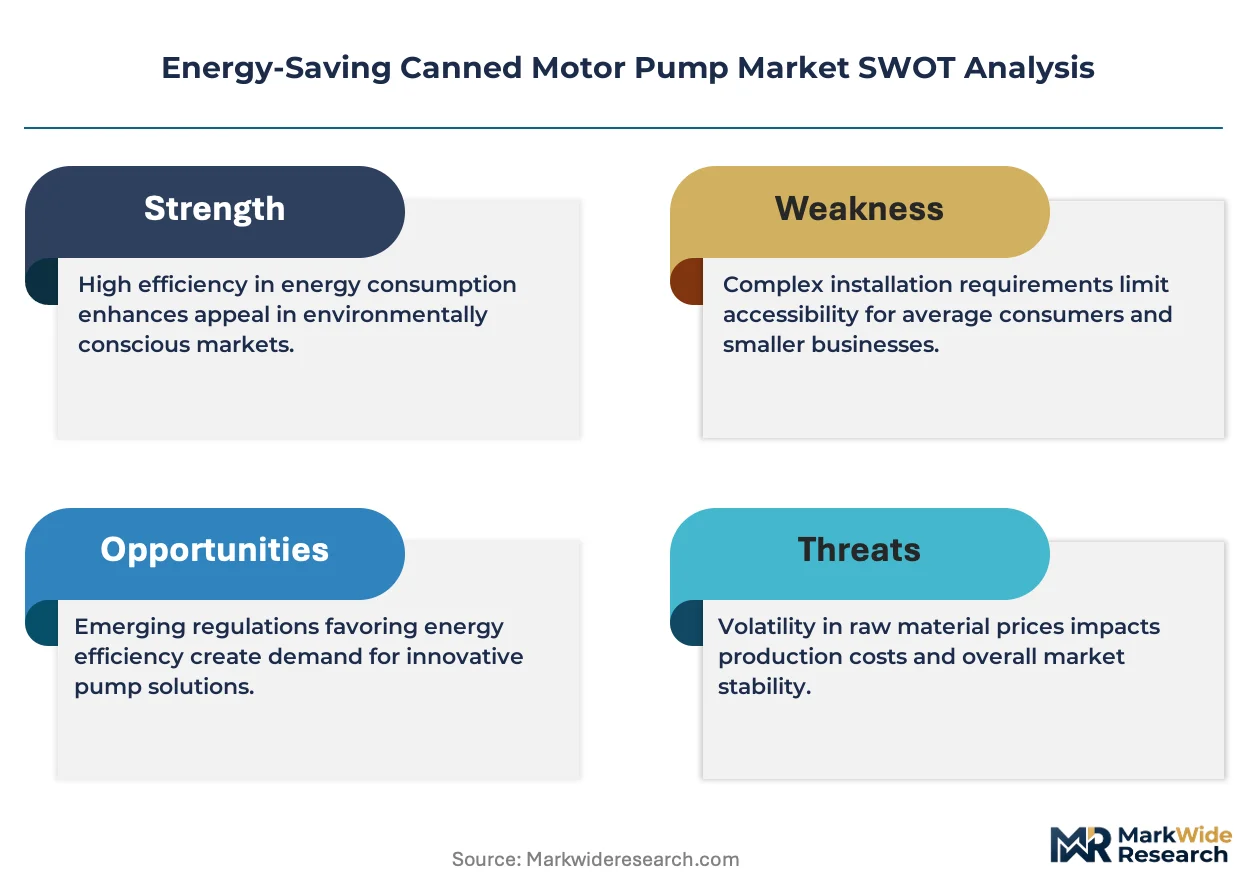
The EU F-Gas Regulation's phase-down schedule is forcing chemical processors to replace conventional sealed pumps ahead of mechanical failure, compressing replacement cycles and elevating hermetic designs from niche to default specification.
Growth Catalysts
- REACH chemical compliance:Processors handling volatile solvents must eliminate fugitive emissions. Canned motor designs satisfy ECHA containment mandates without secondary sealing systems.
- Desalination capacity expansion:Reverse osmosis plants in coastal zones specify leak-free brine circulation. Saltwater corrosion resistance drives specification toward nickel-alloy containment shells.
- Variable frequency drive pairing:Demand-responsive flow control eliminates throttling losses. VFD-integrated canned motor packages capture retrofit opportunities in existing chemical loops.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings compress motor manufacturing margins. Sintered magnet supply concentrates in Chinese processing facilities.
- Containment shell fabrication bottleneck:Hastelloy and titanium shell welding requires certified orbital welding technicians. Qualified supplier base remains geographically concentrated in Germany and Japan.
- Submersible magnetic drive competition:Sealless magnetic couplings achieve comparable leakage protection at lower capital cost for low-pressure aqueous applications.
Strategic Opportunities
- US DOE pump efficiency standards:Federal efficiency mandates create replacement pull in aging petrochemical corridors. DOE certification gaps favor premium hermetic designs.
- Hydrogen handling infrastructure:Liquid hydrogen transfer at cryogenic temperatures demands absolute leak prevention. Canned motor cryogenic variants address emerging fueling station networks.
- Leasing-enabled project finance:Energy-as-a-service models allow vendors to capture recurring revenue. Balance-sheet-capable manufacturers bypass capital-constrained competitor channels.
Industry Challenges
- Orbital welding technician scarcity:Containment shell fabrication requires ASME Section IX-certified welders. Training pipeline lags demand expansion in North American fabrication shops.
- Legacy DCS integration complexity:Variable frequency drive retrofits demand communication protocol translation. Proprietary fieldbus standards in installed chemical plants extend commissioning timelines.
- Multi-jurisdictional certification sequencing:ATEX, IECEx, and UL listings require staggered testing cycles. Parallel approval processes extend time-to-revenue for new product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy-Saving Canned Motor Pump Market |
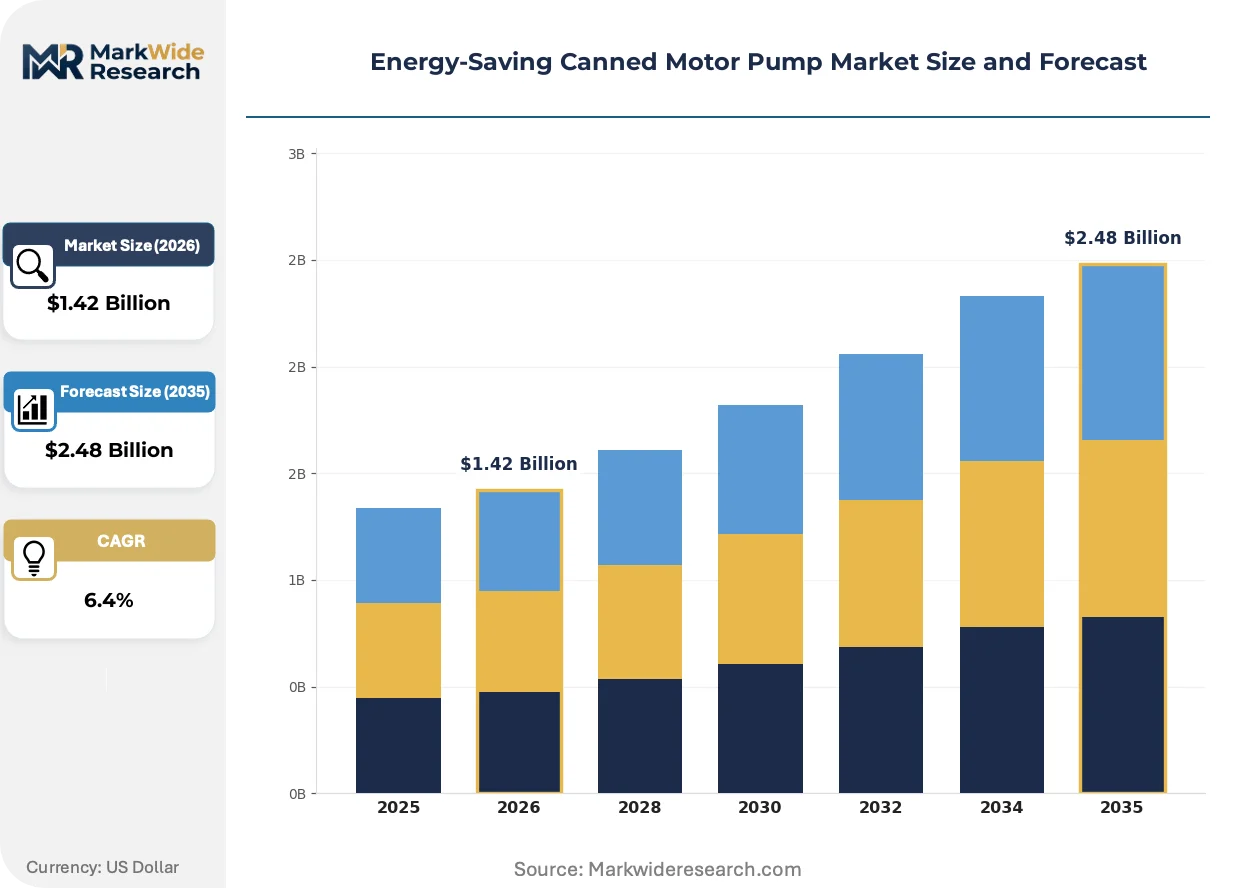
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Positive Displacement Pumps, Submersible Pumps, Axial Flow Pumps End User: Industrial Sector, Power Generation, Chemical Processing, Water Treatment Technology: Variable Frequency Drives, Direct Drive, Pump Automation, High-Efficiency Motors Installation Type: Indoor Installation, Outdoor Installation, Custom Installations, Retrofit Installations |
| Companies Covered | HERMETIC-Pumpen GmbH, Nikkiso Co., Ltd., Teikoku Electric Mfg. Co., Ltd., Kirloskar Brothers Limited, KSB SE & Co. KGaA, Shinhoo, Hayward Tyler Ltd., Flowserve Corporation, OPTIMEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy-Saving Canned Motor Pump Market Trends and Innovations
Digitalization of pump monitoring and predictive maintenance is compressing service intervals and reshaping vendor-customer relationships from transactional equipment supply to continuous performance contracts.
Silicon carbide bearing technology is hybridizing traditional canned motor architectures with ceramic tribology. High-purity chemical processors in pharmaceutical synthesis adopt SiC thrust bearings for reduced particle generation. The technology is hybridizing maintenance schedules by extending mean time between overhaul beyond conventional metal bearing limits.
The EU F-Gas Regulation's hydrofluorocarbon phase-down tightens containment requirements for refrigerant circulation pumps. Processors must demonstrate zero leakage across equipment lifetime. Chemical manufacturing clusters in the Rhine-Ruhr region accelerate hermetic pump specification to preempt enforcement penalties.
Aftermarket service unbundling disrupts traditional OEM-captive maintenance relationships. Third-party specialist servicers equipped with portable stator analysis tools capture routine inspection work. Chemical processors in the US Gulf Coast increasingly separate capital procurement from service contract negotiation.
Energy-Saving Canned Motor Pump Market Segmentation
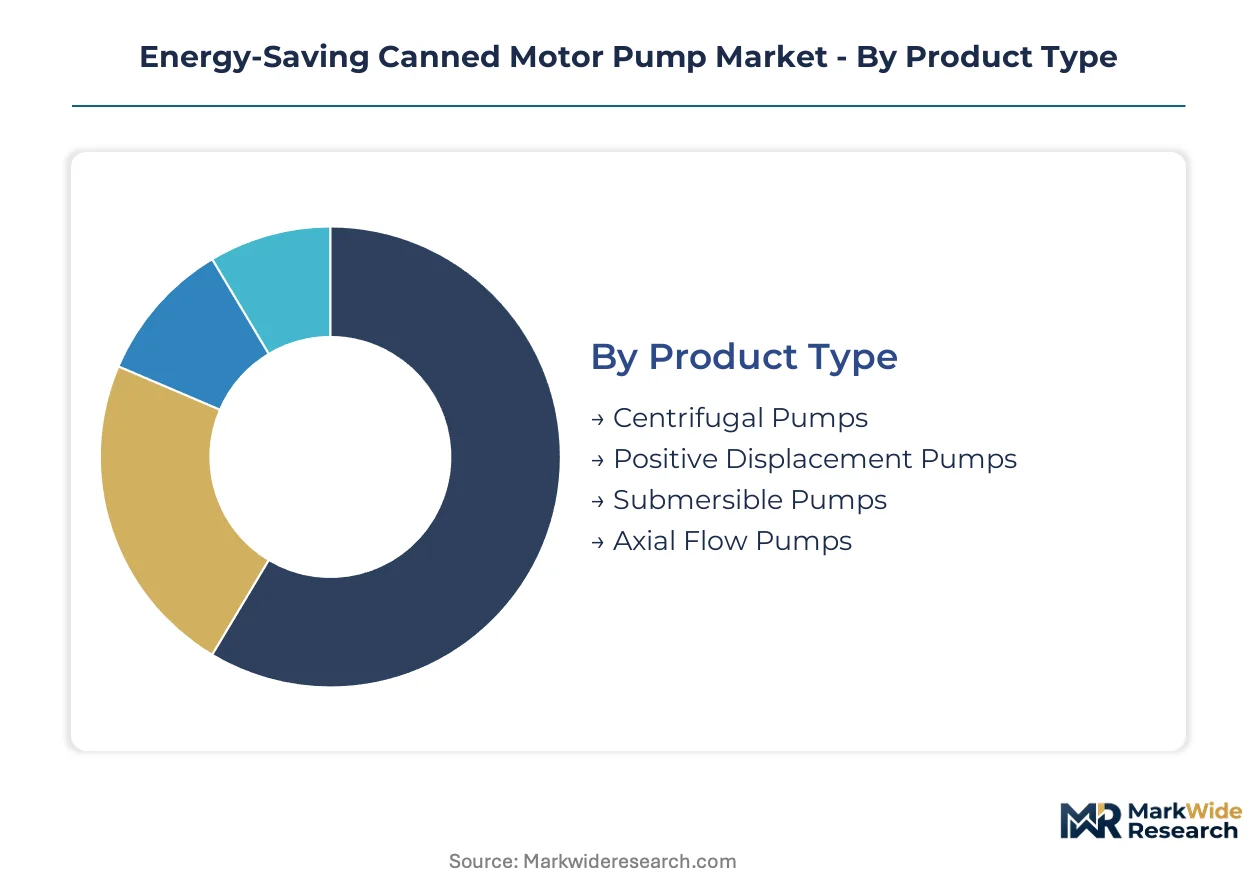
Segmentation in the energy-saving canned motor pump market reveals how procurement specifications diverge across pressure ratings, fluid chemistries, and duty cycles. Buyers in chemical processing prioritize hermetic integrity over capital cost, while power generators emphasize efficiency certification tiers. Understanding these segment boundaries enables vendors to align R&D spend with replacement cycle timing.
Product Type:
Replacement cycles vary dramatically by hydraulic design, with continuous-duty chemical pumps turning over every 8-12 years versus intermittent water treatment units lasting 15-20 years.
- Centrifugal Pumps:Radial flow impellers handle the broadest viscosity range across chemical and power applications. German chemical clusters along the Rhine-Ruhr specify these for sulfuric acid transfer under EU F-Gas Regulation containment mandates. The installed base is largest but retrofit timing is staggered.
- Positive Displacement Pumps:Rotating cavity designs deliver precise flow for polymer and resin handling. Japanese pharmaceutical manufacturers specify these for high-viscosity API synthesis where pulsation-free delivery matters. Capital cost premiums limit adoption to specialty applications.
- Submersible Pumps:Motor-stator integration enables deep-well brine extraction in Middle Eastern desalination plants. Corrosion-resistant nickel-alloy containment shells address saltwater immersion.
- Axial Flow Pumps:High-volume, low-head configurations serve cooling water loops in combined-cycle power stations. Efficiency gains concentrate in turbine condensate circulation.
Centrifugal pumps dominate installed base. Variable frequency drive pairing with positive displacement units is where expansion concentrates.
End User:
Margin structures diverge sharply by buyer sophistication, with chemical processors accepting 40-60% premiums for ATEX certification versus power utilities negotiating on total cost of ownership metrics.
- Chemical Processing:Hazardous fluid handling drives hermetic specification for volatile solvents and toxic intermediates. REACH compliance mandates zero fugitive emissions across ECHA-regulated facilities. Replacement pull is accelerating under EU F-Gas Regulation enforcement timelines.
- Water Treatment:Reverse osmosis and desalination plants specify leak-free brine circulation at high salinity. Coastal installations in Saudi Arabia and the UAE favor nickel-alloy shells for corrosion resistance. Capacity expansion is climbing the fastest among end-use segments.
- Industrial Sector:General manufacturing applications span cooling, heating, and process fluid transfer. DOE efficiency standards in the United States drive retrofit specification upgrades.
- Power Generation:Combined-cycle and nuclear plants require absolute reliability in primary coolant loops. Procurement emphasizes mean time between overhaul and seismic qualification.
Chemical processing commands premium pricing tiers. Water treatment is where volume expansion concentrates.
Technology:
Technology adoption curves track regulatory enforcement intensity, with efficiency mandates accelerating faster than automation integration in conservative process industries.
- Variable Frequency Drives:Demand-responsive speed control eliminates throttling losses in variable-flow chemical loops. VFD-integrated canned motor packages capture retrofit opportunities where legacy throttling valves waste energy. DOE pump efficiency standards favor these configurations.
- High-Efficiency Motors:Permanent magnet synchronous designs achieve IE4/IE5 efficiency ratings. Rare earth magnet supply concentration in Chinese processing facilities creates cost volatility.
- Direct Drive:Elimination of mechanical couplings reduces maintenance points in submersible applications. Simplified architecture appeals to remote desalination installations.
- Pump Automation:Integrated sensors and edge computing enable predictive maintenance. Adoption lags in legacy DCS environments requiring protocol translation.
High-efficiency motors dominate new-build specification. Variable frequency drives are where retrofit revenue concentrates.
Installation Type:
Project delivery models split between capital-intensive greenfield engineering and faster-turn retrofit replacements, with financing structures adapting to each.
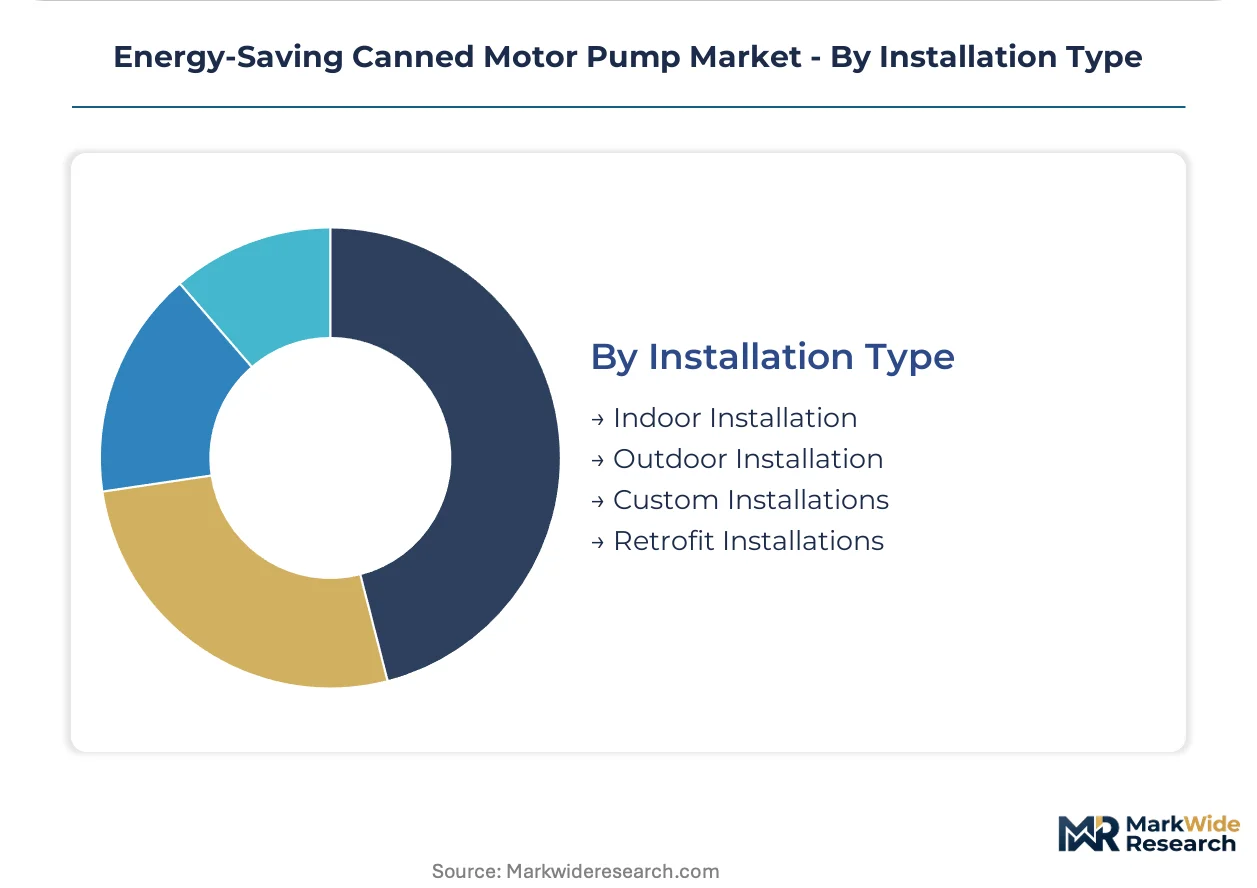
- Retrofit Installations:Drop-in replacements of conventional sealed pumps address EPA leak detection mandates in US petrochemical corridors. Energy-as-a-service leasing models reduce customer capital burden.
- Indoor Installation:Climate-controlled environments in pharmaceutical and food processing facilities simplify motor cooling requirements. Standard containment shell materials suffice.
- Outdoor Installation:Exposure to temperature extremes and precipitation demands enhanced sealing and thermal management. Middle Eastern solar-powered desalination plants specify these for remote coastal sites.
- Custom Installations:Engineered solutions for cryogenic hydrogen transfer or ultra-high-pressure applications. Lead times extend due to ASME Section IX welding certification requirements.
Retrofit installations dominate near-term revenue. Custom installations are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a substantial export surplus in hermetic pump technology, while the United States and Japan balance trade through specialized component imports. China's domestic fabrication capacity is displacing former import dependence for standard-duty units. Middle Eastern desalination projects source premium containment shells from European and Japanese suppliers.
Germany
Rhine-Ruhr chemical clusters drive specification pull for ATEX-certified hermetic pumps handling sulfuric acid and volatile solvents. The EU F-Gas Regulation enforcement compresses replacement cycles for conventional sealed pumps. HERMETIC-Pumpen GmbH anchors domestic engineering expertise in specialty containment shell fabrication.
United States
EPA leak detection mandates for hazardous fluids accelerate retrofit procurement across Gulf Coast petrochemical corridors. DOE pump efficiency standards create certification gaps favoring premium hermetic designs. Houston-area engineering contractors specify nickel-alloy shells for brine handling in expanding desalination capacity.
Japan
Precision motor manufacturing clusters in Nagoya supply permanent magnet assemblies for high-efficiency canned motor variants. METI efficiency benchmarks elevate IE4/IE5 motor specifications in process industries. Teikoku Electric Mfg. Co., Ltd. exemplifies backward integration into stator winding technology for nuclear coolant applications.
China
Dual carbon goals under MEE directives drive energy-efficiency retrofits in coastal chemical provinces. Domestic rare earth processing concentration in Inner Mongolia supplies neodymium magnet feedstock for motor manufacturing. Yangtze River Delta pump assemblers are capturing standard-duty water treatment specifications from former import sources.
Saudi Arabia
NEOM and Red Sea desalination megaprojects specify leak-free brine circulation at extreme salinity levels. SFDA industrial safety requirements align procurement with IECEx certification standards. Eastern Province fabrication yards source Hastelloy containment shells through German and Japanese supplier relationships.
Energy-Saving Canned Motor Pump Market Competitive Landscape
On the supply side, the industry is consolidating around vendors with captive orbital welding capacity and certified ASME Section IX fabrication facilities. Tiered competitive positioning separates premium hermetic specialists from standard-duty assemblers sourcing containment shells externally. Two strategic archetypes dominate: German-engineered specialty fabricators serving chemical hazard applications, and Japanese precision motor manufacturers integrating upstream magnet supply. Competitive moves concentrate on leasing-enabled project finance structures and VFD-integrated package offerings for retrofit channels.
Among Germany-based engineering specialists, HERMETIC-Pumpen GmbH occupies a position exemplifying containment shell fabrication mastery for high-pressure chemical duty. Japanese precision manufacturers including Nikkiso Co., Ltd. and Teikoku Electric Mfg. Co., Ltd. represent the backward-integrated archetype controlling stator and permanent magnet production internally. These three anchors illustrate how geographic clustering of welding certification and rare earth processing shapes competitive differentiation without requiring active strategic claims about individual firm behavior.
| Leading Market Players |
|---|
| HERMETIC-Pumpen GmbH |
| Nikkiso Co., Ltd. |
| Teikoku Electric Mfg. Co., Ltd. |
| Kirloskar Brothers Limited |
| KSB SE & Co. KGaA |
| Shinhoo |
| Hayward Tyler Ltd. |
| Flowserve Corporation |
| OPTIMEX |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in certified orbital welding shops across Germany and Japan is compressing fabrication lead times and elevating containment shell premiums. This utilization squeeze simultaneously empowers incumbent suppliers with captive ASME Section IX capacity while forcing price-sensitive buyers toward standard-duty magnetic drive alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ATEX/IECEx certification grade and containment shell material specification, with Hastelloy C-276 variants commanding substantial premiums over 316L stainless configurations. Cost compression in the economy tier is intensifying because Chinese assemblers are capturing standard water treatment specifications with rare earth magnet supply advantages. Chemical processors in the Rhine-Ruhr cluster demonstrate the lowest price sensitivity, prioritizing hermetic integrity over capital outlay, while municipal water utilities negotiate aggressively on total cost of ownership metrics.
Supply Chain Analysis
Contract manufacturing for precision containment shells concentrates with HERMETIC-Pumpen GmbH's captive fabrication facilities in Germany and specialized orbital welding shops in Nagoya, Japan. Geographic supply concentration centers on Germany, Japan, and China, with the latter dominating rare earth magnet processing in Inner Mongolia. Raw material dependencies draw from neodymium-dysprosium magnet feedstock, nickel-alloy plate stock, and silicon carbide bearing blanks. Single-source vulnerability in qualified orbital welding technicians creates supply chain risk. Distribution runs through OEM-direct channels for premium chemical duty and regional pump distributors for standard water treatment applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The energy-saving canned motor pump market is entering a cyclical recovery phase as EU F-Gas Regulation enforcement compresses replacement cycles for conventional sealed pumps ahead of mechanical failure.
For Market Incumbents: Entrench market position by deepening backward integration into permanent magnet supply chains and expanding captive orbital welding capacity in North America to address technician scarcity. Magnetic drive competitors are gaining share in low-pressure aqueous applications; counter this threat by bundling VFD-integrated packages with predictive maintenance contracts that magnetic drives cannot match. Certification investment in IECEx and UL parallel approval processes accelerates time-to-revenue for new cryogenic hydrogen variants. For New Entrants and Emerging Players: Retrofit channels in US Gulf Coast petrochemical corridors represent the most penetrable entry point, where EPA leak detection mandates have created specification urgency without incumbent service lock-in. Desalination capacity expansion in Saudi Arabia and the UAE offers secondary white-space, particularly for nickel-alloy submersible configurations where European lead times create procurement gaps. A leasing-enabled project finance go-to-market angle bypasses capital-constrained buyer procurement committees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across custom cryogenic and ultra-high-pressure fabrication segments as ASME Section IX certification requirements extend lead times and tie up working capital. Long-term viability over the next decade favors vendors with balance-sheet capacity to offer energy-as-a-service contracts rather than transactional equipment sales. Acquisition targets should display captive welding certification and stator winding expertise. The signal to watch is VFD-integrated package attach rates in chemical retrofit proposals, which indicate vendor success in escaping commodity pricing tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium processing in Inner Mongolia insulates margin from Chinese export quota volatility. |
| Orbital Welding Capacity Expansion | ASME Section IX-certified fabrication in Houston addresses technician scarcity in North American retrofit channels. |
| VFD-Integrated Package Development | Demand-responsive flow control configurations capture DOE efficiency standard compliance premiums. |
| Cryogenic Hydrogen Variant Certification | IECEX and UL listings for liquid hydrogen transfer address emerging fueling station network specifications. |
| Energy-as-a-Service Leasing Models | Recurring revenue contracts bypass capital-constrained municipal water utility procurement constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted to construct this analysis, combining structured primary interviews with secondary validation across trade and technical sources. Plant engineers, maintenance directors at chemical processing facilities, procurement leads from desalination EPC contractors, aftermarket service heads, and OEM technical sales specialists provided operational perspective. Secondary sources included customs and trade flow databases, SEC 10-K filings from listed pump manufacturers, Cefic chemical industry reports, and EPA enforcement action records. Bottom-up unit shipment estimates were triangulated against top-down value projections.
Calibration against historical replacement cycle timing and regulatory enforcement phase-in schedules anchored the projection framework across the analysis window. Segmentation dimensions modeled include hydraulic design type, end-use industry vertical, efficiency certification tier, containment shell material specification, and geographic regulatory cluster. CAGRs were derived from regression analysis of correlated industrial capital expenditure patterns and efficiency mandate compliance deadlines. Forecast inputs incorporated rare earth magnet price volatility indices and desalination capacity expansion pipelines.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, interest rate environments affecting project finance availability, or rare earth export policy shifts would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and replacement cycle compression timing. Quarterly review of EPA enforcement action filings, EU F-Gas Regulation quota auction results, and Middle Eastern desalination project award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Global Hydraulic Gear Pump Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
Hydrogen Circulation Pump Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Spiral Classifier Market