
 Multi-Parameter Patient Monitoring Market | 2026-2036
Multi-Parameter Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Parameter Patient Monitoring Market Foresight
Modular sensor bundling is expanding as the dominant configuration pattern across acute care settings. GE Healthcare leverages in-house manufacturing scale to control component supply for integrated bedside systems. Koninklijke Philips sustains technology leadership in optical pulse oximetry modules that clip into broader monitoring platforms. Shenzhen Mindray Bio-Medical Electronics anchors its competitive position through cost-optimized portable configurations for emerging health systems.
Multi-parameter patient monitoring encompasses devices that simultaneously track vital signs including electrocardiography, blood pressure, oxygen saturation, respiratory rate, and temperature through shared processing units and display interfaces, typically operating with sampling frequencies between 125 Hz and 1000 Hz for cardiac channels. These systems serve primarily to reduce alarm fatigue, streamline clinical workflow, and enable early warning scoring in perioperative and intensive care environments. Bedside monitors dominate installed base value due to their central role in surgical suites and ICUs, while wearable monitors represent the fastest-expanding configuration as ambulatory telemetry protocols migrate outside hospital walls. Wireless technology segments capture disproportionate R&D investment as health systems prioritize cable-free patient mobility and reduced infection vectors from shared equipment.
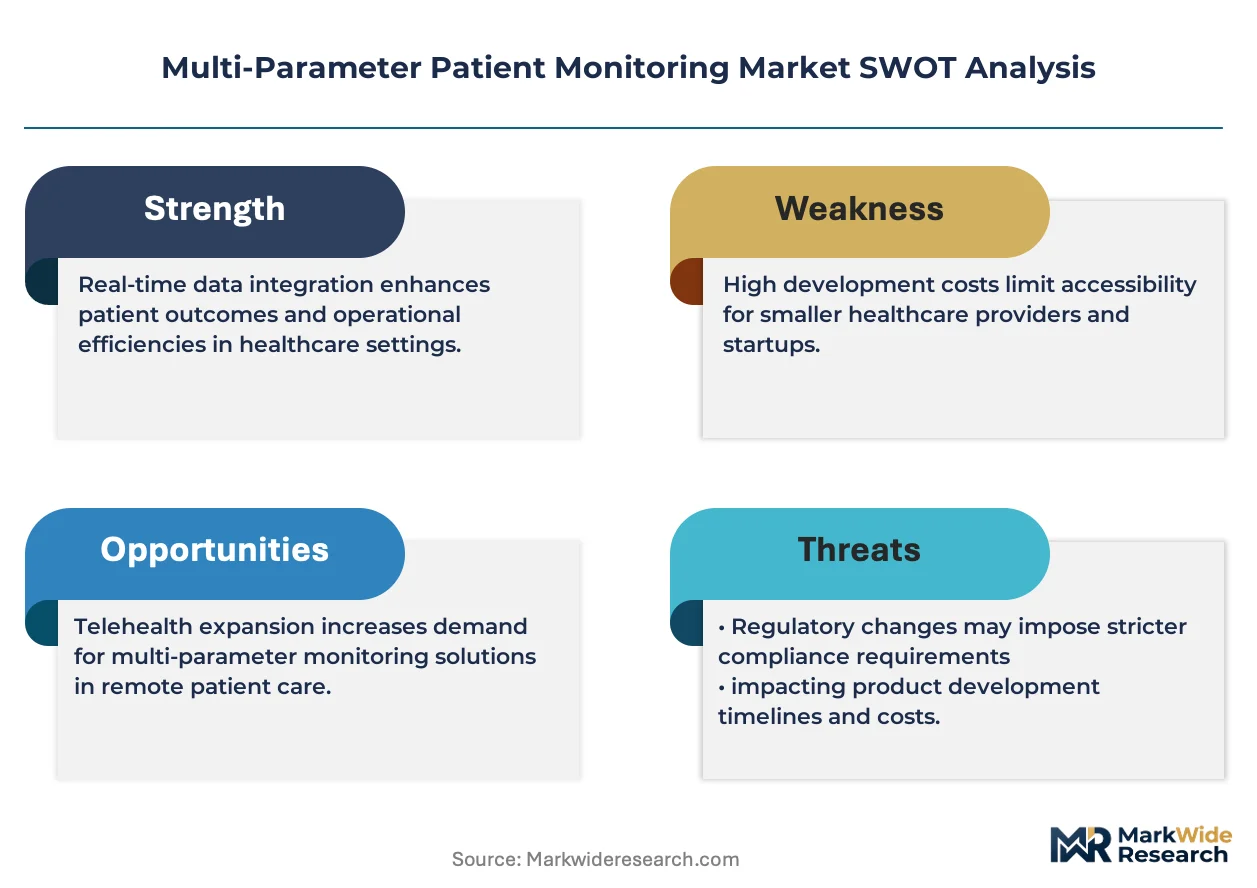
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market entry sequencing for device manufacturers. ISO 80601-2-56 and IEC 60601-1-8 standards govern alarm system performance, directly influencing design priorities for acoustic and visual alert differentiation. Stakeholders must monitor evolving cybersecurity guidance from national regulators as network-connected monitors expand attack surfaces across health delivery organizations.
Market Dynamics
Wireless telemetry protocols are compressing installation timelines and forcing bedside monitor vendors to re-architect hardware around software-defined signal processing rather than dedicated analog front-ends.
Growth Catalysts
- EU MDR technical documentation mandates:Stringent post-market surveillance requirements accelerate hospital replacement cycles for legacy devices lacking digital connectivity and remote firmware update capabilities.
- Perioperative early warning scoring protocols:Surgical suites in tertiary hospitals deploy integrated multi-parameter platforms to automate risk stratification and reduce unplanned ICU admissions.
- India's PLI scheme for medical electronics:Domestic manufacturing incentives attract component suppliers and assembly operations to reduce import dependency for patient monitoring hardware.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries dominate analog-to-digital converter fabrication, creating vulnerability for 24-bit precision cardiac front-ends essential to arrhythmia detection algorithms.
- ISO 80601-2-56 alarm fatigue mitigation standards:Acoustic differentiation requirements extend engineering validation timelines and complicate software release cycles for networked monitoring platforms.
- Disposable electrode cost volatility:Silver-silver chloride sensor prices fluctuate with precious metal markets, pressuring margin structures in high-acuity settings with intensive consumable turnover.
Strategic Opportunities
- Home-based acute care expansion:Germany's Hospital Future Act funds decentralized monitoring infrastructure, creating demand for cellular-connected wearable configurations outside traditional facility walls.
- AI-embedded edge computing convergence:On-device inference engines for sepsis prediction reduce cloud dependency and latency in bandwidth-constrained environments.
- Direct-to-hospital distribution platforms:Digital procurement channels bypass traditional device distributor markups for standardized bedside configurations in mid-tier health systems.
Industry Challenges
- Firmware cybersecurity skill scarcity:Health delivery organizations struggle to recruit embedded systems engineers capable of patching network-connected monitors against evolving threat vectors.
- Legacy RS-232 integration complexity:Decades-old bedside installations require protocol bridging hardware to interface with modern HL7 FHIR data architectures, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Parameter Patient Monitoring Market |
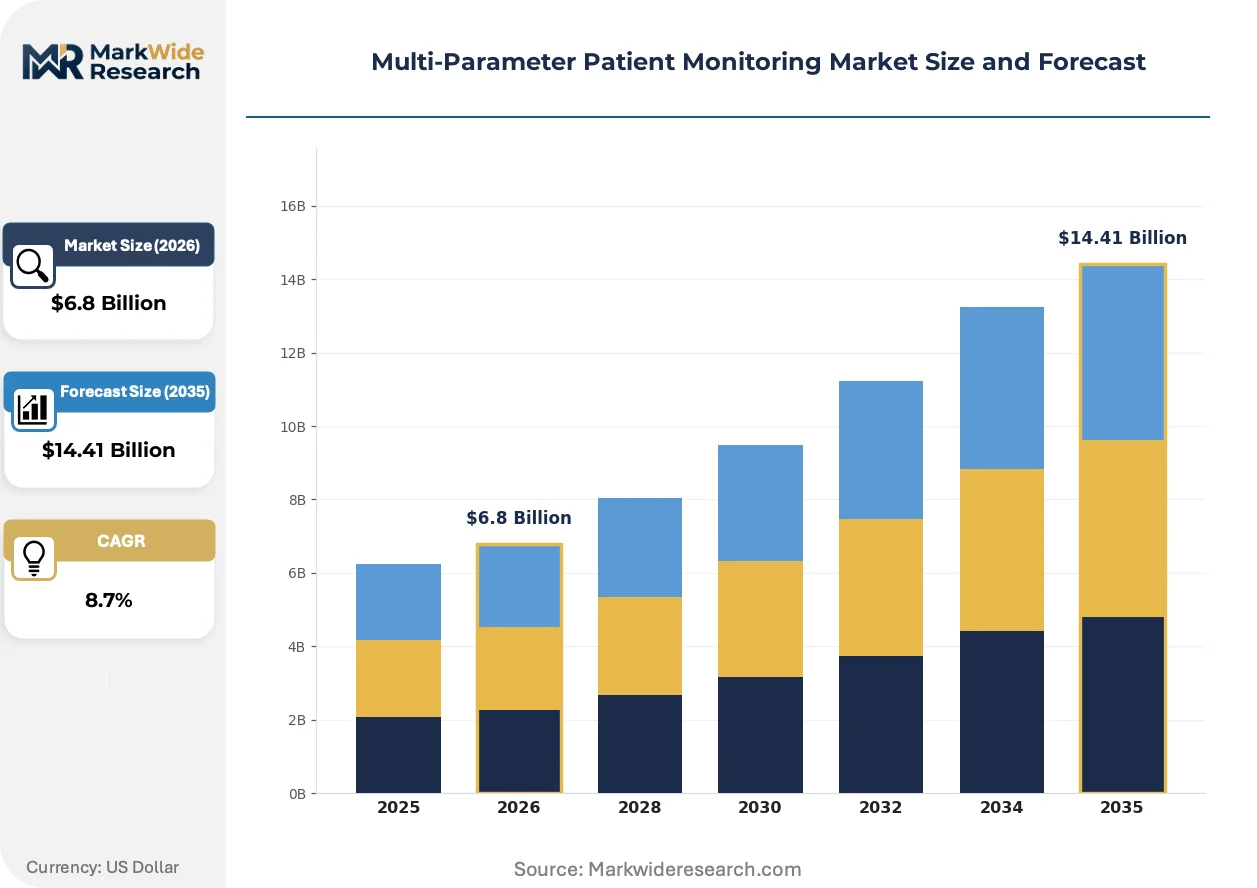
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedside Monitors, Portable Monitors, Wearable Monitors, Handheld Devices Technology: Wireless Technology, Wired Technology, Optical Technology, IoT Solutions End User: Hospitals, Home Care, Emergency Services, Rehabilitation Centers Application: Cardiac Monitoring, Respiratory Monitoring, Fetal Monitoring, Neurological Monitoring |
| Companies Covered | GE Healthcare, Koninklijke Philips, Medtronic, Shenzhen Mindray Bio-Medical Electronics, Masimo, Nihon Kohden, Baxter, Drägerwerk AG & Co. KGaA, OSI Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Parameter Patient Monitoring Market Shifts & Advancements
Signal processing architectures are migrating from dedicated hardware to software-defined platforms, enabling post-deployment algorithm updates and collapsing the traditional monitor replacement cycle.
Continuous multi-lead ECG analysis with embedded arrhythmia classification is consolidating clinical workflow around single-platform monitoring rather than separate telemetry and bedside systems. Cardiac catheterization labs and electrophysiology suites in the United States adopt these configurations fastest, replacing discrete Holter monitors and event recorders. The technology is consolidating vendor relationships as hospitals reduce device supplier counts to streamline training and maintenance contracts.
EU MDR Article 10 post-market clinical follow-up obligations now require systematic collection of real-world performance data from deployed monitoring devices. Manufacturers must establish proactive surveillance systems rather than reactive complaint handling. High-acuity bedside platforms face the steepest compliance burden, prompting some vendors to sunset legacy product lines rather than retrofit connectivity infrastructure.
Hospital procurement committees now unbundle capital equipment purchases from long-term service agreements, treating monitoring hardware as commodity infrastructure while negotiating software subscriptions separately. This bifurcation pressures traditional vendors who historically bundled margins into multi-year maintenance contracts. The shift is most visible in United States IDN consolidation, where centralized supply chain offices impose standardized device specifications across acquired facilities.
Multi-Parameter Patient Monitoring Market Segmentation
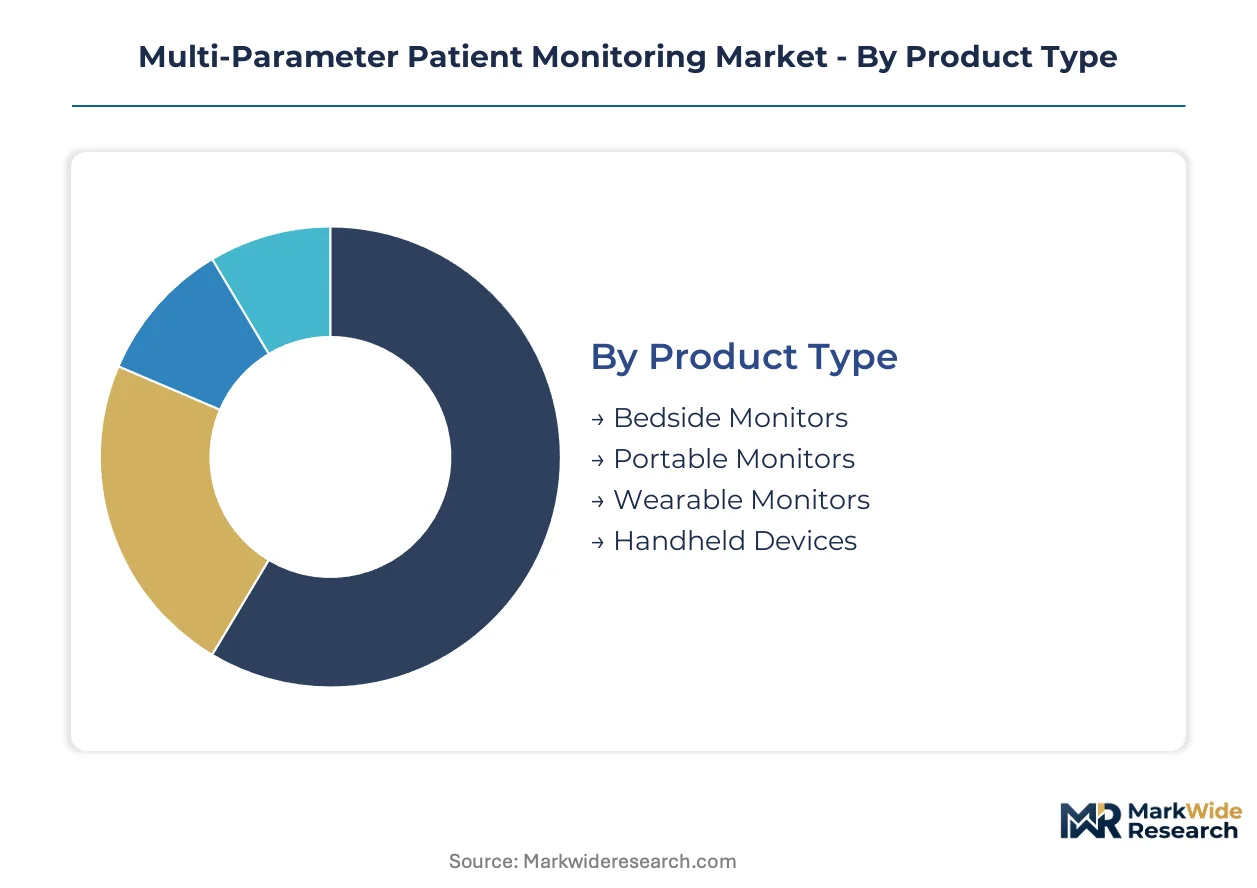
Segmentation in multi-parameter patient monitoring reveals distinct capital requirements and deployment patterns across acute care infrastructure. Each category maps to specific procurement cycles and technical validation pathways that shape vendor competitive positioning.
Product Type:
Capital intensity varies sharply across configurations, with fixed installations demanding substantial upfront facility investment while mobile alternatives prioritize unit economics and consumable attach rates.
- Bedside Monitors:These systems integrate multi-lead ECG, invasive pressure modules, and capnography through centralized processing architectures with dedicated power and network infrastructure. Tertiary surgical suites in the United States and Germany drive replacement demand as early warning scoring protocols mandate higher sampling fidelity and alarm differentiation capabilities.
- Portable Monitors:Battery-powered configurations with modular parameter slots enable intra-hospital transport and step-down unit deployment without fixed installation costs. China's county-level hospital modernization program and India's emerging health systems prioritize these units for flexible ward configuration.
- Wearable Monitors:Patch-based and wrist-worn devices with Bluetooth Low Energy transmission target ambulatory telemetry and hospital-at-home programs.
- Handheld Devices:Compact spot-check units with limited parameter sets serve rapid assessment workflows in triage and outpatient settings.
Bedside monitors absorb the bulk of installed capacity; wearable monitors are expanding most quickly.
Technology:
Signal transmission architecture determines regulatory validation burden and cybersecurity exposure, with wireless protocols requiring more extensive electromagnetic compatibility testing and network hardening.
- Wireless Technology:IEEE 802.11ac/ax and proprietary 2.4 GHz protocols enable cable-free patient mobility and reduced infection risk from shared equipment surfaces. FDA cybersecurity guidance and EU MDR network-connected device requirements are compressing development timelines for these configurations as health systems prioritize seamless electronic health record integration.
- Wired Technology:Galvanically isolated analog front-ends with dedicated shielded cabling maintain signal integrity in high-electromagnetic-interference environments like catheterization labs and MRI suites.
- Optical Technology:Photoplethysmography-based pulse oximetry and regional oxygen saturation modules clip into broader monitoring platforms.
- IoT Solutions:Cloud-connected gateways aggregate data from distributed sensors for centralized surveillance dashboards.
Wired technology retains dominance in high-acuity settings; wireless configurations are climbing the fastest as telemetry protocols migrate beyond traditional facility walls.
End User:
Procurement authority and reimbursement pathways create distinct customer segments with diverging price sensitivity and service contract expectations.
- Hospitals:Integrated delivery networks and academic medical centers negotiate enterprise agreements with standardized specifications across surgical suites, ICUs, and emergency departments. Germany's Hospital Future Act and United States IDN consolidation are accelerating centralized purchasing of networked monitoring platforms with remote firmware management.
- Home Care:Durable medical equipment suppliers and home health agencies demand cellular-connected wearable devices with simplified patient interfaces and automated clinician alerting.
- Emergency Services:Ground and air ambulance operators require ruggedized portable monitors with extended battery life and satellite transmission capability.
- Rehabilitation Centers:Skilled nursing and post-acute facilities prioritize cost-optimized bedside configurations with reduced parameter sets.
Hospitals command the largest share of capital expenditure; home care is gaining share fastest as acute care decentralization accelerates.
Application:
Clinical use case determines sensor configuration, algorithm complexity, and alarm prioritization schemes that differentiate product tiers.
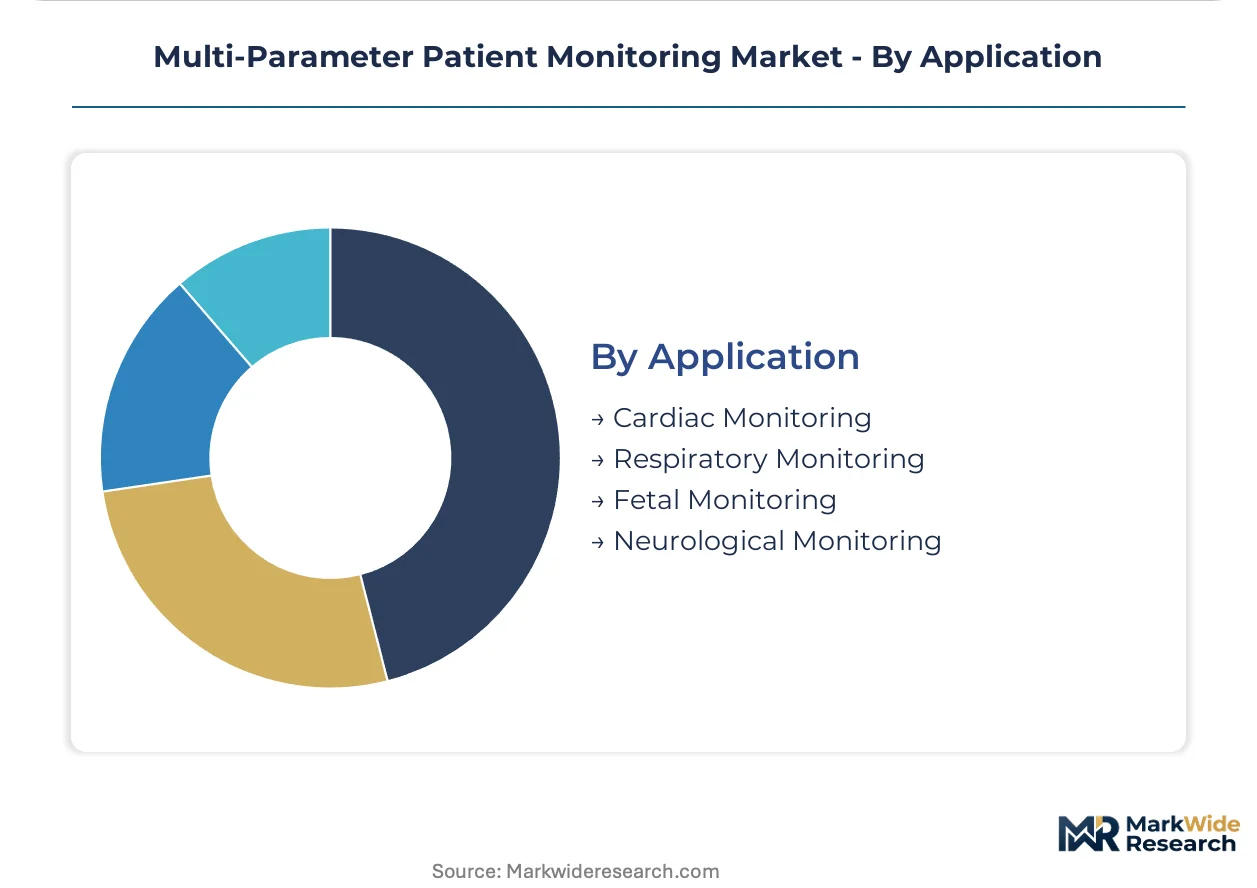
- Cardiac Monitoring:Continuous multi-lead ECG with embedded arrhythmia classification and ST-segment analysis serves perioperative and coronary care environments. Cardiac catheterization labs in the United States are consolidating around single-platform monitoring that replaces discrete Holter and telemetry systems.
- Respiratory Monitoring:Capnography, pulse oximetry, and respiratory impedance plethysmography integrate for ventilator weaning and sedation monitoring.
- Fetal Monitoring:Combined cardiotocography and maternal vital sign tracking supports labor and delivery suites.
- Neurological Monitoring:Bispectral index, intracranial pressure, and cerebral oximetry modules target neuro-ICU and operating room anesthesia workflows.
Cardiac monitoring deploys the broadest installed base; neurological monitoring is on the steepest expansion trajectory as multimodal brain monitoring protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Dongguan concentrate electronics manufacturing for patient monitoring components. These zones attract contract manufacturers serving device vendors across three continents. The geographic distribution of demand reflects health system modernization timelines and regulatory pathway efficiency.
United States
Integrated delivery networks consolidate purchasing across acquired hospital systems, driving standardization of networked bedside platforms. FDA 510(k) clearance pathways and cybersecurity guidance compress development timelines for wireless telemetry configurations. The Boston-Cambridge corridor anchors digital health innovation clusters developing AI-embedded monitoring algorithms.
Germany
The Hospital Future Act funds decentralized acute care infrastructure, expanding demand for cellular-connected wearable monitors outside facility walls. EU MDR technical documentation and post-market surveillance obligations accelerate replacement cycles for legacy devices lacking remote firmware capabilities. The Baden-Württemberg medical technology cluster hosts precision sensor manufacturers supplying cardiac front-end components.
China
County-level hospital modernization programs prioritize portable monitoring configurations for flexible ward deployment. NMPA regulatory harmonization with international standards streamlines market entry for domestic manufacturers. The Yangtze River Delta electronics manufacturing base supplies cost-optimized signal processing modules for emerging health systems across Asia and Africa.
India
The PLI scheme for medical electronics attracts component suppliers and assembly operations to reduce import dependency for monitoring hardware. CDSCO regulatory pathways for Class C and D devices shape product registration sequencing for multinational entrants. The Karnataka medical device cluster near Bengaluru concentrates contract manufacturing for portable and wearable configurations.
Japan
Aging demographics and hospital bed reduction policies drive ambulatory telemetry adoption for home-based acute care. PMDA regulatory requirements for software as a medical device influence validation protocols for AI-embedded monitoring platforms. The Tokyo-Osaka corridor maintains concentration of precision electronics suppliers serving cardiac and neurological monitoring segments.
Multi-Parameter Patient Monitoring Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. The market structure concentrates around three to five integrated platforms commanding hospital enterprise agreements, with mid-tier specialists occupying modular component niches. Strategic archetypes include full-stack bedside system vendors, optical sensor module specialists, and cost-optimized portable manufacturers. Competitive moves center on M&A for algorithm capabilities and strategic partnerships for wireless telemetry certification.
Within the diversified conglomerate tier, GE Healthcare and Koninklijke Philips occupy positions exemplifying integrated manufacturing scale and optical module leadership respectively. Shenzhen Mindray Bio-Medical Electronics represents the cost-optimized portable configuration archetype serving emerging health systems. These three anchors illustrate the geographic and technological segmentation shaping procurement committee evaluations across acute care settings.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips |
| Medtronic |
| Shenzhen Mindray Bio-Medical Electronics |
| Masimo |
| Nihon Kohden |
| Baxter |
| Drägerwerk AG & Co. KGaA |
| OSI Systems |
| Others |
Supply & Pricing Matrix
EU MDR sustainability and post-market surveillance mandates gate qualified supply access and premium-tier pricing for bedside monitoring platforms, as manufacturers must demonstrate remote firmware capabilities and digital connectivity infrastructure to serve German hospital procurement committees and United States IDN consolidation programs.
Pricing Analysis
Price erosion across portable configurations traces to Shenzhen Mindray Bio-Medical Electronics and domestic Chinese manufacturers leveraging Yangtze River Delta component sourcing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared wireless telemetry systems from CE-marked wired installations and unconnected legacy monitors. Cost-down pressure on bedside platforms accelerates because hospital procurement committees now unbundle hardware from service contracts. Emergency services and county-level hospitals in emerging health systems exhibit highest price sensitivity; cardiac catheterization labs in tertiary United States hospitals show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundries dominating 24-bit precision analog-to-digital converter fabrication for cardiac front-ends. Component manufacturing concentrates in China, Taiwan, and South Korea. Raw material dependencies include silver-silver chloride for disposable electrodes, gallium arsenide for optical sensors, and medical-grade plastics for housings. Supply chain risk centers on semiconductor supply concentration disrupting arrhythmia detection algorithm performance. Distribution runs through regional device distributors, direct-to-hospital digital procurement platforms, and GPO contracts for IDN standardization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-parameter patient monitoring is consolidating around integrated platform vendors as EU MDR compliance costs and cybersecurity validation timelines force subscale manufacturers to exit. Procurement committee unbundling of hardware and software contracts accelerates this pressure.
For Market Incumbents: Cement technology leadership in optical pulse oximetry modules and software-defined signal processing architectures to defend against AI-embedded edge computing entrants. Prioritize backward integration into precision sensor manufacturing through Baden-Württemberg and Tokyo-Osaka supplier partnerships. Lock in hospital enterprise agreements before procurement committees finalize standardized specifications across acquired facilities.
For New Entrants and Emerging Players: Enter via home-based acute care telemetry and hospital-at-home programs in Germany's Hospital Future Act funding corridors, where cellular-connected wearable demand outpaces incumbent platform adaptation. Target India's PLI scheme medical electronics clusters for cost-optimized portable assembly. Pursue direct-to-hospital distribution partnerships bypassing traditional device distributor markups.
For Investors and Strategic Acquirers: FDA 510(k) clearance for wireless telemetry configurations with embedded sepsis prediction algorithms is the leading indicator that AI-embedded edge computing convergence has reached commercial viability. Position for five-to-ten year holding periods around modular sensor specialists with ISO 80601-2-56 alarm differentiation capabilities. Monitor CDSCO Class C and D registration timelines for India market entry sequencing signals.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates United States market entry for wireless telemetry with cybersecurity documentation. |
| CE Marking Pathway | Unlocks German Hospital Future Act funding for decentralized acute care infrastructure deployment. |
| Hospital System Partnership | Secures enterprise standardization across United States IDN surgical suites and ICUs. |
| Software Companion Development | Enables post-deployment algorithm updates collapsing traditional monitor replacement cycles. |
| Reimbursement Strategy | Aligns ambulatory telemetry protocols with CMS Medicare hospital-at-home program expansion. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, and hospital procurement database records, complemented by interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee members, and regulatory affairs specialists. Secondary sources included SEC filings, NMPA registration data, and CMS Medicare reimbursement schedules. Bottom-up unit shipment estimates triangulated against top-down health system capital expenditure surveys.
Cross-referencing historical replacement cycle patterns with expert panel input on EU MDR compliance timelines shaped the analytical framework. Segmentation dimensions modeled include product configuration, signal transmission architecture, end-user procurement authority, and clinical application intensity. CAGRs were derived from installed base evolution and ambulatory telemetry protocol migration rates. Forecast inputs incorporated semiconductor supply concentration risk and alarm fatigue mitigation standard implementation pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Taiwan foundry capacity constraints or accelerated United States cybersecurity guidance enforcement. Forecasts reflect documented assumptions about health system modernization funding continuity and regulatory harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
South America Fetal and Neonatal Monitoring Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
Heart Failure Monitoring Systems Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
Gas Exchange Monitor Market
Patient Monitoring
Digital Patient Monitoring Systems Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
United States Patient Monitoring Market