
 Patient Identification Wristbands Market | 2026-2036
Patient Identification Wristbands Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Identification Wristbands Market Analysis
Multi-source procurement for patient identification wristbands is restructuring supply relationships across hospital systems. Zebra Technologies Corporation leverages its barcode printing ecosystem to dominate acute-care contracts. PDC Healthcare anchors the North American market through direct distribution to integrated delivery networks. Brady Worldwide, Inc. competes on specialty materials including latex-free and color-coded options for pediatric and allergy-sensitive populations.
Patient identification wristbands are wearable labels manufactured from synthetic substrates, woven textiles, or metal alloys, typically incorporating barcode symbologies, radio-frequency identification inlays, or quick-response codes for automated data capture at the point of care. The primary purpose is to eliminate identification errors during medication administration, specimen collection, surgical procedures, and patient transport within healthcare facilities. Plastic bands lead unit volume due to lowest per-unit cost and compatibility with thermal-transfer printing, while RFID bands represent the fastest-expanding technology segment as hospitals replace legacy barcode infrastructure for real-time location tracking. Fabric bands retain share in long-term residential care settings where durability across repeated laundering cycles determines total cost of ownership.
The Joint Commission mandates two patient identifiers for every clinical encounter, directly sustaining wristband demand across accredited US hospitals. FDA guidance on medical device data systems influences RFID band interoperability standards with electronic health record platforms. Stakeholders must monitor whether emerging AI-driven patient verification protocols supplement or displace physical wristband requirements in high-acuity settings.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins and forcing wristband suppliers to bundle software, printing hardware, and consumables into multi-year enterprise contracts. Integrated delivery networks now mandate single-source identification platforms, rewarding vendors with full-stack capabilities.
Growth Catalysts
- Joint Commission mandates:The accreditation body's two-identifier requirement sustains wristband demand across every US acute-care encounter. Compliance audits drive replacement cycles for worn or non-scannable bands.
- RFID infrastructure:Real-time location systems in perioperative suites and emergency departments are automating patient flow tracking. Hospitals deploying RFID wristbands reduce bed turnover delays and specimen mislabel incidents.
- Antimicrobial material science:Silver-ion and copper-alloy substrates are displacing standard plastics in infection-control-sensitive units. Material suppliers partner with band manufacturers to meet CDC healthcare-associated infection prevention guidelines.
Market Restraints
- RFID chip supply concentration:Inlay production clusters in East Asian foundries, exposing buyers to semiconductor allocation volatility and extended lead times during capacity crunches.
- Legacy printer lock-in:Thermal-transfer hardware investments by hospital IT departments create switching costs that slow migration to newer direct-thermal or RFID-enabled band formats.
- Disposable cost structure:Single-use plastic bands generate recurring material expenditure that competes with capital budgets for electronic health record upgrades and clinical device procurement.
Strategic Opportunities
- Long-term care expansion:Skilled nursing facilities and assisted-living operators underpenetrate in barcode wristband deployment. Washable fabric bands with embedded RFID offer durable alternatives to adhesive disposables in residential settings.
- Pediatric and neonatal specialization:Size-adjustable bands with hypoallergenic adhesives address the unique skin-sensitivity and circumference-range requirements of infant populations.
- EU MDR traceability:The Medical Device Regulation's unique device identifier requirements create compliance-driven demand for wristbands that integrate with device tracking systems in European hospitals.
Industry Challenges
- EHR interoperability fragmentation:Wristband data formats must synchronize with diverse electronic health record platforms, requiring vendor-specific integration engineering for each hospital system deployment.
- Biocompatibility certification timelines:ISO 10993 testing for skin-contact materials extends product development cycles, delaying commercialization of novel antimicrobial substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Identification Wristbands Market |
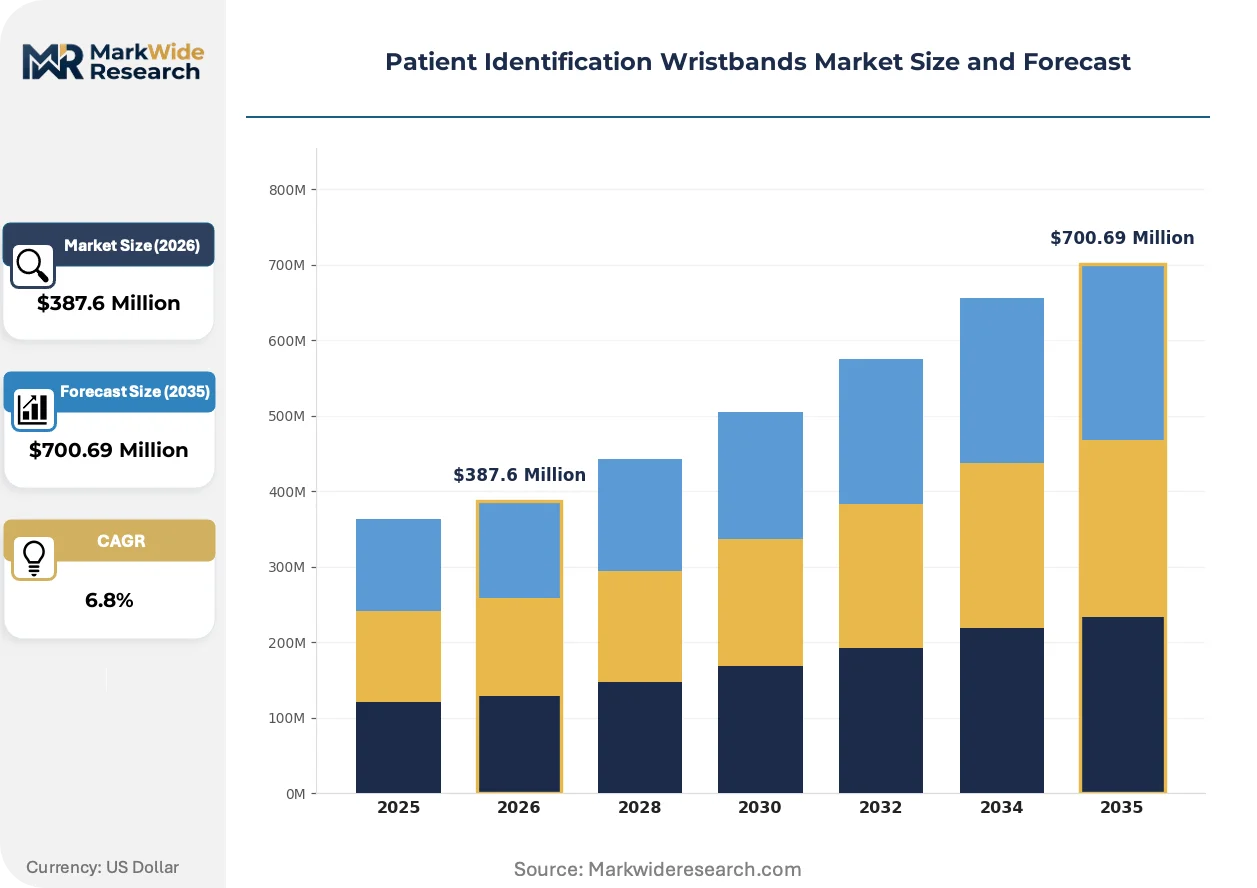
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bands, Fabric Bands, Metal Bands, RFID Bands Application: Hospitals, Clinics, Residential Care, Special Events Technology: Barcode, RFID, QR Code, Color-Coding End User: Healthcare Providers, Event Organizers, Laboratories, Emergency Services |
| Companies Covered | Zebra Technologies Corporation, PDC Healthcare, Brady Worldwide, Inc., McKesson Medical-Surgical Inc., Thermo Fisher Scientific Inc., SATO Holdings Corporation, IdentiSys Inc., Compass Health Brands, Typenex Medical, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Identification Wristbands Market Emerging Trajectories
Active RFID and sensor-embedded wristbands are transforming patient identification from passive labeling into real-time data infrastructure. Material scientists, systems integrators, and hospital IT departments collaborate on platforms that merge identity verification with clinical workflow automation.
Passive UHF RFID inlays with encrypted EPC Gen2v2 protocols are automating medication administration verification at bedside scanners. Large academic medical centers in the United States deploy these bands across perioperative and oncology units, compressing pharmacy verification labor and reducing wrong-patient drug events. The technology is automating reconciliation between physical patient location and electronic health record status flags.
REACH restrictions on phthalates and heavy metals in skin-contact plastics are accelerating substitution of PVC substrates with TPU and silicone alternatives. European band manufacturers reformulate extrusion compounds to maintain printability while meeting SVHC disclosure thresholds. The regulation most affects neonatal and long-term wear applications where prolonged skin contact elevates chemical exposure risk.
Hospital supply chain directors are consolidating identification consumables under single-source distribution agreements that bundle bands, labels, and ribbons. Group purchasing organizations negotiate these arrangements on behalf of member health systems, displacing fragmented procurement through local medical-surgical distributors. The shift is most visible in the United States where GPO contract penetration exceeds seventy percent of acute-care beds.
Patient Identification Wristbands Market Segmentation
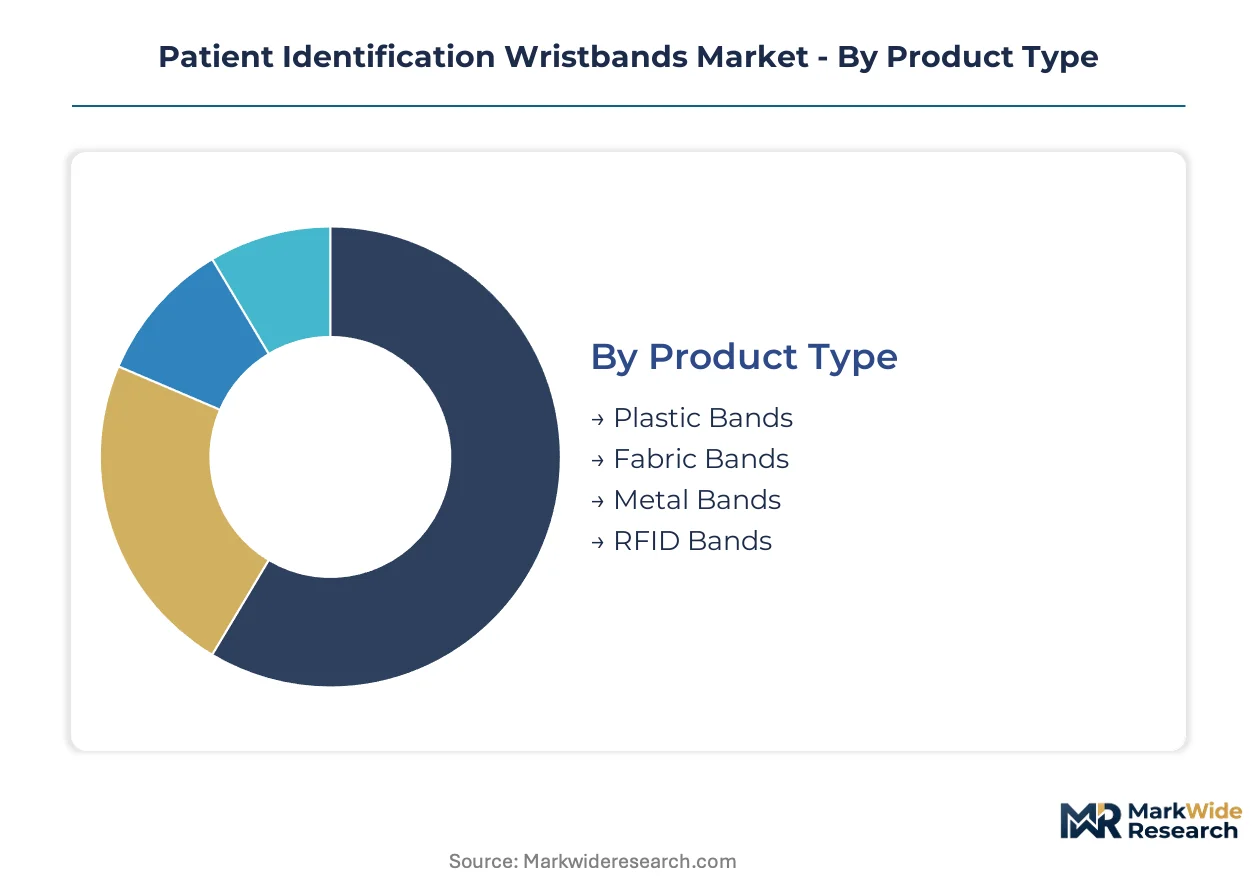
Patient identification wristbands segment across material substrates, care settings, data capture technologies, and purchasing stakeholders. Each dimension carries distinct certification requirements, cost structures, and replacement cycles that shape vendor positioning and procurement strategy.
Product Type:
ISO 10993 biocompatibility certification governs all skin-contact segments, with FDA device listing required for RFID-embedded variants. Antimicrobial claims trigger additional EPA registration for silver-ion and copper-alloy substrates.
- Plastic Bands:Thermoplastic elastomer and PVC substrates dominate acute-care volume through compatibility with thermal-transfer printers. United States hospital systems standardize on these for single-use disposability, though REACH phthalate restrictions are accelerating TPU substitution in European procurement.
- Fabric Bands:Woven polyester and nylon constructions withstand industrial laundering cycles exceeding 200 washes. Skilled nursing facilities in the United States and residential care operators in Germany specify these for multi-day wear durability, reducing per-patient consumable spend.
- Metal Bands:Stainless steel and aluminum alloys serve forensic and psychiatric applications requiring tamper resistance. Limited healthcare penetration outside court-ordered medical evaluations and high-security psychiatric units.
- RFID Bands:UHF inlays with EPC Gen2v2 encryption command premium positioning for real-time location tracking deployments.
Leading the category by volume: Plastic Bands. Growing fastest: RFID Bands.
Application:
Procurement scale and replacement frequency vary dramatically across care settings, with Joint Commission accreditation status determining mandatory wristband protocols.
- Hospitals:Acute-care facilities generate the highest per-bed consumption through admission-discharge turnover and compliance-driven replacement of worn or unscannable bands. RFID infrastructure investments by United States academic medical centers are compressing pharmacy verification labor and bed turnover delays.
- Clinics:Ambulatory surgery centers and specialty clinics deploy lower-cost barcode bands for same-day procedures. California and Texas outpatient networks prioritize direct-thermal formats to eliminate ribbon inventory complexity.
- Residential Care:Long-term care operators underpenetrate in automated identification, creating expansion opportunity for washable fabric RFID solutions.
- Special Events:Mass-gathering medical tents and disaster response deployments use color-coded disposable bands for triage categorization.
Dominating procurement value: Hospitals. Expanding most quickly: Residential Care.
Technology:
Data capture modality determines hardware compatibility, integration engineering burden, and error-reduction efficacy at the point of care.
- Barcode:Code 128 and PDF417 symbologies remain the installed base standard across United States acute care, with scanner infrastructure amortized over decade-long depreciation cycles. Legacy printer lock-in slows migration to newer formats despite RFID's superior read reliability.
- RFID:Passive UHF inlays automate patient flow tracking in perioperative suites and emergency departments. Cleveland Clinic and Mayo Clinic deployments demonstrate specimen mislabel reduction and pharmacy verification compression.
- QR Code:Two-dimensional matrix symbols enable smartphone-based verification for home health and remote patient monitoring workflows.
- Color-Coding:Visual risk stratification (allergy, fall risk, DNR status) supplements scannable identifiers without hardware dependency.
Highest installed base: Barcode. Steepest expansion trajectory: RFID.
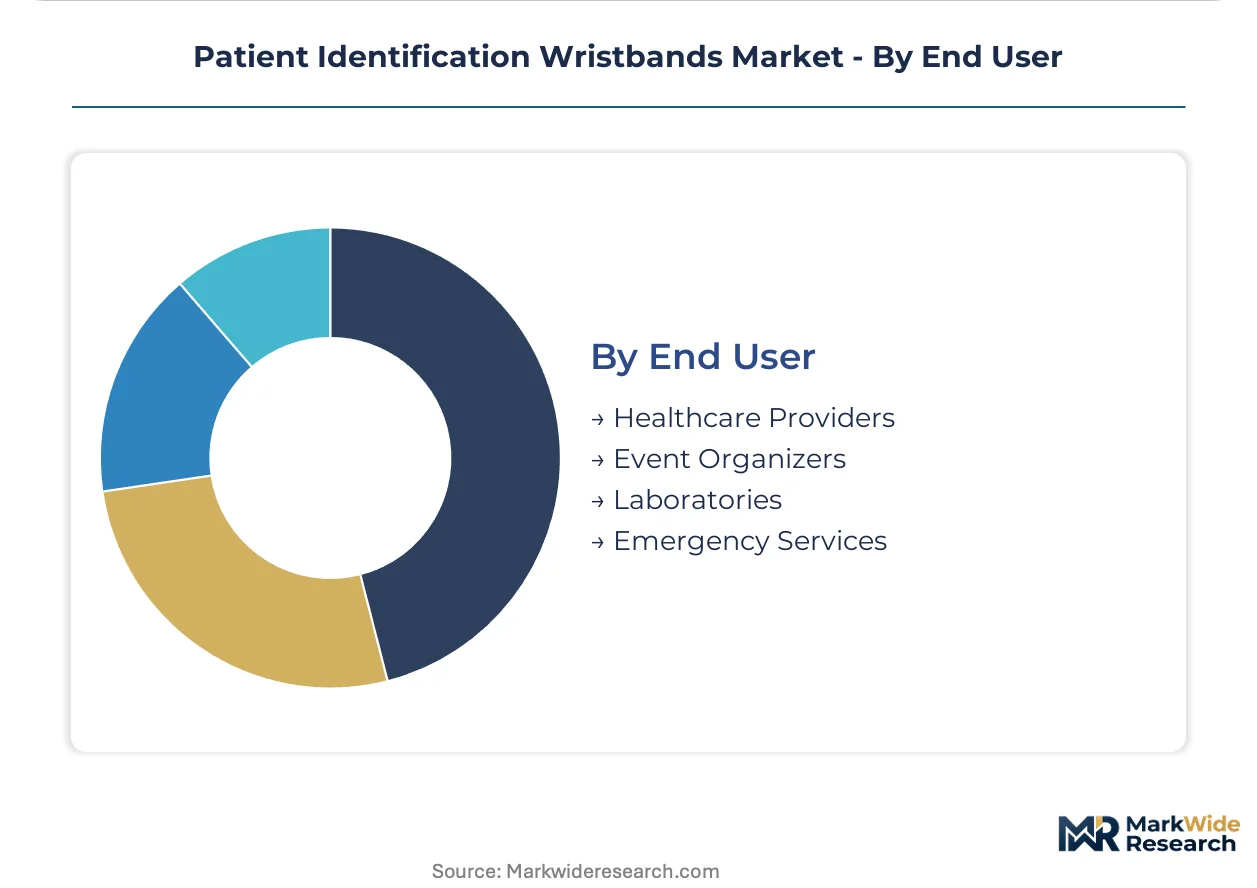
End User:
Purchasing authority and technical specification complexity diverge across stakeholder types, with healthcare providers demanding EHR integration and emergency services prioritizing field durability.
- Healthcare Providers:Integrated delivery networks consolidate identification consumables under multi-year enterprise agreements bundling bands, labels, ribbons, and software. United States GPO contract penetration exceeds seventy percent of acute-care beds, compressing vendor margins.
- Event Organizers:Music festivals and sporting venues deploy single-use color-coded bands for medical tent triage, with specifications driven by fire code and crowd safety consultants rather than clinical standards.
- Laboratories:Specimen collection networks require wristband-to-tube barcode reconciliation, with phlebotomy workflow integration determining format selection.
- Emergency Services:EMS agencies and disaster response teams specify waterproof, tear-resistant substrates for field conditions.
Concentrating procurement authority: Healthcare Providers. Gaining share fastest: Event Organizers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antimicrobial plastic resin production clusters in the US Gulf Coast and German Rhine-Ruhr corridor anchor patient identification wristband supply chains. Hospital procurement consolidation across North America and EU MDR compliance deadlines in Europe reshape regional demand patterns.
United States
Integrated delivery networks in Texas and California drive barcode-to-RFID infrastructure replacement cycles. Joint Commission accreditation audits mandate two-identifier compliance across 6,000 acute-care facilities. The Mayo Clinic in Minnesota deploys real-time location tracking wristbands across perioperative suites.
Germany
REACH SVHC disclosure thresholds accelerate TPU substitution for phthalate-containing PVC substrates. University hospitals in Bavaria pilot washable fabric RFID bands for long-term care integration. The Rhine-Ruhr industrial corridor hosts extrusion compound reformulation for neonatal-grade materials.
Japan
PMDA medical device data system guidance influences RFID interoperability standards with electronic health record platforms. METI subsidizes antimicrobial material R&D for infection-control-sensitive units. Osaka-based manufacturers supply hypoallergenic adhesives for pediatric circumference ranges.
United Kingdom
NHS procurement frameworks consolidate identification consumables under single-source distribution agreements. London teaching hospitals deploy color-coded risk stratification bands for allergy and fall-risk protocols. The Midlands manufacturing belt produces thermal-transfer compatible substrates for acute-care disposability.
India
CDSCO medical device rules drive barcode wristband adoption in tier-1 hospital chains across Maharashtra and Karnataka. Ayushman Bharat insurance expansion creates volume demand for low-cost plastic bands in secondary cities. Delhi-NCR distributors supply government hospital tenders with direct-thermal formats.
Patient Identification Wristbands Market Vendor Landscape
Global majors compete with regional champions across identification technology stacks and material science capabilities. The market exhibits tiered consolidation with full-stack vendors capturing integrated delivery network contracts while specialists defend niche pediatric and antimicrobial segments. Three archetypes dominate: barcode printing ecosystem providers, direct-distribution healthcare specialists, and materials-science innovators. Competitive dynamics center on multi-year enterprise bundling and antimicrobial substrate certification.
Among North American healthcare technology providers, Zebra Technologies Corporation and PDC Healthcare exemplify contrasting scale positions. Zebra anchors the barcode printing ecosystem tier with hardware-software-consumables integration. PDC Healthcare occupies a position within direct-distribution specialists serving integrated delivery networks. Brady Worldwide, Inc. represents the materials-science archetype with specialty substrate capabilities. SATO Holdings Corporation and IdentiSys Inc. sit within regional fabrication tiers addressing procurement fragmentation outside consolidated health systems.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| PDC Healthcare |
| Brady Worldwide, Inc. |
| McKesson Medical-Surgical Inc. |
| Thermo Fisher Scientific Inc. |
| SATO Holdings Corporation |
| IdentiSys Inc. |
| Compass Health Brands |
| Typenex Medical, LLC |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in antimicrobial substrate manufacturing anchor supply-side discipline across the United States and German manufacturing belts, translating ISO 10993 certification timelines into pricing power that resists commoditization pressure from bulk plastic converters.
Pricing Analysis
Warranty and service bundling separates full-stack vendors from consumables-only suppliers, with multi-year enterprise contracts covering hardware, software, bands, and technical support commanding premium positioning against transactional per-unit sales. Three-tier pricing structure across premium RFID-enabled, standard thermal-transfer barcode, and economy direct-thermal bands reflects certification grade and integration complexity. Pricing pressure stems from group purchasing organization consolidation compressing vendor margins in United States acute-care procurement. Ambulatory surgery centers and outpatient clinics exhibit highest price sensitivity, while academic medical centers prioritize error-reduction efficacy over per-unit cost.
Supply Chain Analysis
ISO 10993 biocompatibility certification and EPA antimicrobial registration gate entry for substrate suppliers, extending product development cycles and concentrating qualified production in United States Gulf Coast and German Rhine-Ruhr chemical corridors. UHF RFID inlay production draws from Taiwan and South Korean semiconductor foundries, while thermoplastic elastomer compounding rests on Gulf Coast petrochemical feedstocks. Single-source vulnerability in East Asian chip fabrication exposes buyers to allocation volatility during capacity crunches. Distribution runs through group purchasing organization contracts to integrated delivery networks, displacing fragmented local medical-surgical distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
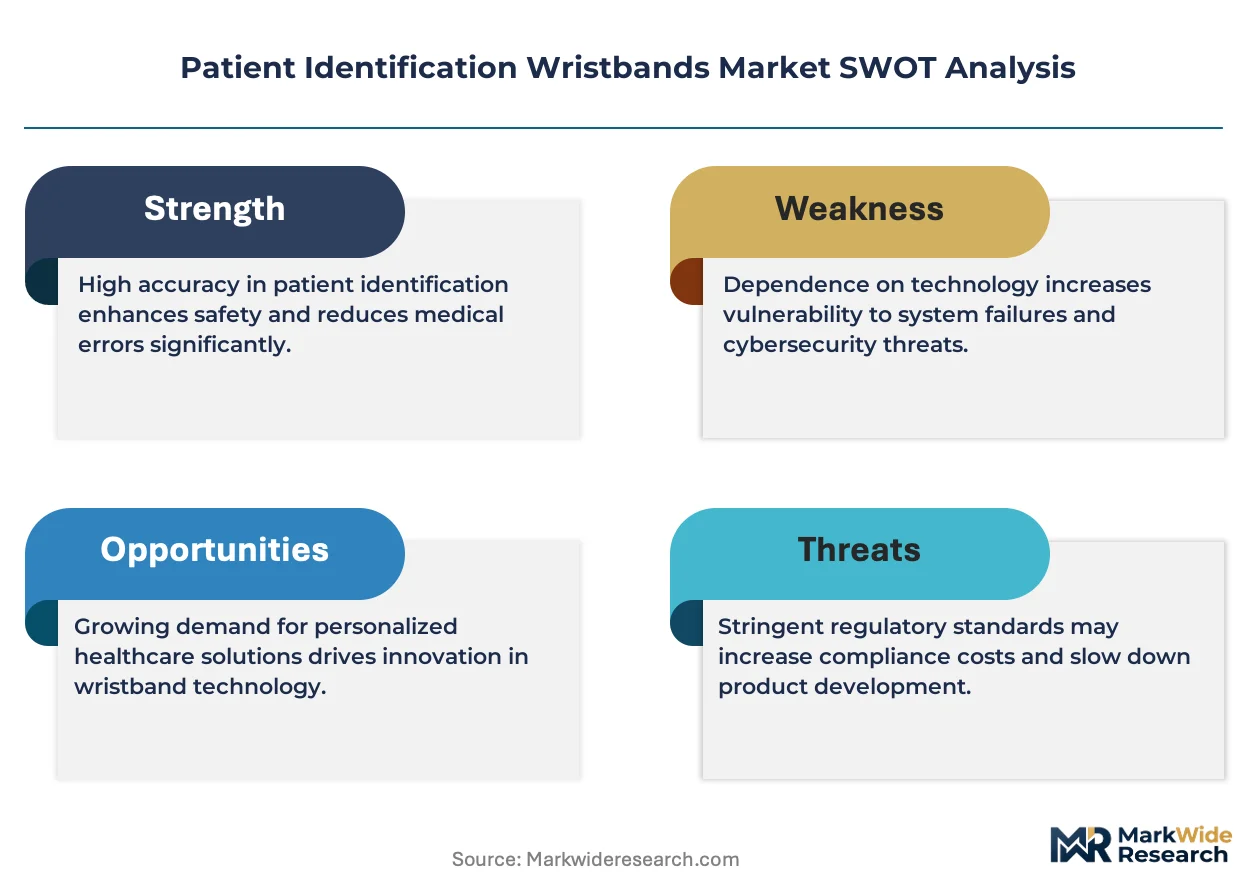
The Patient Identification Wristbands Market functions as a cost-of-compliance arena where Joint Commission two-identifier mandates and ISO 10993 certification requirements erect barrier-to-entry moats favoring incumbents with established regulatory dossiers and hospital system relationships.
For Market Incumbents: Deploy antimicrobial substrate R&D partnerships with CDC-aligned infection control protocols to differentiate against commodity plastic converters. Consolidate position by acquiring regional fabric band specialists with established long-term care distribution in Germany and Japan. Lock in integrated delivery network contracts through hardware-software-consumables bundling before RFID infrastructure replacement cycles peak. For New Entrants and Emerging Players: Capture underpenetrated skilled nursing facility and assisted-living segments in the United States and Germany with washable fabric RFID solutions that reduce per-patient consumable spend against adhesive disposables. Target pediatric and neonatal specialization where hypoallergenic adhesive requirements and size-adjustable designs resist commoditization. Pursue go-to-market partnerships with long-term care equipment distributors rather than competing for GPO-contracted acute-care beds. For Investors and Strategic Acquirers: Distressed-cycle entries favor materials-science innovators with EPA-registered antimicrobial substrates and established ISO 10993 testing relationships in the United States and Germany. Five-to-ten year viability hinges on RFID infrastructure replacement momentum and EHR interoperability consolidation. Monitor FDA guidance on medical device data systems as inflection signal for RFID band interoperability standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Substrate Certification | EPA registration and ISO 10993 compliance unlock premium positioning in infection-control-sensitive units. |
| RFID Infrastructure Partnership | Mayo Clinic and Cleveland Clinic deployments validate real-time location tracking efficacy for perioperative workflows. |
| Long-Term Care Distribution Expansion | Skilled nursing facilities in Germany and the United States underpenetrate in automated identification systems. |
| Hardware-Software-Consumables Bundling | Zebra Technologies and PDC Healthcare enterprise contracts displace fragmented procurement through GPO consolidation. |
| Pediatric Specialization Development | Hypoallergenic adhesives and size-adjustable bands address unique skin-sensitivity requirements in neonatal populations. |
Methodological Framework
Multi-period observation of Joint Commission compliance audit frequencies, RFID infrastructure deployment announcements, and antimicrobial material patent filings anchored the trend analysis, supplemented by interviews with hospital supply chain directors, GPO contracts managers, biomedical engineers, and antimicrobial substrate R&D leads. Secondary validation drew from FDA device listings, EPA antimicrobial registrations, hospital procurement databases, GPO contract disclosures, and SEC filings of publicly traded identification technology vendors. Bottom-up unit volume modeling across material substrates and care settings triangulated against top-down market sizing through healthcare expenditure allocation analysis.
Segment-weighting across plastic, fabric, metal, and RFID band product types combined with hospital, clinic, residential care, and special event application splits shaped the analytical framework across the projection horizon. Technology segmentation incorporated barcode, RFID, QR code, and color-coding data capture modalities alongside healthcare provider, event organizer, laboratory, and emergency services end-user categories. CAGRs were derived from replacement cycle analysis, infrastructure investment trajectories, and regulatory compliance mandate timelines without year-specific anchoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor allocation volatility in East Asian foundries and EHR interoperability standardization pace. Forecasts reflect assumptions regarding Joint Commission accreditation persistence, REACH phthalate restriction enforcement, and RFID infrastructure replacement momentum. A model refresh is warranted upon material change in FDA medical device data systems guidance or EU MDR unique device identifier implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Abdominal Pads Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Physical Therapy Supplies Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Global Patient Lateral Transfer Market
Patient Care Supplies
Self Inflating Bag Market
Patient Care Supplies
Reusable Incontinence Products Market
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Global Incontinence and Ostomy Care Product Market
Patient Care Supplies
Ice Packs for Pain Market