
 Sales Performance Management (SPM) Software Market | 2026-2036
Sales Performance Management (SPM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Performance Management (SPM) Software Market Analytics
Mid-market technology firms are unwinding reliance on spreadsheet-based compensation workflows, creating fresh demand for automated SPM platforms. Xactly anchors its position through deep specialization in enterprise commission management across complex sales hierarchies. Salesforce leverages native CRM integration to control distribution of performance data across cloud ecosystems. Varicent differentiates through advanced AI-driven forecasting modules that reduce quota-setting cycles.
Sales Performance Management (SPM) Software comprises integrated applications that automate sales compensation calculation, quota allocation, territory mapping, and predictive analytics through rules engines and machine learning algorithms operating on structured CRM and ERP data feeds. The primary commercial purpose centers on reducing commission disputes, shortening compensation cycles, and improving seller productivity through transparent incentive design. Cloud-based deployment now leads solution uptake among end users seeking elastic scalability and reduced IT overhead, while on-premise installations retain footholds in government and highly regulated sectors where data residency requirements constrain SaaS adoption. Commission management captures the deepest margin pools as implementation complexity and recurring calibration services extend customer lifetime value.
The US SEC scrutinizes sales compensation disclosures under evolving executive pay transparency rules, pressuring public enterprises toward auditable SPM systems. European GDPR and CSRD frameworks constrain how performance data traverses cloud boundaries, shaping vendor architecture decisions for EU deployments. ISO 27001 certification has become a baseline procurement filter across financial services and healthcare buyers evaluating platform security posture. Stakeholders must weigh integration depth against compliance adaptability when selecting systems destined for multi-jurisdictional sales operations.
Market Dynamics
Cloud-native architecture is displacing legacy on-premise SPM deployments as financial services and pharmaceutical enterprises prioritize elastic scalability and real-time data synchronization across distributed sales teams.
Growth Catalysts
- SEC disclosure mandates:Public enterprises face intensifying scrutiny under executive compensation transparency rules, forcing adoption of auditable commission calculation systems.
- Life sciences compliance:Pharmaceutical sales organizations require automated incentive structures that align with evolving healthcare fraud and abuse regulations.
- AI-driven forecasting:Machine learning algorithms are compressing quota-setting cycles from quarterly to continuous calibration, improving seller productivity metrics.
Market Restraints
- Data residency requirements:GDPR and national sovereignty frameworks constrain cross-border cloud data flows, fragmenting vendor architecture decisions.
- Integration complexity:Legacy ERP systems in manufacturing and government sectors resist seamless API connectivity with modern SPM platforms.
- Specialized talent scarcity:Shortage of professionals combining sales operations expertise with machine learning implementation skills inflates deployment costs.
Strategic Opportunities
- Mid-market penetration:Technology firms with 500-5,000 employees remain underpenetrated, presenting white space for automated compensation workflows.
- Embedded analytics convergence:Integration of SPM with business intelligence platforms creates unified performance visibility for revenue operations teams.
- ISO 27001 certification:Baseline security posture requirements in healthcare and financial services favor vendors with established compliance frameworks.
Industry Challenges
- Legacy system entrenchment:Spreadsheet-based compensation processes persist in established enterprises, creating change management friction during platform transitions.
- Multi-jurisdictional calibration:Sales organizations operating across state and national boundaries face complex territory mapping and currency conversion requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Performance Management (SPM) Software Market |
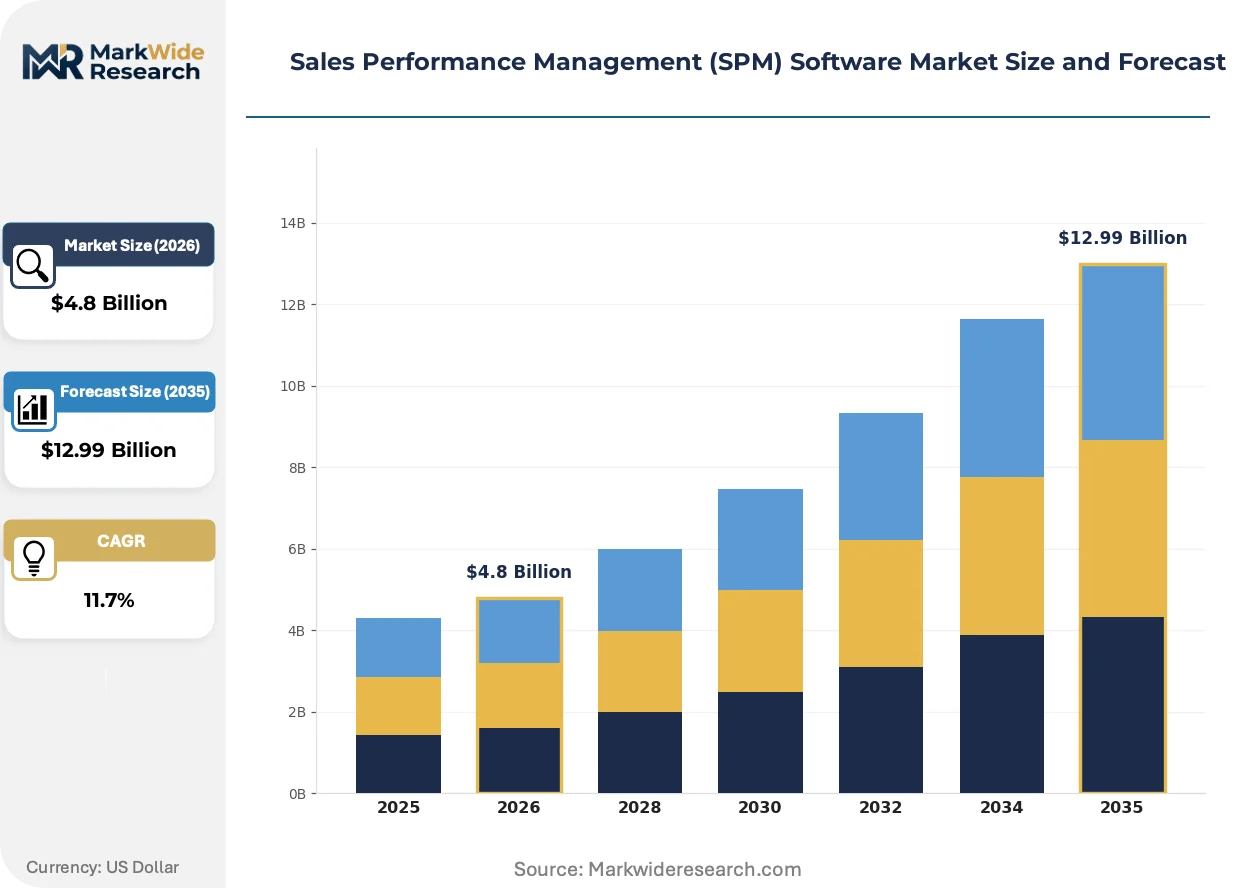
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services End User: SMBs, Large Enterprises, Enterprises, Government Solution: Sales Analytics, Commission Management, Performance Tracking, Forecasting Sales Channel: Direct Sales, Channel Partners, Resellers, Consultants |
| Companies Covered | Spiff, Performio, Xactly, Qobra, Everstage, Varicent, Salesforce, Anaplan, CaptivateIQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Performance Management (SPM) Software Market Evolving Landscape
Real-time performance visualization is reshaping how sales leaders allocate incentives, compressing decision cycles from monthly reviews to continuous optimization. Three developments dominate vendor roadmaps and buyer priorities.
Edge computing infrastructure is miniaturizing data processing for field sales teams. Pharmaceutical and medical device representatives now access commission calculations on mobile devices without cloud latency. This architecture is miniaturizing the gap between transaction closure and incentive visibility, reducing dispute resolution cycles.
CSRD sustainability reporting requirements in Europe are mandating disclosure of sales force diversity and pay equity metrics. SPM vendors must embed ESG tracking modules to capture gender and ethnicity data alongside performance indicators. Financial services firms with EU operations are prioritizing platforms with native CSRD alignment.
Subscription pricing models are displacing perpetual licenses in mid-market procurement. Revenue operations teams prefer consumption-based contracts tied to active seller counts rather than upfront enterprise commitments. This shift is most visible among SaaS-native technology companies seeking operational flexibility during hiring freezes.
Sales Performance Management (SPM) Software Market Segmentation
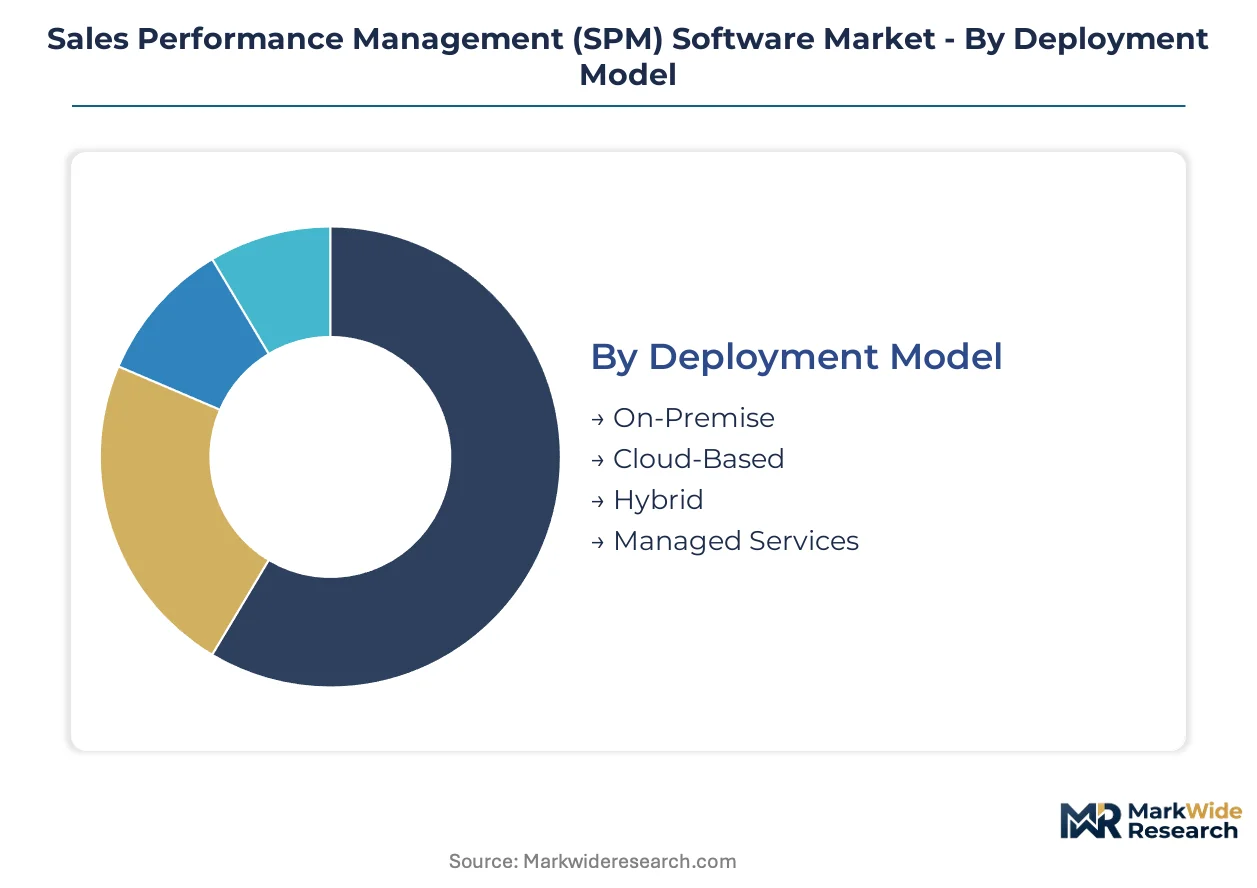
SPM software procurement patterns diverge sharply across deployment preferences and organizational scale. Cloud-native platforms now dominate mid-market technology firms while regulated sectors sustain on-premise demand. Sales channel configuration directly shapes how vendors allocate R&D resources and pricing flexibility.
Deployment Model:
Channel economics favor cloud-based deployments through direct vendor relationships and managed service intermediaries, while on-premise sales flow primarily through systems integrators with compliance expertise.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic scalability with API-first integration into Salesforce and Microsoft Dynamics ecosystems. Financial services firms in the United States and Germany are consolidating procurement here to satisfy real-time synchronization requirements across distributed sales teams.
- On-Premise:Single-tenant installations with localized data storage maintain footholds where data residency mandates constrain SaaS adoption. Government agencies and defense contractors in France and Japan specify these deployments to satisfy national sovereignty frameworks.
- Hybrid:Split architectures partition sensitive compensation data on-premise while routing analytics to cloud infrastructure.
- Managed Services:Third-party hosting arrangements where vendors operate dedicated cloud instances for single clients.
By volume, Cloud-Based leads. By growth pace, Hybrid is gaining share fastest as regulated enterprises seek architectural compromise.
End User:
Customer scale determines implementation complexity and service attach rates, with large enterprises commanding premium consulting while SMBs drive self-service platform adoption.
- Large Enterprises:Organizations exceeding 5,000 employees operate multi-layered sales hierarchies requiring territory mapping across national boundaries. These buyers in the United States and United Kingdom prioritize ISO 27001-certified platforms with dedicated customer success teams.
- SMBs:Firms with 50-500 employees are unwinding spreadsheet workflows for automated commission calculation. Technology sector adoption here is climbing the fastest as venture-backed companies scale revenue operations without proportional headcount expansion.
- Enterprises:Mid-tier organizations between 500-5,000 employees represent white space with fragmented incumbent solutions.
- Government:Public sector procurement emphasizes FedRAMP and equivalent national security certifications.
By revenue concentration, Large Enterprises dominate. By expansion trajectory, SMBs are pulling ahead.
Solution:
Functional module selection correlates with organizational maturity, with basic performance tracking preceding advanced forecasting investments.
- Commission Management:Rules-engine automation of variable compensation calculation with dispute resolution workflows. Life sciences organizations in Switzerland and the United States anchor demand here as healthcare fraud regulations intensify audit requirements.
- Sales Analytics:Business intelligence dashboards visualizing pipeline velocity and win-rate patterns. SaaS companies in Ireland and the Netherlands are expanding fastest as subscription metrics replace transactional sales benchmarks.
- Performance Tracking:Real-time quota attainment monitoring with gamification overlays.
- Forecasting:Machine learning models predicting revenue outcomes from historical CRM data.
By installed base, Commission Management leads. By investment momentum, Forecasting is expanding most quickly.
Sales Channel:
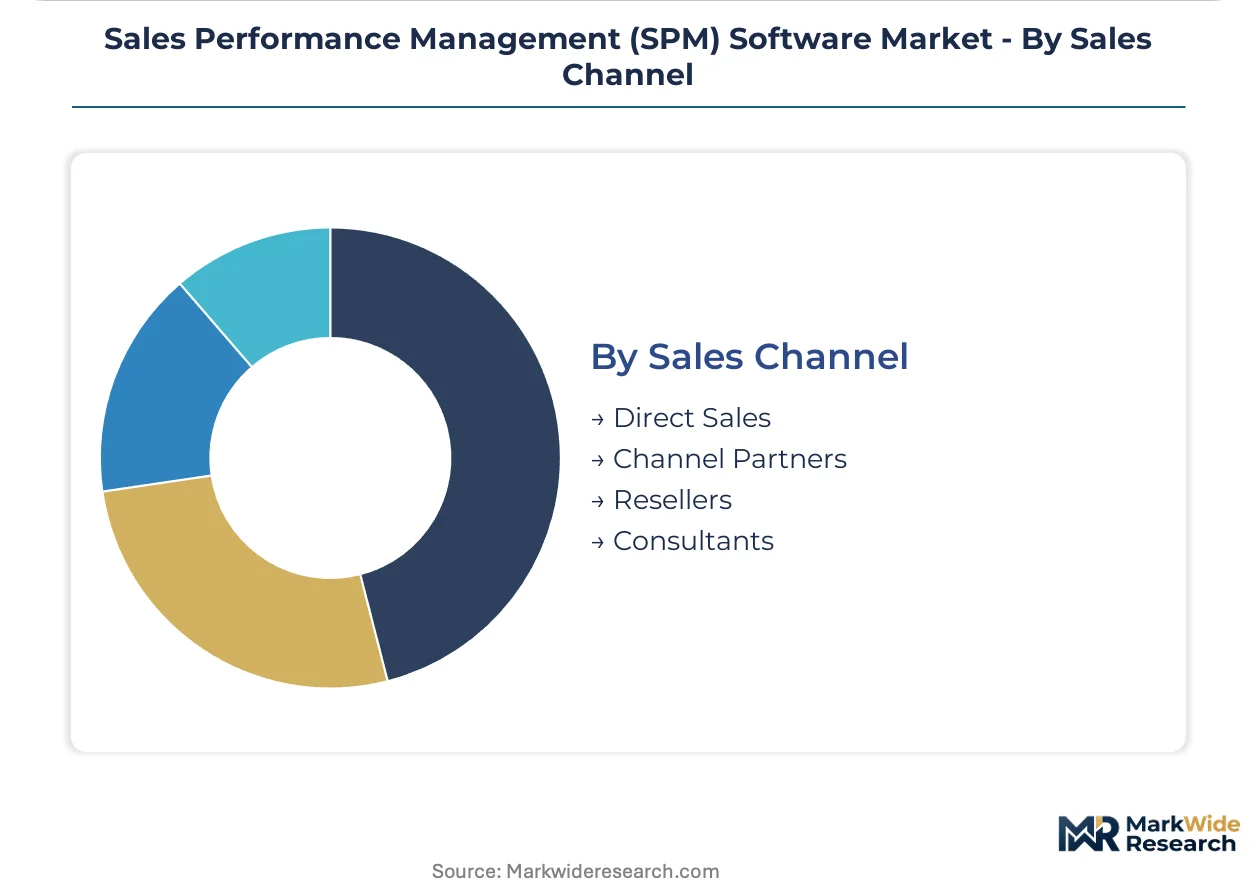
Route-to-market structure fragments by customer sophistication, with direct relationships controlling strategic accounts and partner networks penetrating geographic whitespace.
- Direct Sales:Vendor field organizations managing enterprise procurement cycles with customized demonstrations and security reviews. These teams capture the largest deal values in the United States and Germany where C-suite sponsorship determines platform selection.
- Channel Partners:Value-added resellers bundling SPM with broader CRM transformation services. Regional systems integrators in Australia and Canada are seeing the steepest expansion as mid-market buyers prefer consolidated vendor relationships.
- Resellers:Transaction-focused distributors with limited implementation support.
- Consultants:Advisory-led engagements where strategy firms recommend platform selection.
By transaction volume, Direct Sales leads. By coverage expansion, Channel Partners are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based SPM vendors export cloud-native platforms to enterprise buyers across Germany, United Kingdom, and Japan, where financial services and pharmaceutical sectors drive cross-border procurement corridors.
United States
Enterprise SaaS procurement and SEC disclosure mandates reshape vendor selection criteria for public companies. The SEC scrutinizes sales compensation disclosures under executive pay transparency rules, pressuring enterprises toward auditable systems. Financial services clusters in New York and San Francisco intensify demand for real-time performance tracking.
Germany
Cloud migration across financial services firms accelerates demand for elastic scalability and data synchronization. GDPR and national sovereignty frameworks constrain cross-border cloud data flows, fragmenting vendor architecture decisions. Frankfurt's banking sector leads adoption of ISO 27001-certified platforms with localized hosting requirements.
United Kingdom
Life sciences organizations expand adoption of commission management platforms to align incentive structures with compliance requirements. The Financial Conduct Authority oversees disclosure standards for variable compensation in asset management. London's pharmaceutical and fintech clusters drive concentrated procurement of AI-driven forecasting modules.
Switzerland
Pharmaceutical sales organizations require automated incentive structures that align with healthcare fraud and abuse regulations. Swissmedic oversight combines with EU regulatory alignment to shape platform requirements. Basel's pharmaceutical headquarters anchor regional demand for complex sales hierarchy management.
Japan
Manufacturing and technology enterprises unwind spreadsheet-based compensation workflows for automated platforms. METI guidelines on digital transformation incentivize cloud adoption among mid-market firms. Tokyo's enterprise software procurement clusters favor vendors with dedicated customer success teams and localized implementation support.
Sales Performance Management (SPM) Software Market Competitive Landscape
Player mix skews toward cloud-native specialists with deep CRM integration capabilities. The vendor base concentrates around three strategic tiers: enterprise incumbents with compliance certifications, mid-market challengers with consumption-based pricing, and AI-native entrants with predictive forecasting modules. Dominant competitive moves include strategic partnerships with systems integrators and portfolio diversification into embedded analytics.
Within the enterprise tier, Xactly and Varicent exemplify archetypes of commission management specialization and AI-driven forecasting respectively. Salesforce occupies a position as the native CRM-integrated platform controlling distribution of performance data across cloud ecosystems. Spiff represents the mid-market challenger archetype with automated workflows targeting technology firms scaling revenue operations.
| Leading Market Players |
|---|
| Spiff |
| Performio |
| Xactly |
| Qobra |
| Everstage |
| Varicent |
| Salesforce |
| Anaplan |
| CaptivateIQ |
| Others |
Value Network & Pricing Analysis
ISO 27001 certification gates both vendor qualification and price tier placement in enterprise SPM procurement, with financial services and healthcare buyers filtering out uncertified suppliers while paying premiums for audit-ready platforms. This dual filtering mechanism concentrates pricing power among established cloud-native vendors and fragments the supplier base into compliance-tiered segments.
Pricing Analysis
Cloud-native SPM platforms command 40-60% subscription premiums over legacy on-premise installations, while hybrid architectures occupy a narrowing mid-tier. Three-tier pricing structure across premium, standard, and economy levels reflects ISO certification status, integration depth with Salesforce and Microsoft Dynamics, and dedicated customer success team allocation. Pricing pressure stems from mid-market challengers offering consumption-based contracts tied to active seller counts. Technology firms with 500-5,000 employees exhibit highest price sensitivity due to venture capital constraints, while Fortune 500 pharmaceutical enterprises prioritize compliance over cost.
Supply Chain Analysis
Implementation lead times for enterprise SPM deployments now stretch 8-14 months due to specialized talent scarcity in sales operations and machine learning engineering. Software development concentrates in the United States, Ireland, and India, with cloud infrastructure provisioning anchored in AWS, Azure, and Google Cloud data centers across Frankfurt, London, and Tokyo. The supply chain draws from CRM platform ecosystems and ERP integration specialists, with single-source vulnerability residing in Salesforce API dependency. Distribution runs through direct vendor field organizations for strategic accounts and value-added resellers for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
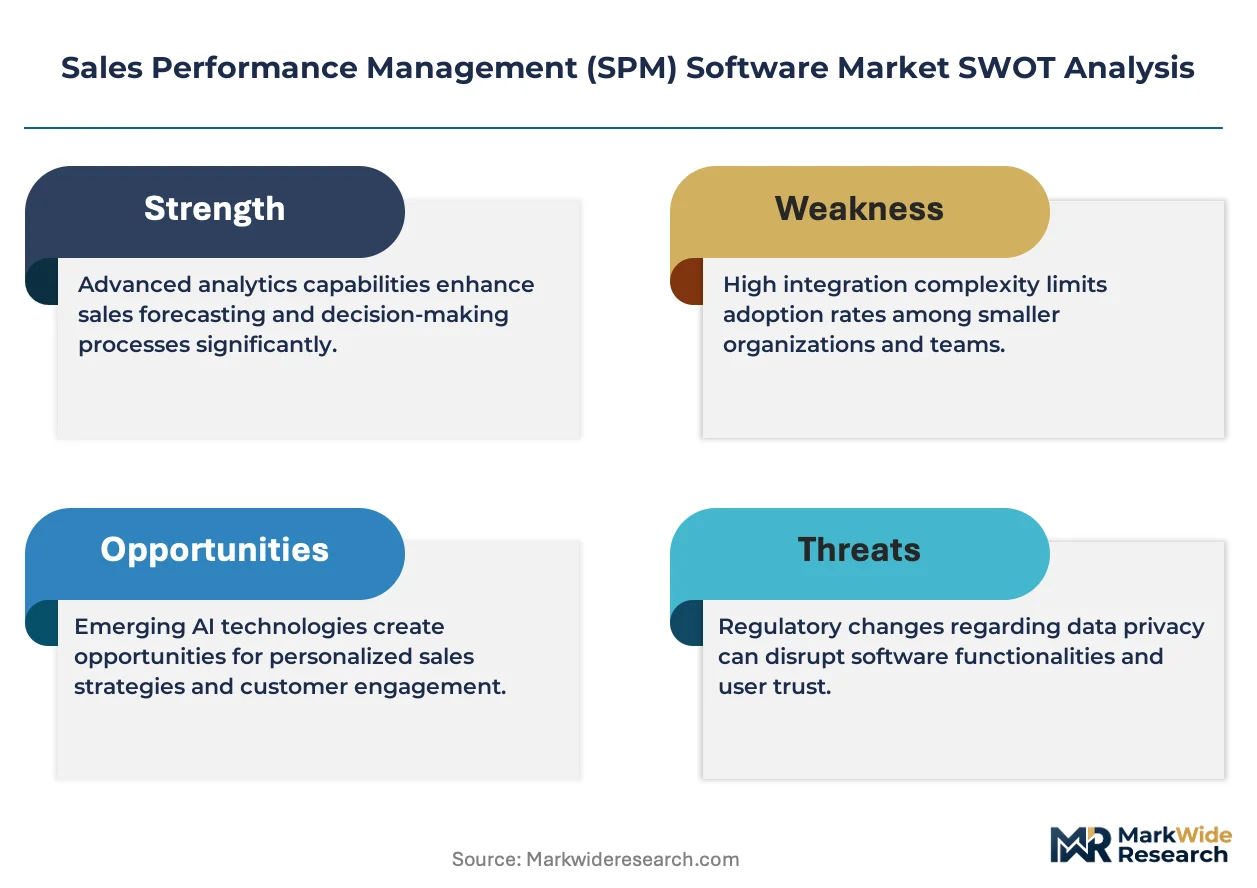
Scarcity of professionals bridging sales operations expertise with machine learning implementation skills constrains platform deployment velocity and inflates service attach rates, creating asymmetric returns for vendors who cultivate this hybrid capability.
For Market Incumbents: Fortify competitive moats by deepening ISO 27001 certification portfolios and embedding AI-driven forecasting modules that compress quota-setting cycles. Cloud-native challengers with consumption-based pricing threaten enterprise margin structures. Prioritize vertical integration into specialized implementation services to capture recurring calibration revenue and extend customer lifetime value. For New Entrants and Emerging Players: Differentiate on edge computing architecture for pharmaceutical field sales teams, where mobile commission calculation without cloud latency remains underserved. Target mid-market technology firms with 500-5,000 employees in Japan and Germany, where spreadsheet unwinding accelerates but incumbent penetration remains fragmented. Pursue consultant-led advisory engagements to influence platform selection before procurement cycles formalize. For Investors and Strategic Acquirers: CSRD sustainability reporting requirements in Europe reshape the acquisition landscape by mandating ESG tracking modules for sales force diversity and pay equity metrics. Long-term viability favors vendors with native compliance alignment across GDPR, SEC disclosure mandates, and emerging AI governance frameworks. Monitor ISO 27001 certification velocity as the signal indicating which mid-market challengers can scale into regulated financial services and healthcare accounts.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Forecasting Module Development | Machine learning algorithms compress quota-setting cycles from quarterly to continuous calibration for pharmaceutical sales organizations. |
| Edge Computing Infrastructure Deployment | Miniaturized data processing eliminates cloud latency for medical device representatives accessing commission calculations on mobile devices. |
| CSRD Compliance Integration | Native ESG tracking modules capture gender and ethnicity data alongside performance indicators for EU financial services firms. |
| Consumption-Based Pricing Launch | Revenue operations teams at SaaS-native technology companies prefer contracts tied to active seller counts over upfront enterprise commitments. |
| ISO 27001 Certification Expansion | Baseline security posture requirements in healthcare and financial services filter procurement toward established compliance frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with revenue operations executives, sales compensation administrators, CRM integration specialists, and cloud procurement officers. Secondary validation drew from SEC disclosure filings, Salesforce ecosystem partnership directories, GDPR implementation case studies, and ISO 27001 certification registries. Bottom-up sizing of vendor-reported customer counts and top-down triangulation against enterprise software spending estimates anchored value projections.
Across the analysis window, forecasts model deployment mode transitions, organizational scale tier migrations, and solution module adoption sequences. Segmentation dimensions include cloud-native versus on-premise architecture, employee count thresholds, and integration complexity with existing ERP systems. CAGRs derive from logistic diffusion curves fitted to historical SaaS penetration patterns and regulatory compliance deadline clustering.
Material uncertainties — SEC rulemaking timelines, GDPR enforcement intensity, and AI governance framework emergence — sit outside the modeled envelope. Forecasts reflect assumptions about cloud migration velocity and mid-market buyer education cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Lead Capture Software Market
Software & Services
Proxy Services and Software Market
Software & Services
Mainframe Software Market
Software & Services
Hotel Management Software Market
Software & Services
United Kingdom IT Services Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Salon Booking Software Market
Software & Services
Europe Contract Lifecycle Management Software Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
Media Editing App Market
Software & Services
Global Intranet Software Market
Software & Services
Employee Advocacy Software Market
Software & Services
Productivity Software Publishing Market
Software & Services
Photo Editor App Market
Software & Services
Content Distribution Software Market