
 Application Development and Modernization (ADM) Market | 2026-2036
Application Development and Modernization (ADM) Market Size, Share, and Industry Trends Forecast 2026-2036
Application Development and Modernization (ADM) Market Outlook
Healthcare IT is expanding its share of ADM spending as providers replace monolithic electronic health record systems with modular architectures. Accenture leverages its multi-cloud certification breadth to anchor large hospital network transformations. Grid Dynamics competes on price-performance for real-time analytics pipelines in pharmaceutical supply chains. SoftServe specializes in FHIR-compliant API layers that bridge legacy HL7v2 infrastructure with modern patient portals.
Application Development and Modernization encompasses the engineering, refactoring, and migration of software applications across cloud-native, containerized, and distributed architectures, typically employing CI/CD pipelines, infrastructure-as-code, and automated testing protocols to ensure functional parity during transition. Its primary commercial purpose is to reduce technical debt while enabling elastic scalability and interoperability across enterprise technology estates. Legacy Modernization commands the largest current revenue pool among service types, though Cloud Services is capturing the fastest growth as regulated industries overcome data-residency objections. Hybrid Cloud deployment dominates in sectors with jurisdictional data-sovereignty requirements, while Public Cloud leads among technology startups and digital-native SMEs seeking zero-capital-expenditure scaling.
FDA 21 CFR Part 11 compliance obligations shape validation requirements for ADM projects in US life sciences, while the EU AI Act imposes conformity assessments on automated decision systems that modernized applications must accommodate. HIPAA security rule updates in the United States and GDPR Article 32 technical measures in Europe both mandate encryption-by-default and audit-log immutability that influence platform selection. Stakeholders should monitor how NIST AI Risk Management Framework integration into federal procurement criteria will reshape vendor qualification standards for government modernization contracts.
Market Dynamics
Container orchestration platforms and infrastructure-as-code tooling are compressing modernization timelines while forcing legacy system integrators to retool delivery models or cede ground to cloud-native specialists.
Growth Catalysts
- EU AI Act conformity assessments:Automated decision systems in financial services must undergo documented validation, triggering wholesale core banking replacements across Frankfurt and Paris banking clusters.
- CSRD data-traceability mandates:German industrial conglomerates face audit requirements that mainframe estates cannot satisfy, accelerating mainframe-to-cloud migration contracts.
- FHIR interoperability standards:Healthcare providers in the United States replace HL7v2 message formats with RESTful APIs to meet CMS patient-access rules.
Market Restraints
- Specialized mainframe skill scarcity:COBOL and assembler expertise concentrates among aging workforces in the United States and Germany, inflating contract rates for legacy assessment phases.
- Multi-cloud certification costs:Vendor-specific competency requirements from AWS, Azure, and GCP force service providers to maintain redundant training pipelines.
- Data-residency jurisdictional fragmentation:Divergent sovereignty rules across EU member states complicate single-architecture deployments for cross-border enterprises.
Strategic Opportunities
- India's PLI scheme for IT hardware:Domestic data-center infrastructure incentives position Bangalore and Hyderabad as captive development hubs for European banking modernization programs.
- Edge-to-cloud orchestration convergence:Manufacturing IoT telemetry pipelines in automotive supply chains demand unified management layers that span factory floors and hyperscale regions.
- API monetization platforms:Open banking frameworks in the United Kingdom create revenue streams from previously internal integration layers.
Industry Challenges
- Platform engineering talent gaps:Site reliability engineering and GitOps practices remain scarce in tier-two IT services markets, constraining delivery velocity.
- FDA 21 CFR Part 11 validation timelines:Pharmaceutical ADM projects require documented evidence packages that extend project durations by 40-60 percent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Development and Modernization (ADM) Market |
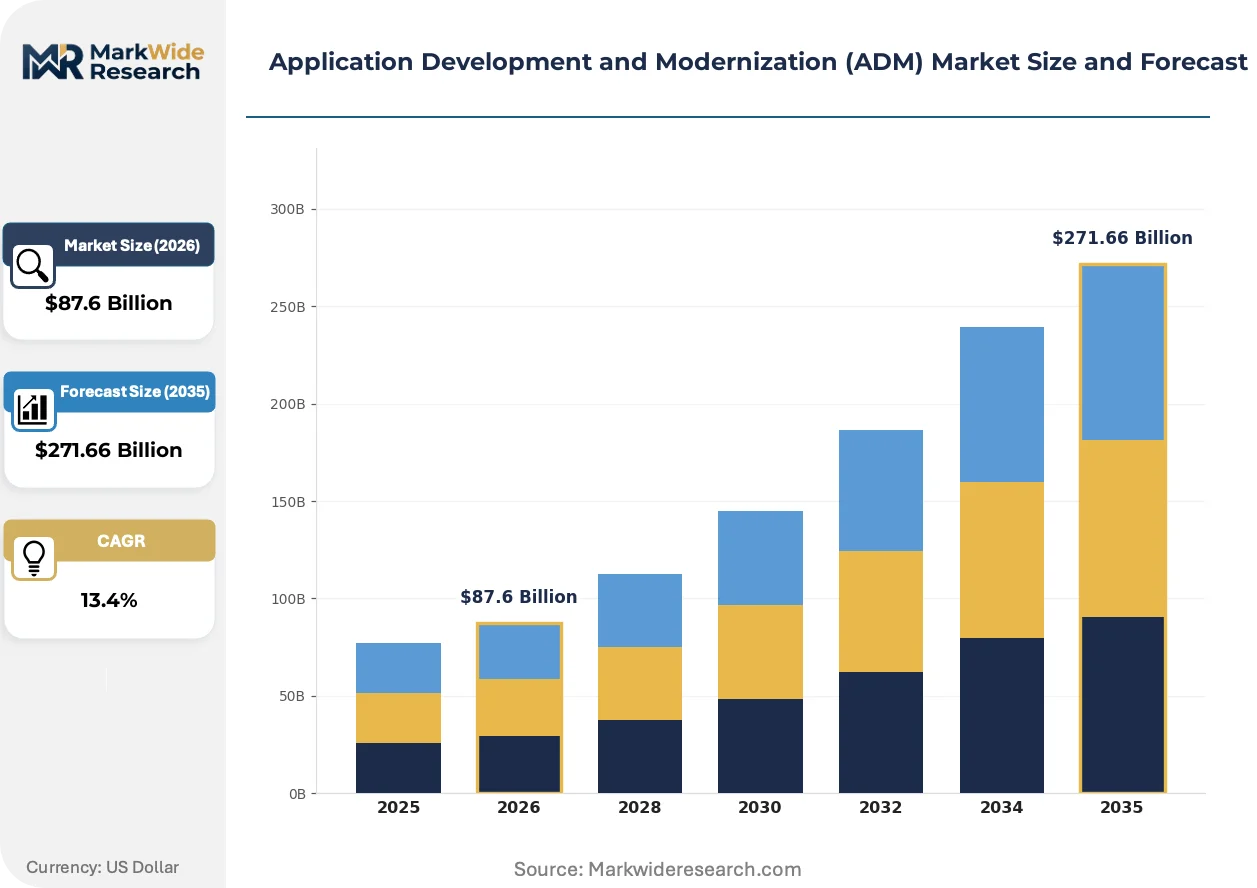
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $271.66 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Mobile Development, DevOps, Legacy Modernization Deployment Model: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud End User: SMEs, Large Enterprises, Government, Nonprofits Technology: Microservices, Containers, Serverless, APIs |
| Companies Covered | SoftServe, Lumitech, Accenture, Rocket Software, BairesDev, Grid Dynamics, Mphasis, WhizzBridge, N-iX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Development and Modernization (ADM) Market Strategic Shifts
Platform engineering disciplines are displacing ad-hoc DevOps implementations, establishing internal developer portals as the control plane for enterprise software factories.
Kubernetes-based container orchestration is consolidating control over heterogeneous runtime environments. Financial services institutions in Germany and the United States are standardizing on GitOps-driven deployment patterns. This convergence is compressing vendor fragmentation and elevating managed service providers with multi-cluster federation capabilities.
The EU AI Act's risk-classification framework imposes conformity documentation on high-risk automated systems. Life sciences and banking verticals must embed algorithmic audit trails into modernized application architectures. French and Dutch regulators are issuing sector-specific guidance faster than implementation standards can stabilize.
Hospital procurement committees now mandate FHIR-native architectures as a threshold qualification for EHR replacement contracts. Systems integrators without SMART-on-FHIR demonstrators are dropping from shortlists. This behavioral shift is most pronounced in United States academic medical centers with CMS innovation funding.
Application Development and Modernization (ADM) Market Segmentation
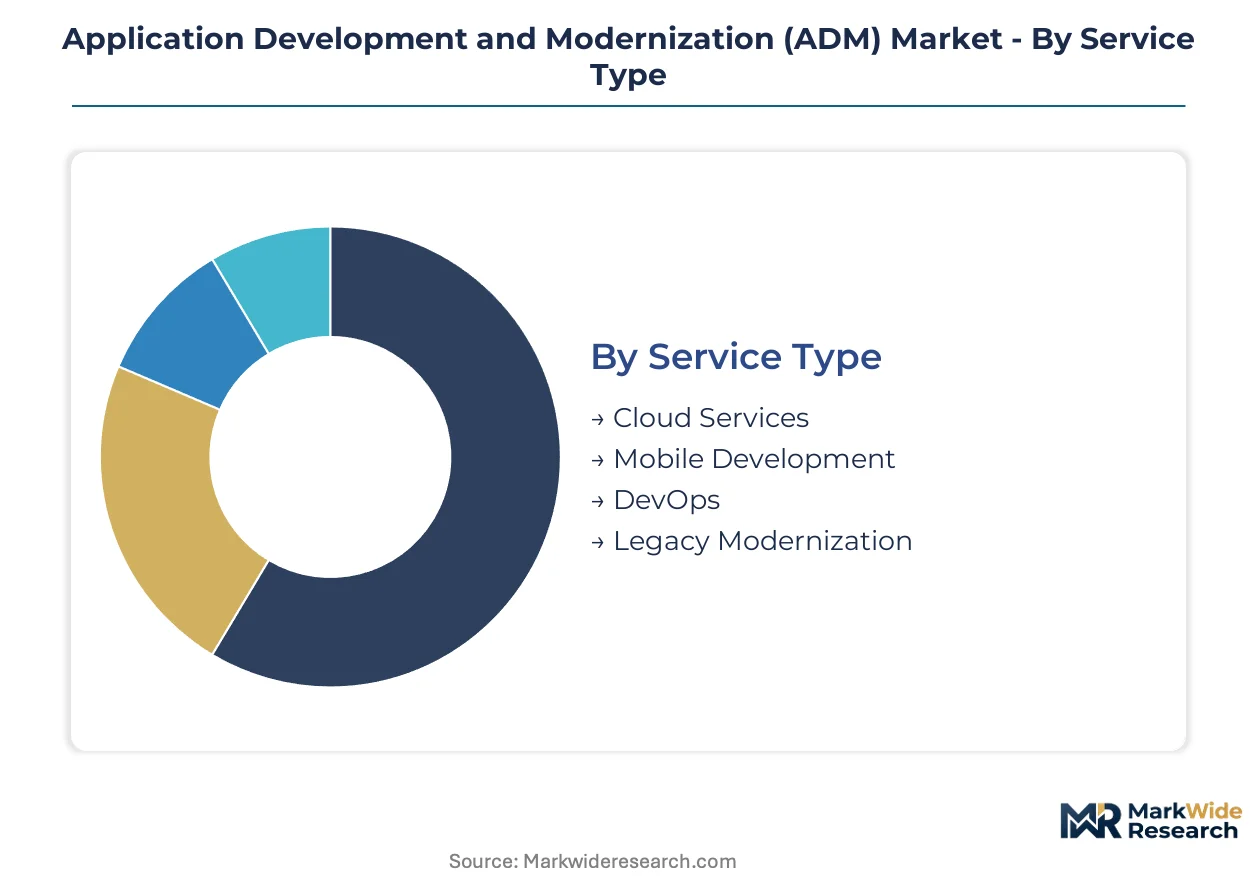
ADM procurement patterns diverge sharply across service maturity, infrastructure sovereignty requirements, and regulatory exposure. Buyers sort into distinct technical and commercial profiles that reshape vendor qualification criteria and contract structures.
Service Type:
Buyers differentiate by technical debt exposure and transformation ambition rather than budget scale alone.
- Legacy Modernization:Mainframe-to-cloud refactoring and COBOL replacement dominate contract values in German industrial and US financial services sectors. German conglomerates facing CSRD data-traceability mandates drive concentrated demand for mainframe estate documentation and phased migration roadmaps.
- Cloud Services:Hyperscale workload migration and managed Kubernetes operations accelerate fastest among pharmaceutical and healthcare providers. FDA 21 CFR Part 11 validation requirements extend project timelines but lock in multi-year managed service relationships.
- DevOps:CI/CD pipeline construction and platform engineering capabilities concentrate in technology startups and digital-native SMEs seeking zero-downtime deployment cadences.
- Mobile Development:Cross-platform application rebuilds and progressive web app conversions serve patient portals and retail banking interfaces requiring SMART-on-FHIR or open banking compliance.
Volume sits with Legacy Modernization; growth tilts toward Cloud Services.
Deployment Model:
Infrastructure location decisions track data residency obligations and latency sensitivity rather than cost optimization alone.
- Hybrid Cloud:Unified management planes span on-premises bare metal and hyperscale regions, mandatory for EU financial institutions navigating GDPR Article 32 encryption requirements and cross-border data fragmentation. German automotive supply chains deploy factory-floor edge nodes federated with AWS or Azure regions.
- Public Cloud:Serverless and container-native workloads concentrate among technology startups and venture-backed SMEs with no legacy capital expenditure base. Zero-trust network architectures and API gateway standardization dominate procurement specifications.
- Private Cloud:Dedicated infrastructure satisfies US healthcare HIPAA security rule mandates and pharmaceutical GxP validation requirements. Academic medical centers with CMS innovation funding specify on-premises FHIR servers with immutable audit logging.
- On-Premises:Air-gapped environments persist in defense contractors and classified government systems requiring NIST 800-171 compliance.
Deployment volume clusters in Hybrid Cloud; steepest expansion trajectory belongs to Public Cloud among digital-native entrants.
End User:
Procurement authority and risk tolerance separate buyer categories more than sector affiliation.
- Large Enterprises:Multi-year transformation programs with dedicated vendor management offices and stage-gate governance. German industrial conglomerates and US hospital networks issue RFPs exceeding 50 million dollars requiring multi-cloud certification breadth.
- SMEs:Project-based engagements with outcome-based pricing and rapid vendor switching. Technology startups prioritize GitOps demonstrators over legacy systems integration credentials.
- Government:Federal procurement criteria integrating NIST AI Risk Management Framework reshape vendor qualification standards. Validation documentation and supply chain attestation dominate technical evaluation.
- Nonprofits:Grant-funded modernization with constrained internal technical capacity, concentrating in healthcare and educational institutions.
Contract value concentrates with Large Enterprises; deal velocity favors SMEs.
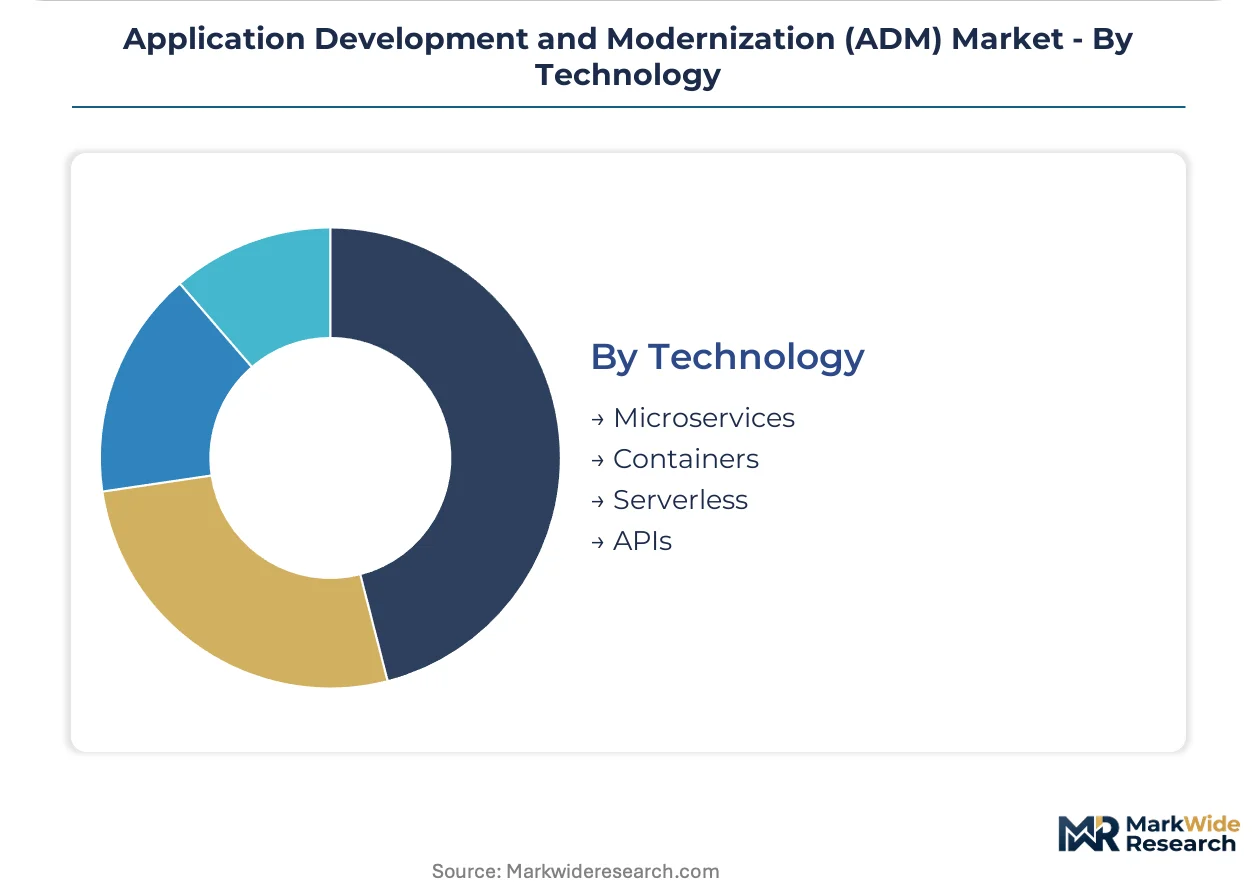
Technology:
Architecture choices determine talent requirements and interoperability boundaries.
- Containers:Kubernetes orchestration platforms consolidate runtime control across heterogeneous environments. Financial services institutions in Germany and the United States standardize on GitOps-driven deployment patterns with multi-cluster federation.
- APIs:FHIR-compliant interface layers bridge legacy HL7v2 infrastructure with modern patient portals. Open banking frameworks in the United Kingdom create revenue streams from previously internal integration layers.
- Microservices:Domain-driven decomposition of monolithic electronic health record systems modularizes upgrade cycles and reduces regression testing scope.
- Serverless:Function-as-a-service adoption concentrates in event-driven pharmaceutical supply chain telemetry and retail banking transaction processing.
Implementation volume favors Containers; API investment expands most quickly with regulatory interoperability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service delivery concentrates in India and Eastern Europe while consumption clusters in Germany and the United States. This geographic split shapes contract structures and compliance requirements across the ADM value chain.
United States
FDA 21 CFR Part 11 validation obligations extend pharmaceutical modernization timelines by 40-60 percent. HIPAA security rule updates mandate encryption-by-default for healthcare ADM procurement. Hospital networks in Boston and the Research Triangle issue RFPs exceeding 50 million dollars for EHR replacement with FHIR-native architectures.
Germany
CSRD data-traceability mandates force industrial conglomerates to document mainframe estate lineage for audit compliance. The EU AI Act imposes conformity assessments on automated decision systems in Frankfurt banking clusters. Automotive supply chains in Baden-Württemberg deploy factory-floor edge nodes federated with hyperscale cloud regions.
United Kingdom
Open banking frameworks create revenue streams from API monetization of previously internal integration layers. The Financial Conduct Authority's operational resilience rules accelerate core banking replacement programs. London fintech clusters standardize on GitOps-driven deployment patterns for multi-cloud workload orchestration.
India
PLI scheme incentives for IT hardware position Bangalore and Hyderabad as captive development hubs for European banking modernization. Domestic data-center infrastructure expansion supports GDPR Article 32 compliance for offshore delivery. Mumbai-based system integrators compete on price-performance for real-time analytics pipelines.
France
ANSM and CNIL sector-specific guidance on EU AI Act implementation outpaces standardization, creating compliance uncertainty for life sciences ADM projects. Paris banking clusters undergo wholesale core system replacements for automated decision system validation. Île-de-France technology consultancies specialize in algorithmic audit trail architecture.
Application Development and Modernization (ADM) Market Competitive Environment
Top-tier vendors anchor multi-year transformation programs with dedicated vendor management offices, while mid-tier specialists compete on price-performance for modular engagements. The vendor base stratifies across three tiers: global systems integrators with multi-cloud certification breadth, regional specialists with vertical domain expertise, and cloud-native boutiques with GitOps delivery capabilities. Dominant competitive moves include strategic partnerships for technology access and portfolio diversification into platform engineering services.
Among US-based global integrators, Accenture occupies a position exemplifying certification breadth across AWS, Azure, and GCP. SoftServe represents the specialist archetype with FHIR-compliant API layer capabilities bridging legacy HL7v2 infrastructure. Grid Dynamics sits within the price-performance tier for real-time analytics pipeline delivery in pharmaceutical supply chains.
| Leading Market Players |
|---|
| SoftServe |
| Lumitech |
| Accenture |
| Rocket Software |
| BairesDev |
| Grid Dynamics |
| Mphasis |
| WhizzBridge |
| N-iX |
| Others |
Value Chain & Pricing Dynamics
COBOL and assembler expertise concentration among aging workforces in the United States and Germany drives labor-cost differentials that separate premium-tier system integrators from price-competitive offshore alternatives. These skill scarcity patterns compress margins for legacy assessment phases while elevating rates for multi-cloud certified delivery teams.
Pricing Analysis
Margin tightening in legacy modernization reflects COBOL specialist scarcity inflating assessment-phase rates by multiples over cloud-native engineering. Project-based pricing dominates mainframe-to-cloud contracts, with differentiation tracking certification breadth across AWS, Azure, and GCP. Cost-down pressure on mid-tier DevOps services accelerates as India's PLI scheme enables Bangalore-based price competition. Hospital networks with CMS innovation funding show lowest price sensitivity; technology startups exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with mainframe skill concentration in the United States and Germany, where assembler expertise retirement curves outpace training pipeline replenishment. Service delivery draws from India, Poland, and Ukraine for cloud-native development, with raw material dependencies spanning proprietary mainframe emulation software, hyperscaler compute credits, and FHIR-compliant middleware licenses. Tariff exposure on IT hardware imports into India threatens cost structures. Distribution runs through direct enterprise sales with multi-year managed service attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering talent scarcity props pricing power for certified delivery organizations while constraining expansion velocity for uncredentialed competitors.
For Market Incumbents: Deepen multi-cloud certification pipelines to defend against cloud-native boutiques capturing GitOps-driven engagements. Anchor hospital network transformations with FHIR-native demonstrators before SMART-on-FHIR mandates harden procurement criteria. Vertical integration into platform engineering services locks in recurring revenue against project-based price erosion. For New Entrants and Emerging Players: EU AI Act conformity assessment requirements in France and Germany open a window for algorithmic audit trail specialists to penetrate banking modernization programs. Target mid-tier pharmaceutical manufacturers facing FDA 21 CFR Part 11 validation bottlenecks with documentation-automation tooling. Lead with outcome-based pricing to bypass incumbent credential barriers. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing vertical domain expertise given CSRD data-traceability mandate acceleration in German industrial conglomerates. Acquisition focus: mid-scale integrators with mainframe documentation capabilities and established hyperscaler partnerships. Monitor NIST AI Risk Management Framework integration into federal procurement criteria as inflection signal for government modernization contract access.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Engineering Service Launch | GitOps-driven internal developer portals capture enterprise software factory contracts from ad-hoc DevOps implementations. |
| Multi-Cloud Certification Expansion | AWS, Azure, and GCP competency breadth qualifies vendors for German conglomerate RFPs exceeding fifty million dollars. |
| FHIR-Compliant API Layer Development | SMART-on-FHIR demonstrators secure hospital procurement committee shortlists for EHR replacement programs. |
| Edge-to-Cloud Orchestration Partnership | Factory-floor Kubernetes federation with hyperscale regions serves automotive supply chain telemetry pipelines. |
| Regulatory Validation Documentation Automation | FDA 21 CFR Part 11 evidence package compression reduces pharmaceutical project timeline extensions by forty to sixty percent. |
Study Parameters
Document review covered hyperscaler capex disclosures, SEC filings from listed systems integrators, and EU regulatory guidance documents, complemented by interviews with CTOs at hospital networks, platform engineering leads at financial services institutions, procurement officers at German industrial conglomerates, and regulatory affairs specialists at pharmaceutical manufacturers. Secondary validation drew from GPO contracts, CMS innovation funding databases, and cloud service provider partner certification records. Bottom-up service line estimates were triangulated against top-down market sizing.
Cross-referencing historical contract value patterns with panel input from vendor management offices anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, deployment model, organization size, vertical regulatory exposure, and regional adoption pattern. CAGRs were derived from growth rate convergence analysis. Industry-specific inputs encompassed mainframe estate documentation pipeline backlogs and FHIR interoperability mandate implementation timelines.
Caveats apply where EU AI Act standardization delays or NIST framework procurement integration timing could materially shift the outlook. Forecasts reflect documented assumptions about skill scarcity persistence and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Patent Management Software Market
Software & Services
Quick Service Restaurants (QSR) IT Market
Software & Services
Casino Management Systems Market
Software & Services
Radio Propagation Software Market
Software & Services
Lending Software Market
Software & Services
Generative Design Software Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market
Software & Services
RIP Color Management Software Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Commercial Drone Software Market
Software & Services
Online Project Management Software Market
Software & Services
Global Kiosk Software Market
Software & Services
Sales Training Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Case Management Software (CMS) Market
Software & Services
Global Email Management Software Market