
 Supply Chain Visibility (SCV) Software Market | 2026-2036
Supply Chain Visibility (SCV) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Supply Chain Visibility (SCV) Software Market Insights
German software engineering capacity is repositioning toward predictive analytics layers within SCV stacks. SAP SE leverages its ERP-installed base to embed visibility modules directly into procurement workflows. Oracle sustains competitive pressure through database-cloud integration that unifies inventory signals across multi-tier supplier networks. FourKites anchors its position in freight-specific real-time tracking, competing on sensor-network density rather than breadth of enterprise applications.
Supply Chain Visibility software encompasses platforms that ingest, correlate, and present multi-source logistics data through standardized APIs, EDI protocols, and IoT telemetry streams to enable proactive exception management across supplier tiers. Its primary commercial purpose is reducing latency between physical supply chain events and managerial response, thereby compressing cash-to-cash cycles and mitigating disruption-induced stockouts. Cloud-based deployments now capture the majority of new bookings, while on-premises installations retain traction among defense contractors and regulated pharmaceutical manufacturers with data-sovereignty requirements. Real-time tracking solutions command premium pricing relative to reporting tools, reflecting the operational value of sub-minute latency in automotive and cold-chain pharmaceutical applications.
FDA traceability mandates under the Food Safety Modernization Act and EU REACH documentation requirements are compelling manufacturers to deploy SCV platforms with immutable audit trails and lot-level genealogy. Germany's KBA enforces component-origin verification for automotive suppliers, directly shaping product specification requirements for European SCV vendors. Stakeholders must evaluate whether their visibility architecture can accommodate impending mandatory sustainability disclosures without parallel system duplication.
Market Dynamics
The convergence of EU AI Act compliance deadlines and CSRD sustainability disclosure mandates is forcing enterprises to replace fragmented point solutions with unified audit-ready SCV architectures. Pharmaceutical distributors in Germany and automotive OEM supply chains in the United States are driving the most urgent procurement cycles.
Growth Catalysts
- FDA Traceability Mandates:The Food Safety Modernization Act compels food manufacturers to deploy lot-level genealogy tracking, directly expanding SCV platform procurement across cold-chain logistics providers.
- Automotive OEM Pressure:Germany's KBA enforces component-origin verification requirements that cascade through multi-tier supplier networks, mandating real-time visibility infrastructure.
- Cloud Migration:Third-party logistics providers serving manufacturing clusters are consolidating data streams through API-native platforms to compress exception-response latency.
Market Restraints
- Data Sovereignty Requirements:Defense contractors and pharmaceutical manufacturers in regulated jurisdictions must maintain on-premises deployments, fragmenting vendor addressable market.
- Sensor Network Capital Intensity:Real-time tracking modules require dense IoT telemetry infrastructure that mid-market freight operators cannot amortize across thin margin structures.
- Legacy ERP Entrenchment:Deep integration with existing procurement workflows creates switching costs that delay platform replacement cycles.
Strategic Opportunities
- Predictive Analytics Layer:German software engineering capacity is repositioning toward exception-forecasting capabilities that anticipate disruptions before physical events occur.
- EU Green Deal Alignment:Mandatory carbon footprint disclosure requirements create demand for SCV platforms with embedded emissions calculation engines.
- Pharmaceutical Cold-Chain Expansion:Cell and gene therapy distribution networks require sub-minute latency tracking that commands premium pricing tiers.
Industry Challenges
- Multi-Tier Data Harmonization:Supplier networks operate on incompatible EDI protocols and API standards, requiring expensive normalization layers.
- Cybersecurity Certification Delays:ISO 27001 and SOC 2 compliance timelines extend sales cycles for vendors targeting regulated pharmaceutical and defense end-uses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supply Chain Visibility (SCV) Software Market |
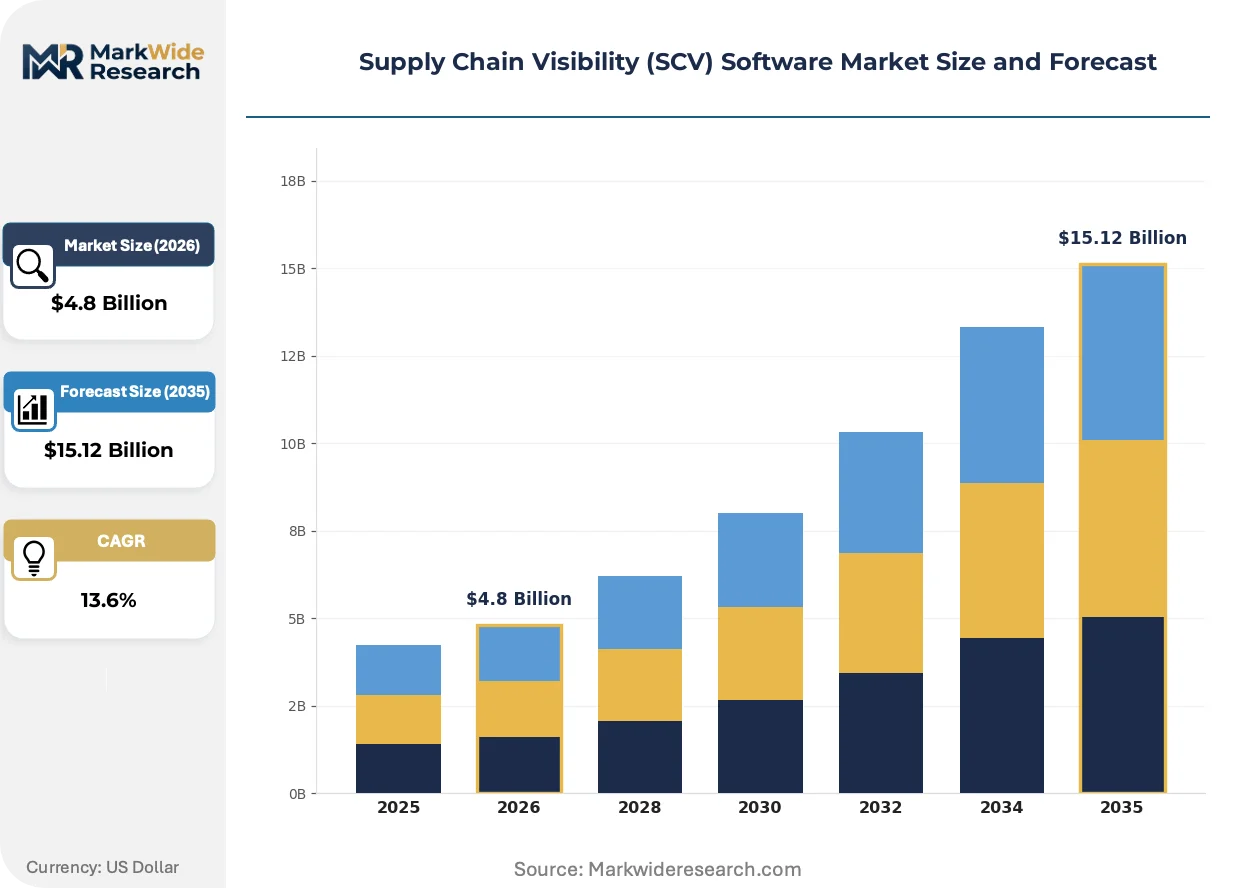
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.12 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, SaaS End User: Manufacturers, Retailers, Distributors, Logistics Providers Deployment Model: Public Cloud, Private Cloud, Managed Services, Value-Added Resellers Solution: Real-Time Tracking, Inventory Management, Risk Assessment, Reporting Tools |
| Companies Covered | SAP SE, Oracle, IBM, Blue Yonder, FourKites, project44, Kinaxis, Infor, Descartes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supply Chain Visibility (SCV) Software Market Trends and Innovations
Real-time visibility architectures are overtaking retrospective reporting tools as the default procurement specification. Three concurrent developments are compressing deployment timelines and reshaping competitive differentiation.
API-first cloud-native platforms are overtaking middleware-heavy integration approaches in new enterprise bookings. These platforms ingest multi-source logistics data through standardized connectors rather than custom EDI mapping, enabling pharmaceutical distributors in Germany to achieve sub-minute latency without dedicated integration teams. The structural consequence is collapsing implementation timelines from quarters to weeks.
EU CSRD disclosure mandates are compelling manufacturers to embed sustainability telemetry directly into SCV data models. The regulation requires auditable scope-three emissions documentation that cannot be satisfied by standalone carbon accounting tools. Automotive suppliers in Germany are responding by procuring platforms with pre-configured ESG reporting modules.
Buyer consolidation among third-party logistics providers is compressing vendor evaluation cycles and elevating procurement sophistication. Large 3PLs serving automotive OEMs in the United States now require proof-of-concept deployments with quantified cash-to-cash cycle compression before contract signature. This behavior shift is most visible in Michigan and South Carolina manufacturing corridors where OEM penalty clauses for supply disruption have steepened.
Supply Chain Visibility (SCV) Software Market Segmentation
SCV software procurement patterns diverge sharply between embedded ERP modules and standalone visibility platforms. Deployment architecture and end-use operational requirements dictate integration depth, pricing tier, and vendor selection criteria across buyer categories.
Product Type:
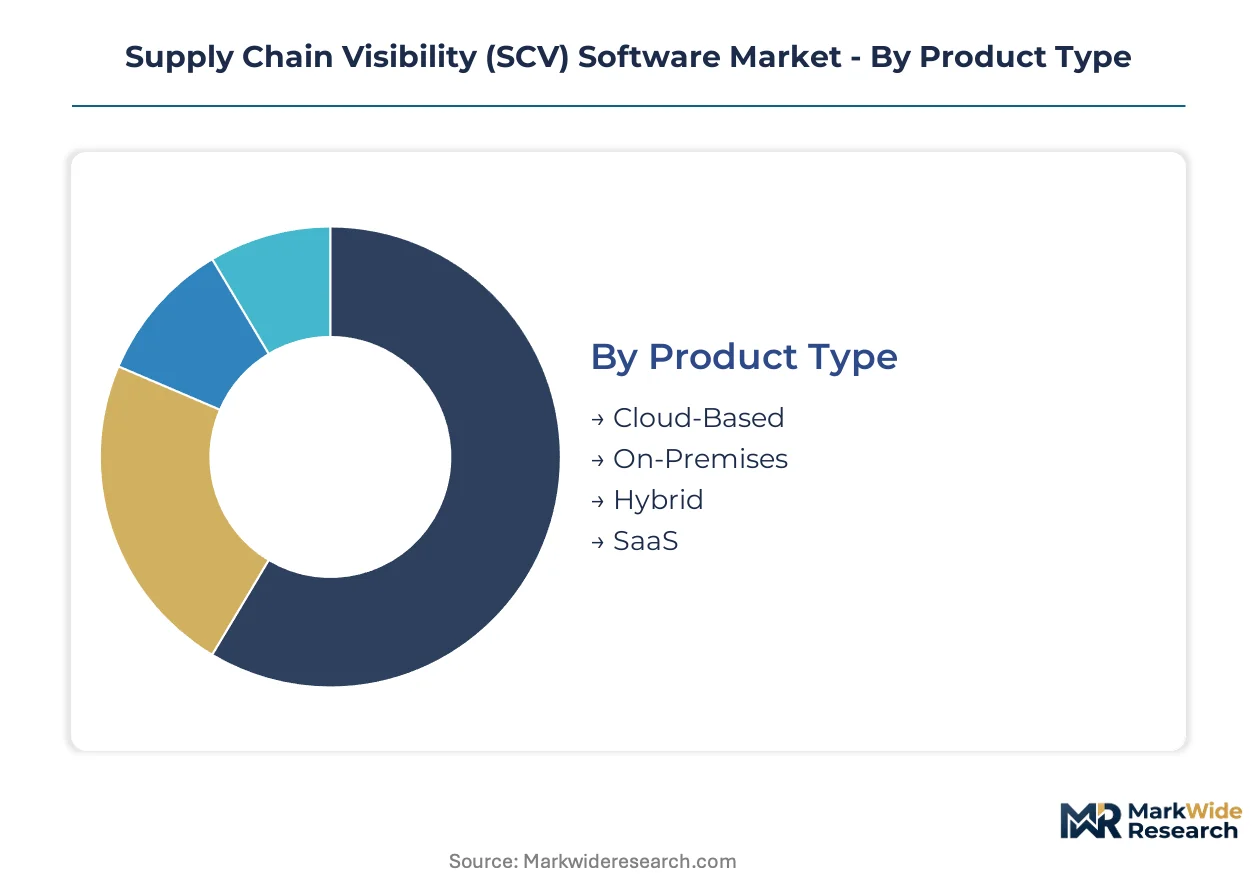
Integration depth separates cloud-native deployments from captive infrastructure, with hybrid architectures occupying procurement discussions where data sovereignty constraints apply.
- Cloud-Based:Multi-tenant architectures deliver API-first data ingestion with sub-minute latency for automotive and pharmaceutical cold-chain applications. Third-party logistics providers in Michigan and South Carolina manufacturing corridors favor this model for rapid scaling without capital commitment.
- On-Premises:Dedicated hardware installations maintain physical data control for defense contractors and regulated pharmaceutical manufacturers subject to FDA data-localization requirements. Germany's pharmaceutical distributors deploy these where EU AI Act audit trails must remain within national jurisdiction.
- Hybrid:Split architectures process sensitive tier-one supplier data on-premises while pushing tier-three visibility to cloud tiers. Automotive OEMs in Germany leverage this for KBA component-origin verification without exposing proprietary design specifications.
- SaaS:Subscription models with standardized connectors collapse implementation timelines from quarters to weeks for mid-market freight operators.
Volume placements concentrate in Cloud-Based deployments; the faster expansion belongs to Hybrid configurations bridging sovereignty and agility requirements.
End User:
Customer sophistication and penalty-clause exposure determine feature requirements and pricing tolerance across buyer categories.
- Manufacturers:Multi-tier supplier networks demand lot-level genealogy tracking mandated by FDA Food Safety Modernization Act and EU REACH documentation. Automotive OEMs in Germany and food processors in the United States drive premium-tier procurement for exception-forecasting capabilities.
- Logistics Providers:Third-party operators serving manufacturing clusters consolidate data streams through API-native platforms to compress cash-to-cash cycles. Large 3PLs now require quantified cycle compression proof before contract signature.
- Distributors:Pharmaceutical distributors in Germany expand real-time tracking module adoption to satisfy EU CSRD sustainability disclosure mandates with auditable scope-three emissions documentation.
- Retailers:Inventory positioning optimization dominates procurement specifications, with demand concentrating among omnichannel operators managing cross-border fulfillment complexity.
Procurement volume clusters with Manufacturers; Retailers are gaining share fastest as omnichannel fulfillment requirements intensify.
Deployment Model:
Infrastructure control preferences and cybersecurity certification timelines shape deployment architecture selection.
- Public Cloud:Shared infrastructure delivers cost efficiency for mid-market operators, though ISO 27001 compliance timelines extend sales cycles in regulated end-uses.
- Private Cloud:Dedicated tenant environments satisfy pharmaceutical and defense data-sovereignty requirements without full on-premises capital burden.
- Managed Services:Outsourced operations appeal to freight operators lacking internal telemetry infrastructure expertise.
- Value-Added Resellers:Channel partners embed SCV modules into broader supply chain consulting engagements, particularly in European manufacturing corridors.
Contract volume favors Public Cloud; Private Cloud is climbing the fastest as regulatory jurisdictions tighten data-localization enforcement.
Solution:
Functional module selection reflects operational pain-point severity and penalty-clause exposure within buyer supply chains.
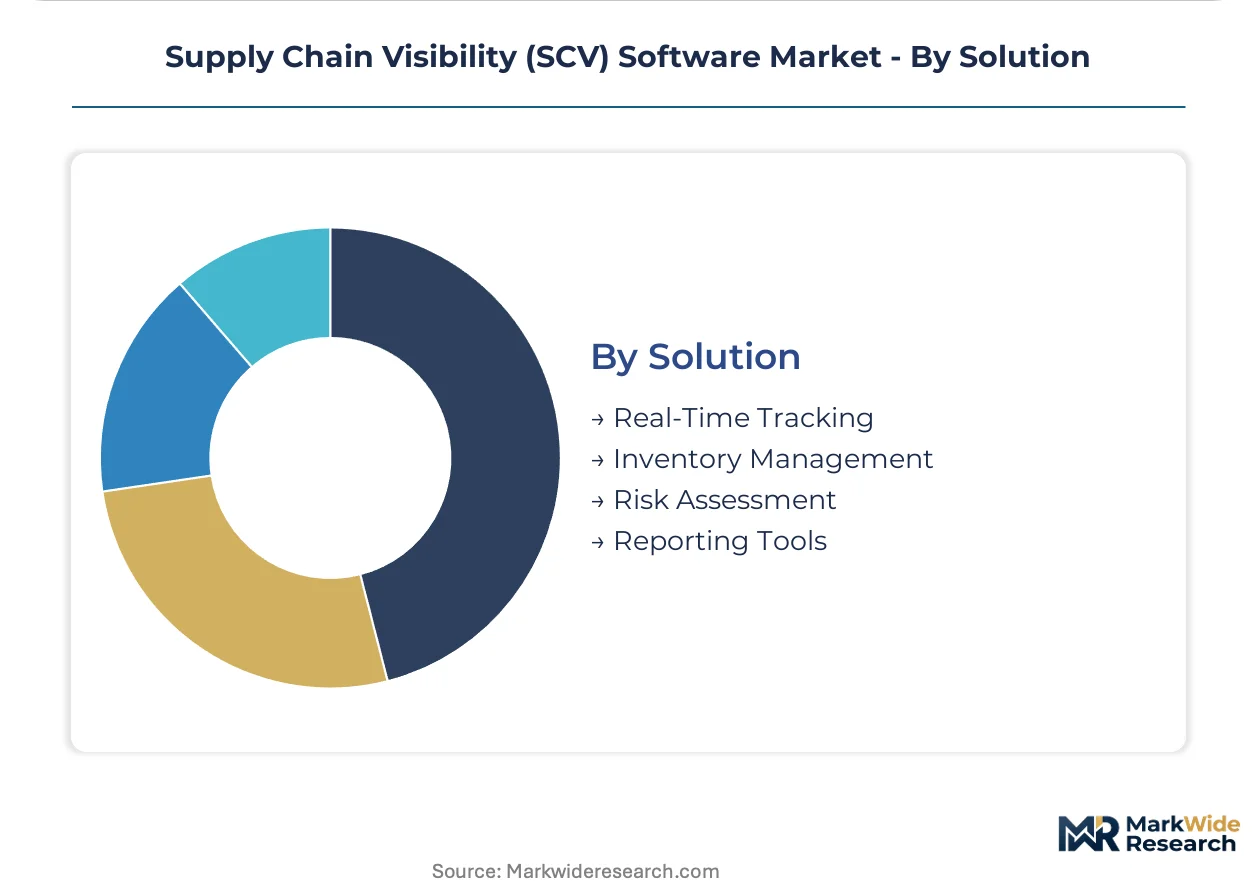
- Real-Time Tracking:Sensor-network-dependent solutions command premium pricing for sub-minute latency in automotive sequencing and cell therapy distribution. IoT telemetry density requirements exclude thin-margin mid-market operators.
- Inventory Management:Multi-echelon optimization modules integrate with existing ERP procurement workflows, creating switching costs that delay platform replacement.
- Risk Assessment:Predictive analytics layers anticipate disruptions before physical events occur, with German software engineering capacity repositioning toward this capability.
- Reporting Tools:Retrospective dashboards retain traction among compliance-focused buyers preparing for EU CSRD and FDA traceability audits.
Revenue concentration sits with Real-Time Tracking; Risk Assessment shows the steepest expansion trajectory as predictive capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure concentration in Northern Virginia and Frankfurt anchors SCV software development, while automotive manufacturing corridors in Michigan and Baden-Württemberg drive deployment density.
United States
Third-party logistics providers serving automotive OEMs dominate procurement volume, with Michigan and South Carolina manufacturing corridors requiring sub-minute latency tracking to avoid penalty clauses. FDA traceability mandates under the Food Safety Modernization Act compel cold-chain food processors to deploy lot-level genealogy platforms. Seattle and San Francisco Bay Area cloud providers supply the underlying API-native infrastructure.
Germany
Pharmaceutical distributors in Frankfurt and Munich are expanding real-time tracking module adoption to satisfy EU CSRD sustainability disclosure mandates. The KBA enforces component-origin verification requirements that cascade through multi-tier automotive supplier networks in Baden-Württemberg and Bavaria. Berlin-based software engineering capacity is repositioning toward predictive analytics layers within SCV stacks.
China
Dual carbon goals and MIIT data-localization requirements are compelling manufacturers to deploy hybrid visibility architectures with on-premises tier-one processing. Yangtze River Delta electronics assemblers and Pearl River Delta export manufacturers represent the primary demand concentration. NMPA pharmaceutical traceability rules are accelerating procurement of audit-ready platforms in Shanghai and Suzhou.
India
PLI scheme beneficiaries in automotive and electronics manufacturing are consolidating supplier data streams through API-native platforms to compress cash-to-cash cycles. Maharashtra and Gujarat pharmaceutical exporters deploy SCV systems to meet EU REACH documentation requirements for European market access. Bangalore and Hyderabad SaaS providers are emerging as regional platform vendors.
United Kingdom
Post-Brexit customs complexity is driving demand for multi-tier visibility among freight operators managing EU-UK corridor flows. London-based financial services and insurance sectors require SCV platforms for supply chain risk underwriting. Midlands automotive suppliers are adopting real-time tracking to maintain just-in-sequence delivery contracts with German OEMs.
Supply Chain Visibility (SCV) Software Market Competitive Landscape
Global majors compete with regional champions across integration depth and deployment velocity, with ERP-embedded modules commanding premium pricing against standalone visibility platforms. The vendor base separates into three strategic archetypes: database-cloud integrators unifying multi-tier inventory signals, freight-specific sensor-network operators competing on telemetry density, and API-native challengers collapsing implementation timelines. Dominant competitive moves include strategic partnerships with cloud hyperscalers and vertical integration into predictive analytics capabilities.
Within the ERP-embedded tier, SAP SE and Oracle exemplify the integration-depth archetype, leveraging installed procurement workflow bases to embed visibility modules directly into enterprise operations. Among freight-specific specialists, FourKites anchors the sensor-network density position. These three companies represent distinct competitive vectors: ERP entrenchment, database-cloud unification, and real-time telemetry infrastructure respectively.
| Leading Market Players |
|---|
| SAP SE |
| Oracle |
| IBM |
| Blue Yonder |
| FourKites |
| project44 |
| Kinaxis |
| Infor |
| Descartes |
| Others |
Pricing and Supply Chain Analysis
IoT sensor hardware costs cascade through SCV software pricing tiers, with telemetry density requirements separating premium real-time tracking modules from basic reporting tools. Cloud hyperscaler infrastructure fees in Northern Virginia and Frankfurt data centers compress margins for SaaS-native vendors serving mid-market freight operators.
Pricing Analysis
Warranty and implementation support bundling distinguishes enterprise-grade SCV contracts from self-service SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels reflects latency guarantees, with sub-minute tracking commanding substantial premiums over batch-updated dashboards. Price differentiation hinges on ISO 27001 certification status and embedded predictive analytics capabilities. Pricing pressure stems from API-native challengers collapsing implementation timelines, squeezing legacy middleware vendors. Mid-market third-party logistics providers exhibit highest price sensitivity, while automotive OEMs accepting penalty-clause exposure demonstrate lowest.
Supply Chain Analysis
EU data-localization mandates and China's MIIT requirements are reshaping cloud infrastructure sourcing toward sovereign-hosted deployments. Software engineering talent concentrates in Germany, India, and the United States, with Bangalore and Berlin emerging as predictive analytics development hubs. Raw material dependencies span semiconductor components for edge sensors, optical fiber for telemetry networks, and cobalt for cold-chain monitoring devices. Single-source vulnerability runs through Taiwan semiconductor fabrication for IoT chipsets. Distribution runs through direct enterprise sales teams for large manufacturers, value-added resellers for European mid-market, and cloud marketplace listings for SaaS-native adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first architectures are displacing middleware-heavy integration approaches, compressing deployment timelines and reshaping competitive dynamics across buyer categories.
For Market Incumbents: Extend predictive analytics capabilities through acquisition of German engineering teams specializing in exception-forecasting algorithms. Deepen ERP integration moats by embedding visibility modules directly into procurement workflow APIs, countering standalone platform displacement. Address cloud-native challenger threat by collapsing implementation timelines for existing installed base through pre-configured connectors. For New Entrants and Emerging Players: Capture pharmaceutical cold-chain white space in cell and gene therapy distribution networks where sub-minute latency requirements exclude thin-margin operators. Penetrate EU CSRD compliance segment with pre-configured emissions calculation engines bundling scope-three documentation. Pursue proof-of-concept-led go-to-market with quantified cash-to-cash cycle compression guarantees before contract signature. For Investors and Strategic Acquirers: FDA Food Safety Modernization Act enforcement actions are the leading indicator that lot-level genealogy platform demand is accelerating beyond supply capacity. Long-term viability favors vendors with audit-ready architectures spanning multi-tier supplier networks. Target acquisition archetype: API-native challengers with sub-quarter implementation timelines and embedded sustainability telemetry. Watch for EU AI Act compliance deadline clustering as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding visibility modules into SAP and Oracle procurement workflows captures enterprise installed base. |
| Strategic Partnership | Cloud hyperscaler alliances in Frankfurt and Northern Virginia accelerate sub-minute latency infrastructure deployment. |
| Acquisition of Specialist Firm | Predictive analytics startups in Berlin add exception-forecasting capabilities ahead of competitive parity. |
| Geographic Expansion | India PLI scheme beneficiaries in Maharashtra and Gujarat require API-native platforms for EU REACH compliance. |
| Product Launch | ESG reporting modules with pre-configured CSRD templates address mandatory carbon disclosure requirements. |
Research Methodology
Multi-period observation of FDA enforcement patterns, EU regulatory deadline clustering, and 3PL procurement cycle timing anchored the trend analysis, supplemented by interviews with SCV platform CTOs, automotive OEM supply chain directors, pharmaceutical distributor logistics heads, and cloud infrastructure procurement officers. Secondary validation drew from SEC 10-K filings of ERP vendors, hyperscaler capex disclosures, EMA regulatory guidance documents, and customs data on IoT sensor imports. Bottom-up bookings data triangulated against top-down enterprise IT spending surveys.
Segment-weighting applied deployment model splits, end-user concentration patterns, and solution-type revenue mixes across the projection horizon. Segmentation dimensions modeled include cloud-native versus on-premises architecture, manufacturer versus logistics provider versus distributor buyer archetype, and real-time tracking versus inventory management versus risk assessment functional modules. CAGRs derived from logistic curve fitting to technology adoption S-curves, calibrated against historical ERP module penetration rates. Forecast inputs incorporated EU AI Act compliance timeline assumptions and pharmaceutical cold-chain expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply disruptions, cybersecurity certification delays, and regulatory enforcement variance across jurisdictions. Forecasts reflect documented assumptions regarding cloud migration velocity and API standardization timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Objectives & Key Results (OKR) Software Market
Software & Services
Global Mobile User Interface Services Market
Software & Services
Global Local SEO Software Market
Software & Services
Lending Software Market
Software & Services
Broadcast Scheduling Software Market
Software & Services
Middleware Market
Software & Services
Collaboration Software Market
Software & Services
Global Mobile Application Testing Solution Market
Software & Services
US Digital Marketing Software Market
Software & Services
Global Club Management Software Market
Software & Services
Email Applications Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
VFX Software Market
Software & Services
Global Project Software Market
Software & Services
Aviation Software Market
Software & Services
Electromagnetic Simulation Software Market