
 Global Website Builder Software Market | 2026-2036
Global Website Builder Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Website Builder Software Market Foresight
The EU AI Act is realigning how website builder platforms embed automated content generation and data processing tools, forcing vendors to redesign core architectures for transparency and auditability. Wix.com Ltd. leverages its Israeli R&D base to sustain rapid compliance iteration across European deployments. Squarespace, Inc. anchors its premium positioning through design-centric templates that compete on brand aesthetics rather than feature breadth. Shopify Inc. dominates the e-commerce builder segment through deep payment and logistics integrations that extend merchant operational control.
Website builder software encompasses cloud-native and on-premise platforms that enable non-technical users to construct, publish, and manage websites through visual interfaces, template libraries, and modular component architectures without direct code manipulation. These systems typically render responsive HTML/CSS output through proprietary rendering engines or open-source foundations like WordPress, serving commercial presence, transactional storefronts, and content distribution across device types. Cloud-based and SaaS deployment models capture the dominant share of new subscriptions due to lower upfront friction and automatic security patching, while drag-and-drop editors and e-commerce builders concentrate margin pools through higher-tier pricing and transaction fee structures. Small and medium enterprises represent the most contested end-user segment as vendors race to simplify onboarding workflows and reduce time-to-publish metrics.
The EU AI Act and GDPR framework shape European product roadmaps by mandating explainability for AI-driven design suggestions and restricting cross-border data flows to approved jurisdictions. The FCC and state-level privacy laws in California and Virginia create a fragmented compliance landscape in the United States that increases platform engineering overhead. Stakeholders must monitor how emerging digital accessibility standards and sustainability disclosure rules reshape hosting infrastructure requirements and customer procurement criteria.
Market Dynamics
Cloud-native deployment models are compressing time-to-publish metrics and forcing incumbent vendors to rebuild core rendering engines for serverless architectures. The EU AI Act's explainability mandates are triggering architectural redesigns across European deployments.
Growth Catalysts
- SME Digital Presence Mandates:Small and medium enterprises across India and Germany are accelerating website launches to capture e-commerce revenue streams. Government digitization programs in both countries subsidize SaaS adoption.
- GDPR Compliance as Feature:Privacy-by-design architectures have become a competitive differentiator. Vendors embedding automated consent management and data localization tools capture procurement preference from European healthcare and financial services buyers.
- Headless CMS Convergence:API-first content architectures enable omnichannel publishing. Retail and media buyers in the United States deploy these systems to synchronize web storefronts with mobile applications and in-store displays.
Market Restraints
- Input Cost Volatility:GPU and cloud compute pricing fluctuations compress margins for AI-powered design suggestion features. Vendors absorbing these costs face margin pressure on freemium tiers.
- Supply Concentration Risk:Hyperscaler cloud infrastructure dependence creates single-point-of-failure exposure. AWS, Azure, and Google Cloud dominance limits vendor negotiating leverage for European data residency requirements.
- Technical Limitation:JavaScript bundle sizes for drag-and-drop editors degrade mobile performance. Emerging market users on 3G networks experience abandonment rates that undermine conversion metrics.
Strategic Opportunities
- Underpenetrated Rural India:Tier-3 and Tier-4 cities exhibit sub-15% formal business website penetration. Vernacular-language template libraries and UPI-integrated payment gateways unlock this demand pool.
- EU Green Deal Alignment:Sustainability disclosure requirements for digital infrastructure create certification opportunities. Carbon-neutral hosting claims differentiate vendors in public sector procurement across France and the Netherlands.
- Voice-Interface Convergence:Natural language processing and visual editing tools are merging. Non-technical users in Japan and South Korea deploy voice commands to manipulate page layouts without screen interaction.
Industry Challenges
- Accessibility Engineering Gap:WCAG 2.2 compliance requires specialized front-end talent. Vendors struggle to recruit developers with simultaneous expertise in semantic HTML and automated testing frameworks.
- Legacy System Integration Friction:Enterprise buyers demand ERP and CRM connectivity. Custom API development for SAP and Oracle ecosystems extends implementation timelines and strains professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Website Builder Software Market |
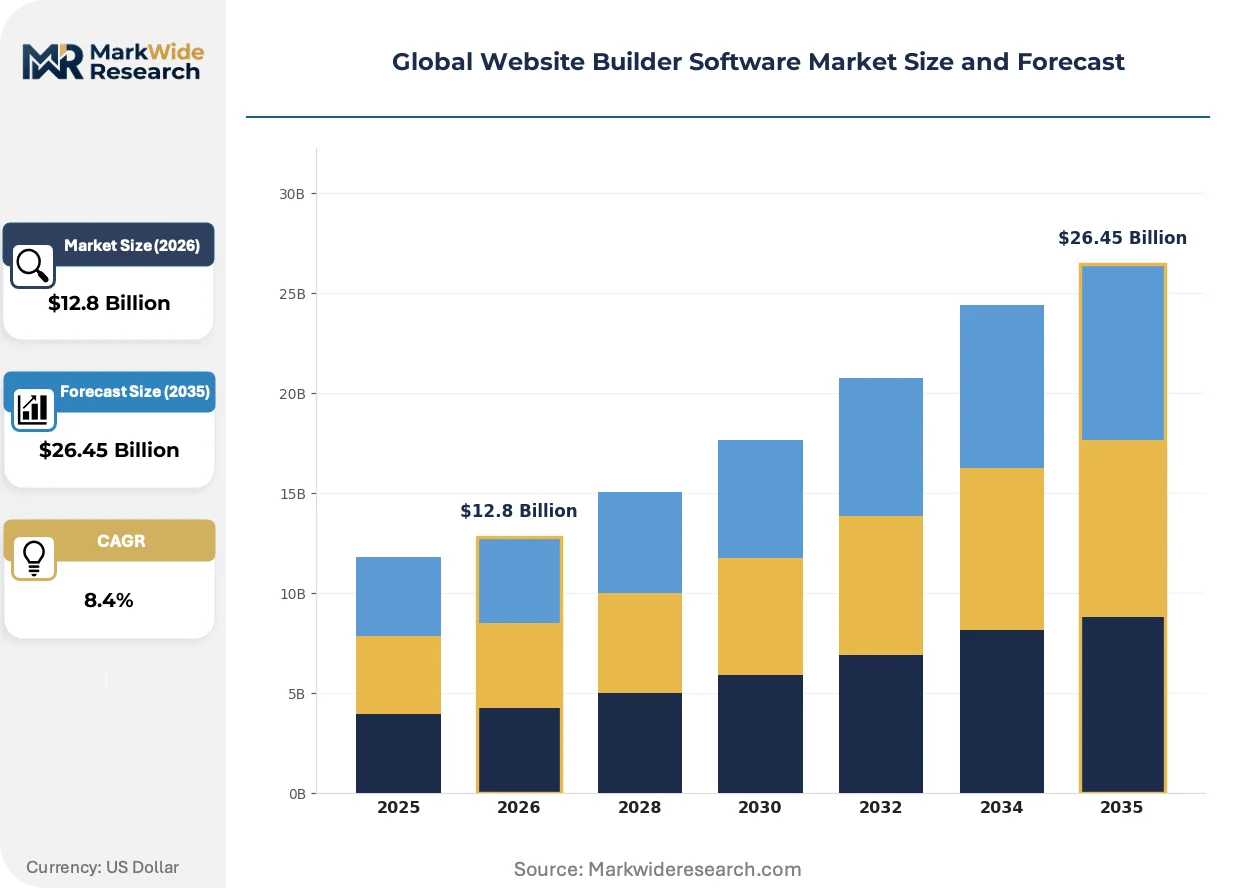
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Hosted Solution Type: Drag-and-Drop Editors, E-Commerce Builders, Blogging Platforms, Portfolio Creators, Landing Page Tools End User Segment: Small & Medium Enterprises, Freelancers, Non-Profit Organizations, Educational Institutions, Government Bodies Pricing Model: Subscription-Based, Freemium, One-Time License, Pay-As-You-Go, Tiered Pricing |
| Companies Covered | WordPress.org, Wix.com Ltd., Squarespace, Inc., Webflow, Inc., GoDaddy Operating Company, LLC, Shopify Inc., Jimdo GmbH, IONOS Inc., Duda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Website Builder Software Market Shifts & Advancements
Generative design automation is compressing the traditional agency-client workflow. Procurement criteria are pivoting from template quantity toward AI output quality and auditability.
Visual editing interfaces are consolidating around component-based design systems. Mid-market retailers in Germany and the United States adopt these tools to maintain brand consistency across hundreds of localized storefronts. The technology is consolidating previously fragmented design operations into centralized governance models.
The EU AI Act's algorithmic transparency requirements are forcing vendors to document training data provenance and suggestion logic. European deployments now require explainability dashboards that expose why specific layout recommendations appear. Healthcare and financial services buyers in France and Germany are delaying procurement until vendors certify compliance.
Self-service onboarding is displacing traditional sales-led implementation for sub-50-employee buyers. Channel economics favor low-touch digital acquisition over field sales teams. This shift is most visible in India's micro-enterprise segment, where WhatsApp-integrated support replaces dedicated account management.
Global Website Builder Software Market Segmentation
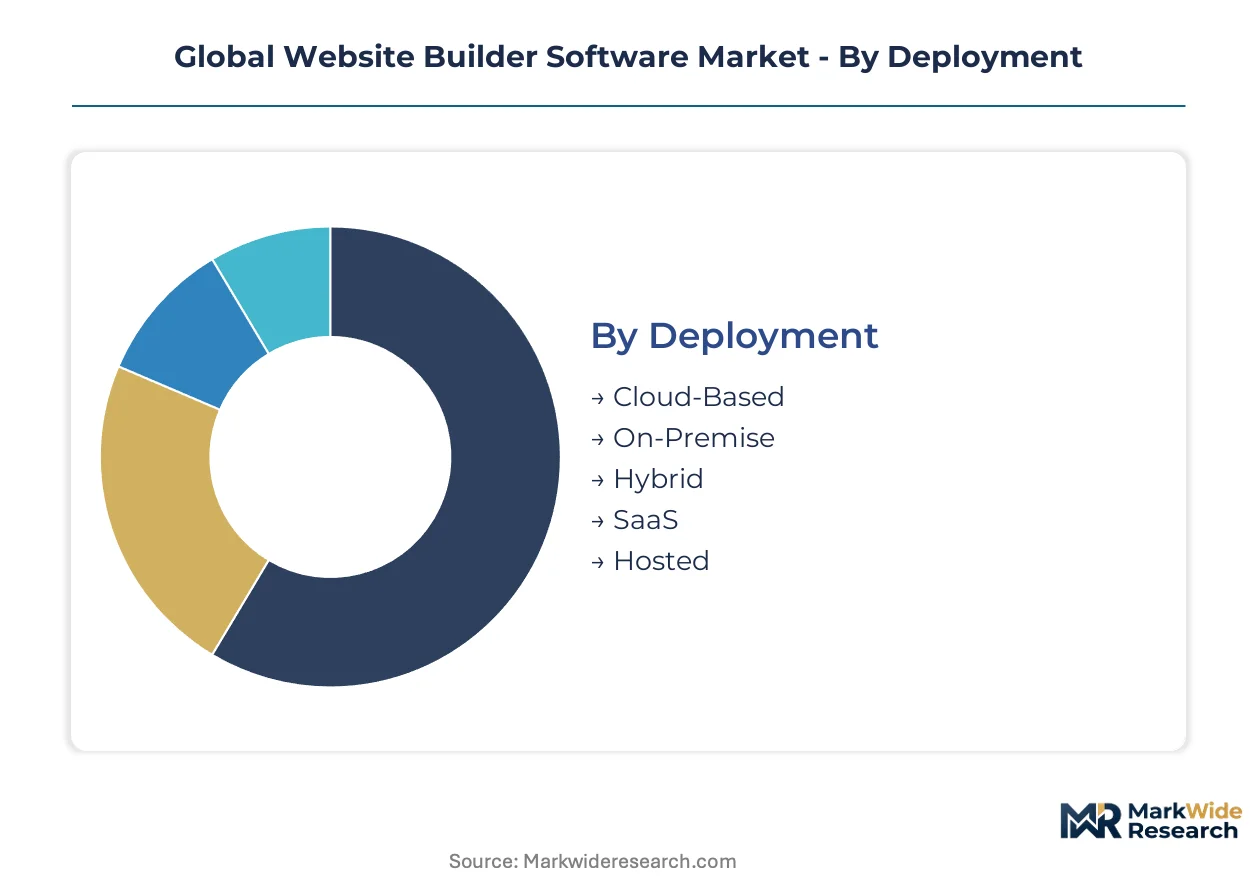
Website builder software segments diverge sharply by technical sophistication and procurement authority. Deployment architecture determines compliance overhead, while pricing model selection correlates directly with customer lifecycle value and churn tolerance.
Deployment:
Buyers in this category separate by data sovereignty requirements and IT staffing levels.
- Cloud-Based:Multi-tenant architectures with automatic scaling and patch management dominate SME procurement in Germany and India. GDPR data localization mandates from CNIL and BfDI push vendors toward EU-region compute clusters, raising infrastructure costs but reducing legal exposure for healthcare and financial services buyers.
- SaaS:Browser-native platforms with zero-install deployment capture freelancer and micro-enterprise demand across the United States. Recurring revenue predictability attracts vendor investment in onboarding automation, though customer acquisition costs spiral in saturated urban markets.
- On-Premise:Self-hosted installations with full source control serve defense contractors and government bodies with air-gapped security requirements.
- Hybrid:Split architectures combining cloud front-ends with on-premise data stores address ERP integration needs in Japanese manufacturing.
- Hosted:Managed single-tenant deployments with dedicated support contracts appeal to mid-market retailers lacking DevOps capacity.
Volume sits with Cloud-Based; growth tilts toward SaaS.
Solution Type:
Commercial purpose dictates feature prioritization and margin structure across buyer types.
- E-Commerce Builders:Inventory management, payment gateway orchestration, and tax automation modules define this segment. Indian vendors embedding UPI and COD workflows capture Tier-2 and Tier-3 city merchants; Shopify and WooCommerce integrations dominate US and German mid-market adoption.
- Drag-and-Drop Editors:Visual component libraries with real-time preview render responsive HTML/CSS without code exposure. Wix and Squarespace compete on template aesthetic differentiation; mobile performance optimization remains a technical constraint on 3G networks in rural India.
- Blogging Platforms:Content-first architectures with RSS syndication and newsletter integration serve media professionals and thought leadership marketers.
- Portfolio Creators:Image-optimized templates with lightbox galleries and client proofing tools target photographers and designers in Japan and South Korea.
- Landing Page Tools:Conversion-focused single-page builders with A/B testing and lead capture forms concentrate in US SaaS marketing stacks.
E-Commerce Builders command the highest revenue per user; Drag-and-Drop Editors are expanding most quickly among non-technical freelancers.
End User Segment:
Organizational scale determines implementation complexity and support channel preferences.
- Small & Medium Enterprises:Formal business registrations with 10-250 employees drive platform standardization decisions. German Mittelstand manufacturers prioritize ERP connectivity; Indian SMEs demand vernacular-language interfaces and WhatsApp-integrated support.
- Freelancers:Solo operators billing hourly for client work value rapid deployment and portfolio demonstration speed over feature depth. Subscription price sensitivity peaks in this segment, with freemium-to-paid conversion rates determining vendor unit economics.
- Non-Profit Organizations:Donation processing integration and volunteer management tools shape procurement; grant-funded budgets limit pricing flexibility.
- Educational Institutions:Multi-site governance, student data privacy compliance, and LMS integration requirements differentiate K-12 from university deployments.
- Government Bodies:Accessibility mandates, security certification, and procurement transparency rules extend sales cycles but guarantee multi-year contracts.
SMEs anchor current volume; Freelancers represent the steepest expansion trajectory as gig economy participation rises.
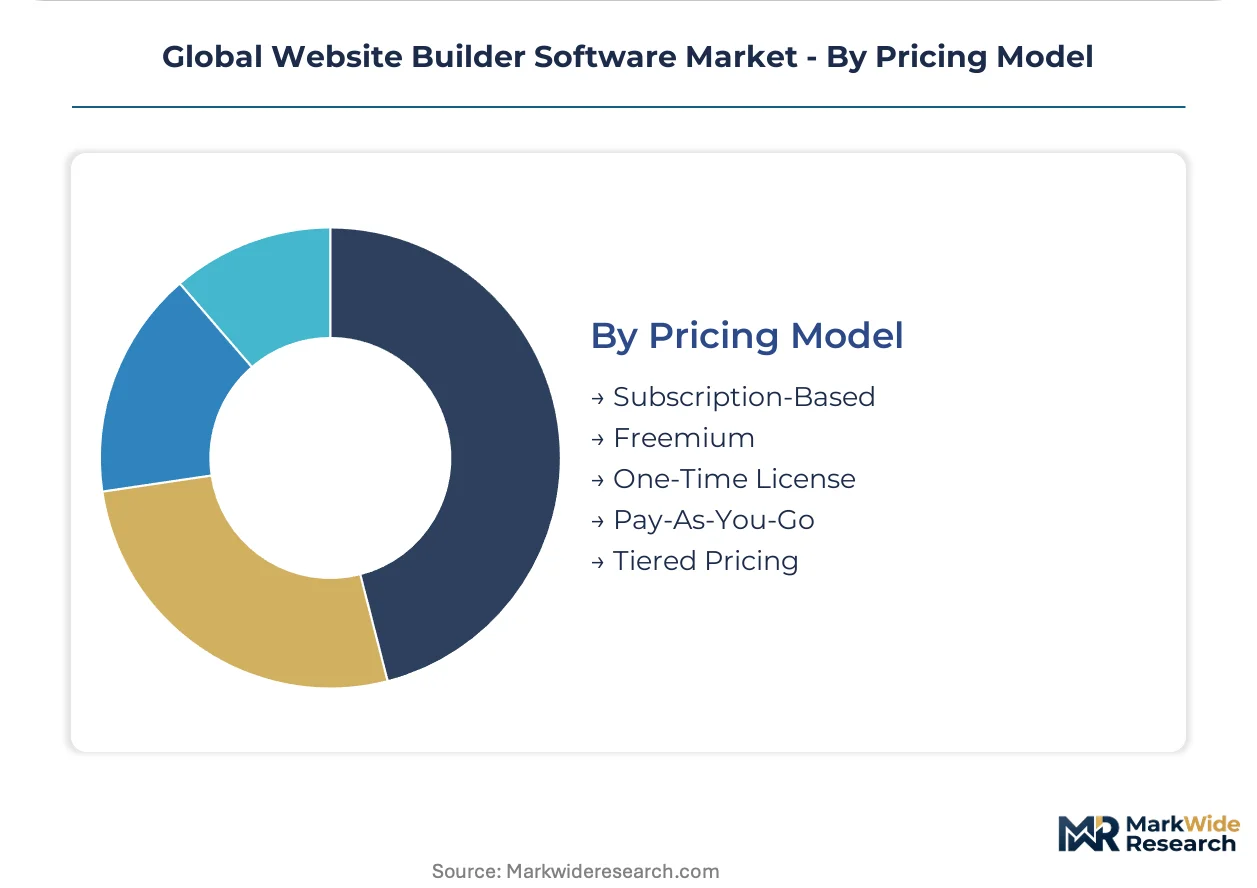
Pricing Model:
Cash flow timing and value realization sequencing separate buyers in this category.
- Subscription-Based:Monthly or annual recurring payments with tiered feature gates dominate vendor revenue recognition. Annual prepay discounts improve cash conversion cycles; monthly options reduce commitment friction for seasonal businesses in tourism and events.
- Freemium:Zero-entry pricing with conversion triggers at usage or feature thresholds. Storage limits, custom domain requirements, and branding removal drive upgrades; support cost allocation per free user strains unit economics at scale.
- One-Time License:Perpetual purchase with optional maintenance contracts appeals to capital-budget government and enterprise buyers.
- Pay-As-You-Go:Usage-metered billing for bandwidth, storage, or transaction volume aligns costs with actual consumption.
- Tiered Pricing:Explicit feature stratification across three or more named plans simplifies choice architecture.
Subscription-Based captures the largest revenue pool; Freemium user acquisition is climbing the fastest among venture-backed entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Development of website builder platforms concentrates in the United States and Israel, while consumption spreads across Germany, India, and Japan as digital entrepreneurship accelerates. Vendor R&D clusters in Silicon Valley and Tel Aviv shape feature roadmaps that later diffuse to regional markets with localized compliance adaptations.
United States
SaaS procurement by freelancers and micro-enterprises drives subscription volume in California and New York. FCC state-level privacy fragmentation between California and Virginia forces vendors to maintain multiple compliance configurations. Austin and Miami emerge as secondary hubs where venture-backed entrants target Latin American market expansion.
Germany
Mittelstand manufacturers in Bavaria and North Rhine-Westphalia demand ERP-integrated website builders for B2B commerce. BfDI data localization rulings and EU AI Act explainability mandates push vendors toward EU-region hosting clusters. Berlin hosts the largest concentration of compliance-focused SaaS engineering talent outside Silicon Valley.
India
Tier-2 and Tier-3 city merchants in Maharashtra and Gujarat accelerate website launches for UPI-enabled e-commerce. RBI payment aggregator regulations and DGFT export documentation requirements shape platform feature priorities. Bangalore and Hyderabad host development centers serving both domestic vernacular-language markets and Middle East expansion.
Japan
Portfolio creators and design agencies in Tokyo and Osaka drive demand for aesthetic-focused templates with mobile optimization. METI digital transformation subsidies reduce adoption friction for small retailers in Kansai. Voice-interface editing experiments concentrate in Nagoya manufacturing corridors where hands-free workflow tools gain traction.
United Kingdom
Creative freelancers and marketing agencies in London sustain drag-and-drop editor subscriptions despite post-Brexit regulatory divergence. Information Commissioner's Office guidance on automated decision-making affects AI design suggestion deployments. Manchester and Edinburgh develop as secondary clusters where platform vendors localize for Commonwealth market expansion.
Global Website Builder Software Market Competitive Landscape
The competitive structure tilts toward integrated commerce platforms with adjacent payment and logistics capabilities. Consolidation pressure concentrates among venture-backed SaaS providers competing for freelancer mindshare against incumbent template libraries. Three archetypes dominate: e-commerce-native platforms with deep operational toolchains, design-centric builders competing on aesthetic differentiation, and open-source foundations with extensive plugin marketplaces. Geographic expansion through localized template libraries and strategic partnerships with regional payment processors represent the primary competitive vectors.
Within the e-commerce-native tier, Shopify Inc. and Wix.com Ltd. occupy positions that exemplify divergent approaches to merchant operational control. Squarespace, Inc. anchors the design-centric archetype through premium template positioning. Among open-source foundations, WordPress.org represents the extensibility-maximized model where third-party developers capture marginal feature innovation.
| Leading Market Players |
|---|
| WordPress.org |
| Wix.com Ltd. |
| Squarespace, Inc. |
| Webflow, Inc. |
| GoDaddy Operating Company, LLC |
| Shopify Inc. |
| Jimdo GmbH |
| IONOS Inc. |
| Duda |
| Others |
Supply & Pricing Matrix
AWS EC2 Reserved Instance pricing indices cascade through vendor cost structures, compressing margins on freemium tiers while subscription premiums absorb hyperscaler volatility. Cloud compute concentration forces SaaS builders into three-tier pricing structures across premium, standard, and economy levels that internalize infrastructure pass-through costs.
Pricing Analysis
Value-based pricing anchored to transaction throughput and merchant revenue capture dominates e-commerce builder tiers. Subscription models stratify by feature depth and support tier, with GDPR compliance modules commanding certification premiums. Cost compression in entry-level tiers intensifies because GPU provisioning for AI design features absorbs margin. Freelancers exhibit peak price sensitivity, while German Mittelstand manufacturers prioritize ERP integration value over subscription cost.
Supply Chain Analysis
Direct-to-SaaS channels handle hyperscale buyer demand through browser-native deployment, bypassing traditional software distribution. Infrastructure supply concentrates in the United States, Ireland, and Singapore where AWS, Azure, and Google Cloud operate primary compute regions. Vendor technology stacks draw from open-source rendering engines, proprietary template libraries, and API-first content architectures. Single-source vulnerability to hyperscaler pricing power creates margin exposure. Distribution runs through self-service onboarding portals with automated provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as compliance engineering costs force sub-scale vendors toward acquisition or exit. The EU AI Act's explainability mandates disproportionately burden venture-backed entrants lacking dedicated European R&D presence.
For Market Incumbents: Deploy compliance automation as a competitive moat. Invest in EU-region hosting clusters to preempt BfDI data localization rulings. Acquire voice-interface editing specialists before Japanese manufacturing corridors lock in preferred vendor relationships. Channel control through WhatsApp-integrated support networks defends against low-cost Indian challengers. For New Entrants and Emerging Players: AI-native design suggestion engines with explainability dashboards offer entry wedge against legacy template libraries. Target Tier-3 and Tier-4 Indian cities where vernacular-language interfaces and UPI payment integration remain underdeveloped. Pursue METI subsidy-aligned positioning for Japanese small retailers seeking digital transformation funding. For Investors and Strategic Acquirers: The window for entry favors compliance-ready mid-market platforms with existing EU hosting infrastructure. Long-term viability hinges on omnichannel publishing capabilities that synchronize web, mobile, and in-store display content. Monitor BfDI and CNIL enforcement patterns as inflection indicators for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | BfDI explainability mandates unlock healthcare and financial services procurement in Germany. |
| Vernacular Language Template Expansion | Tier-3 Indian city penetration requires Maharashtra and Gujarat localized interfaces. |
| Headless CMS Platform Integration | API-first architectures enable German retailers to synchronize web storefronts with in-store displays. |
| Carbon-Neutral Hosting Certification | EU Green Deal alignment differentiates vendors in French and Dutch public sector tenders. |
| Voice-Interface Editing Development | Hands-free workflow tools gain traction in Nagoya manufacturing corridors under METI subsidies. |
Research Methodology
Independent corroboration across platform engineering leads, SaaS procurement officers, and channel partner directors underwrites the qualitative findings. Primary fieldwork with CTOs at German Mittelstand manufacturers, Indian micro-enterprise owners, and Japanese design agency principals combined with secondary validation. Regulatory filings from BfDI, CNIL, and RBI, alongside hyperscaler capex disclosures and EU AI Act implementation guidance, anchored supply-side assessment. Bottom-up deployment model sizing and top-down vendor revenue triangulation cross-validated segment splits.
Comparable-period anchoring to historical cloud infrastructure adoption curves and SME digitization program enrollment shaped the projection horizon. The analytical framework modeled deployment architecture, organization size, vertical integration complexity, and regional regulatory cluster across the analysis window. CAGRs derived from vendor reported subscriber growth, average revenue per user trajectories, and infrastructure cost pass-through elasticity. AI feature penetration rates and compliance certification timelines served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen regulatory enforcement intensity, hyperscaler pricing regime shifts, and emerging market connectivity infrastructure delays. Forecasts reflect assumptions about sustained SME digitization subsidy continuity and stable cross-border data flow rulings. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Construction Suites Software Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
Global Open API Market
Software & Services
Global Permit Management Software Market
Software & Services
Sales Gamification Software Market
Software & Services
Salesforce Services Market
Software & Services
Global Microscope Software Market
Software & Services
System Infrastructure Software Market
Software & Services
Load Balancing Software Market
Software & Services
Nonconformance Management Software Market
Software & Services
Freight Forwarding Software Market
Software & Services
Medical E-Commerce Software Market
Software & Services
MRP Software Market
Software & Services
Contract Lifecycle Management (CLM) Solution Market
Software & Services
Global Fixed Asset Management Software Market