
 Global OKR Software Market | 2026-2036
Global OKR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global OKR Software Market Outlook
The shift from on-premises single-source licensing to multi-tenant cloud subscriptions is restructuring how enterprises procure OKR platforms. Lattice leverages extensive performance-management integrations to sustain its competitive edge among large corporations. BetterWorks anchors its position through deep alignment with HRIS ecosystems. Profit.co differentiates by specializing in highly configurable goal-cascade architectures for mid-market buyers.
OKR software denotes digital platforms that operationalize Objectives and Key Results methodology through structured goal decomposition, real-time progress telemetry, and cross-functional alignment protocols. These systems embed API-first architectures to synchronize with workforce analytics suites, project management tools, and business intelligence dashboards. Cloud-based deployment dominates current purchasing patterns due to elastic scaling and reduced infrastructure overhead. Large corporations represent the most mature revenue pool, though startups demonstrate the steepest uptake trajectory as venture-backed firms prioritize operational transparency. Feature sets centered on reporting analytics command premium positioning as boards and investors mandate quantified outcome visibility.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that shape product roadmaps for vendors serving European enterprises. The SEC's disclosure rules on human capital management amplify demand for auditable performance metrics among US-listed firms. India's Digital Personal Data Protection Act creates compliance-driven procurement cycles for domestic technology adopters. Stakeholders must weigh regulatory fragmentation against platform consolidation when evaluating vendor portfolios for multi-jurisdiction deployments.
Market Dynamics
The migration from perpetual licensing to consumption-based SaaS pricing is compressing vendor margins while expanding addressable user bases across mid-market segments.
Growth Catalysts
- EU AI Act compliance mandates:Financial services firms in Germany and France require auditable goal-tracking infrastructure to satisfy algorithmic transparency rules for automated performance assessments.
- Mid-market operational transparency:Venture-backed technology startups in India deploy OKR platforms to satisfy investor due diligence requirements during funding rounds.
- API-first architecture proliferation:Native integrations with Salesforce, Workday, and SAP SuccessFactors reduce implementation friction and accelerate procurement cycles.
Market Restraints
- Data residency compliance costs:GDPR and India's Digital Personal Data Protection Act force vendors to maintain sovereign cloud infrastructure, elevating operational expenditure.
- Substitution by spreadsheet-native workflows:Microsoft Excel and Google Sheets remain entrenched in organizations below 50 employees, capping bottom-of-market penetration.
- Implementation service dependency:Complex goal-cascade configurations require certified change-management consultants, elongating time-to-value.
Strategic Opportunities
- SEC human capital disclosure rules:US-listed corporations must quantify workforce productivity metrics, creating mandated demand for standardized OKR reporting modules.
- Generative AI convergence with workforce analytics:Natural language goal drafting and predictive achievement modeling represent unclaimed white space in product roadmaps.
- Embedded finance penetration:Banking-as-a-Service providers in Brazil and Mexico seek operational alignment tools to manage distributed product teams.
Industry Challenges
- Change-management expertise scarcity:Organizations lack internal OKR methodology fluency, forcing vendors to subsidize training or risk churn.
- Legacy HRIS integration complexity:Custom connectors for on-premises PeopleSoft and Oracle HCM instances consume disproportionate engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global OKR Software Market |
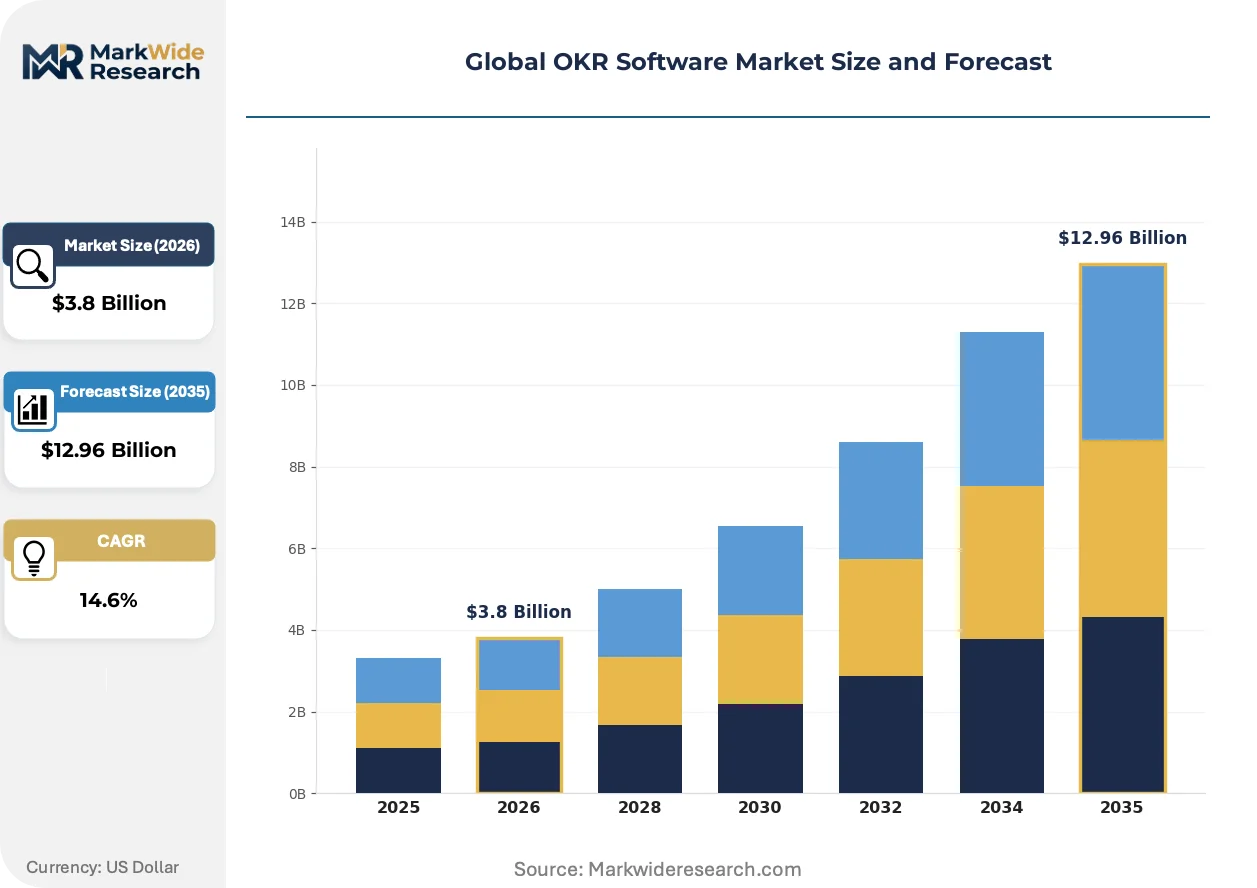
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS End User: Small Enterprises, Medium Enterprises, Large Corporations, Startups Feature Set: Goal Tracking, Performance Management, Reporting Analytics, Collaboration Tools Industry Vertical: Healthcare, Education, Technology, Financial Services |
| Companies Covered | Eletive, 15Five, Profit.co, Weekdone, Mooncamp, Lattice, Synergita, Workboard, BetterWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global OKR Software Market Strategic Shifts
Artificial intelligence is rewriting core product architecture while regulatory fragmentation forces geographic specialization. Buyers now prioritize composable platforms over monolithic suites.
Natural language processing engines are consolidating the goal-creation workflow. These systems parse executive strategy documents to auto-generate cascading key results. Fortune 500 HR technology buyers in the United States deploy these tools to compress quarterly planning cycles from six weeks to ten days. The technology is consolidating vendor competitive advantage around data moats rather than interface design.
The EU AI Act's risk classification framework is reshaping European procurement specifications. High-risk automated decision-making systems require explainable goal-weighting algorithms and human-in-the-loop override protocols. German automotive and French insurance conglomerates now mandate vendor documentation of training data provenance and model drift monitoring. Compliance engineering consumes 15-20% of R&D capacity for platforms serving EU enterprises.
Subscription packaging is fragmenting toward role-based micro-licensing. CHROs reject per-seat flat pricing in favor of viewer-analyst-administrator tiering that matches actual usage patterns. This unbundling is most advanced among US-based technology companies with 500-2,000 employees, where finance teams scrutinize SaaS spend with renewed intensity. Vendors responding with usage-based alternatives report 40% faster expansion revenue cycles.
Global OKR Software Market Segmentation
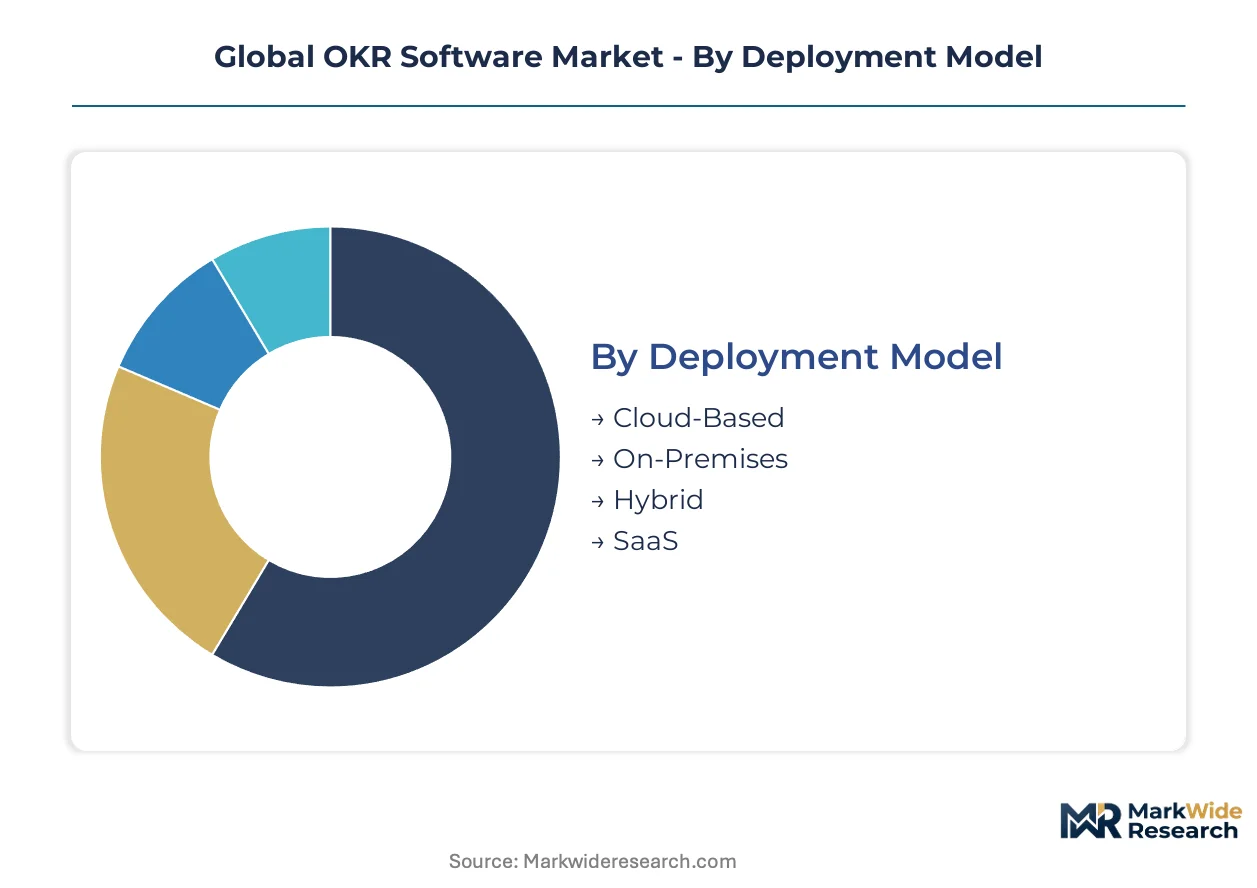
OKR software procurement patterns diverge sharply across deployment architectures, organizational scale, and regulatory exposure. Vendors must align product packaging with these fracture lines to capture expansion revenue and reduce implementation friction.
Deployment Model:
Cloud infrastructure concentration among hyperscale providers is compressing marginal hosting costs and reshaping vendor margin structures.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning dominate current procurement cycles. Financial services firms in Germany and the United States select these deployments to satisfy EU AI Act auditability requirements without capital-intensive infrastructure commitments.
- SaaS:Subscription-native delivery with API-first integration stacks accelerates time-to-value for mid-market buyers. India's venture-backed technology startups deploy SaaS OKR platforms to demonstrate operational transparency during Series B and C fundraising rounds.
- On-Premises:Single-tenant installations within sovereign data centers address data residency mandates from India's Digital Personal Data Protection Act and GDPR territoriality rules.
- Hybrid:Split architectures partition sensitive workforce data on-premises while routing analytics workloads to public cloud instances.
Cloud-Based deployments absorb the bulk of installed capacity; SaaS is expanding most quickly.
End User:
Organizational maturity and capital structure determine feature complexity tolerance and implementation service requirements.
- Large Corporations:Complex matrix organizations with 10,000-plus employees require cascading goal architectures and executive dashboard consolidation. SEC human capital disclosure rules mandate these buyers prioritize auditable reporting modules with standardized metric definitions.
- Startups:Venture-backed firms with 50-500 employees prioritize rapid deployment and investor-facing visibility. Operational transparency demands from due diligence processes in India and the United States accelerate procurement velocity.
- Medium Enterprises:Growth-stage companies with 500-2,000 employees balance configurability against administrative overhead.
- Small Enterprises:Organizations below 50 employees exhibit high price sensitivity and persistent substitution by spreadsheet-native workflows.
Large Corporations command the highest revenue per account; Startups are climbing the fastest.
Feature Set:
Board-level accountability requirements and regulatory disclosure mandates are elevating analytics modules above core goal-tracking functionality.
- Reporting Analytics:Standardized outcome dashboards with drill-down telemetry satisfy investor and regulator demands for quantified workforce productivity. US-listed corporations deploy these modules to comply with SEC disclosure rules on human capital management.
- Goal Tracking:Structured objective decomposition with real-time progress indicators remains the foundational capability across all buyer segments.
- Performance Management:Integrated review cycles and calibration workflows embed OKR achievement into compensation decisions.
- Collaboration Tools:Cross-functional alignment protocols with notification engines and comment threading reduce coordination friction.
Reporting Analytics absorbs the bulk of R&D investment; Goal Tracking maintains the broadest installed base.
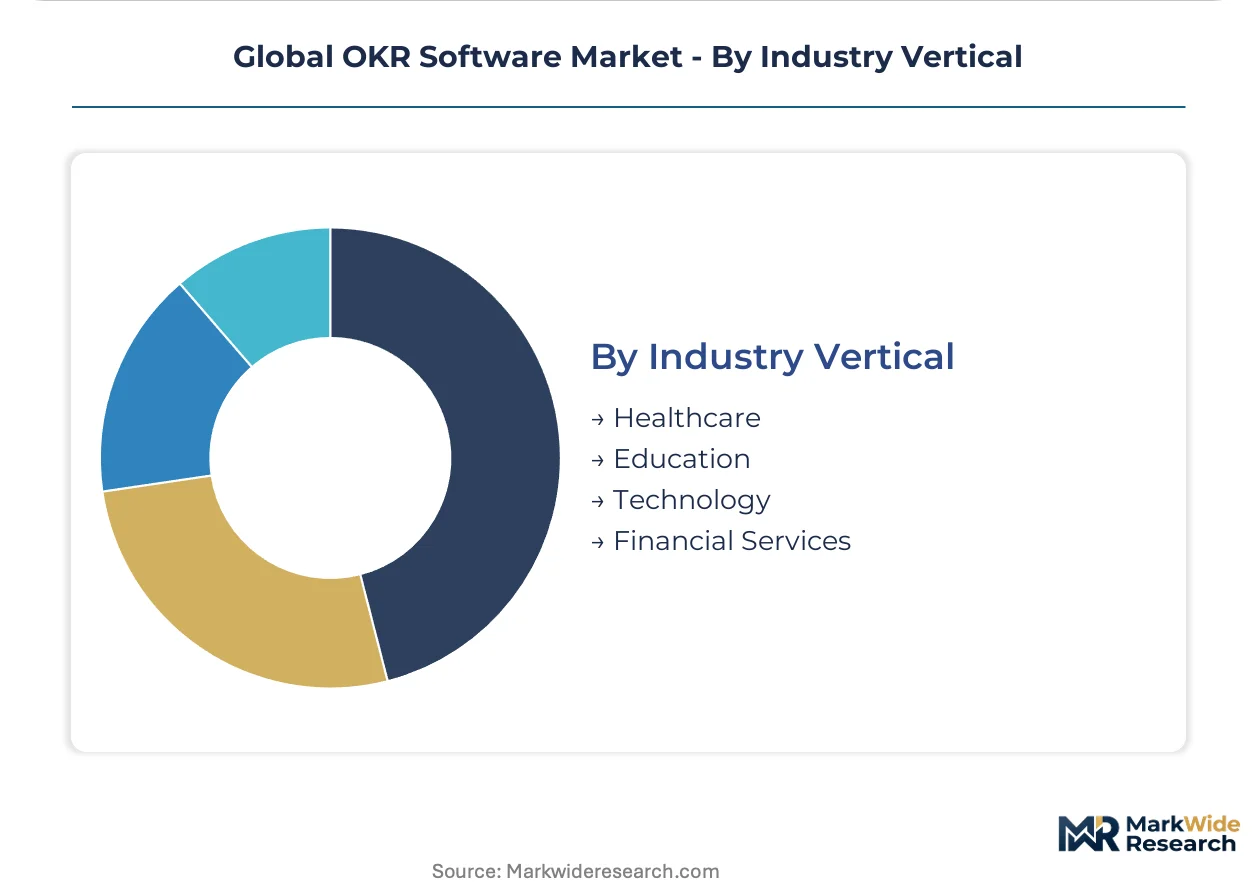
Industry Vertical:
Regulatory intensity and workforce distribution patterns create divergent procurement specifications across sectors.
- Financial Services:Banks, insurers, and asset managers in Germany and France face EU AI Act algorithmic transparency mandates for automated performance assessments. These buyers require explainable goal-weighting documentation and human-in-the-loop override protocols.
- Technology:Software and platform companies with distributed engineering teams prioritize API integrations with project management suites and business intelligence dashboards.
- Healthcare:Hospital systems and pharmaceutical manufacturers navigate HIPAA compliance and workforce credentialing complexity.
- Education:Universities and K-12 districts with seasonal employment patterns demand flexible licensing structures.
Financial Services commands premium pricing; Technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's venture capital density anchors North American OKR platform procurement velocity. The concentration of technology headquarters and institutional investor networks creates concentrated demand for operational transparency tools.
United States
SEC human capital disclosure rules mandate auditable workforce productivity metrics from US-listed corporations. The regulatory pressure accelerates procurement of standardized OKR reporting modules among Fortune 500 HR technology buyers. San Francisco and New York Metro clusters concentrate venture-backed startups deploying these platforms to satisfy investor due diligence requirements.
Germany
EU AI Act compliance mandates reshape procurement specifications for automated performance assessment systems. German automotive and financial services conglomerates require explainable goal-weighting documentation and human-in-the-loop override protocols. Munich and Frankfurt industrial clusters drive premium-tier demand for sovereign cloud deployments satisfying GDPR territoriality rules.
India
Venture-backed technology startups in Bangalore and Delhi-NCR deploy OKR platforms to demonstrate operational transparency during Series B and C fundraising rounds. The Digital Personal Data Protection Act creates compliance-driven procurement cycles for domestic technology adopters. SaaS-native delivery models accelerate time-to-value for mid-market buyers navigating investor scrutiny.
United Kingdom
Financial services firms in London's Square Mile require auditable goal-tracking infrastructure to satisfy algorithmic transparency expectations from UK regulators. The concentration of banking-as-a-service providers and fintech scale-ups generates demand for cross-functional alignment tools. Cambridge and Manchester technology corridors exhibit steep uptake trajectories among growth-stage companies.
France
French insurance conglomerates and healthcare technology firms navigate EU AI Act risk classification frameworks for automated decision-making systems. Paris-based enterprise buyers mandate vendor documentation of training data provenance and model drift monitoring. Lyon and Toulouse industrial clusters demonstrate emerging demand for compliant performance management architectures.
Global OKR Software Market Competitive Environment
Global majors compete with regional champions across integration depth and compliance engineering capabilities. The vendor landscape organizes around three strategic tiers: enterprise-suite incumbents with HRIS ecosystem anchoring, mid-market specialists with configurable goal-cascade architectures, and API-first challengers with native project-management connectivity. Competitive moves concentrate on M&A for integration portfolio expansion and geographic compliance infrastructure buildout.
Within the enterprise-suite tier, Lattice and BetterWorks occupy positions defined by performance-management ecosystem depth. Profit.co exemplifies the mid-market specialization archetype with emphasis on goal-cascade configurability. These three anchors represent divergent strategic bets on buyer segmentation rather than feature parity competition.
| Leading Market Players |
|---|
| Eletive |
| 15Five |
| Profit.co |
| Weekdone |
| Mooncamp |
| Lattice |
| Synergita |
| Workboard |
| BetterWorks |
| Others |
Value Chain & Pricing Dynamics
Hyperscale cloud compute pricing indices cascade through OKR software vendor margin structures, compressing infrastructure costs while subscription packaging fragments toward role-based micro-licensing that mirrors actual usage patterns across buyer segments.
Pricing Analysis
Implementation service bundling separates enterprise-tier deployments from self-serve SaaS tiers, with certified change-management consultants commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects integration depth, with API-native connectivity to Workday and SAP SuccessFactors driving tier placement. Cost compression in the mid-market intensifies as finance teams scrutinize SaaS spend with renewed intensity. Small enterprises below 50 employees exhibit highest price sensitivity, while large corporations absorb premium analytics modules to satisfy SEC disclosure mandates.
Supply Chain Analysis
Cross-border data transmission costs from sovereign cloud infrastructure in Germany, India, and the United Kingdom elevate operational expenditure for vendors serving regulated enterprises. Engineering talent concentration in Bangalore, San Francisco, and Berlin feeds product development pipelines, with compliance engineering consuming disproportionate R&D capacity. Single-source vulnerability in hyperscale cloud provisioning creates concentration risk for multi-tenant architectures. Distribution runs through direct enterprise sales teams for large corporations and product-led growth channels for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
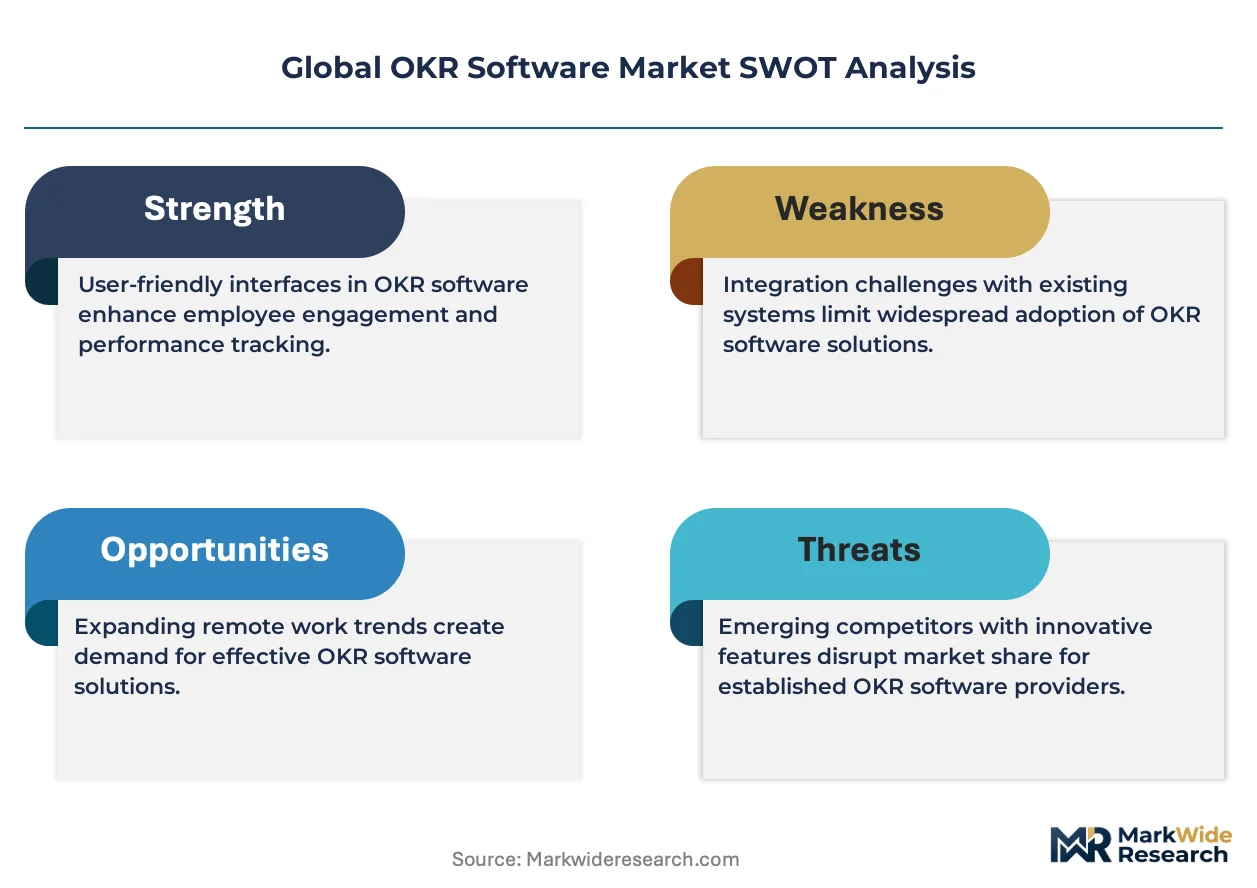
The Global OKR Software Market operates as a cost-of-compliance story, with EU AI Act algorithmic transparency mandates creating a barrier-to-entry moat for vendors possessing auditable goal-tracking infrastructure and explainable AI documentation capabilities.
For Market Incumbents: Acquire specialized compliance engineering teams to fortify EU AI Act documentation capabilities and human-in-the-loop override protocols. Consolidate integration portfolios through targeted API-first platform acquisitions that deepen connectivity with workforce analytics suites. Defend against spreadsheet-native workflow substitution by embedding real-time progress telemetry that Excel cannot replicate. Prioritize sovereign cloud infrastructure expansion in Germany and India to capture data residency-driven procurement cycles. For New Entrants and Emerging Players: SEC human capital disclosure rules in the United States open a window for standardized reporting modules targeting Fortune 500 HR technology buyers with audit-ready metric definitions. Natural language goal drafting and predictive achievement modeling represent unclaimed white space in product roadmaps for venture-backed technology startups. The most penetrable segment comprises growth-stage companies with 500-2,000 employees seeking configurable goal-cascade architectures without enterprise implementation overhead. A vertical-specific go-to-market angle targeting financial services firms in London's Square Mile accelerates initial traction through regulatory tailwinds. For Investors and Strategic Acquirers: The window for entry favors mid-market specialists with configurable architectures and established API integration portfolios. Long-term viability hinges on compliance engineering differentiation as regulatory fragmentation intensifies across jurisdictions. Acquisition target archetypes include regional champions with deep GDPR or Digital Personal Data Protection Act certification and established sovereign cloud deployments. Monitor SEC enforcement patterns on human capital disclosure as the inflection indicator for mandated demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Engineering Buildout | EU AI Act documentation capabilities unlock German and French financial services procurement cycles. |
| API-First Platform Integration | Native Salesforce and Workday connectivity reduces implementation friction for Fortune 500 buyers. |
| Sovereign Cloud Expansion | GDPR and India's Digital Personal Data Protection Act data residency mandates drive infrastructure localization. |
| Generative AI Product Development | Natural language goal drafting compresses quarterly planning cycles from six weeks to ten days. |
| Role-Based Micro-Licensing Launch | Viewer-analyst-administrator tiering matches actual usage patterns and accelerates expansion revenue cycles. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted across CHROs, IT procurement officers, platform engineers, and integration specialists at financial services and technology enterprises. SEC 10-K disclosures, EU AI Act implementation guidance, and venture capital investment databases provided segmentation validation. Bottom-up deployment counts and top-down SaaS spend estimates were reconciled through iterative triangulation.
Data-stream reconciliation across the projection horizon incorporated deployment model, organization size, vertical industry, and regional adoption pattern dimensions. CAGRs were derived from elasticity-adjusted pricing trajectories and user expansion coefficients. Workforce analytics suite integration penetration and regulatory disclosure mandate enforcement timelines served as industry-specific forecast inputs throughout the modeling period.
The model assumes a particular technology adoption path; alternative pathways for generative AI convergence would alter the outlook for natural language goal drafting penetration. Forecasts reflect assumptions about EU AI Act enforcement intensity and SEC human capital disclosure rule expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Towing Software Market
Software & Services
Latin America ERP Software Market
Software & Services
User Interface Software Market
Software & Services
Global Desktop As a Service Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
Computer Assisted Translation Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
User Retention Software Market
Software & Services
Programmable Automation Controller (PAC) Programming Software Market
Software & Services
Metal Fabrication Software Market
Software & Services
B2B Price Optimization and Management Software Market
Software & Services
Global Business Software and Service Market
Software & Services
Enterprise Search Software Market
Software & Services
Preventive Maintenance Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Asia-Pacific Accounting Software Market